
 France Cloud Robotics Market | 2026-2036
France Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
France Cloud Robotics Market Insights
Edge-to-cloud latency specification is unwinding legacy on-premise architectures across French industrial sites. Siemens anchors European automation credibility through its Munich-Paris R&D corridor, while ABB leverages decades of robotic installed base to cross-sell cloud connectivity modules. Microsoft competes aggressively on Azure IoT integration for multi-robot fleet orchestration.
Cloud robotics fuses distributed computing, real-time sensor telemetry, and remote AI inference to coordinate physical machines via centralized or federated cloud backends; systems typically operate on sub-100-millisecond latency thresholds for safety-critical motion control. Service robots capture widening margin pools in French healthcare and eldercare facilities, whereas autonomous mobile robots dominate logistics throughput expansion at Charles de Gaulle hub operations. Hybrid cloud deployment modes attract manufacturers balancing proprietary process data sovereignty against elastic compute scaling.
France's national cybersecurity agency ANSSI mandates cloud security certification for critical infrastructure robotics, while EU AI Act risk-classification rules govern autonomous decision-making transparency in deployed systems. The country's national data protection regulator CNIL enforces GDPR-aligned constraints on cross-border telemetry flows from connected robots. Stakeholders must weigh sovereign cloud mandates against the interoperability demands of pan-European supply chain integration.
Market Dynamics
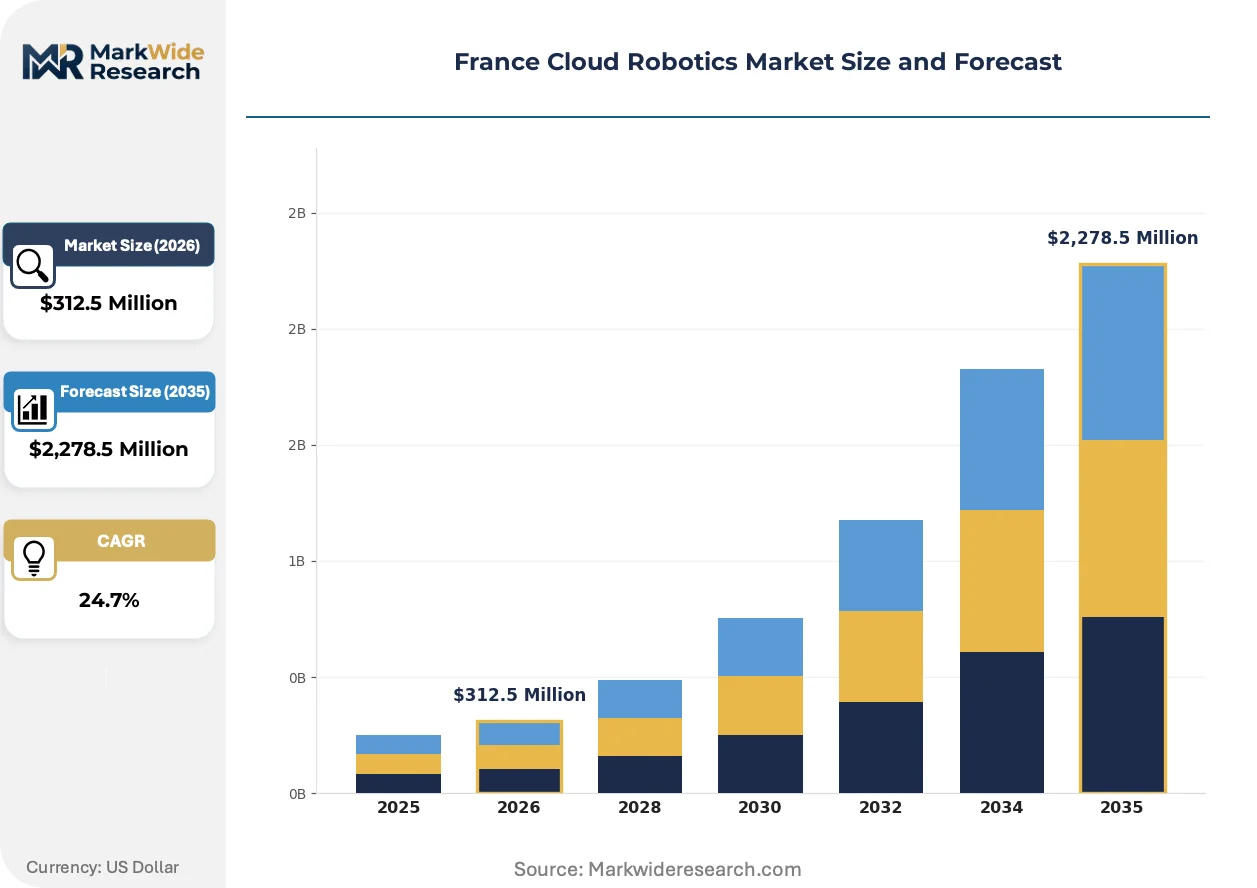
Edge-to-cloud latency thresholds below 100 milliseconds are dismantling legacy on-premise robotic architectures across French industrial sites, forcing manufacturers to reconfigure control systems around distributed compute fabrics.
Growth Catalysts
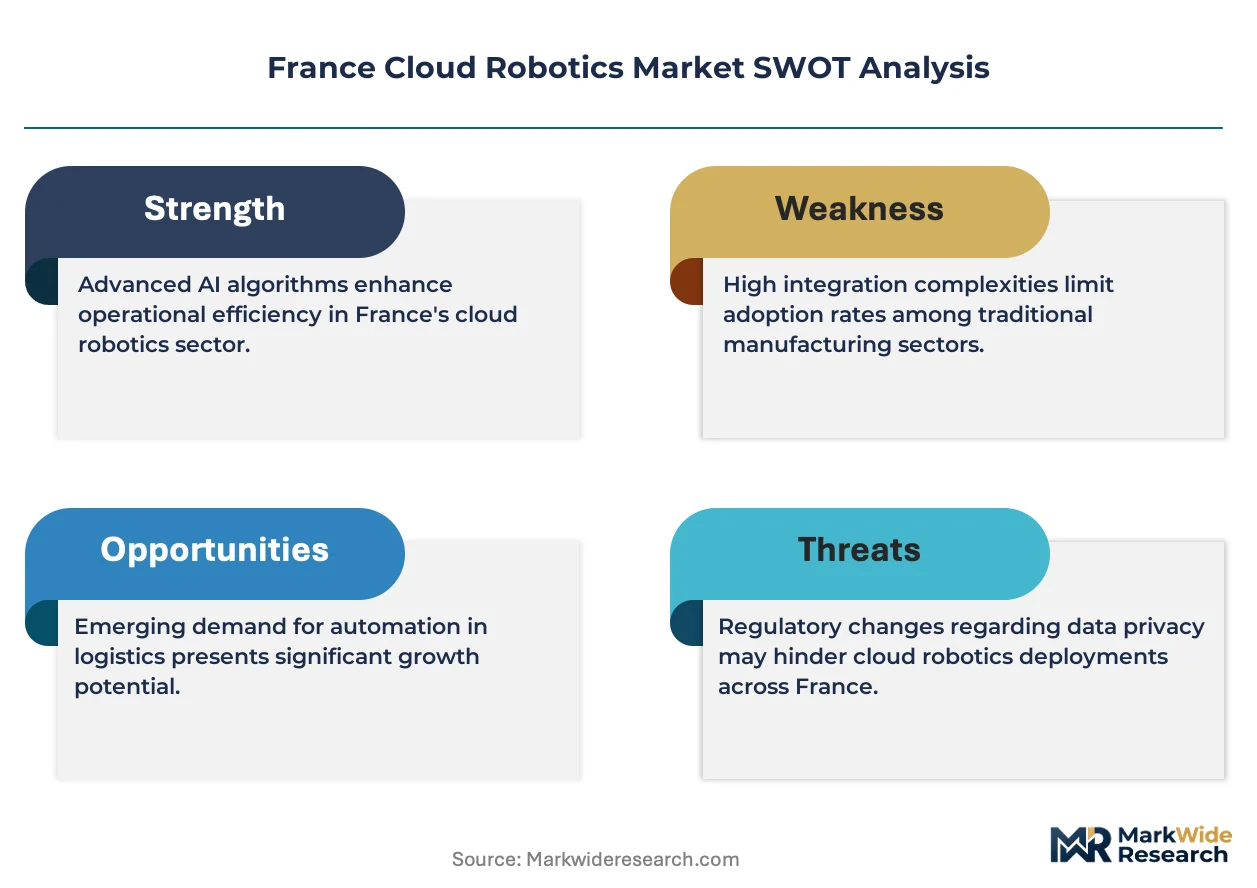
- EU AI Act compliance mandates:Risk-classification rules for autonomous decision-making transparency are accelerating replacement cycles for non-compliant robotic systems in automotive and logistics facilities.
- Paris-Saclay robotics cluster concentration:The Île-de-France innovation hub channels public R&D funding and venture capital toward cloud-native robotic startups, compressing commercialization timelines.
- Sub-50ms 5G private networks:Factory-floor deployments of ultra-reliable low-latency communication are enabling safety-critical motion control previously tethered to local controllers.
Market Restraints
- ANSSI cloud security certification costs:Critical infrastructure robotics face mandatory sovereign cloud compliance, adding six-figure certification overhead per deployment.
- GDPR-cross-border telemetry friction:CNIL enforcement on robot sensor data flows creates architectural constraints for manufacturers operating pan-European fleets.
- Limited edge-AI silicon supply:Concentration of neural processing unit fabrication in East Asian foundries exposes French system integrators to allocation volatility.
Strategic Opportunities
- Auvergne-Rhône-Alpes manufacturing corridor:Underpenetrated SME metalworking and precision engineering clusters present retrofit demand for cloud-connected collaborative robots.
- Healthcare service robot integration:Eldercare facilities in Provence-Alpes-Côte d'Azur are piloting remote-monitoring robotic assistants with centralized AI diagnostics.
- Federated learning architectures:Privacy-preserving model training across hospital networks without raw data centralization addresses GDPR constraints while enabling collective intelligence.
Industry Challenges
- Cloud-robotics systems engineering talent scarcity:Hybrid skill sets spanning embedded control, distributed systems, and safety-critical software command premium compensation, constraining deployment velocity.
- Legacy PLC integration complexity:Brownfield manufacturing sites require protocol translation layers between proprietary automation buses and cloud-native APIs, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Cloud Robotics Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,278.5 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Industrial Robots, Autonomous Mobile Robots, Hybrid Robots Deployment Mode: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Manufacturing, Healthcare, Logistics, Retail Technology: AI, Machine Learning, IoT, Computer Vision |
| Companies Covered | Amazon, Google, Microsoft, Siemens, ABB, IBM, Fanuc, Yaskawa, KUKA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Cloud Robotics Market Trends and Innovations
French cloud robotics is converging around three vectors: control architecture decentralization, regulatory-driven transparency mandates, and procurement model restructuring toward operational expenditure frameworks.
Digital twin environments for robotic fleet simulation are fragmenting traditional hardware-in-the-loop validation workflows. Automotive manufacturers in the Hauts-de-France region are adopting cloud-hosted physics engines to pre-commission production lines, compressing startup timelines from months to weeks. This virtualization is fragmenting capital allocation between physical and synthetic testing infrastructure.
The EU AI Act's risk-based classification system is imposing algorithmic audit trails on autonomous mobile robots in logistics hubs. Deployments at Charles de Gaulle cargo terminals now require documented decision logic for path-planning anomalies, with technical documentation subject to market surveillance authority review. Warehouse operators are responding by embedding explainable AI modules into navigation stacks.
Robot-as-a-service contracting is displacing capital purchase models among French third-party logistics providers. Tier-two fulfillment operators in Occitanie are accessing collaborative robot fleets through per-pick pricing structures, transferring obsolescence risk to system integrators. This shift is most pronounced in e-commerce fulfillment verticals facing seasonal demand volatility.
France Cloud Robotics Market Segmentation
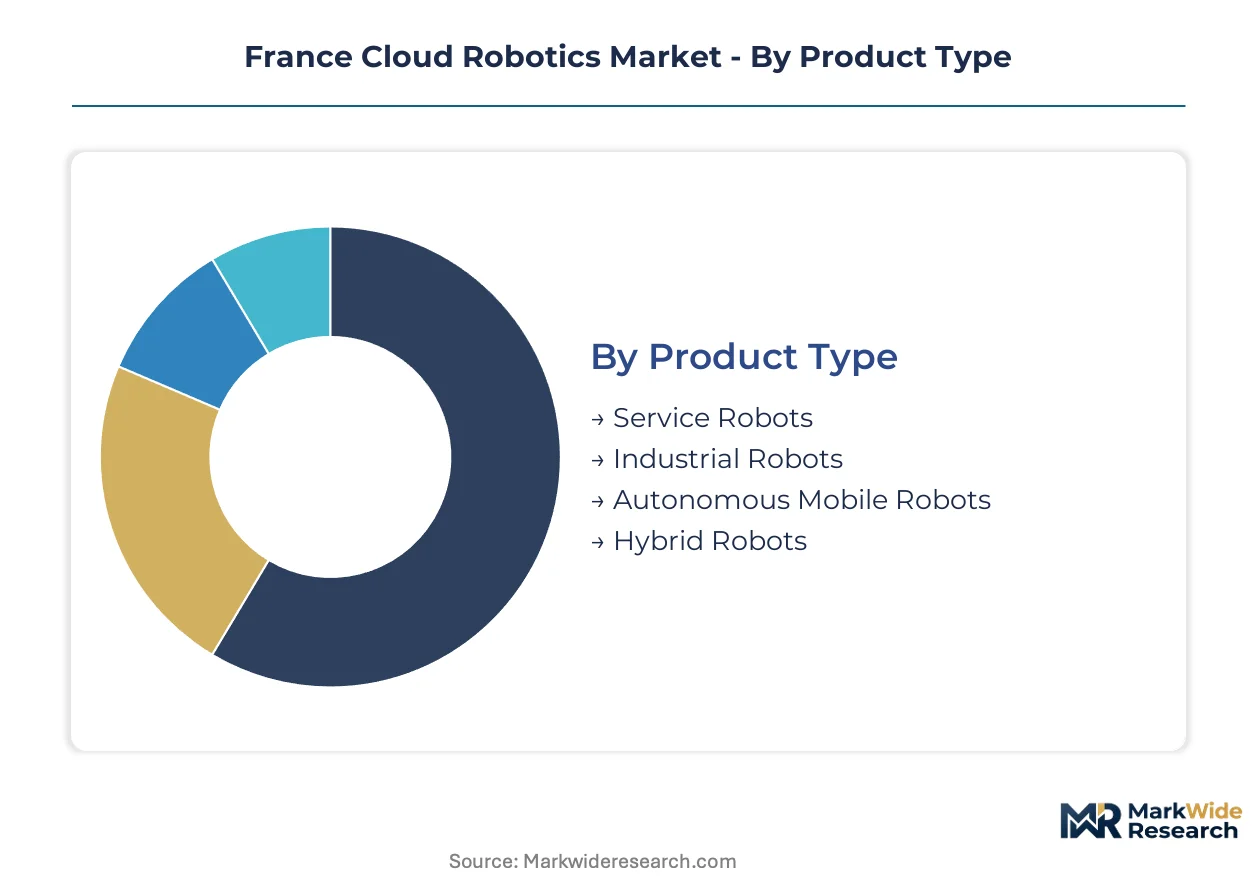
Segmentation in the France Cloud Robotics Market reveals how regulatory pressure, latency requirements, and data sovereignty concerns reshape procurement patterns across hardware categories and deployment architectures. Channel dynamics vary sharply between capital-intensive industrial installations and operational-expenditure service models.
Product Type:
Channel mix diverges sharply: industrial robots flow through system integrators with long sales cycles, while service robots increasingly reach end-users via Robot-as-a-Service platforms with per-unit pricing.
- Industrial Robots:Six-axis articulated arms and SCARA systems with cloud-connected programmable logic controllers dominate automotive assembly lines in Hauts-de-France. Renault and Stellantis facilities drive replacement demand as EU AI Act compliance deadlines approach for legacy installations.
- Service Robots:Eldercare assistance units and disinfection systems with centralized AI diagnostics concentrate in Provence-Alpes-Côte d'Azur healthcare networks. CNIL data localization requirements favor domestic cloud hosting for patient-interfacing deployments.
- Autonomous Mobile Robots:Warehouse navigation systems with fleet orchestration APIs expand through Charles de Gaulle logistics corridors.
- Hybrid Robots:Dual-mode systems combining manipulation and mobility target precision engineering SMEs in Auvergne-Rhône-Alpes.
Industrial robots dominate installed base. Service robots are where expansion concentrates.
Deployment Mode:
Cost tier stratification separates sovereign-certified private deployments from elastic public cloud scaling, with hybrid architectures capturing mid-market manufacturers balancing compliance and flexibility.
- Hybrid Cloud:Federated architectures partition safety-critical motion control to on-premise edge nodes while offloading training workloads to elastic cloud backends. Auvergne-Rhône-Alpes metalworking SMEs favor this model for proprietary process data protection.
- Private Cloud:ANSSI-certified sovereign infrastructure mandates six-figure compliance overhead, restricting adoption to critical infrastructure operators and defense-adjacent robotics.
- Public Cloud:Azure IoT and AWS RoboMaker instances serve startup robotics clusters in Paris-Saclay with pay-as-you-go simulation and training pipelines.
- Multi-Cloud:Redundancy architectures mitigate vendor lock-in for pan-European fleet operators managing cross-border telemetry under GDPR constraints.
Private cloud captures premium-margin deployments. Hybrid cloud is climbing the fastest as manufacturers navigate sovereignty-compute tradeoffs.
End User:
Application concentration maps directly to regional industrial specialization, with Île-de-France logistics and Hauts-de-France automotive anchoring volume while healthcare penetration varies by eldercare facility privatization.
- Manufacturing:Smart factory deployments integrate digital twin simulation with physical production lines, compressing commissioning timelines from months to weeks.
- Logistics:Charles de Gaulle cargo terminals and Occitanie fulfillment centers drive autonomous mobile robot density for e-commerce throughput.
- Healthcare:Remote-monitoring robotic assistants pilot in PACA eldercare facilities with federated learning architectures preserving patient data locality.
- Retail:Inventory-scanning and customer-service robots remain experimental, constrained by high-touch service norms and union negotiation frameworks.
Manufacturing absorbs the majority of industrial robot shipments. Healthcare is gaining share fastest as demographic pressure accelerates automation imperatives.
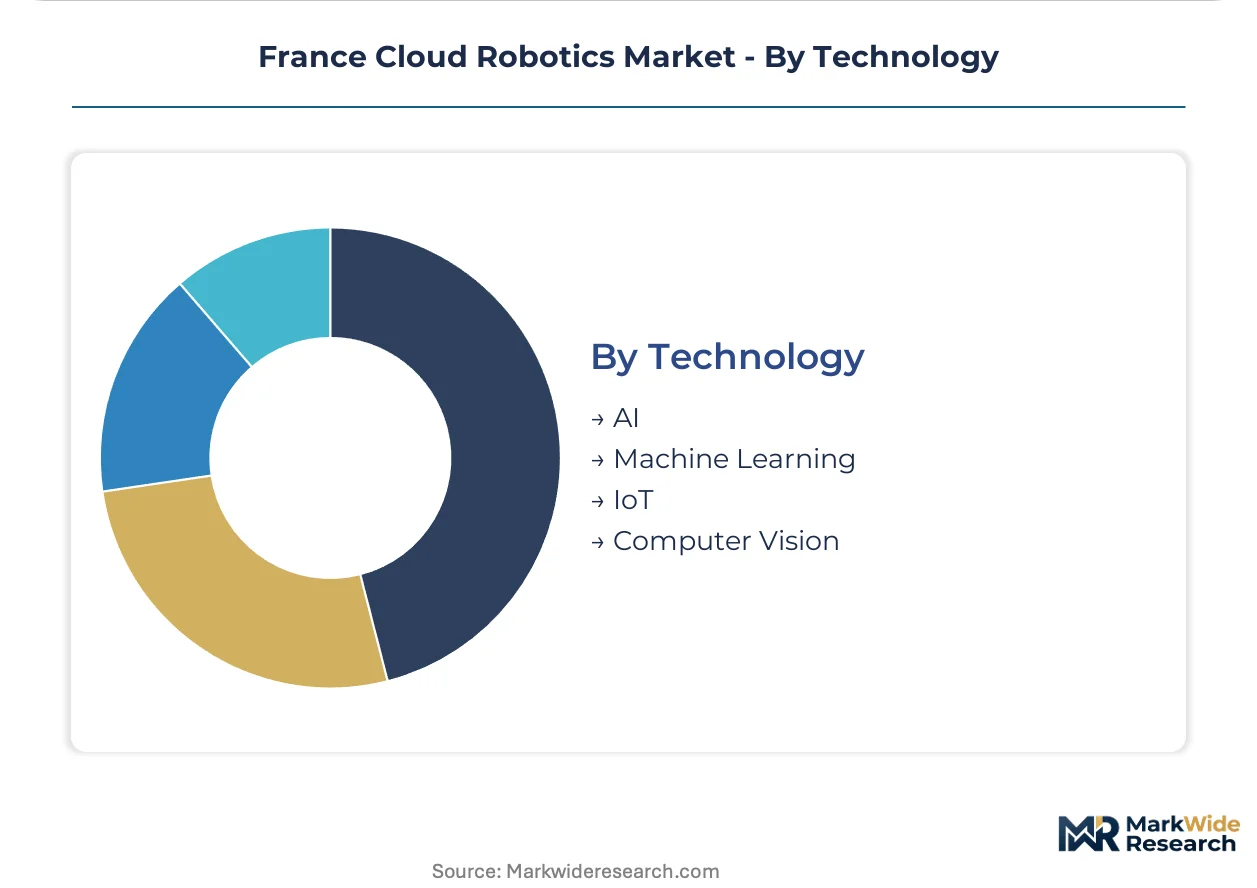
Technology:
Maturity gradients separate established IoT telemetry stacks from emerging computer vision architectures, with AI integration depth determining competitive differentiation in navigation and manipulation tasks.
- AI:Explainable path-planning modules satisfy EU AI Act documentation requirements for autonomous decision-making in logistics deployments.
- Computer Vision:Real-time object recognition and semantic segmentation enable collaborative robot safety systems without physical cages.
- Machine Learning:Predictive maintenance models trained on federated hospital networks address GDPR constraints while enabling collective fleet intelligence.
- IoT:Sensor telemetry pipelines with sub-100-millisecond latency thresholds underpin safety-critical motion control architectures.
IoT connectivity forms the foundational layer across all deployments. Computer vision is expanding most quickly as manipulation tasks require higher environmental perception fidelity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's cloud robotics infrastructure clusters around three distinct industrial corridors, each shaped by regional specialization and proximity to regulatory centers. Île-de-France dominates R&D concentration while manufacturing deployment spreads through peripheral regions.
Île-de-France
Paris-Saclay's robotics cluster channels public R&D funding toward cloud-native startups, compressing commercialization timelines for autonomous systems. ANSSI cybersecurity certification requirements for critical infrastructure robotics add compliance overhead but reinforce the region's sovereign cloud hosting advantage. Charles de Gaulle logistics terminals drive autonomous mobile robot density for e-commerce throughput expansion.
Hauts-de-France
Renault and Stellantis assembly lines generate replacement demand as EU AI Act compliance deadlines approach for legacy robotic installations. The region's automotive concentration attracts system integrators specializing in digital twin pre-commissioning workflows. Lille's proximity to Belgian and German supply chains enables cross-border fleet orchestration pilots.
Auvergne-Rhône-Alpes
Metalworking and precision engineering SMEs present retrofit demand for cloud-connected collaborative robots with hybrid deployment architectures. Manufacturers here favor federated models partitioning safety-critical control to edge nodes while offloading training workloads to elastic backends. Lyon-based integrators serve as intermediaries between Paris cloud providers and factory-floor implementations.
Provence-Alpes-Côte d'Azur
Eldercare facilities pilot remote-monitoring robotic assistants with centralized AI diagnostics, constrained by CNIL data localization requirements for patient-interfacing systems. The region's healthcare privatization trajectory determines automation procurement velocity. Nice and Marseille clusters specialize in federated learning architectures preserving data locality across hospital networks.
Occitanie
Third-party logistics providers access collaborative robot fleets through per-pick Robot-as-a-Service pricing, transferring obsolescence risk to system integrators. Toulouse's aerospace heritage supplies embedded control engineering talent for cloud-robotics systems integration. Seasonal e-commerce demand volatility accelerates operational-expenditure contracting models over capital purchase.
France Cloud Robotics Market Competitive Landscape
Concentration sits with diversified industrial automation conglomerates and hyperscale cloud providers, creating a bifurcated structure where hardware heritage competes against software-native orchestration platforms. Strategic archetypes include robotics OEMs with installed base leverage, cloud hyperscalers integrating IoT middleware, and system integrators bridging brownfield protocol translation. Dominant competitive moves encompass cross-selling connectivity modules to legacy robot fleets and vertical integration into edge-AI silicon supply.
Within the industrial automation tier, Siemens anchors European credibility through its Munich-Paris R&D corridor while ABB leverages decades of robotic installed base to position cloud connectivity offerings. Microsoft competes aggressively on Azure IoT integration for multi-robot fleet orchestration, representing the hyperscaler archetype that treats physical machines as endpoint extensions of cloud-native infrastructure. These three occupy positions spanning hardware control heritage, middleware abstraction, and pure software orchestration.
| Leading Market Players |
|---|
| Amazon |
| Microsoft |
| Siemens |
| ABB |
| IBM |
| Fanuc |
| Yaskawa |
| KUKA |
| Others |
Pricing and Supply Chain Analysis
Edge-AI silicon substitution for legacy programmable logic controllers is redrawing component sourcing maps toward East Asian foundries while compressing margin structures for French system integrators caught between certification mandates and silicon allocation volatility.
Pricing Analysis
EU AI Act dictates the pricing tier structure across deployment modes, with ANSSI-certified private cloud installations commanding premium positioning against elastic public cloud alternatives. Pricing stratifies across sovereign-certified, hybrid-federated, and standard-economy tiers based on compliance overhead and latency specification. Cost compression in the mid-market hybrid segment is intensifying because metalworking SMEs demand edge-node sovereignty without full certification burden. Third-party logistics providers show highest price sensitivity due to Robot-as-a-Service contracting transfer of obsolescence risk.
Supply Chain Analysis
Strait of Malacca transit underwrites neural processing unit delivery schedules for French robotics deployments, exposing integrators to geopolitical friction in East Asian semiconductor corridors. Component sourcing draws from Taiwan, South Korea, and China for edge-AI silicon, with German and Italian suppliers anchoring precision mechanical assemblies. Single-source vulnerability concentrates in advanced node fabrication, where foundry allocation volatility disrupts commissioning timelines. Distribution runs through Lyon-based system integrators serving as intermediaries between Paris cloud providers and Auvergne-Rhône-Alpes factory floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
French cloud robotics rewards players who control scarce hybrid skill sets spanning embedded safety-critical software, distributed systems architecture, and regulatory compliance navigation. Talent acquisition and retention now determine deployment velocity more than capital access.
For Market Incumbents: Consolidate around ANSSI certification pipelines to lock out non-compliant challengers in critical infrastructure verticals. Deepen backward integration into edge-AI silicon supply through strategic foundry partnerships, mitigating allocation risk that threatens commissioning timelines. Acquire Lyon-based system integrators to capture the intermediary layer between cloud providers and brownfield manufacturing sites. For New Entrants and Emerging Players: Lead with federated learning architectures that preserve data locality across hospital networks, addressing CNIL constraints while enabling collective intelligence without raw telemetry centralization. Target eldercare facilities in Provence-Alpes-Côte d'Azur as the most penetrable healthcare segment, where privatization trajectories accelerate procurement velocity. Position through per-pick Robot-as-a-Service pricing to transfer capital risk and align with seasonal e-commerce demand patterns. For Investors and Strategic Acquirers: EU AI Act risk-classification deadlines reshape the acquisition landscape, compressing valuation windows for non-compliant legacy robotic installations ahead of replacement cycles. Long-term viability favors targets with hybrid cloud deployment expertise and sovereign certification track records. Watch ANSSI certification queue lengths as the signal indicating compliance bottleneck severity and premium pricing power duration.| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Certification Investment | Creates mandatory barrier to critical infrastructure deployments in Île-de-France logistics corridors. |
| Federated Learning Architecture Development | Enables CNIL-compliant AI training across hospital networks without raw patient data centralization. |
| Edge-AI Silicon Supply Agreement | Secures neural processing unit allocation from Taiwan foundries against automotive sector competition. |
| Robot-as-a-Service Platform Launch | Transfers obsolescence risk to integrators while capturing seasonal demand volatility in Occitanie fulfillment. |
| Digital Twin Pre-Commissioning Capability | Compresses automotive line startup timelines from months to weeks for Hauts-de-France Renault-Stellantis facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hyperscaler capex disclosures, and customs trade data. Interviews with cloud robotics engineering leads, ANSSI certification auditors, hospital biomedical engineers, and system integrator project directors combined with bottom-up installation tracking and top-down market sizing triangulation. Secondary validation drew from EU AI Act implementation guidance, CNIL data localization rulings, and ANSSI cloud security certification records.
Segmentation dimensions modeled include deployment architecture, robot product category, end-use vertical, and regional industrial cluster concentration across the projection horizon. CAGRs derived from installed base evolution, replacement cycle compression, and compliance-driven upgrade mandates. Forecast inputs incorporated 5G private network rollout pace, edge-AI silicon supply allocation trends, and EU AI Act enforcement intensity variation by member state.
Forecasts assume regulatory continuity in EU AI Act risk-classification timelines and ANSSI certification requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as GDPR cross-border telemetry enforcement patterns and East Asian semiconductor supply stability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Commercial Robots Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Industrial Robot Controllers Market