
 Global Articulated Robot Market | 2026-2036
Global Articulated Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Articulated Robot Market Analysis
The capital-intensity divergence between heavy-industrial specialists and collaborative newcomers is rotating competitive dynamics across the sector. FANUC Corporation leverages its captive servo-motor foundries to sustain margin control in high-payload welding cells. KUKA AG anchors European automotive lines through deep integration with German OEM tooling standards. Universal Robots A/S competes at the lower payload tier with modular architectures that slash deployment timelines for mid-size electronics fabricators.
An articulated robot employs serial-link kinematic chains with rotary joints—typically four to seven axes—to position end-effectors within three-dimensional workspaces, with repeatability tolerances often below ±0.05 mm for electric-drive precision variants. These systems execute welding, painting, material handling, and packaging tasks across factory floors where programmable flexibility replaces fixed automation. Electric technology dominates installed bases due to energy efficiency and control fidelity, while collaborative robots represent the fastest-expanding product type as force-limiting designs penetrate electronics and healthcare cleanrooms. Material handling applications command the largest revenue pool, though packaging lines in consumer goods are accelerating retrofit cycles.
The EU Machinery Directive and CE marking framework mandate functional safety validations for articulated systems deployed across European member states, while China's MIIT issues GB standards that govern electromagnetic compatibility and operational safety for domestic installations. The US OSHA lockout/tagout rules intersect with ANSI/RIA R15.06 specifications to shape North American integration protocols. Stakeholders must monitor evolving ISO 10218 safety revisions and national cybersecurity mandates for networked robot controllers as connectivity becomes standard architecture.
Market Dynamics
Electric-drive precision variants are tightening repeatability tolerances below ±0.05 mm, forcing pneumatic and hydraulic architectures into niche heavy-forging applications while battery assembly lines in Germany and Japan absorb capital at unprecedented velocity.
Growth Catalysts
- EU Machinery Directive CE marking:Mandatory functional safety validations are accelerating replacement cycles of legacy unguarded systems across European automotive stamping plants.
- China's Yangtze River Delta cluster:Concentrated electronics fabrication demand is pulling collaborative robot deployments into mid-size consumer goods packaging lines.
- Force-limiting joint technology:ISO 10218-1 compliance for power-and-force limiting is opening cleanroom healthcare applications previously blocked by cage requirements.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium procurement dependency on Chinese processing infrastructure creates input cost volatility for high-torque servo motors.
- CE marking timeline friction:Third-party notified body backlogs extend certification cycles for new collaborative robot platforms entering European markets.
- Pneumatic actuator residual demand:Explosion-proof requirements in chemical processing sustain lower-cost pneumatic substitutes for electric precision arms.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive sectors are creating first-mover deployment windows for cobot integrators.
- 5G-integrated edge controllers:Convergence of ultra-reliable low-latency communication with real-time kinematic processing enables cloud-native robot fleet management.
- Brazil's ANVISA medical device pathway:Streamlined registration for surgical assistance robots is opening Latin American healthcare automation.
Industry Challenges
- Safety-certified systems integration:ANSI/RIA R15.06 compliance engineering talent scarcity extends commissioning timelines for North American automotive retrofits.
- Legacy PLC interoperability:Proprietary fieldbus protocols in 1990s-era factory floors force costly gateway middleware development for unified robot orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Articulated Robot Market |
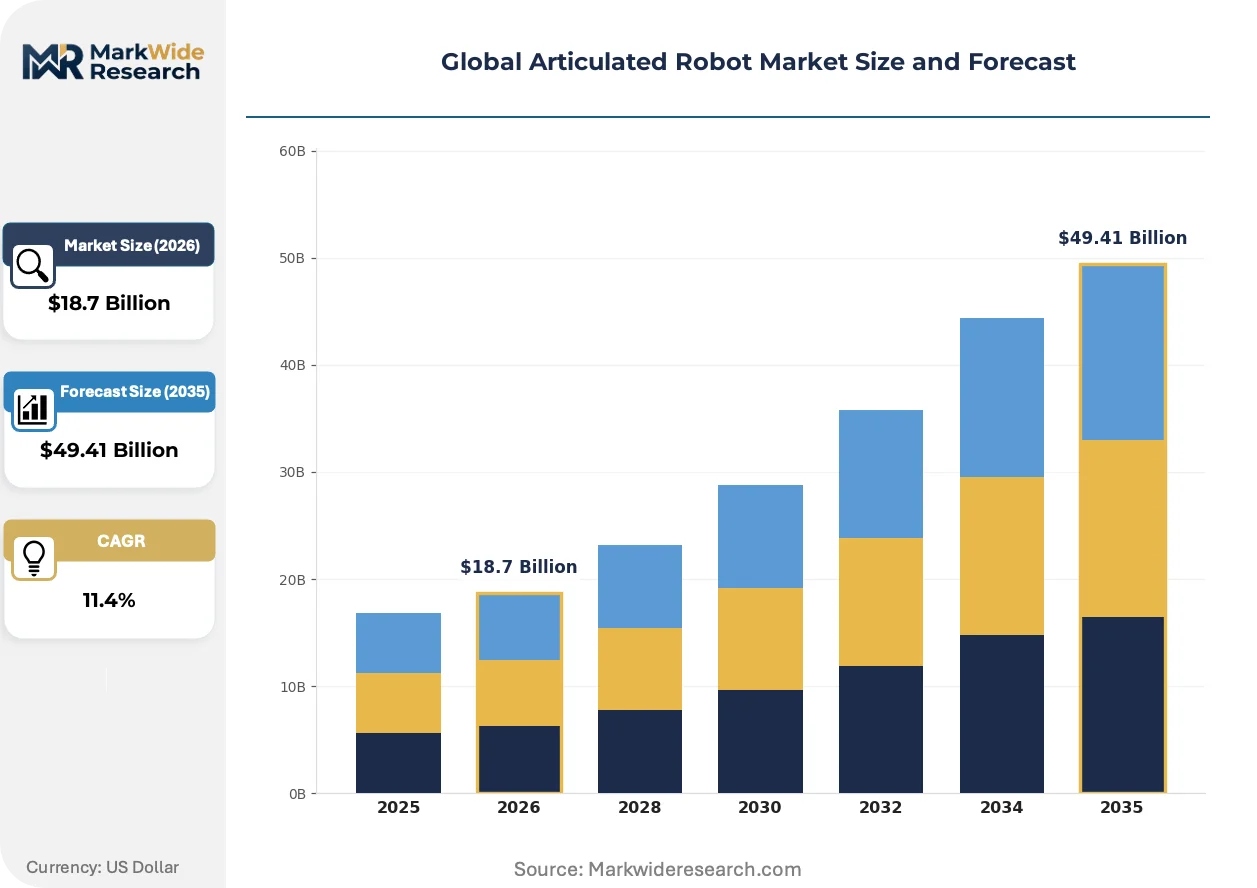
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Robots, Outdoor Robots, Hybrid Robots, Collaborative Robots Application: Welding, Painting, Material Handling, Packaging End User: Automotive, Electronics, Healthcare, Consumer Goods Technology: Hydraulic, Pneumatic, Electric, Mechanical |
| Companies Covered | ABB Ltd., FANUC Corporation, Yaskawa Electric Corporation, KUKA AG, Kawasaki Heavy Industries, Ltd., Mitsubishi Electric Corporation, Denso Corporation, Seiko Epson Corporation, Universal Robots A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Articulated Robot Market Emerging Trajectories
Digital twin simulation is compressing deployment risk for articulated systems before physical installation, while force-torque sensor integration and modular payload architectures are rewriting procurement specifications across precision manufacturing.
Direct-drive torque motors are supplanting traditional gearbox-reducer assemblies in collaborative robot joints. Electronics fabricators in South Korea and Taiwan are adopting these frictionless architectures for sub-micron assembly tasks. The elimination of backlash and maintenance intervals is compressing total cost of ownership calculations against pneumatic alternatives.
China's MIIT GB/T 12643-2021 vocabulary and characteristic standards are mandating unified safety parameter documentation for domestic robot installations. Industrial users must now submit electromagnetic compatibility test reports alongside mechanical risk assessments. Domestic integrators are responding by pre-certifying controller platforms to accelerate end-user deployment timelines.
Buying committees now require lifecycle service cost guarantees before capital release, displacing traditional equipment-only procurement. German automotive tier-one suppliers are bundling predictive maintenance subscriptions into seven-year total cost contracts. This shift is most visible in Bavarian powertrain assembly lines where uptime penalties dominate vendor selection criteria.
Global Articulated Robot Market Segmentation
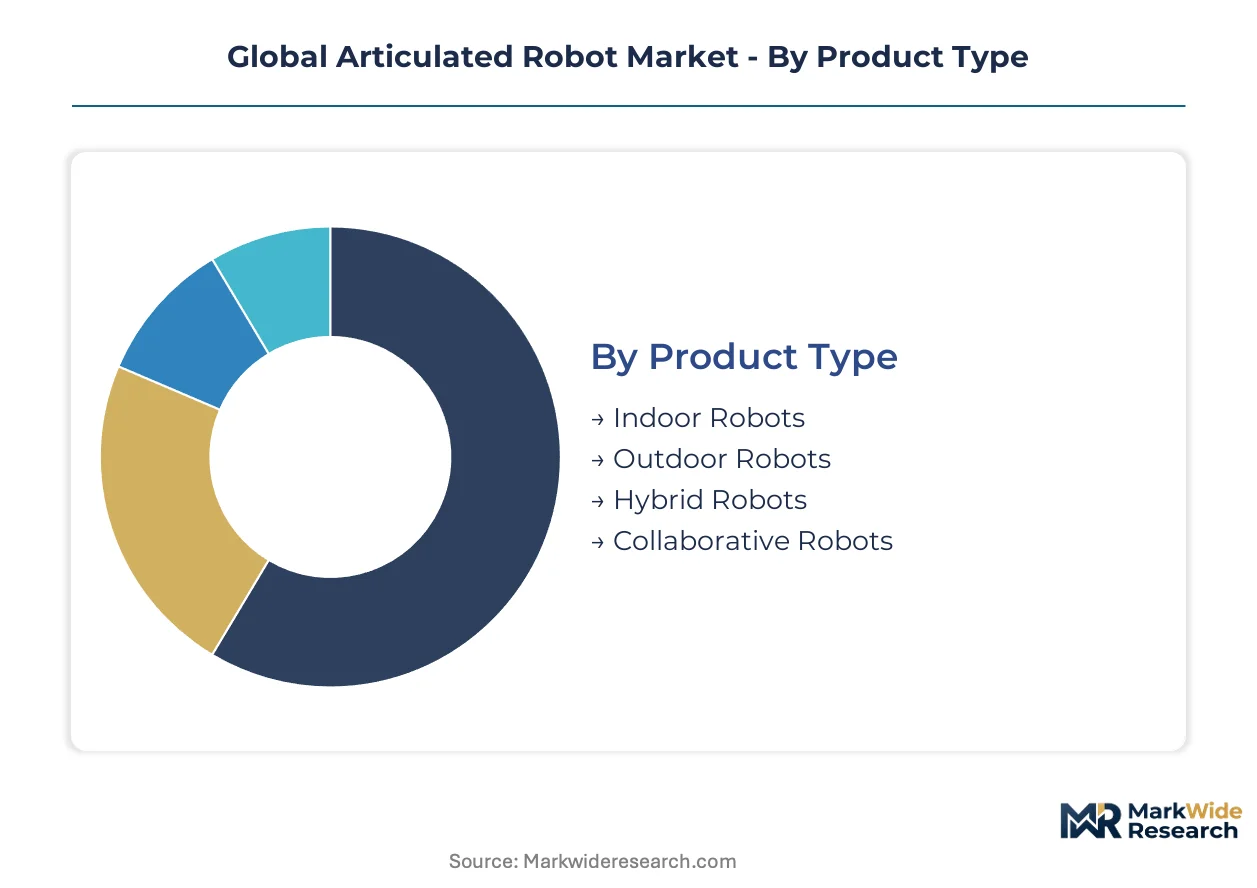
Articulated robot procurement decisions cascade through four interlocking dimensions—product architecture, factory-floor application, end-use industry, and drive technology—each filtering capital allocation toward distinct performance thresholds and compliance regimes. Understanding where specifications diverge across these axes clarifies vendor positioning and integration complexity.
Product Type:
Margin pools concentrate in force-limiting collaborative architectures where safety certification premiums offset higher unit engineering costs, while traditional industrial variants compete on throughput density.
- Collaborative Robots:Force-torque sensing joints enable human-robot workspace sharing without physical guarding. ISO 10218-1 power-and-force limiting compliance opens electronics cleanrooms in South Korea and Taiwan where cage-free layouts maximize floor density.
- Indoor Robots:Enclosed-environment precision arms dominate automotive welding cells with repeatability below ±0.05 mm. German OEMs specify these for battery module assembly where contamination control intersects cycle-time targets.
- Outdoor Robots:IP67-rated sealing and thermal management protect kinematic chains in construction and agriculture deployments. Demand concentrates in Nordic infrastructure projects requiring year-round operational envelopes.
- Hybrid Robots:Modular architectures swap end-effectors between material handling and inspection tasks. Mid-size Japanese fabricators deploy these for mixed-model production where batch sizes fluctuate weekly.
The dominant share belongs to Indoor Robots, while Collaborative Robots are gaining share fastest.
Application:
Volume concentration tracks automotive capital cycles, yet packaging lines in consumer goods are compressing retrofit timelines through standardized controller platforms.
- Material Handling:Palletizing and machine-tending operations absorb the largest installed base. China's Yangtze River Delta electronics clusters deploy electric-drive variants for component feeding where speed consistency reduces work-in-process buffers.
- Welding:Arc and spot welding cells require high-payload repeatability and anti-spatter cable management. German automotive stamping plants specify these for aluminum-intensive electric vehicle body-in-white construction.
- Packaging:Pick-and-place delta-kinematic hybrids address primary and secondary packaging. Brazilian food processors favor these for washdown compliance under ANVISA hygiene mandates.
- Painting:Explosion-proof electric drives with atomizer integration dominate automotive finishing. Italian luxury vehicle coachbuilders specify these for multi-layer clearcoat precision.
Material Handling commands the broadest deployment footprint, though Packaging applications are climbing the fastest.
End User:
Customer sophistication varies sharply—automotive buyers demand seven-year total cost guarantees while healthcare procurement prioritizes regulatory documentation speed.
- Automotive:Tier-one suppliers specify welding and material handling cells with predictive maintenance subscriptions. Bavarian powertrain lines bundle uptime penalties into vendor contracts.
- Electronics:Sub-micron assembly tasks favor direct-drive torque motors eliminating gearbox backlash. Taiwanese semiconductor packaging houses drive specifications for cleanroom-compatible lubricants.
- Consumer Goods:Mid-size packaging lines prioritize deployment velocity over absolute precision. Indian PLI scheme beneficiaries in electronics fabrication represent emerging demand concentration.
- Healthcare:Surgical assistance and pharmaceutical dispensing require ISO 13485 quality system alignment. Brazilian ANVISA pathway streamlining is accelerating Latin American hospital adoption.
Automotive retains the deepest integration relationships, while Healthcare is expanding most quickly.
Technology:
Drive architecture selection reflects a trade-off between energy efficiency and explosive-environment safety, with electric systems capturing precision applications and pneumatics retaining chemical processing niches.
- Electric:Servo-motor precision with encoder feedback dominates new installations. FANUC's captive foundry model for rare-earth magnets insulates margin control despite Chinese processing concentration.
- Pneumatic:Intrinsically safe actuation persists in solvent-rich painting and chemical processing. Lower capital cost sustains demand where explosion-proof electric certification timelines extend procurement cycles.
- Hydraulic:High-force density for heavy forging and die casting survives in legacy automotive stamping. Maintenance intensity limits new adoption outside retrofit scenarios.
- Mechanical:Cam-driven and linkage systems persist in ultra-high-speed packaging where programmability requirements remain minimal. Candy and confectionery lines in Belgium and Switzerland retain these for cost stability.
Electric technology holds the widest specification penetration, though Pneumatic retains defensive positions in regulated environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys articulated robots primarily for electronics assembly density, while Germany channels capital toward automotive powertrain precision and the United States balances warehouse automation with emerging healthcare applications. This consumption-mix differential shapes regional vendor strategies and certification priorities.
China
MIIT GB standards enforcement accelerates domestic controller platform pre-certification. Yangtze River Delta electronics clusters absorb collaborative robot deployments for consumer goods packaging lines where floor density maximization overrides absolute precision requirements.
Germany
EU Machinery Directive CE marking mandates functional safety validations for automotive stamping plant retrofits. Bavarian powertrain assembly lines bundle predictive maintenance subscriptions with seven-year uptime penalty clauses into vendor selection criteria.
United States
OSHA lockout/tagout rules intersect with ANSI/RIA R15.06 specifications to shape automotive retrofit commissioning timelines. Midwest automotive corridors face safety-certified systems integration talent scarcity that extends project delivery schedules.
Japan
METI industrial policy supports electric-drive precision variant development for sub-micron assembly tasks. Nagoya-area automotive tier-one suppliers specify direct-drive torque motors eliminating gearbox backlash for battery module construction.
South Korea
MFDS medical device pathways and KOSHA safety frameworks govern healthcare automation adoption. Seoul Capital Area semiconductor packaging houses drive cleanroom-compatible lubricant specifications for electronics fabrication lines.
Global Articulated Robot Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive component production distinguishing the upper echelon from margin-pressured assemblers. Heavy-industrial incumbents compete on payload density and automotive OEM integration depth, while collaborative newcomers exploit modular architectures and deployment velocity. Strategic moves concentrate on backward integration into rare-earth magnet supply chains and predictive maintenance service bundling.
Within the integrated leader tier, FANUC Corporation and ABB Ltd. exemplify archetypes of captive supply chain control and global installed base leverage respectively. Yaskawa Electric Corporation occupies a position bridging precision servo heritage with collaborative platform expansion. These three anchors represent divergent responses to electric-drive tolerance tightening and force-limiting joint commoditization pressures.
| Leading Market Players |
|---|
| ABB Ltd. |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| KUKA AG |
| Kawasaki Heavy Industries, Ltd. |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| Seiko Epson Corporation |
| Universal Robots A/S |
| Others |
Supply Flow & Price Mechanics
EU Machinery Directive CE marking requirements simultaneously gate supplier qualification and stratify price tiers across the articulated robot market, forcing vendors to absorb certification engineering costs or pass them through as safety-grade premiums that separate validated European integrators from uncertified Asian competitors.
Pricing Analysis
Long-term total cost of ownership contracts now dominate German automotive procurement, bundling seven-year predictive maintenance subscriptions with hardware acquisition rather than per-unit spot transactions. Price differentiation hinges on ISO 10218-1 safety certification tier and captive servo-motor production, with collaborative robot platforms facing cost compression from modular newcomer architectures while high-payload welding cells retain margin through rare-earth magnet supply control. Tier-one automotive buyers in Bavaria show lowest price sensitivity due to uptime penalty clauses, whereas mid-size Indian electronics fabricators under PLI scheme pressure negotiate aggressively on upfront capital.
Supply Chain Analysis
Inbound logistics costs from Shanghai Port container congestion and Yangtze River Delta feeder delays are amplifying working capital requirements for European and North American integrators sourcing complete kinematic chains. Supply concentrates in China, Japan, and Germany, with neodymium permanent magnets, precision harmonic drives, and servo-motor controller boards anchoring bill-of-materials exposure. Single-source dependency on Chinese rare-earth processing infrastructure creates tariff and export restriction vulnerability. Distribution runs through authorized integrator networks that handle CE marking compliance and field commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and safety recertification services are expanding faster than hardware shipments, creating recurring revenue layers that justify upfront equipment pricing compression.
For Market Incumbents: Shield margin pools by deepening backward integration into rare-earth magnet foundries and force-torque sensor calibration facilities, countering modular collaborative robot entrants that commoditize joint-level safety hardware through standardized ISO 10218-1 compliance platforms. Prioritize captive production of high-torque servo motors to offset Chinese processing concentration risk.
For New Entrants and Emerging Players: Lead with deployment velocity advantages in India's PLI scheme electronics fabrication corridors, where mid-size consumer goods packaging lines prioritize commissioning speed over absolute repeatability. Target force-limiting collaborative architectures for healthcare cleanroom applications in Brazil's ANVISA-streamlined surgical assistance pathway, using cloud-native controller platforms to bypass legacy PLC interoperability barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across collaborative robot sub-segments as direct-drive torque motors eliminate gearbox assemblies and compress component counts. Over the five-to-ten year viability window, prioritize acquisition targets with pre-certified controller platforms under China's MIIT GB/T 12643-2021 standards and established predictive maintenance subscriber bases. Monitor CE marking notified body backlog durations as inflection signal for European market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | FANUC's captive foundry model insulates servo-motor margins against Chinese neodymium processing volatility. |
| Predictive Maintenance Subscription Bundling | German automotive tier-one suppliers now require seven-year uptime guarantees with penalty clauses in Bavarian powertrain lines. |
| Cloud-Native Controller Platform Development | 5G-integrated edge controllers enable real-time fleet management for electronics clusters in South Korea and Taiwan. |
| CE Marking Pre-Certification Investment | Domestic Chinese integrators pre-certify platforms to MIIT GB standards, accelerating Yangtze River Delta deployment timelines. |
| Force-Limiting Joint Modularization | Universal Robots' standardized architectures slash commissioning duration for mid-size packaging retrofit cycles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC robotics segment disclosures, and EU Machinery Directive implementation guidance, combining structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and safety compliance officers alongside bottom-up and top-down triangulation.
Segmentation dimensions modeled span product architecture, factory-floor application, end-use industry, and drive technology across the projection horizon, with CAGRs derived from production capacity expansion schedules, automotive capital expenditure pipelines, and electronics fabrication cluster formation patterns in China and India.
The analysis sits within stated boundaries; outcomes outside sustained rare-earth magnet supply continuity, CE marking timeline normalization, or collaborative robot safety standard harmonization would require recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Thailand Cloud Robotics Market