
 Industrial Robots Market | 2026-2036
Industrial Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Robots Market Analysis
Modular robot-cell bundling is rebalancing how mid-sized manufacturers evaluate capital outlays against per-unit flexibility. FANUC Corporation leverages its captive CNC and servo-motor supply chain to control component costs across articulated and SCARA lines. ABB anchors its position through software-integrated workcells that combine hardware with offline programming platforms. KUKA AG competes by specializing in heavy-payload automotive body-shop configurations.
An industrial robot is a reprogrammable, multi-axis manipulator with articulated, SCARA, delta, or Cartesian kinematics, typically driven by AC servo motors and controlled through real-time operating systems executing point-to-point or continuous-path motion programs; its commercial purpose is to automate repetitive, hazardous, or precision-demanding tasks in manufacturing and logistics environments. Articulated robots occupy the largest installed base due to their six-degree-of-freedom dexterity in welding and painting operations, though collaborative robotics represents the fastest-expanding technology segment as force-limited designs open assembly tasks to smaller factories without protective guarding. Material handling applications generate the steadiest replacement demand, while machine vision integration is deepening margin pools in electronics end-user segments where micron-level placement accuracy is mandatory.
The US OSHA machine-guarding standards and the EU Machinery Directive with its CE marking requirements shape product design by mandating risk assessments and protective measures before market entry. China's GB standards for industrial robot safety and performance, administered by SAMR, create a separate compliance pathway for suppliers targeting domestic automotive and electronics manufacturers. Stakeholders must monitor how the EU AI Act's risk-classification framework will apply to autonomous robotics systems with embedded decision-making algorithms.
Market Dynamics
Electric vehicle battery assembly lines are forcing automotive OEMs to retool entire production floors with higher-payload articulated systems, compressing traditional five-year capital cycles into eighteen-month refresh windows.
Growth Catalysts
- China's MIIT dual carbon mandates:Servo-motor efficiency standards now require 20% energy reduction in new robot installations, accelerating replacement demand across Guangdong and Jiangsu manufacturing belts.
- Machine vision convergence:Electronics assemblers in Stuttgart's automotive cluster are integrating micron-level placement systems for battery management unit production.
- Collaborative robotics:Force-limited designs are opening welding tasks to mid-sized German suppliers previously blocked by protective guarding costs.
Market Restraints
- Rare earth magnet dependency:Neodymium supply from Chinese processing facilities creates 60-90 day lead time volatility for AC servo motor production.
- EU Machinery Directive friction:CE marking requirements for autonomous decision-making systems extend certification timelines by 8-14 months.
- Technical payload ceilings:Current collaborative robot architectures top out at 25kg, excluding heavy automotive body-shop applications.
Strategic Opportunities
- India's PLI scheme for manufacturing:Component localization incentives are attracting robot system integrators to Pune and Chennai industrial corridors.
- Battery recycling automation:End-of-life EV battery disassembly requires new dexterous manipulation systems absent from current installed bases.
- 5G private networks:Real-time motion control over wireless is enabling modular cell reconfiguration without cable harness replacement.
Industry Challenges
- Mechatronics talent scarcity:Germany's automotive belt reports 40% vacancy rates for PLC programming and servo tuning specialists.
- Legacy controller integration:Proprietary fieldbus protocols from 1990s-era installations block seamless data extraction for predictive maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Robots Market |
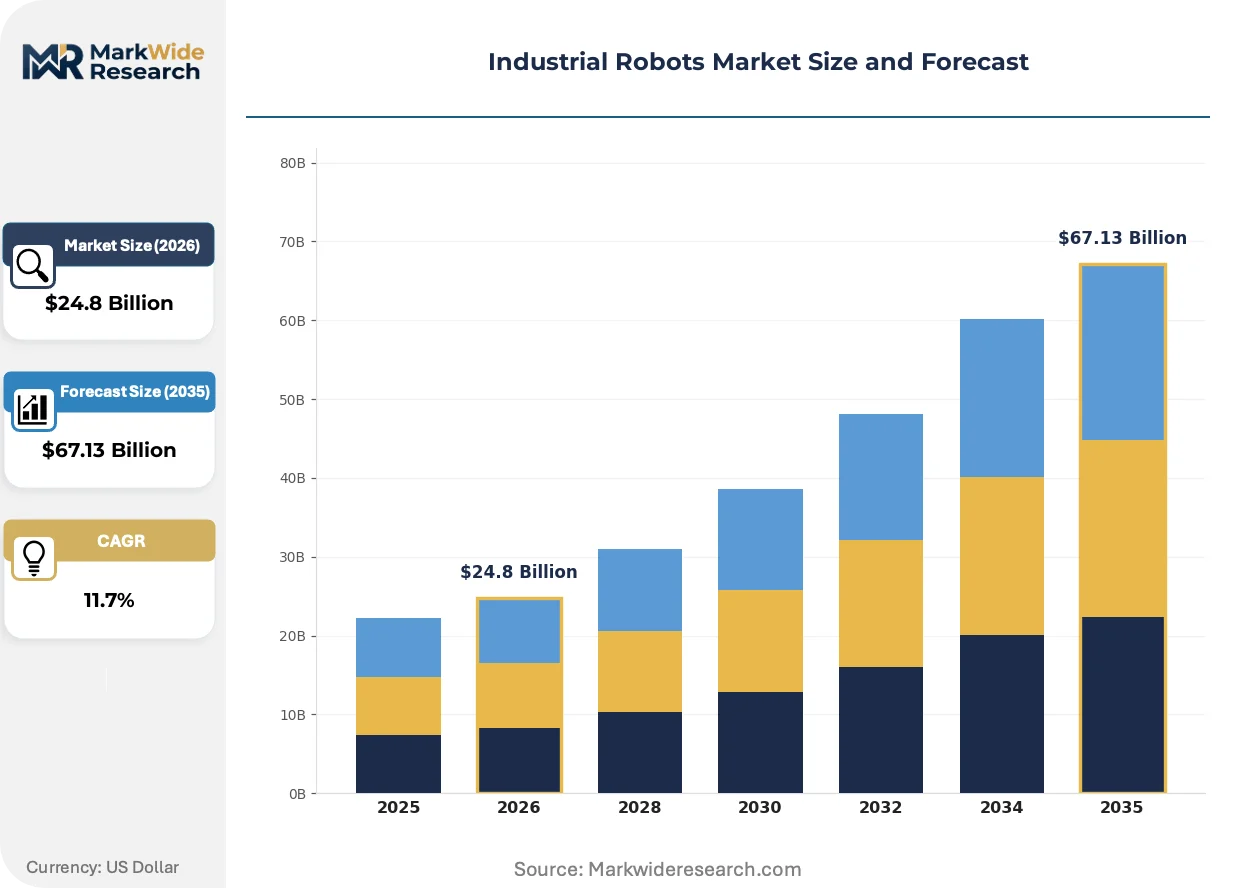
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $67.13 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Delta Robots, Cartesian Robots Application: Welding, Painting, Assembly, Material Handling End User: Automotive, Electronics, Food & Beverage, Pharmaceuticals Technology: Collaborative Robotics, Autonomous Robotics, AI Integration, Machine Vision |
| Companies Covered | FANUC Corporation, ABB, Seiko Epson Corporation, Yaskawa Electric Corporation, Kawasaki Heavy Industries, KUKA AG, Denso Corporation, Universal Robots, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Robots Market Emerging Trajectories
Software-defined motion control is collapsing the boundary between hardware vendors and system integrators, enabling end-users to reprogram workcells without manufacturer service calls.
Digital twin simulation platforms are automating offline programming workflows for automotive body-shop configurations. BMW's Leipzig and Spartanburg plants now validate 90% of robot paths virtually before physical commissioning. This compression is eliminating two-week on-site integration periods and reducing collision-related downtime.
The EU AI Act's risk-classification framework is mandating conformity assessments for autonomous robotics with embedded decision algorithms. High-risk categorization triggers third-party auditing requirements for welding and painting installations. German automotive suppliers are front-loading compliance documentation to avoid 2030 enforcement bottlenecks.
Robot-as-a-service contracting is displacing outright purchase in mid-sized electronics manufacturing. Monthly per-hour rates bundle maintenance, software updates, and retraining into predictable operating expenditures. This shift is most pronounced in South Korean semiconductor packaging facilities seeking to preserve balance-sheet flexibility during demand cycles.
Industrial Robots Market Segmentation
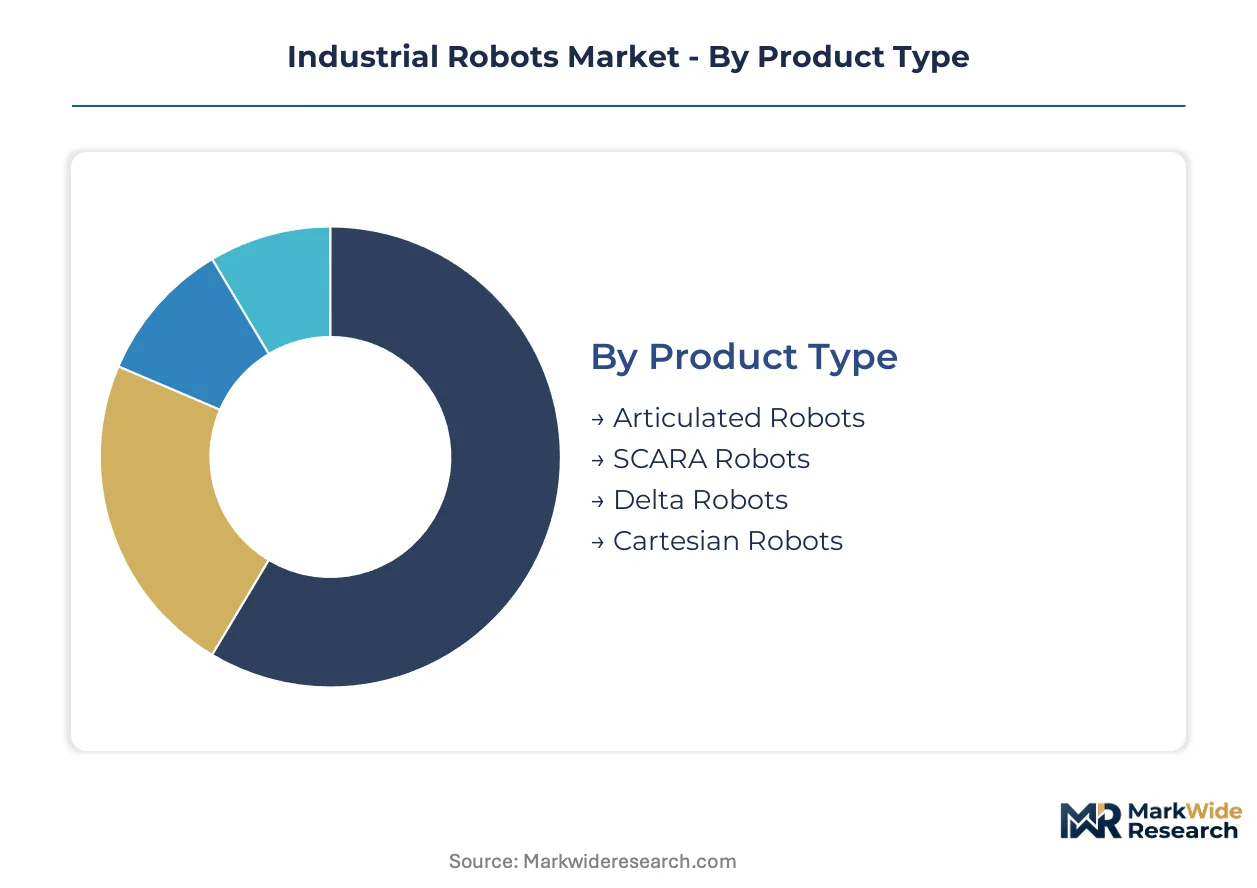
Segmentation in industrial robotics determines capital allocation cycles, spare parts inventory, and integration partner selection. Upgrade windows vary dramatically across robot architectures and end-use environments.
Product Type:
Replacement cycles differ sharply by kinematic complexity and mechanical wear patterns.
- Articulated Robots:Six-axis configurations with rotary joints dominate automotive body-shop installations. Stuttgart's EV battery assembly corridors are refreshing these systems on compressed eighteen-month cycles versus traditional five-year horizons.
- SCARA Robots:Selective compliance assembly robot arms deliver high-speed planar motion with Z-axis vertical travel. Electronics manufacturers in Jiangsu province favor SCARA lines for surface-mount device placement where repeatability tolerances reach ±0.01mm.
- Delta Robots:Parallel kinematic structures excel in lightweight pick-and-place operations at sustained velocities exceeding 300 cycles per minute.
- Cartesian Robots:Gantry-mounted linear actuators provide cost-effective positioning across large work envelopes in palletizing and machine tending.
Articulated robots sit at the top of the volume ranking, with collaborative variants climbing the fastest.
Application:
Process heat exposure and consumable wear dictate maintenance scheduling and controller refresh decisions.
- Welding:Arc and spot welding installations endure thermal cycling and spatter accumulation that degrade cable harnesses and servo motors. German automotive suppliers are retrofitting force-limited collaborative systems for low-volume jig welding previously blocked by guarding costs.
- Material Handling:Palletizing, depalletizing, and machine feeding generate the steadiest replacement demand due to continuous duty cycles and payload stress.
- Painting:Explosive atmosphere requirements mandate ATEX-certified components with specialized sealing that extends procurement lead times.
- Assembly:Precision fastening and insertion tasks are migrating to collaborative platforms with embedded torque sensing.
Material handling commands the largest installed base, though welding applications are gaining share fastest in EV manufacturing corridors.
End User:
Sector-specific regulatory pressures and automation maturity shape procurement specifications.
- Automotive:OEMs and Tier-1 suppliers deploy high-payload articulated systems across powertrain, body-in-white, and paint-shop operations. China's MIIT dual carbon mandates are forcing servo-motor efficiency upgrades across Guangdong stamping and welding facilities.
- Electronics:Semiconductor packaging and PCB assembly require micron-level placement accuracy driving machine vision integration.
- Food & Beverage:Washdown-rated IP67 enclosures and NSF-compliant lubricants dominate specification sheets for primary and secondary packaging lines.
- Pharmaceuticals:FDA 21 CFR Part 11 compliance and isolator integration requirements constrain robot selection to validated platforms with complete batch documentation.
Automotive retains the deepest installed base, with electronics expanding most quickly on precision automation demand.
Technology:
Software architecture and sensing modality determine integration complexity and safety system design.
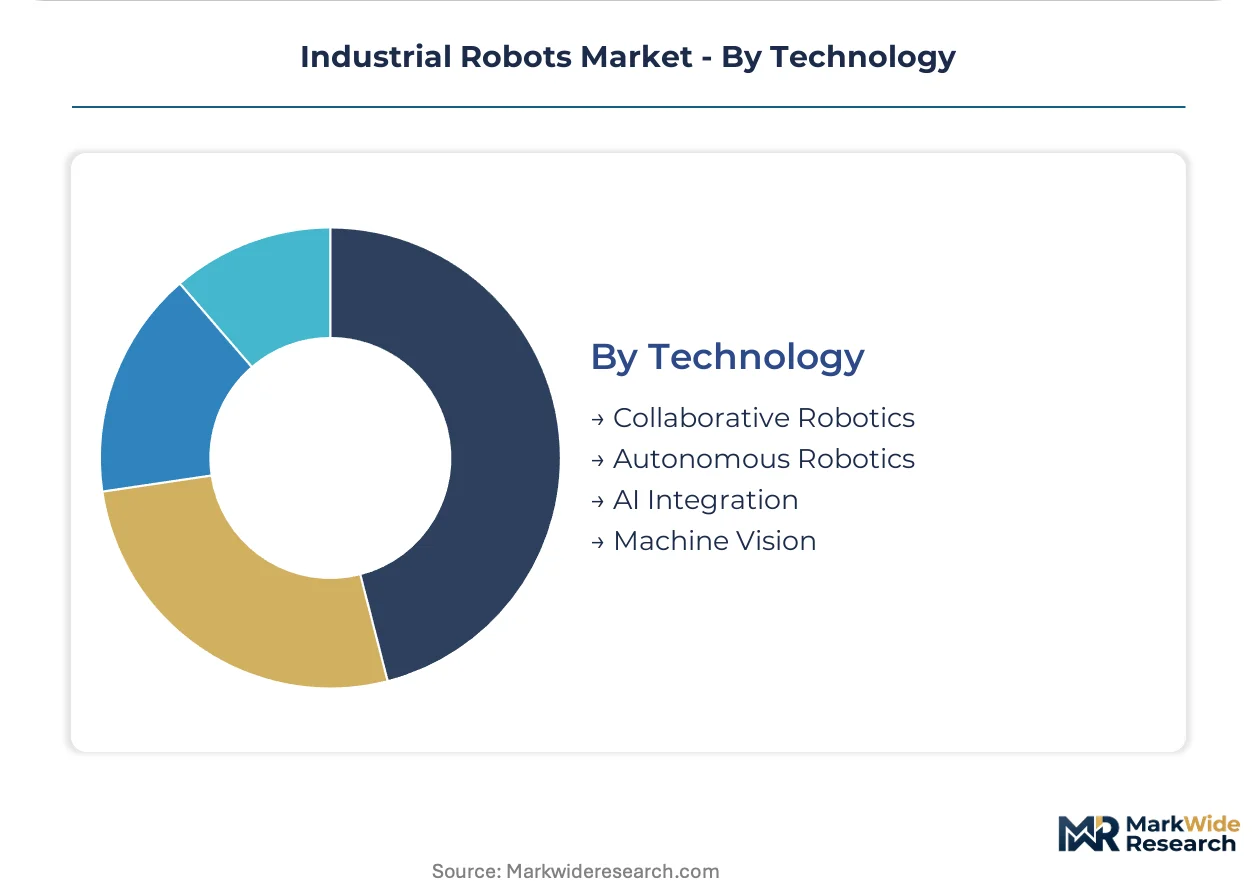
- Collaborative Robotics:Force-limited designs with power and force limiting (PFL) enable human-robot interaction without fixed guarding. Current payload ceilings at 25kg exclude heavy automotive body-shop applications.
- Machine Vision:2D and 3D vision systems with convolutional neural network processing enable adaptive part recognition and defect detection.
- AI Integration:Embedded decision algorithms for path optimization and predictive maintenance trigger EU AI Act conformity assessment requirements.
- Autonomous Robotics:Mobile manipulators with simultaneous localization and mapping navigate unstructured logistics environments.
Machine vision leads technology attachment rates, while collaborative systems are steepest expansion trajectory among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial robot industry traces its commercial origins to Japan's post-war manufacturing modernization, with Unimate's 1961 General Motors deployment establishing North American demand patterns that persist today.
China
MIIT dual carbon mandates and new energy vehicle production quotas are accelerating servo-motor efficiency requirements across Guangdong and Jiangsu manufacturing belts. SAMR-administered GB standards for industrial robot safety create separate compliance pathways for domestic suppliers. Shenzhen and Dongguan electronics corridors are integrating micron-level placement systems for battery management unit production.
Germany
Automotive OEM retooling for electric vehicle battery assembly is compressing traditional five-year capital cycles into eighteen-month refresh windows. EU Machinery Directive CE marking requirements extend certification timelines for autonomous decision-making systems. Stuttgart and Wolfsburg automotive clusters are deploying force-limited collaborative systems for low-volume jig welding previously blocked by guarding costs.
United States
OSHA machine-guarding standards shape product design by mandating risk assessments before market entry. IRA clean energy manufacturing incentives are attracting battery assembly automation investments to Michigan and South Carolina. BMW's Spartanburg plant validates 90% of robot paths through digital twin simulation before physical commissioning.
Japan
METI industrial automation policies and JIS standards maintain quality benchmarks for precision manufacturing exports. Aging workforce demographics are driving collaborative robotics adoption in Nagoya and Osaka industrial zones. Yaskawa Electric and FANUC anchor domestic supply chains for AC servo motor and CNC controller production.
South Korea
MFDS-equivalent industrial safety frameworks and semiconductor packaging demand concentrate procurement in Gyeonggi and Chungcheong provinces. Robot-as-a-service contracting is displacing outright purchase in mid-sized electronics manufacturing. Monthly per-hour rates bundle maintenance and software updates into predictable operating expenditures.
Industrial Robots Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software-integrated workcell offerings versus standalone hardware supply. The vendor base organizes into three tiers: captive component manufacturers with upstream control over servo motors and controllers; system integrators bundling hardware with offline programming platforms; and pure-play collaborative robotics specialists. Consolidation pressures favor M&A activity between mid-sized integrators and component suppliers, while geographic expansion into India's PLI-subsidized corridors accelerates.
Among Japanese-origin industrial automation conglomerates, FANUC Corporation, Yaskawa Electric Corporation, and Mitsubishi Electric Corporation exemplify the captive-component archetype through in-house production of CNC systems and servo motors. ABB and KUKA AG occupy positions within the European tier of software-integrated workcell providers. Seiko Epson Corporation represents the precision SCARA specialist segment serving electronics assembly applications.
| Leading Market Players |
|---|
| FANUC Corporation |
| ABB |
| Seiko Epson Corporation |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries |
| KUKA AG |
| Denso Corporation |
| Universal Robots |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China's Jiangsu and Guangdong manufacturing belts anchor upstream servo-motor and controller supply, compressing margins for independent European and Japanese system integrators while concentrating pricing power among captive-component conglomerates. This ownership pattern feeds directly into aftermarket service bundling and software subscription tiers that now separate premium workcell providers from hardware-commoditized competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with premium tiers commanding 40-60% markups for CE-marked autonomous systems with embedded AI decision algorithms. Certification grade under EU Machinery Directive and ISO 10218 safety tiers drive the steepest price differentiation alongside after-sales software update contracts. Cost compression in economy-tier articulated robots is intensifying because Chinese domestic suppliers are flooding export markets with GB-standard-equivalent hardware. Mid-sized German automotive suppliers exhibit the highest price sensitivity, while pharmaceutical OEMs purchasing FDA-validated platforms show minimal elasticity.
Supply Chain Analysis
Workforce-availability constraints in Japan's Nagoya industrial zone and Germany's Stuttgart automotive belt are forcing automation suppliers to relocate final assembly and testing operations to Pune and Chennai corridors under India's PLI scheme. Component manufacturing concentrates in China, Japan, and South Korea, with rare earth magnet processing for AC servo motors drawing from Chinese separation facilities. Single-source vulnerability in neodymium supply creates procurement risk for motor manufacturers. Distribution runs through authorized system integrator networks that bundle hardware with offline programming platforms and predictive maintenance software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in industrial robotics rests on software-defined motion control architectures that collapse hardware differentiation while extracting recurring revenue from predictive maintenance and digital twin subscriptions. Servo-motor efficiency upgrades under China's MIIT dual carbon mandates accelerate replacement demand, creating premium-tier pricing power for compliant suppliers.
For Market Incumbents: Anticipate collaborative robotics specialists eroding share in sub-25kg payload assembly applications by front-loading force-limited certification documentation before EU AI Act enforcement bottlenecks. Prioritize backward integration into machine vision processing hardware to defend margin position against software-integrated workcell competitors. Lock in long-term rare earth magnet supply agreements with Chinese processors to isolate AC servo motor production from 60-90 day lead time volatility.
For New Entrants and Emerging Players: System integrator partnerships in India's PLI-subsidized corridors offer the most penetrable white-space target, bypassing captive-component supply chain advantages held by Japanese conglomerates. Battery recycling automation for end-of-life EV disassembly presents uncaptured demand for dexterous manipulation systems absent from current installed bases. Lead with robot-as-a-service contracting models that convert capital expenditure into predictable operating expenditures for mid-sized electronics manufacturers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized European system integrators lacking captive servo-motor production but holding established automotive OEM relationships. Long-term viability favors suppliers with software-integrated workcell platforms capable of extracting recurring revenue across compressed eighteen-month capital refresh cycles. Watch for MIIT enforcement intensity on dual carbon mandates as the inflection signal separating compliant premium-tier suppliers from stranded hardware-commoditized competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motor Manufacturing | FANUC and Yaskawa control component costs across articulated and SCARA lines through in-house AC servo production. |
| Software-Defined Motion Control Platform Launch | ABB's offline programming platforms collapse hardware-service boundaries and eliminate manufacturer-dependent reprogramming calls. |
| Machine Vision Hardware Acquisition | Electronics assemblers in Stuttgart's automotive cluster demand micron-level placement systems for battery management unit production. |
| Geographic Manufacturing Footprint Expansion | Component localization incentives under India's PLI scheme attract robot system integrators to Pune and Chennai industrial corridors. |
| Robot-as-a-Service Contracting Model | South Korean semiconductor packaging facilities preserve balance-sheet flexibility through monthly per-hour rates bundling maintenance and software updates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists alongside secondary validation through SEC filings, customs and trade data, SAMR GB standard publications, and EU Machinery Directive enforcement records. Bottom-up installed base estimates triangulated against top-down macroeconomic production indices across automotive, electronics, and pharmaceutical manufacturing corridors.
Segment-weighting approaches modeled robot architecture, application environment, end-user industry, and technology attachment rates across the projection horizon. CAGRs derived from historical replacement cycle compression, regulatory mandate timing, and technology diffusion curves in precision automation. Forecast inputs incorporated MIIT dual carbon enforcement trajectories, EU AI Act risk-classification implementation, and 5G private network deployment rates enabling wireless real-time motion control.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruption, EU autonomous robotics certification delays, and mechatronics talent scarcity in Germany's automotive belt. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution rates. Material deviation in MIIT mandate timing or neodymium processing capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
China Autonomous Mobile Robot Market