
 Drain Camera Market | 2026-2036
Drain Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Drain Camera Market Foresight
Aftermarket service revenue is narrowing toward software subscriptions and cloud-based inspection data management. RIDGID leverages its Emerson parent company's industrial distribution network to sustain parts availability across North American rental channels. Envirosight competes through specialized training programs and certification ecosystems that anchor municipal customer loyalty. Deep Trekker differentiates with portable, battery-operated underwater systems that navigate confined-space infrastructure without tethered power requirements.
A drain camera is a specialized optical inspection device comprising a flexible or rigid borescope, high-resolution image sensor, integrated lighting array, and cable reel system designed to visually assess interior conditions of wastewater conduits, storm drains, and process piping. Push cameras and robotic crawlers dominate equipment fleets, with robotic systems capturing expanding share as municipalities automate long-distance sewer assessment. Digital and wireless technologies are displacing analog transmission standards, while preventive maintenance applications outpace reactive drain cleaning in contract value per deployment.
EPA enforces Clean Water Act provisions that mandate regular sewer system evaluation, compelling municipalities to maintain certified inspection equipment. OSHA confined-space entry regulations shape camera specifications for operator safety in hazardous vault environments. Stakeholders must monitor how AI defect-classification accuracy standards from ISO and national infrastructure agencies redefine minimum acceptable image resolution and reporting formats.
Market Dynamics
EPA Clean Water Act enforcement is accelerating equipment replacement cycles as municipalities face combined sewer overflow mandates and AI-powered defect recognition standards redefine minimum inspection protocols across wastewater infrastructure.
Growth Catalysts
- Combined Sewer Overflow Mandates:EPA enforcement under the Clean Water Act compels US municipalities to maintain certified robotic crawler fleets for preventive sewer assessment, expanding procurement of automated inspection systems.
- AI Defect Classification:Machine vision algorithms trained on pipe degradation datasets are automating crack and infiltration detection, reducing manual video review time for municipal engineering departments.
- Germany:Federal wastewater infrastructure modernization programs are funding robotic crawler acquisitions by municipal utilities, with procurement concentrated in aging Ruhr Valley and Bavarian sewer networks.
Market Restraints
- High-Resolution Sensor Costs:CMOS image sensors and specialized lighting arrays represent concentrated input cost exposure, with supply chain concentration in East Asian semiconductor foundries creating price volatility for equipment manufacturers.
- Tethered Power Limitations:Traditional crawler systems require generator or vehicle-mounted power supplies, restricting deployment in remote storm drain networks and increasing mobilization costs for rural utilities.
- OSHA Confined-Space Compliance:Entry permit requirements and atmospheric monitoring protocols for hazardous vault environments add operational friction and training overhead to inspection deployments.
Strategic Opportunities
- Japan:Earthquake-resistant infrastructure assessment programs and aging Tokyo-Osaka sewer corridors present underpenetrated demand for portable battery-operated systems that navigate confined spaces without tethered power.
- Cloud-Based Data Management:Subscription inspection data platforms are displacing on-premise storage, enabling municipal customers to centralize condition assessment records across distributed sewer networks.
- Stormwater Infrastructure:Climate adaptation funding for urban flood resilience is extending camera deployment beyond sanitary sewers into culvert and detention basin inspection applications.
Industry Challenges
- Certified Operator Shortage:NASSCO PACP certification requirements for defect coding create bottlenecks as utilities compete for trained inspection technicians capable of operating robotic crawler systems.
- Legacy Analog System Integration:Municipal fleets with substantial sunk investment in coaxial cable-based push cameras face capital planning conflicts when upgrading to digital wireless transmission standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drain Camera Market |
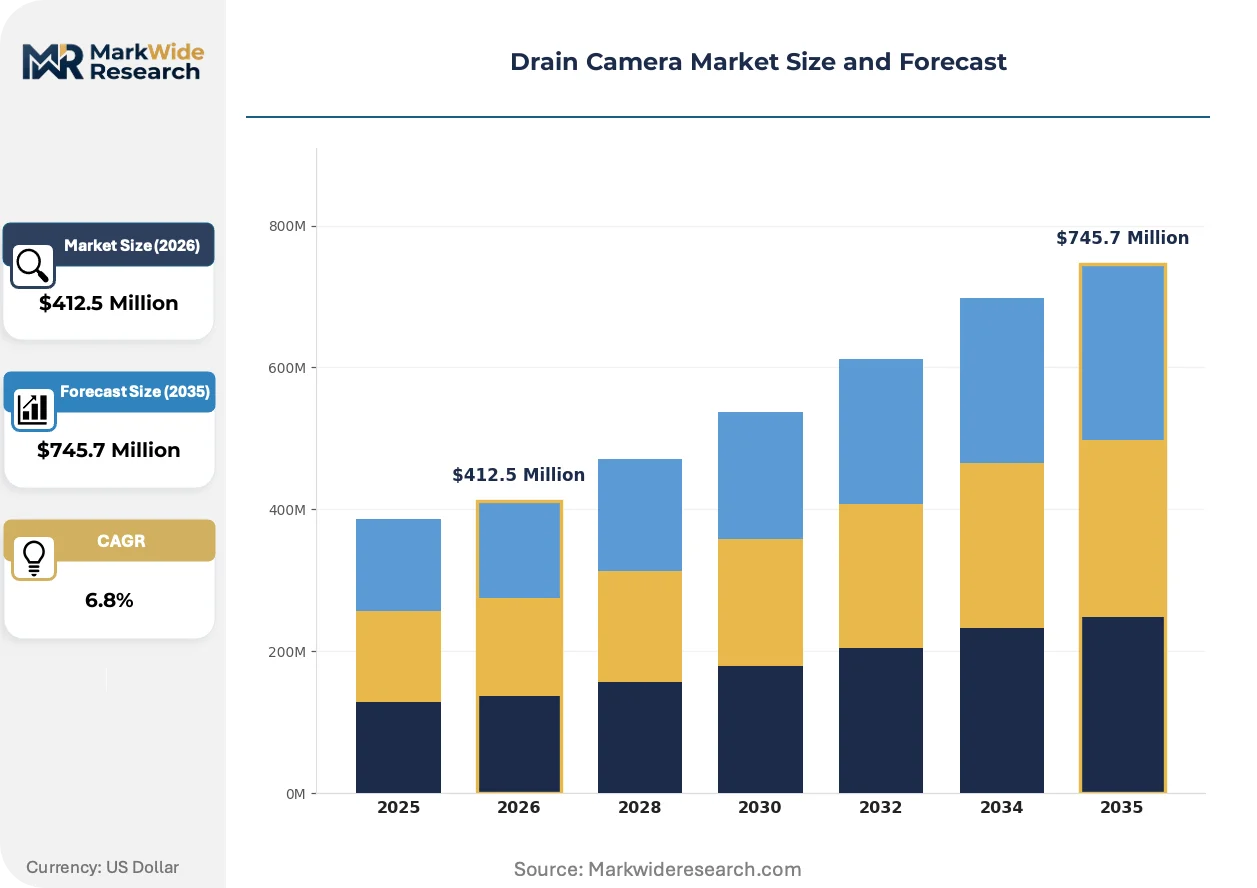
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Leveling Cameras, Push Cameras, Robotic Cameras, Inspection Crawlers End User: Plumbing Services, Municipalities, Industrial Facilities, Homeowners Technology: Analog, Digital, Wireless, Fiber Optic Application: Pipe Inspection, Drain Cleaning, Sewer Inspection, Preventive Maintenance |
| Companies Covered | RIDGID (Emerson Electric Co.), CUES Inc., Envirosight LLC, Rothenberger, Rausch Electronics USA, Deep Trekker Inc., Spartan Tool LLC, iPEK International GmbH (IDEX), General Wire Spring Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drain Camera Market Shifts & Advancements
Digital wireless transmission standards are compressing equipment lifecycles as AI-powered analytics platforms reshape how inspection data generates maintenance decisions across municipal engineering departments.
Self-propelled robotic crawler systems equipped with pan-tilt-zoom cameras and laser profiling capabilities are collapsing the distinction between routine preventive assessment and detailed structural engineering surveys. German municipal utilities are deploying these systems for automated distance runs exceeding 500 meters, eliminating multiple mobilizations previously required with manual push cameras. The technology is collapsing inspection cost structures for large-diameter interceptor sewers while generating standardized condition data compatible with asset management software.
EPA enforcement of combined sewer overflow consent decrees is mandating continuous monitoring infrastructure in US municipalities, with inspection frequency requirements driving equipment utilization rates higher. The regulatory pressure is accelerating replacement of analog video systems with digital recording platforms capable of metadata tagging and automated report generation. Large US utilities in the Great Lakes and Northeast regions are responding by centralizing inspection programs and standardizing on equipment formats that integrate with GIS-based asset databases.
Preventive maintenance contracts are displacing reactive emergency call-outs as the dominant procurement model for municipal sewer inspection services. Engineering departments are bundling scheduled assessment frequencies with software subscriptions that track pipe degradation over time, unbundling equipment ownership from data analysis. This shift is most visible in the United States, where aging infrastructure liability concerns and EPA consent decree timelines are concentrating procurement authority at metropolitan utility district level rather than individual municipality contracts.
Drain Camera Market Segmentation
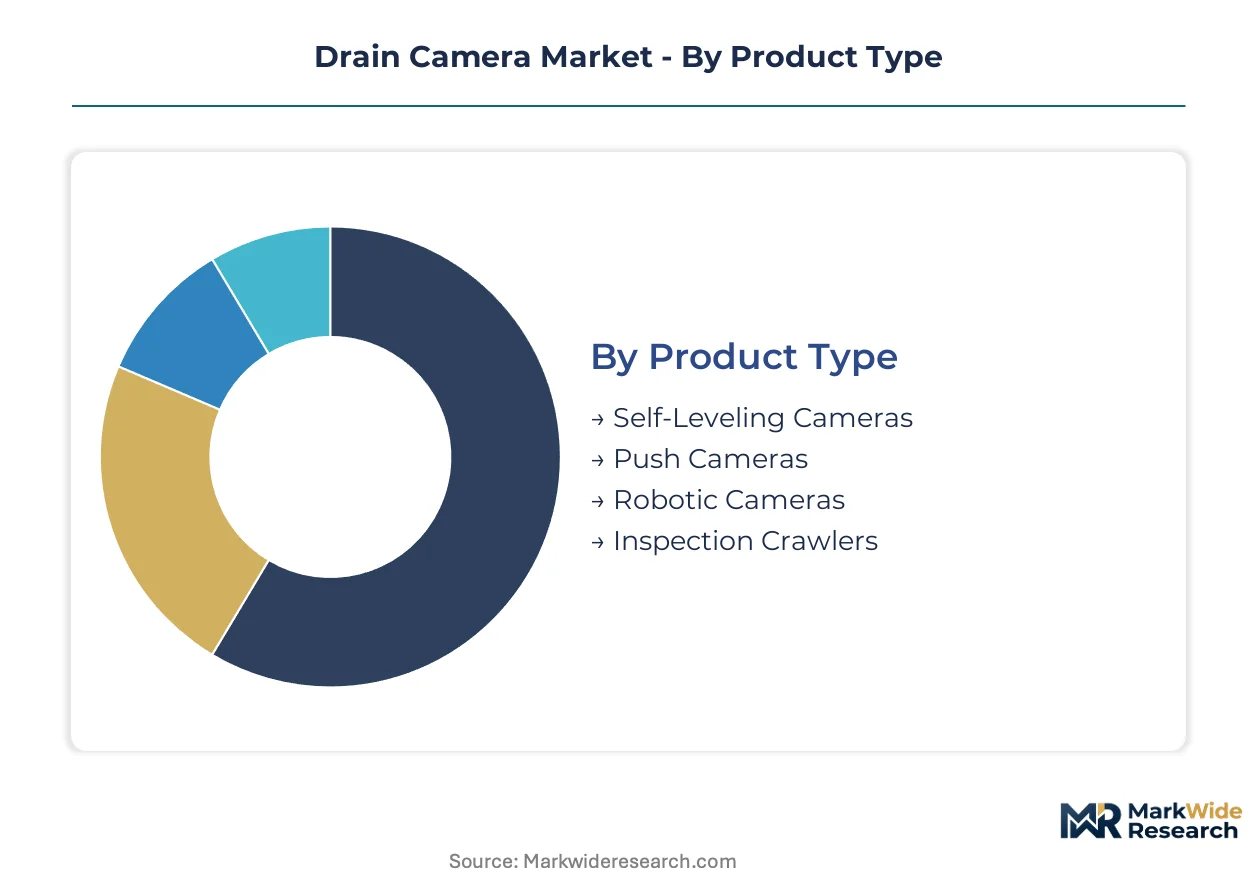
Drain camera procurement patterns diverge sharply across equipment formats, operator capabilities, and infrastructure ownership models. Municipal engineering departments prioritize robotic crawler systems for interceptor sewer networks, while plumbing contractors favor portable push cameras for residential service calls. Understanding these segment boundaries clarifies where technology investments concentrate and which customer types drive replacement cycles.
Product Type:
Use-case spectrum spans manual push operations through fully automated robotic assessment, with power requirements and conduit diameter dictating equipment selection across municipal and commercial fleets.
- Robotic Cameras:Self-propelled crawler systems integrate pan-tilt-zoom optics, laser profiling, and cable reel mechanisms for unmanned operation in large-diameter interceptors exceeding 300mm. German Ruhr Valley utilities deploy these for automated runs surpassing 500 meters, collapsing mobilization costs while generating PACP-compatible condition data for asset management platforms.
- Push Cameras:Flexible borescope assemblies with integrated LED arrays and manual cable feed systems dominate residential plumbing and small-diameter lateral inspection. United States plumbing service contractors concentrate procurement here due to lower capital thresholds and compatibility with standard van-mounted power supplies.
- Self-Leveling Cameras:Gravity-stabilized camera heads maintain consistent orientation in inclined or vertical pipe sections, reducing operator adjustment time in complex sewer geometries.
- Inspection Crawlers:Wheeled or tracked chassis designs optimized for specific pipe diameter ranges, with modular wheel kits adapting to varying conduit conditions without platform replacement.
The dominant share belongs to Push Cameras, while Robotic Cameras are closing the gap fastest.
End User:
Customer type determines procurement authority structure, with centralized municipal purchasing contrasting against fragmented commercial service contracting.
- Municipalities:Metropolitan sewer districts and city engineering departments maintain certified inspection fleets under EPA Clean Water Act consent decrees, with procurement centralized at utility-district level in the United States. These entities drive demand for robotic systems with GIS integration and automated defect reporting.
- Plumbing Services:Independent contractors and regional service chains acquire portable push cameras for reactive drain cleaning and residential lateral inspection, with equipment financing structured around job-site revenue per deployment.
- Industrial Facilities:Process plant maintenance departments deploy specialized cameras for cooling water intake, effluent discharge, and internal process piping assessment under confined-space safety protocols.
- Homeowners:Rental channel and consumer-grade equipment purchases for single-use diagnostic applications, with minimal attachment to certification or data management requirements.
Municipalities command the largest equipment investment per customer, though Plumbing Services represent the broadest addressable customer base.
Technology:
Transmission standard selection shapes equipment lifecycle economics, with digital platforms displacing legacy analog infrastructure across municipal upgrade programs.
- Digital:CMOS sensor-based recording with metadata tagging, GPS positioning, and automated report generation. United States Great Lakes utilities mandate digital platforms for combined sewer overflow monitoring compliance, with file formats standardized for GIS asset database integration.
- Wireless:Battery-operated transmission eliminating tethered power and coaxial cable drag, enabling deployment in remote storm drain networks where vehicle access is restricted. Japanese earthquake-resistant infrastructure programs favor these systems for confined-space vault assessment.
- Analog:Coaxial cable-based composite video transmission with established technician familiarity, though facing replacement pressure from municipal digital upgrade mandates.
- Fiber Optic:High-bandwidth signal transmission for ultra-high-definition inspection and extended cable runs beyond 300 meters, concentrated in specialized structural engineering survey applications.
Digital technology holds established leadership, while Wireless platforms are expanding most quickly into battery-constrained deployment environments.
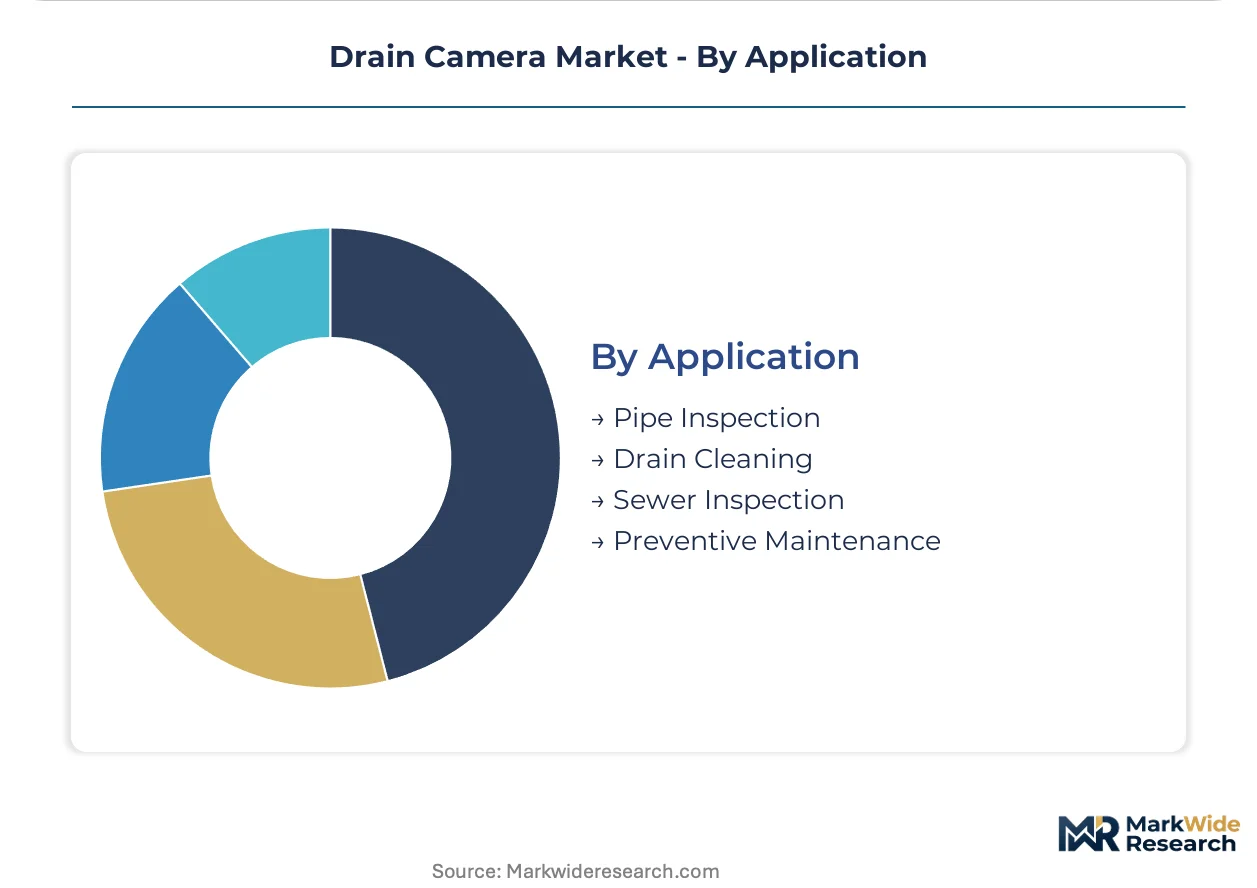
Application:
Service model evolution shifts procurement from reactive emergency response toward scheduled preventive assessment with software-integrated data retention.
- Sewer Inspection:Systematic condition assessment of sanitary and combined sewer networks under regulatory compliance timelines, generating PACP-coded defect records for capital planning prioritization.
- Preventive Maintenance:Scheduled assessment frequencies bundled with cloud-based degradation tracking, displacing reactive call-out economics in United States metropolitan utility districts.
- Pipe Inspection:General-purpose conduit assessment spanning process piping, storm drains, and building drainage systems without regulatory compliance driver.
- Drain Cleaning:Diagnostic pre-work and verification post-work for mechanical clearing operations, with camera deployment secondary to the primary service revenue.
Sewer Inspection generates the highest equipment specification requirements, though Preventive Maintenance is gaining share fastest through subscription-based service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. United States municipalities favor robotic crawler fleets under EPA consent decrees, while German utilities prioritize automated long-distance assessment systems, and Japanese operators demand portable battery-operated units for confined-space vault environments.
United States
Metropolitan sewer districts in the Great Lakes and Northeast regions drive procurement of GIS-integrated robotic systems. EPA Clean Water Act enforcement mandates combined sewer overflow monitoring, compelling utilities to replace analog video equipment with digital recording platforms. Chicago and Cleveland utilities are centralizing inspection programs at district level rather than individual municipality contracts.
Germany
Federal wastewater infrastructure modernization programs fund robotic crawler acquisitions across aging Ruhr Valley and Bavarian sewer networks. Municipal utilities deploy self-propelled systems for automated runs exceeding 500 meters, collapsing mobilization costs for large-diameter interceptors. The Bavarian cluster around Munich anchors procurement for pan-tilt-zoom systems with laser profiling capabilities.
Japan
Earthquake-resistant infrastructure assessment programs generate demand for wireless battery-operated systems navigating confined spaces without tethered power. METI-funded corridor modernization targets aging Tokyo-Osaka sewer networks. Osaka utilities are deploying portable units for vault assessment where vehicle access is restricted.
United Kingdom
Privatized water utilities under OFWAT regulatory pressure consolidate inspection procurement across regional operating companies. Thames Water and United Utilities are standardizing on digital platforms with automated defect reporting. The Southeast England cluster drives adoption of cloud-based inspection data management subscriptions.
Canada
Municipal engineering departments in Ontario and British Columbia adopt EPA-aligned inspection protocols for cross-border infrastructure compliance. Environment Canada stormwater regulations extend camera deployment into culvert and detention basin applications. Toronto and Vancouver utilities are bundling preventive maintenance contracts with software subscriptions.
Drain Camera Market Competitive Landscape
Capability concentration sits with specialized crawler manufacturers; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: industrial equipment divisions with distribution networks, dedicated inspection technology specialists with certification ecosystems, and portable system innovators with battery-operated architectures. Strategic moves center on software subscription bundling and cloud-based data platform integration.
Among diversified industrial parents, RIDGID leverages Emerson Electric's distribution infrastructure across North American rental channels. Envirosight occupies a position within the specialist tier, anchoring municipal customer relationships through training and certification programs. Deep Trekker exemplifies the portable innovation archetype, representing battery-operated underwater system differentiation for confined-space deployment.
| Leading Market Players |
|---|
| RIDGID (Emerson Electric Co.) |
| CUES Inc. |
| Envirosight LLC |
| Rothenberger |
| Rausch Electronics USA |
| Deep Trekker Inc. |
| Spartan Tool LLC |
| iPEK International GmbH (IDEX) |
| General Wire Spring Company |
| Others |
Supply & Pricing Matrix
East Asian semiconductor foundries concentrate CMOS image sensor and specialized LED array production, anchoring input cost volatility that compresses margins for equipment manufacturers while concentrating pricing power with upstream component suppliers.
Pricing Analysis
Long-term municipal procurement contracts dominate equipment sales, with three-tier pricing structure across premium robotic crawler systems, standard push camera assemblies, and economy-grade rental units. Price differentiation hinges on NASSCO PACP certification tier and bundled software subscription depth. Pricing pressure stems from EPA-mandated digital upgrade cycles forcing fleet replacements. Municipal utilities exhibit lowest price sensitivity due to consent decree compliance deadlines, while independent plumbing contractors face acute margin compression.
Supply Chain Analysis
Taiwanese and South Korean contract manufacturers hold concentrated capacity for high-resolution CMOS sensors and solid-state lighting modules. Equipment assembly draws from Chinese machined chassis suppliers and German precision cable reel specialists. Single-source vulnerability concentrates in advanced image sensor supply. Distribution runs through Emerson's North American industrial rental network alongside specialized municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: EPA consent decrees and NASSCO certification requirements create switching costs that cement incumbent positions against unqualified challengers.
For Market Incumbents: Entrench municipal relationships by embedding PACP-certified training programs directly into metropolitan utility district procurement specifications. Deepen backward integration into cloud-based inspection data platforms to capture recurring subscription revenue. Counter portable battery-operated challengers by acquiring tethered-to-wireless conversion technology.
For New Entrants and Emerging Players: Establish a beachhead in Japan's earthquake-resistant infrastructure assessment segment, where METI-funded programs favor wireless battery-operated systems for confined-space vault deployment. Target Osaka utilities with localized operator training partnerships. Lead with stormwater culvert inspection applications where regulatory compliance is emerging rather than entrenched.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed inspection technology specialists holding NASSCO certification ecosystems and municipal customer lock-in. Five-to-ten-year viability hinges on software subscription attach rates displacing equipment-centric revenue. Monitor EPA consent decree enforcement intensity across Great Lakes utilities as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Subscription Bundling | Recurring revenue from cloud-based PACP data management displaces one-time equipment sales at Chicago-area utilities. |
| Wireless Battery Platform Development | Untethered power architecture opens remote storm drain deployments previously inaccessible to vehicle-mounted systems. |
| Certification Ecosystem Investment | NASSCO PACP training programs anchor municipal customer loyalty and create procurement specification barriers. |
| Geographic Manufacturing Footprint | Regional assembly near German Ruhr Valley utilities reduces mobilization logistics for 500-meter automated crawler runs. |
| AI Defect Classification Integration | Machine vision automation reduces manual video review burden for EPA compliance reporting at Cleveland metropolitan districts. |
Research Methodology
Desk research of EPA consent decree filings, municipal procurement databases, and NASSCO certification records preceded structured interviews with municipal engineering directors, robotic crawler fleet managers, and plumbing service contractors. Secondary validation drew from equipment manufacturer technical specifications, trade association training program data, and infrastructure asset management software disclosures. Bottom-up segment sizing triangulated against top-down regulatory mandate projections.
Assumptions held EPA enforcement timelines and NASSCO certification requirements constant while varying municipal budget allocation patterns and technology substitution rates across the analysis window. Segmentation modeling spanned equipment format, transmission technology, end-user type, and application service model. CAGRs derived from equipment replacement cycle analysis tied to consent decree compliance deadlines and digital platform upgrade mandates.
Sensitivities concentrate around EPA enforcement intensity variations, CMOS sensor supply disruptions, and municipal budget freeze scenarios. Forecasts reflect documented regulatory assumptions and infrastructure age demographics. Quarterly review of consent decree settlement announcements and semiconductor foundry capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
India Asset Tracking Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Temperature Data Loggers Market
Sensors
Smart Barcode Readers Market
Sensors
Micro Location Technology Market
Sensors
Asset Tags Market
Sensors
Lidar in Mapping Market
Sensors
Vibration Monitoring Market
Sensors
Barcode Scanner Market
Sensors
Wireless RFID Readers Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Remote Sensing Technology Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Europe Remote Sensing Technology Market