
 Data Center Robotics Market | 2026-2036
Data Center Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Robotics Market Intelligence
Multi-source procurement of robotic subsystems is recalibrating how data center operators balance integration cost against vendor lock-in risk. Geek+ leverages its AMR software stack to anchor deployments across Asian hyperscale facilities. Amazon Robotics sustains in-house production of drive units and navigation modules, controlling a captive supply chain for its fulfillment-adjacent server farm operations. Hitachi Vantara differentiates through predictive maintenance algorithms that extend robot fleet uptime in mission-critical infrastructure environments.
Data center robotics encompasses autonomous systems engineered for server rack transport, cable management, thermal monitoring, and predictive maintenance within climate-controlled IT facilities, typically operating on lithium-ion powertrains with sub-millimeter positioning accuracy via LiDAR and SLAM mapping. Autonomous Mobile Robots dominate current procurement volumes as operators prioritize flexible fleet scaling over fixed conveyor infrastructure. Machine Learning and Computer Vision segments capture expanding R&D allocation as these technologies enable real-time anomaly detection in server aisle patrol applications. Cloud Service Providers represent the most concentrated end-user demand pool, driven by their need to minimize human entry into high-security white spaces.
OSHA guidelines for industrial robot safety and the EU AI Act's risk-classification framework for autonomous systems are tightening compliance thresholds for cross-border equipment certification. ISO 10218 standards for robot safety integrity now shape procurement specifications for data center operators in North America and Europe. Stakeholders must monitor how evolving liability frameworks for autonomous decision-making in critical infrastructure reshape insurance and deployment governance across jurisdictions.
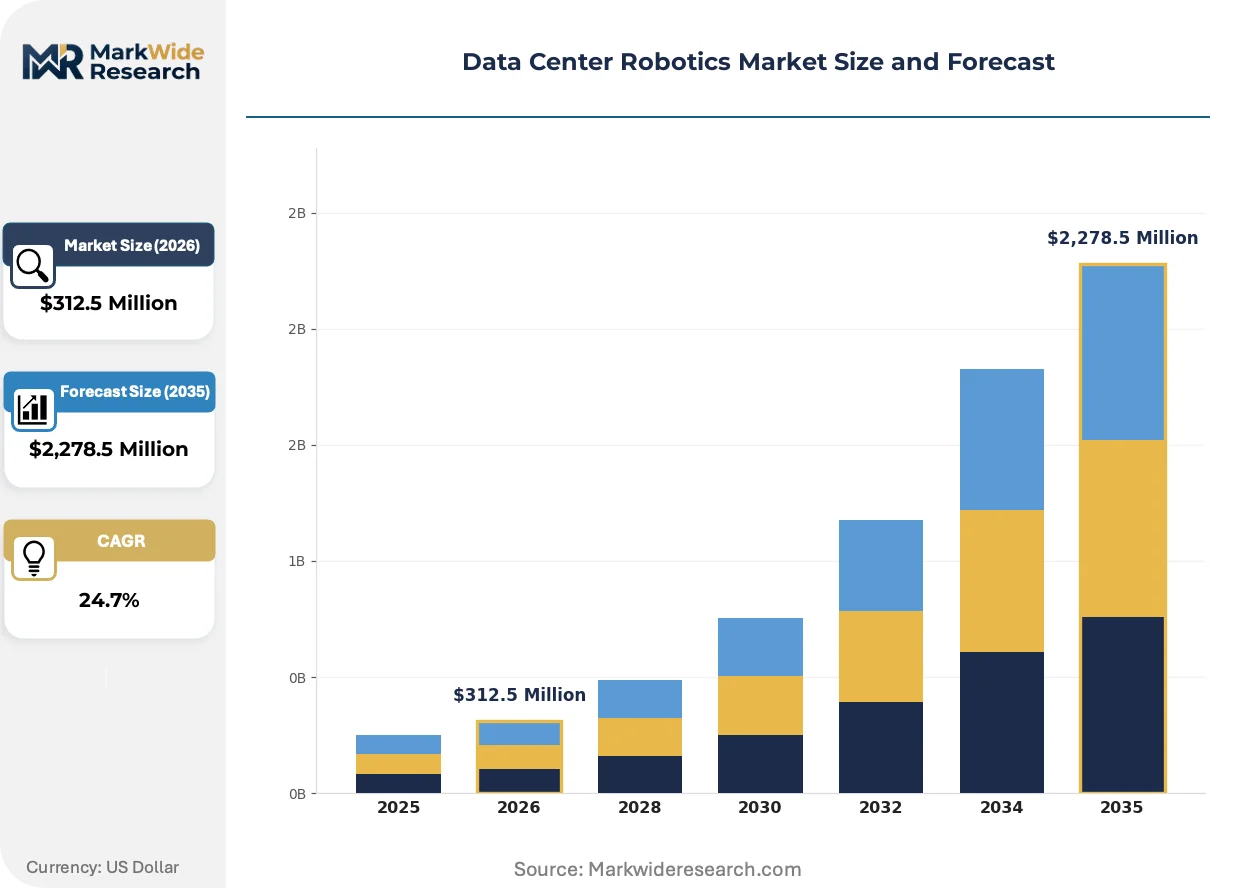
Market Dynamics
Autonomous fleet deployments across hyperscale campuses are compressing operational costs while EU AI Act risk classifications force recertification timelines for mobile robotic platforms entering European facilities.
Growth Catalysts
- EU AI Act risk-tiering:Mandatory conformity assessments for high-risk autonomous systems create certified supplier pools that lock out uncertified competitors.
- Cloud Service Provider capex cycles:Hyperscale operators in the United States, Germany, and China are expanding robot fleets to minimize human entry into secure white spaces.
- LiDAR-SLAM integration:Sub-millimeter positioning accuracy enables server rack transport without fixed conveyor infrastructure, reducing facility retrofit costs.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in East Asia expose fleet operators to shipping disruption and tariff exposure.
- ISO 10218 compliance friction:Safety integrity certification for collaborative robots extends procurement cycles by eight to fourteen months in North American and European markets.
- Fixed infrastructure substitution:Established conveyor and automated storage systems in legacy data centers delay AMR adoption where sunk costs remain unamortized.
Strategic Opportunities
- Edge facility penetration:Smaller regional data centers in India and Brazil remain underserved by current vendor configurations optimized for mega-scale campuses.
- Predictive maintenance convergence:Machine learning algorithms fused with thermal imaging sensors enable real-time anomaly detection during autonomous patrol routes.
- OSHA guideline expansion:Emerging federal safety protocols for industrial human-robot collaboration will mandate fleet upgrades across United States facilities.
Industry Challenges
- Mechatronics talent scarcity:Shortages in robotics integration engineering and SLAM algorithm development constrain deployment velocity for mid-scale operators.
- Cross-border certification fragmentation:Divergent safety standards between OSHA, EU AI Act implementations, and Japan's METI guidelines force redundant testing for multi-national fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Robotics Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,278.5 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Mobile Robots, Robotic Arms, Automated Guided Vehicles, Carton Handling Robots Technology: Machine Learning, Computer Vision, Sensor Technology, AI Algorithms End User: Cloud Service Providers, Telecom Companies, Data Center Operators, Enterprises Deployment: On-Premises, Hybrid Setup, Fully Automated, Cloud-Based |
| Companies Covered | GreyOrange, Seegrid, Amazon Robotics, Hitachi Vantara, Vertiv, Geek+, OTTO Motors, Lenovo, Locus Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Robotics Market Strategic Shifts & Innovations
Machine learning inference at the edge is compressing response latencies for thermal anomaly detection, while regulatory frameworks harden around autonomous decision-making in critical infrastructure environments.
Computer vision systems are converging with thermal imaging arrays to enable simultaneous server health monitoring and physical security patrol. Cloud Service Providers in the United States and Germany are deploying these fused sensor packages across aisle-roaming AMR fleets. This convergence is collapsing separate inspection and surveillance workflows into single autonomous passes, reducing per-rack operational labor hours.
The EU AI Act's risk-classification framework for autonomous systems is mandating conformity assessments before high-risk robot deployments enter European data centers. Industrial consequence includes documented algorithmic transparency requirements and human oversight protocols for thermal inspection decisions. Facility operators in Germany and France are front-loading compliance investments to avoid deployment freezes during certification backlog periods.
Hyperscale buyers are consolidating vendor relationships around full-stack fleet management contracts that bundle hardware, software, and predictive maintenance. Traditional subsystem procurement through separate LiDAR, drive unit, and navigation module suppliers is losing share to integrated platform vendors. This pattern is most pronounced in United States and Chinese markets where Cloud Service Providers operate densest campus concentrations.
Data Center Robotics Market Segmentation
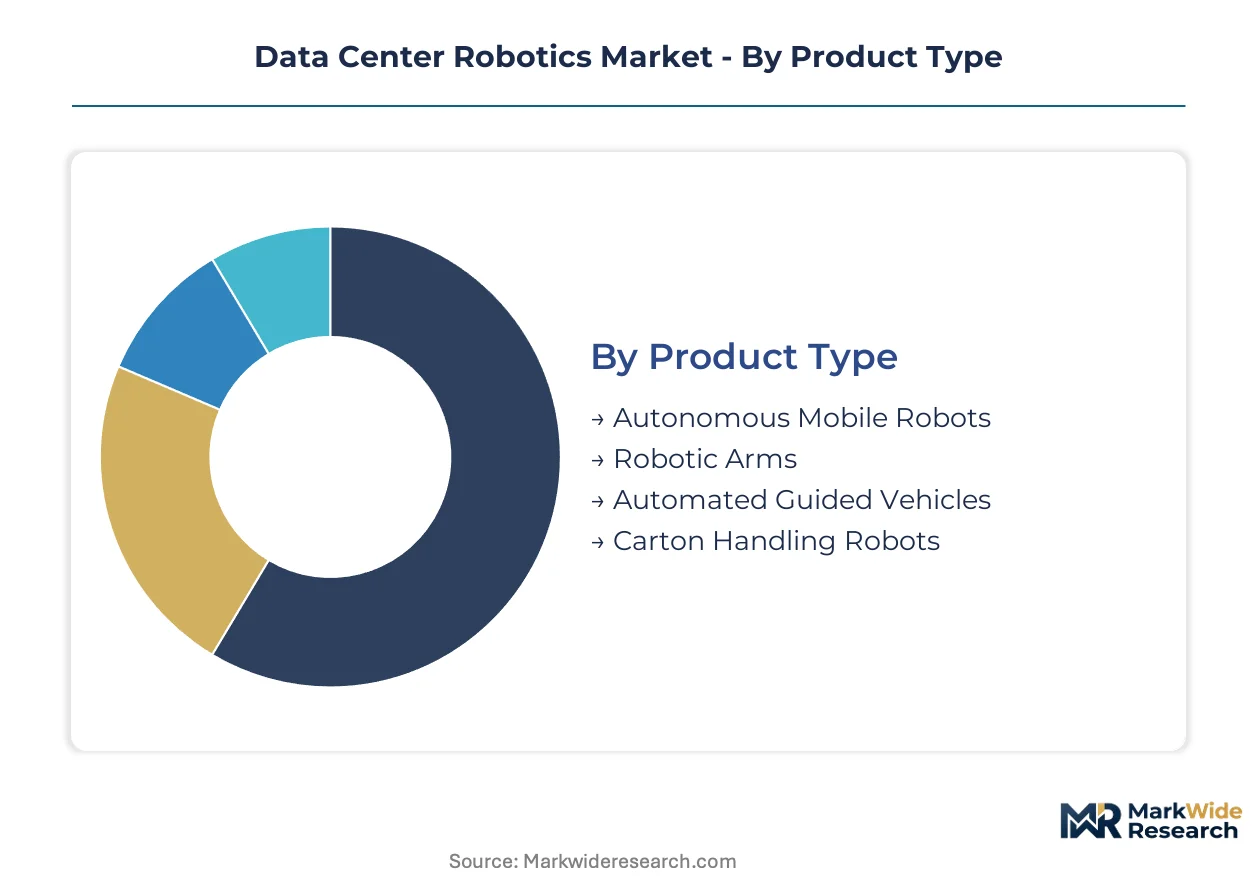
Segmentation in data center robotics reveals how procurement priorities diverge between hyperscale operators optimizing for fleet scale and regional facilities prioritizing deployment flexibility. Understanding these splits enables vendors to align R&D investment with buyer willingness-to-pay across hardware, software, and service bundles.
Product Type:
Cost tier differentiation separates buyers pursuing full-stack fleet contracts from those assembling subsystems through multi-source procurement.
- Autonomous Mobile Robots:LiDAR-SLAM navigation platforms operating on lithium-ion powertrains enable sub-millimeter positioning for server rack transport without fixed conveyor infrastructure. Cloud Service Providers in the United States and Germany deploy AMR fleets across white spaces to minimize human entry, compressing operational labor hours per aisle patrol cycle. AMRs lead volumes today; Robotic Arms are gaining share fastest.
- Robotic Arms:Articulated manipulators with six-plus degrees of freedom execute cable management and component installation tasks in constrained rack environments. Demand concentrates among Telecom Companies retrofitting legacy facilities where aisle width precludes mobile platform navigation. ISO 10218 safety certification extends procurement cycles by eight to fourteen months in North American and European markets.
- Automated Guided Vehicles:Magnetic tape or QR-code guided transport systems move server racks along predetermined facility routes. Enterprises with predictable workload patterns favor AGVs where route flexibility remains secondary to capital cost minimization.
- Carton Handling Robots:Specialized end-effector systems manage packaging material flow for equipment receiving and decommissioning workflows. Data Center Operators deploy these at facility loading docks to automate inbound server rack staging.
AMR procurement dominates hyperscale capex cycles; Robotic Arms capture expanding share in retrofit-heavy Telecom segments.
Technology:
Application maturity determines whether buyers prioritize proven inference engines or experimental sensor fusion architectures.
- Machine Learning:Edge-deployed inference models compress response latencies for thermal anomaly detection during autonomous patrol routes. Cloud Service Providers allocate expanding R&D budgets to ML-enabled predictive maintenance algorithms that extend robot fleet uptime. Machine Learning leads volumes today; AI Algorithms are expanding most quickly.
- Computer Vision:Fused optical and thermal imaging arrays enable simultaneous server health monitoring and physical security patrol. German hyperscale operators front-load compliance investments to meet EU AI Act algorithmic transparency requirements for vision-based inspection decisions.
- Sensor Technology:LiDAR, ultrasonic, and infrared arrays provide environmental mapping and collision avoidance inputs. Procurement concentrates among mid-scale Data Center Operators lacking in-house sensor integration capabilities.
- AI Algorithms:Decision-making frameworks for autonomous navigation and task prioritization in dynamic facility environments. The EU AI Act's high-risk classification mandates conformity assessments before European deployment, creating certified supplier pools.
Machine Learning anchors current procurement; AI Algorithms face steepest regulatory-driven expansion trajectories.
End User:
Customer type shapes whether deployments prioritize security isolation, network latency reduction, or operational cost compression.
- Cloud Service Providers:Hyperscale operators operating densest campus concentrations in the United States, Germany, and China consolidate vendor relationships around full-stack fleet management contracts. CSP capex cycles drive dominant procurement volumes; Enterprises are climbing the fastest.
- Telecom Companies:Network infrastructure operators retrofit legacy central offices for edge computing workloads. Robotic deployments focus on cable management automation in space-constrained environments.
- Data Center Operators:Colocation and wholesale facility managers balance tenant security requirements against operational efficiency gains. Procurement emphasizes ISO 10218-compliant collaborative robots for shared white space access.
- Enterprises:Private data center operators in financial services and healthcare verticals prioritize hybrid deployment models with human oversight protocols. OSHA guideline expansion for industrial human-robot collaboration will mandate fleet upgrades across United States facilities.
Cloud Service Providers dominate current procurement; Enterprises represent the steepest expansion trajectory as vertical-specific compliance requirements harden.
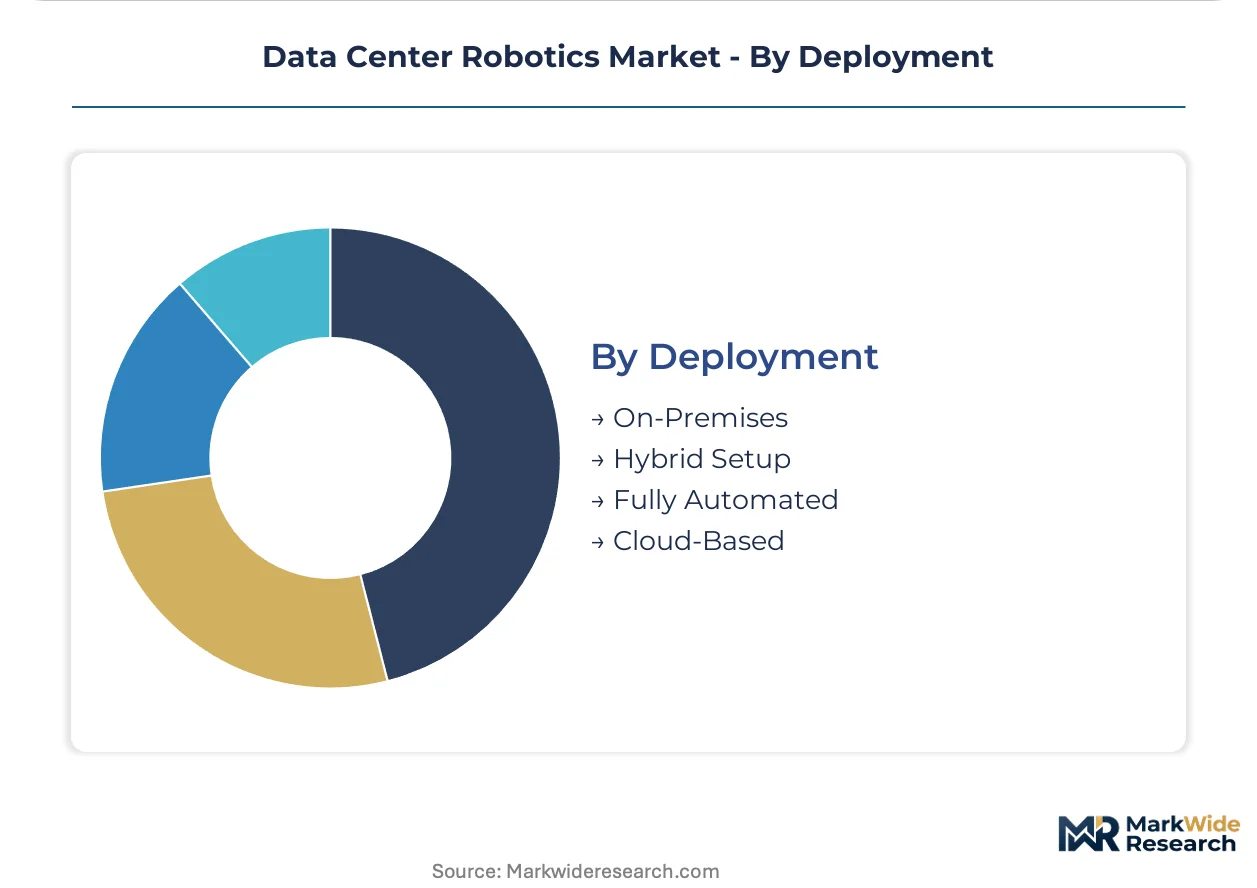
Deployment:
Volume scale separates mega-campus operators pursuing full automation from regional facilities requiring human-in-the-loop architectures.
- On-Premises:Locally hosted robot management systems maintain operational continuity during external network disruptions. Financial services Enterprises in the United States favor on-premises deployments to satisfy SEC audit trail requirements for autonomous decision logs. On-Premises leads volumes today; Fully Automated is gaining share fastest.
- Fully Automated:Human-out-of-the-loop operations across server rack transport, thermal inspection, and predictive maintenance workflows. Chinese hyperscale operators deploy fully automated fleets across campuses exceeding one million square feet.
- Hybrid Setup:Mixed human-robot workflows with supervisory control for high-consequence decisions. German facilities adopt hybrid models to satisfy EU AI Act human oversight mandates for high-risk autonomous systems.
- Cloud-Based:Centralized fleet management with over-the-air software updates and cross-facility performance analytics. Smaller regional Data Center Operators in underserved markets favor cloud-based deployment to minimize on-site engineering headcount.
On-Premises deployments anchor current infrastructure; Fully Automated configurations capture expanding share as hyperscale operators densify campus concentrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ashburn-Dulles corridor hyperscale campuses in Virginia anchor procurement volumes for autonomous mobile robot fleets serving thermal inspection and server rack transport workloads.
United States
Cloud Service Provider capex cycles in Northern Virginia and Dallas-Fort Worth drive concentrated demand for LiDAR-SLAM navigation platforms. OSHA guidelines for industrial robot safety extend procurement cycles by eight to fourteen months for collaborative deployments. Phoenix and Atlanta metro areas host expanding mega-scale campuses where operators minimize human entry into secure white spaces through fully automated fleet configurations.
Germany
Frankfurt Rhine-Main data center clusters prioritize EU AI Act compliance investments ahead of mandatory conformity assessments for high-risk autonomous systems. The country's national regulator mandates algorithmic transparency requirements for thermal inspection decisions. Bavaria and Hesse facility operators front-load certification spending to avoid deployment freezes during backlog periods.
China
Beijing-Tianjin-Hebei and Yangtze River Delta campus concentrations exceed one million square feet, enabling human-out-of-the-loop operations at scale. MIIT guidelines shape domestic safety standards for mobile robotic platforms in critical infrastructure environments. Shenzhen and Hangzhou hyperscale operators deploy captive supply chains for drive unit and navigation module production.
Japan
Tokyo and Osaka metro data center operators balance space constraints against precision requirements for cable management automation. METI guidelines for autonomous systems in industrial settings influence procurement specifications for collaborative robot deployments. Nagoya industrial corridor suppliers concentrate on mechatronics integration engineering for regional facility retrofits.
India
Maharashtra and Karnataka data center operators represent underserved demand for edge-optimized robotic configurations outside mega-scale campus templates. The country's national IT regulator influences data localization requirements that shape on-premises fleet management system deployments. Mumbai and Bangalore facility managers prioritize hybrid human-robot workflows with supervisory control architectures.
Data Center Robotics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent warehouse automation spaces with transferable navigation stacks. The vendor base stratifies around full-stack fleet management contracts versus multi-source subsystem procurement. Three archetypes dominate: integrated platform vendors bundling hardware-software-maintenance, captive in-house producers serving affiliated cloud operations, and specialized component suppliers for LiDAR and drive units. Competitive moves concentrate on strategic partnerships for certification acceleration and geographic expansion into underserved regional markets.
Among Asia-Pacific-based platform vendors, Geek+ exemplifies the integrated archetype with software-anchored deployments across hyperscale facilities. Amazon Robotics occupies a position representing captive supply chain control for fulfillment-adjacent server farm operations. Hitachi Vantara sits within the predictive maintenance specialization tier, extending robot fleet uptime through algorithmic service offerings.
| Leading Market Players |
|---|
| GreyOrange |
| Seegrid |
| Amazon Robotics |
| Hitachi Vantara |
| Vertiv |
| Geek+ |
| OTTO Motors |
| Lenovo |
| Locus Robotics |
| Others |
Cost & Logistics Intelligence
EU AI Act conformity assessments gate qualified supply pools and premium-tier pricing access for high-risk autonomous systems entering European data centers. Cloud Service Providers in Germany and France front-load certification investments to secure deployment slots before backlog periods compress vendor availability.
Pricing Analysis
Input-cost pass-through from lithium-ion battery cells and LiDAR sensor modules shapes vendor pricing structures across fleet management contracts. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified platforms from uncertified alternatives and basic AGV configurations. Pricing pressure stems from hyperscale buyers consolidating around full-stack contracts that bundle hardware, software, and predictive maintenance. Regional Data Center Operators in India and Brazil exhibit highest price sensitivity due to constrained capex cycles, while Cloud Service Providers in Northern Virginia prioritize certification grade over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale buyers mandate multi-supplier qualification for drive units, navigation modules, and battery management systems to mitigate vendor lock-in risk. Manufacturing concentration centers on China for lithium-ion cells, South Korea for advanced LiDAR arrays, and Japan for precision mechatronics components. Raw material dependencies span rare earth elements for permanent magnet motors, high-purity silicon for sensor chipsets, and nickel-cobalt cathode formulations. Tariff exposure on East Asian battery imports represents the dominant structural risk. Distribution runs through direct vendor relationships with Cloud Service Providers and regional system integrators serving mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center robotics functions as a stable compounder anchored by hyperscale capex cycles that refresh fleet infrastructure on predictable replacement timelines.
For Market Incumbents: To counter emerging platform vendors from adjacent warehouse automation spaces, deepen predictive maintenance algorithm differentiation and secure ISO 10218 certification acceleration partnerships with North American testing laboratories. Capacity addition in India addresses underserved edge facility demand before regional competitors establish reference deployments. For New Entrants and Emerging Players: Regional system integrators represent the most accessible channel partner type for penetrating Brazil and India's mid-scale Data Center Operator segment with cloud-based fleet management offerings. White-space concentration in edge computing retrofits of legacy central offices offers fastest path to reference accounts. Target Telecom Companies with cable management-focused Robotic Arm configurations that navigate space-constrained aisle environments. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized sensor fusion startups with thermal imaging expertise and established METI compliance pathways for Japanese market entry. Long-term viability framing centers on algorithmic transparency capabilities that satisfy evolving EU AI Act documentation requirements. The signal to watch is OSHA guideline expansion timing for United States human-robot collaboration mandates that would trigger fleet upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Acceleration | Early conformity assessment completion locks out uncertified competitors from German and French hyperscale procurement. |
| Predictive Maintenance Platform Launch | Machine learning-enabled uptime extension commands premium pricing in mission-critical infrastructure environments. |
| Edge Facility Geographic Expansion | India and Brazil configurations optimized for sub-mega-scale campuses capture underserved regional demand. |
| LiDAR-SLAM Navigation Integration | Sub-millimeter positioning accuracy eliminates fixed conveyor retrofit costs in legacy facility upgrades. |
| Multi-Source Subsystem Partnership | Flexible procurement architectures reduce vendor lock-in risk for mid-scale Data Center Operators. |
Research Approach
Bottom-up Cloud Service Provider capex modeling reconciled against top-down robotic subsystem production tracking forms the analytical core of this study. Primary interviews with data center operations directors, fleet procurement managers, robotics integration engineers, and regulatory compliance officers combined with secondary validation from SEC hyperscaler filings, EU AI Act implementation guidance, and OSHA technical documentation. Trade data from customs records and component shipment manifests anchored supply-side triangulation against demand signals from facility expansion announcements.
Historical trendline analysis of AMR deployment velocities across United States, German, and Chinese hyperscale campuses established baseline growth patterns. The projection framework spans product type segmentation, technology maturity tiers, end-user concentration levels, and deployment architecture complexity. CAGRs derived from facility densification trajectories, replacement cycle compression, and regulatory-driven upgrade mandates. Industry-specific inputs include LiDAR cost decline curves, lithium-ion supply expansion timelines, and certification backlog duration estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement consistency and OSHA guideline finalization timing. Deviation in lithium-ion supply chain disruption severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
APAC Service Robots Market