
 Autonomous Navigation Robots Market | 2026-2036
Autonomous Navigation Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Navigation Robots Market Insights
China's manufacturing corridor is reshaping component availability and cost structures for navigation hardware. ABB leverages its industrial automation heritage to dominate heavy-load autonomous transport in European automotive plants. Northrop Grumman Corporation anchors defense-grade navigation systems with hardened SLAM algorithms for GPS-denied environments. BAE Systems specializes in maritime and aerospace autonomy stacks that sustain long-range mission profiles without external positioning.
Autonomous navigation robots integrate perception sensors, path-planning algorithms, and actuation systems to execute locomotion without human teleoperation in dynamic environments. These systems typically fuse LiDAR point clouds with inertial measurement units to achieve centimeter-level localization accuracy for safety-critical industrial tasks. Industrial robots currently occupy the largest revenue pool across product types, while delivery robots represent the fastest-expanding segment as last-mile logistics operators seek to reduce per-package fulfillment costs. SLAM technology leads the technology dimension for indoor applications, though computer vision is displacing legacy sensor fusion in outdoor security and agricultural scouting deployments.
The FAA governs commercial drone navigation in US airspace, while the EU AI Act imposes conformity requirements on autonomous decision-making systems deployed in European logistics networks. FDA oversight extends to healthcare robots performing medication delivery or patient transport within hospital corridors, creating dual compliance burdens for vendors targeting clinical settings. Stakeholders must monitor how divergent safety certification timelines across regulators affect product roadmaps and geographic launch sequencing.
Market Dynamics
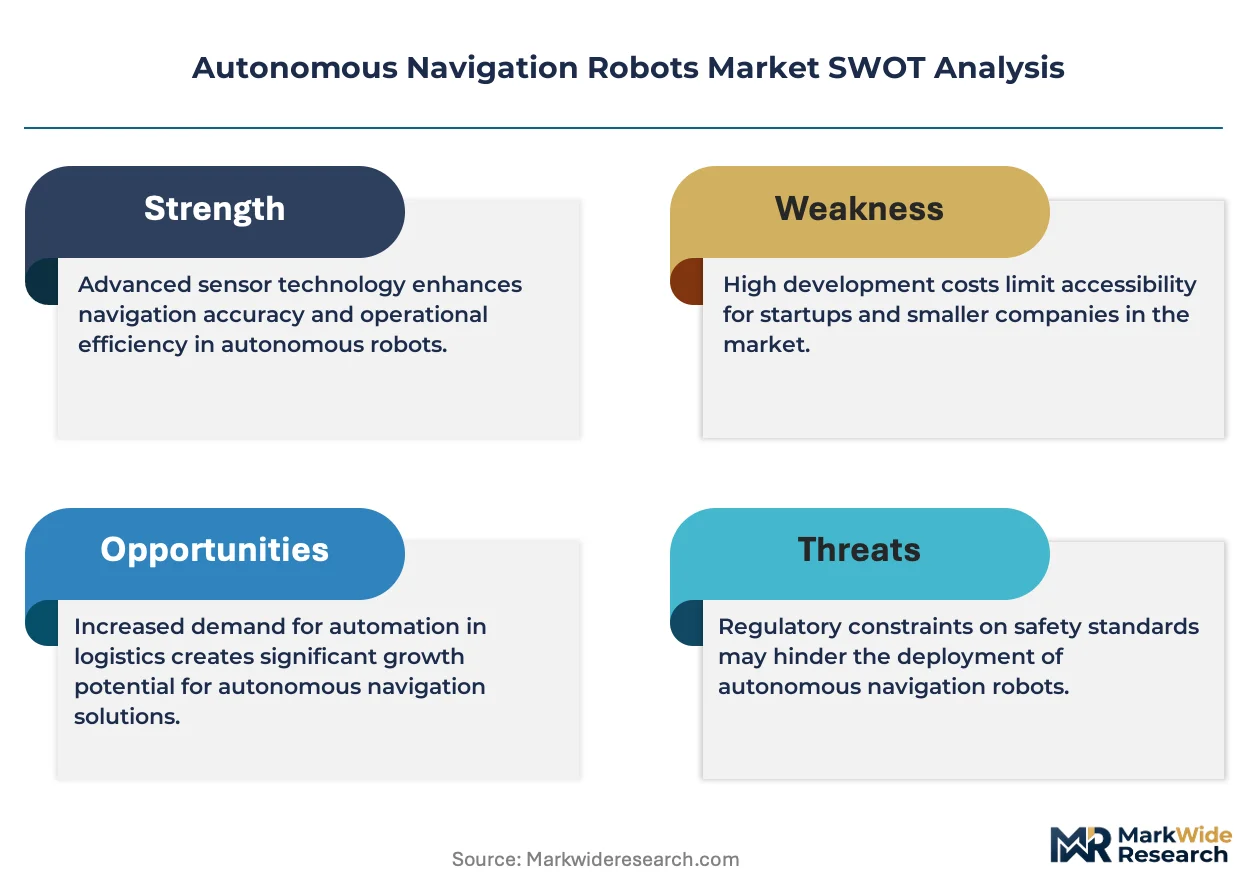
The EU AI Act is forcing hardware vendors to redesign sensor fusion architectures for conformity assessment before European logistics deployments can proceed. This regulatory pressure cascades through firmware development timelines and third-party certification budgets.
Growth Catalysts
- EU AI Act Conformity Requirements:Logistics operators in Germany must validate autonomous decision-making systems before fleet scaling, creating sustained demand for certified navigation stacks.
- LiDAR Cost Compression:China's manufacturing corridor has reduced solid-state sensor prices, enabling mid-size warehouse operators to justify AMR procurement.
- FDA Hospital Automation:Healthcare facilities seek medication delivery robots that meet device guidance for patient corridor navigation.
Market Restraints
- SLAM Algorithm Supply Concentration:Defense-grade navigation software development clusters in GPS-denied simulation facilities with limited vendor access.
- Inertial Measurement Unit Input Volatility:MEMS gyroscope foundry capacity constraints in Taiwan affect component lead times for industrial robot OEMs.
- Computer Vision Substitution Threat:Camera-based localization is displacing multi-sensor fusion in outdoor security patrol applications.
Strategic Opportunities
- Indian Pharmaceutical Logistics:CDSCO-regulated cold chain facilities lack autonomous transport infrastructure for temperature-sensitive material handling.
- Vision-LiDAR Convergence:Sensor fusion architectures that combine dense depth mapping with semantic scene understanding unlock agricultural scouting deployments.
- Japan METI Automation Incentives:Subsidies for aging workforce replacement drive demand for hospital patient transport robots.
Industry Challenges
- Multi-Regulatory Certification Timelines:Vendors targeting clinical settings face overlapping FDA device requirements and EU AI Act conformity assessments.
- Legacy Warehouse Management System Integration:Proprietary WMS protocols require custom middleware development for fleet orchestration.
- SLAM Specialist Talent Scarcity:Robotics firms compete for engineers with simultaneous localization and mapping expertise across indoor and outdoor domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Navigation Robots Market |
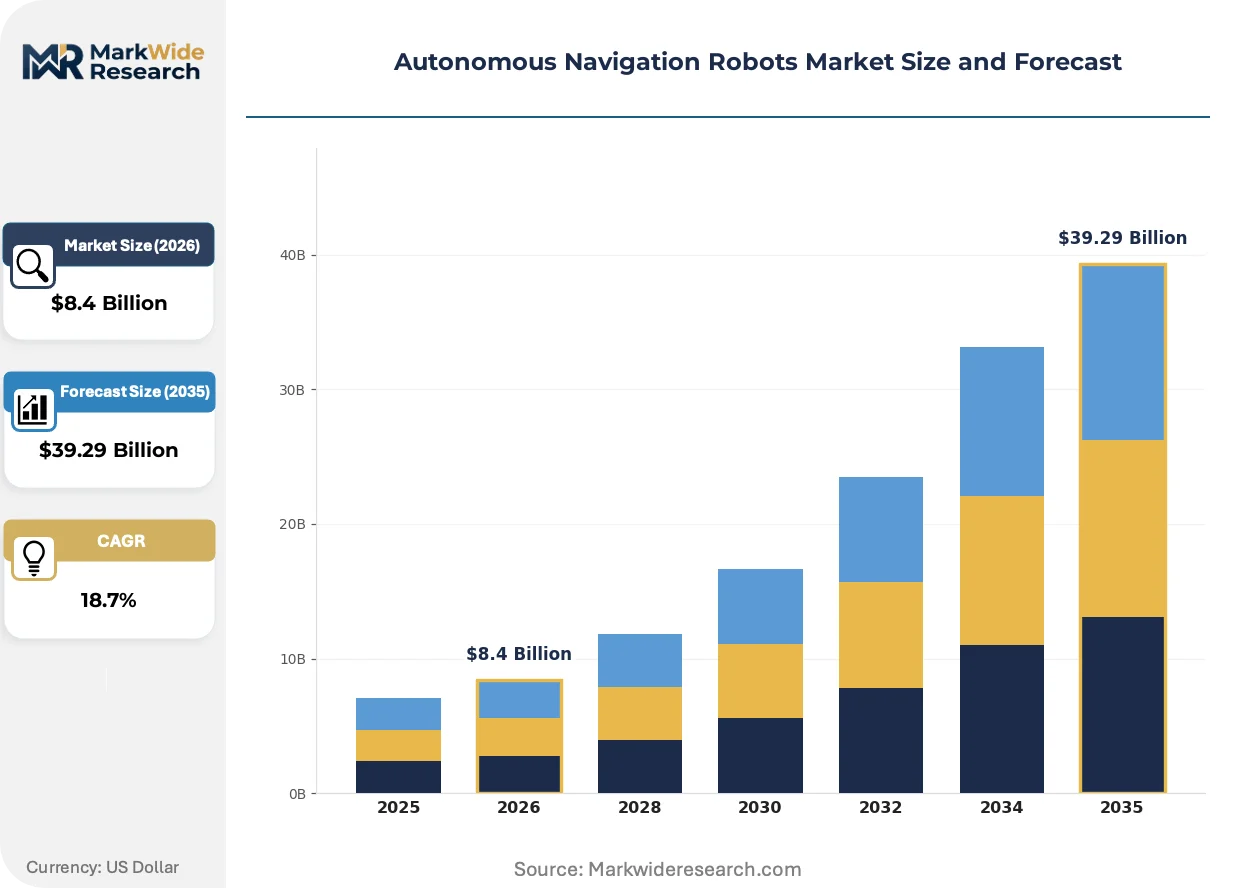
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Delivery Robots, Inspection Robots Technology: LiDAR, Computer Vision, SLAM, GPS Application: Warehouse Management, Agriculture, Security, Healthcare End User: Manufacturing, Retail, Logistics, Hospitals |
| Companies Covered | ABB, Safran, L3Harris Technologies, Moog, Northrop Grumman Corporation, BAE Systems, Lockheed Martin Corporation, Elbit Systems, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Navigation Robots Market Trends and Innovations
Navigation architectures are hybridizing sensor modalities to reduce unit costs while maintaining safety integrity levels. Three developments are compressing competitive positioning across hardware and software layers.
Visual-inertial odometry is hybridizing dense geometric mapping with semantic understanding for dynamic obstacle classification. Automotive suppliers in Stuttgart are piloting these stacks for just-in-time parts delivery. The convergence is compressing the price-performance gap between premium LiDAR systems and camera-dominant alternatives.
The EU AI Act's risk classification framework is mandating human oversight interfaces for autonomous decision-making in logistics networks. European third-party logistics providers must demonstrate conformity before scaling fleet deployments beyond pilot phases. German automotive plants are front-loading validation budgets to secure first-mover clearance.
Hospital procurement committees are unbundling robot hardware from software service agreements, demanding separate pricing for navigation updates and fleet management. This purchasing pattern is displacing traditional capital expenditure models in US healthcare systems. The shift is most visible in Texas and Florida medical center networks seeking operational flexibility.
Autonomous Navigation Robots Market Segmentation
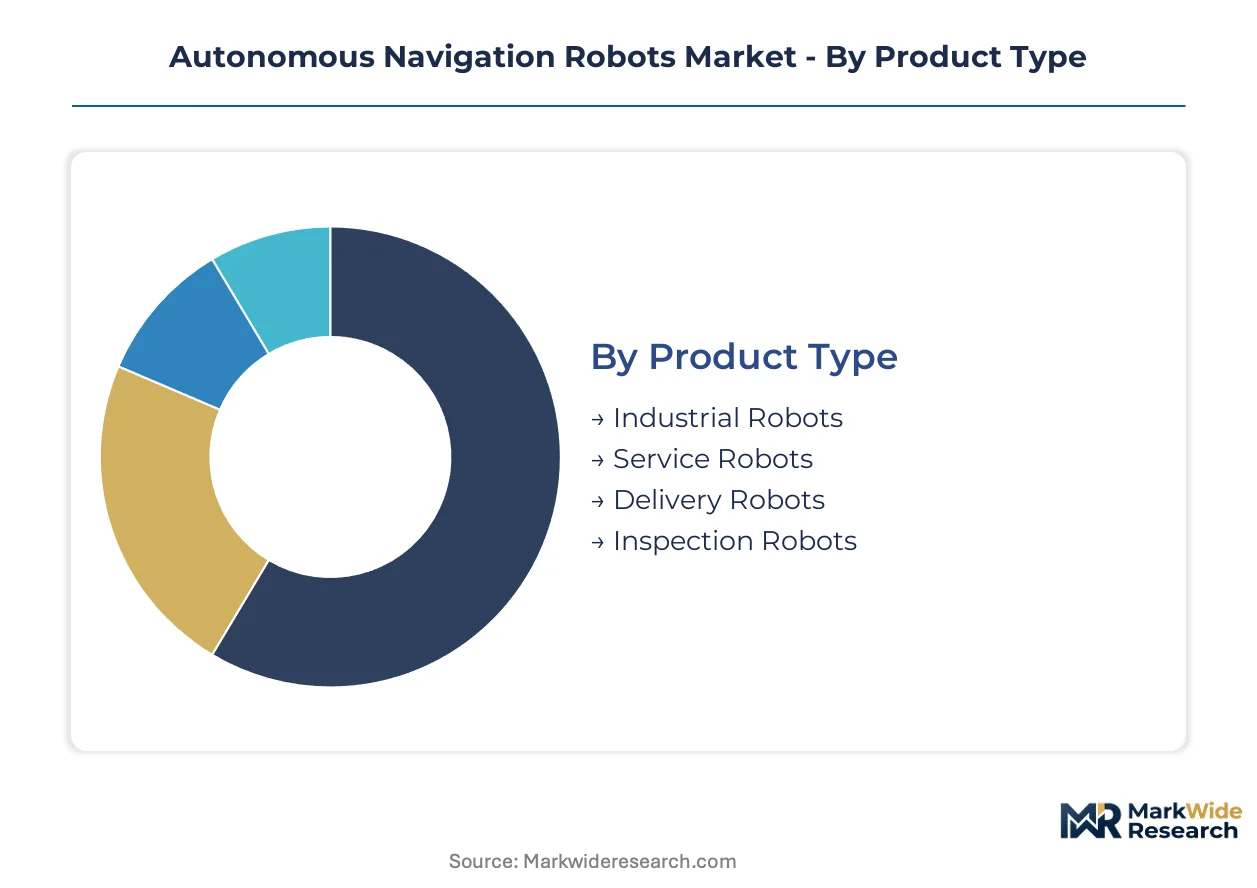
Autonomous navigation robots serve radically different operational contexts, from sterile hospital corridors to GPS-denied agricultural fields. Segmentation reveals how sensor fusion requirements, regulatory burdens, and procurement patterns diverge across deployment environments. Vendors must align hardware specifications and certification strategies to the precise constraints of each vertical.
Product Type:
Use-case spectrum spans heavy-load manufacturing floors to lightweight last-mile sidewalks, with payload capacity and safety integrity levels defining procurement priorities.
- Industrial Robots:These systems integrate multi-ton payload capacity with SIL-2 safety architectures for automotive assembly lines and heavy manufacturing. Demand concentrates in Germany's automotive supplier networks, where just-in-time parts delivery requires centimeter-level repeatability under tight cycle-time constraints.
- Delivery Robots:Lightweight sidewalk-class units carry 15-25 kg payloads across urban last-mile networks using camera-dominant perception stacks. Logistics operators in Texas and Florida medical center networks are unbundling hardware from software service agreements to secure operational flexibility for fleet scaling.
- Service Robots:Human-interactive platforms perform concierge, guidance, and cleaning functions in commercial spaces. Japanese hospital procurement committees prioritize patient transport variants eligible for METI automation subsidies.
- Inspection Robots:Ruggedized platforms with extended battery endurance patrol energy infrastructure and hazardous environments. BAE Systems anchors maritime and aerospace autonomy stacks for long-range mission profiles without external positioning.
Established volume favors Industrial Robots; emerging adoption favors Delivery Robots.
Technology:
Cost tier stratification separates premium multi-sensor fusion from emerging camera-dominant alternatives, with regulatory compliance driving architecture selection.
- SLAM:Simultaneous localization and mapping algorithms fuse LiDAR point clouds with inertial measurement units to achieve centimeter-level accuracy in GPS-denied indoor environments. German automotive plants front-load validation budgets to secure EU AI Act conformity for fleet deployments.
- Computer Vision:Deep learning-based localization using monocular or stereo camera arrays enables outdoor security patrol at substantially lower unit cost. Agricultural scouting deployments in China's manufacturing corridor are accelerating camera-dominant substitution for legacy multi-sensor stacks.
- LiDAR:Solid-state and mechanical spinning sensors provide dense 3D point clouds for obstacle detection and mapping. China's component manufacturing has compressed sensor prices, enabling mid-size warehouse operators to justify AMR procurement.
- GPS:Satellite-based positioning supports outdoor fleet coordination and wide-area route optimization. Defense-grade navigation systems from Northrop Grumman Corporation deploy hardened SLAM-GPS fusion for contested electromagnetic environments.
SLAM commands premium positioning in indoor logistics; Computer Vision is gaining share fastest in outdoor and agricultural applications.
Application:
Customer type diversity ranges from FDA-regulated healthcare systems to fragmented agricultural cooperatives, with compliance burden and procurement sophistication varying sharply.
- Warehouse Management:Autonomous mobile robots orchestrate put-away, picking, and replenishment in distribution centers. North American warehouse operators are expanding fleet deployments as labor costs rise and legacy WMS integration challenges persist.
- Healthcare:Medication delivery and patient transport robots must satisfy FDA device guidance for corridor navigation and emergency stop protocols. Texas and Florida medical center networks are driving unbundling of hardware from software service agreements.
- Agriculture:Vision-LiDAR convergence enables crop scouting, yield estimation, and precision spraying across variable terrain. Stuttgart automotive suppliers are piloting hybrid stacks that transfer to agricultural OEMs.
- Security:Patrol robots with thermal imaging and acoustic anomaly detection secure perimeters and critical infrastructure. Camera-based localization is displacing multi-sensor fusion in outdoor deployments where cost sensitivity dominates.
Warehouse Management anchors current revenue; Healthcare represents the steepest expansion trajectory given regulatory tailwinds and labor substitution pressures.
End User:
Geography and maturity dispersion concentrates advanced deployments in German automotive and North American logistics, with emerging demand in Indian pharmaceutical cold chain.
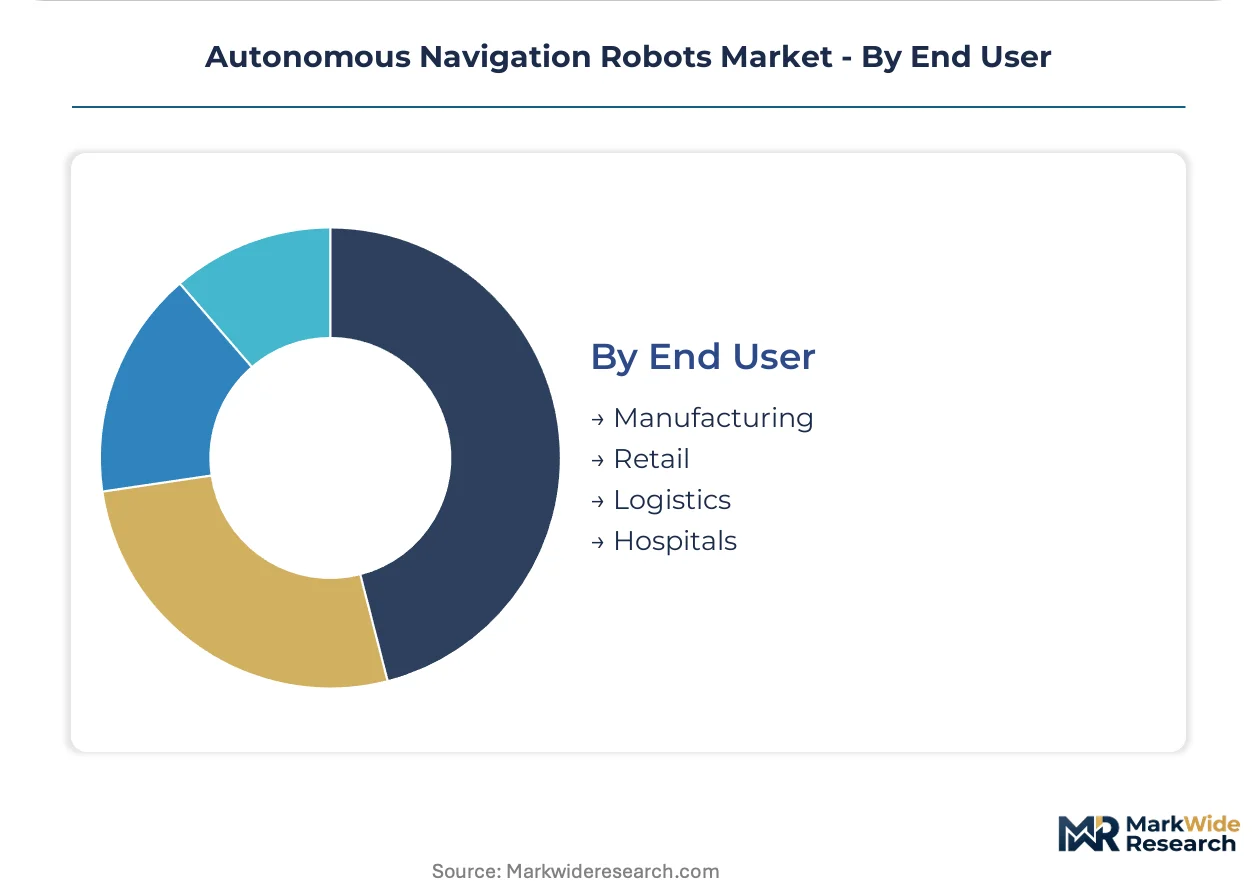
- Manufacturing:Automotive and electronics assembly lines demand heavy-load autonomous transport with millimeter positioning accuracy. ABB leverages industrial automation heritage to dominate European automotive plant deployments.
- Logistics:Third-party logistics providers in Germany pilot large-scale AMR integration under EU AI Act conformity requirements. Fleet orchestration challenges persist due to proprietary WMS protocol fragmentation.
- Retail:Inventory counting and customer assistance robots operate in store environments with high human traffic density. Last-mile fulfillment cost reduction drives interest in micro-fulfillment center automation.
- Hospitals:Patient transport and medication delivery systems face dual FDA device and EU AI Act compliance burdens. METI subsidies in Japan accelerate aging workforce replacement investments.
Manufacturing holds established volume concentration; Hospitals exhibit the fastest emerging adoption curve driven by regulatory clarity and subsidy programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in China's eastern provinces dominate navigation sensor supply, while demand-side deployment concentrates in German automotive corridors and North American logistics hubs. This geographic split shapes procurement timelines and certification sequencing across vendor portfolios.
United States
Warehouse operators in Texas and Florida medical center networks are expanding AMR fleets as labor costs escalate. The FDA governs commercial healthcare robot navigation through device guidance for patient corridor operations. Austin and Dallas logistics clusters drive unbundled procurement of hardware from software service agreements.
Germany
Automotive suppliers and third-party logistics providers in Stuttgart are piloting large-scale AMR integration for just-in-time parts delivery. The EU AI Act mandates conformity assessment for autonomous decision-making systems before fleet scaling beyond pilot phases. Bavarian automotive plants front-load validation budgets to secure first-mover regulatory clearance.
China
Manufacturing corridors in the Yangtze River Delta are reshaping LiDAR component availability and cost structures for navigation hardware. MIIT standards and GB certification requirements govern industrial robot deployment in smart factory initiatives. Shenzhen and Shanghai sensor foundries compress solid-state LiDAR prices for mid-size warehouse operators globally.
Japan
Hospital procurement committees prioritize patient transport robots eligible for METI automation subsidies addressing aging workforce replacement. The PMDA oversees medical device navigation systems performing medication delivery in clinical settings. Nagoya and Osaka medical center networks accelerate fleet procurement under national automation incentive programs.
India
CDSCO-regulated pharmaceutical cold chain facilities lack autonomous transport infrastructure for temperature-sensitive material handling. The country's national pharmaceutical regulator imposes distribution integrity requirements that autonomous systems must satisfy. Maharashtra and Gujarat logistics clusters represent emerging demand centers for certified navigation stack deployment.
Autonomous Navigation Robots Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor fusion and localization algorithms. The vendor base stratifies across defense-grade navigation stacks, industrial automation heritage players, and emerging pure-play AMR developers. Three archetypes dominate: diversified industrial conglomerates with automation divisions, aerospace-defense contractors with hardened SLAM expertise, and venture-backed logistics robotics specialists. Competitive moves concentrate on strategic partnerships for WMS middleware integration and sensor cost compression through Asian supply chain relationships.
Within the defense-grade navigation tier, Northrop Grumman Corporation and BAE Systems occupy positions anchoring hardened SLAM algorithms for GPS-denied environments. ABB represents the industrial automation heritage archetype, leveraging century-long manufacturing system integration expertise. These three entities exemplify how technical specialization in contested electromagnetic environments or heavy-load manufacturing floors creates defensible positioning against generalized robotics entrants.
| Leading Market Players |
|---|
| ABB |
| Safran |
| L3Harris Technologies |
| Moog |
| Northrop Grumman Corporation |
| BAE Systems |
| Lockheed Martin Corporation |
| Elbit Systems |
| General Dynamics Corporation |
| Others |
Pricing and Supply Chain Analysis
China's Yangtze River Delta sensor foundries concentrate solid-state LiDAR production, anchoring margin pools downstream with German automotive OEMs and North American warehouse operators who command premium pricing for certified navigation stacks. This upstream concentration forces mid-tier buyers into extended payment cycles while defense-grade vendors extract royalty premiums for GPS-denied SLAM algorithms.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, separating premium conformity-assessed stacks from standard firmware lacking formal validation. Three-tier pricing stratification across certified-premium, standard-validated, and economy-unvalidated levels reflects FDA device guidance tiers for healthcare applications. Pricing pressure stems from camera-dominant localization displacing multi-sensor fusion in outdoor security patrols. Hospital procurement committees exhibit lowest price sensitivity given dual compliance burdens, while mid-size warehouse operators face acute cost compression from legacy WMS integration requirements.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements as Taiwanese MEMS gyroscope foundries tighten component allocation for industrial robot OEMs. China's sensor manufacturing, South Korea's semiconductor packaging, and Germany's precision optics collectively anchor upstream supply. Solid-state LiDAR emitters, inertial measurement units, and edge-compute processors constitute critical input dependencies. Single-source vulnerability concentrates in GPS-denied SLAM algorithm development clustered within defense simulation facilities. Distribution runs through direct OEM relationships for heavy-load industrial systems and third-party logistics integrators for warehouse AMR fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SLAM engineering talent scarcity constrains fleet scaling timelines, with German automotive plants and US hospital networks competing for identical algorithm validation expertise. This capability gap rewards first-movers who secure conformity clearance ahead of regulatory deadline clustering.
For Market Incumbents: Build certification moats by front-loading EU AI Act validation budgets before German logistics operators lock in long-term fleet contracts. Anchor defensive positioning through backward integration into solid-state LiDAR supply partnerships with Yangtze River Delta foundries. Camera-dominant substitution in outdoor security threatens premium sensor fusion margins; counter by embedding semantic scene understanding into hybrid vision-LiDAR architectures for agricultural scouting defensibility.
For New Entrants and Emerging Players: India's CDSCO-regulated pharmaceutical cold chain represents the most penetrable geographic underpenetration, with Maharashtra and Gujarat logistics clusters lacking temperature-sensitive autonomous transport infrastructure. Target hospital patient transport in Texas and Florida medical networks where unbundled procurement patterns favor software-native entrants over hardware-legacy vendors. Pursue METI subsidy-eligible deployments in Japan's Nagoya and Osaka medical centers as a regulatory-cleared beachhead.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed AMR developers who have exhausted Series C runway without achieving EU AI Act conformity. Five-to-ten year viability hinges on regulatory clearance velocity rather than raw technical performance. Prioritize acquisition targets with validated SLAM stacks in FDA-reviewed healthcare corridors. Monitor German automotive plant fleet deployment announcements as inflection indicators for conformity-assessed navigation stack demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Investment | German automotive OEMs secure first-mover clearance before fleet scaling mandates tighten. |
| Vision-LiDAR Sensor Fusion Development | Hybrid architectures unlock agricultural scouting deployments beyond warehouse automation saturation. |
| WMS Middleware Platform Acquisition | Proprietary protocol integration capabilities determine fleet orchestration contract winners. |
| Defense-Grade SLAM Licensing | GPS-denied algorithm royalties extract premiums from maritime and aerospace autonomy stacks. |
| Indian Cold Chain Infrastructure Partnership | CDSCO-regulated pharmaceutical distribution lacks certified navigation stack deployment. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with robotics engineering directors, hospital procurement committee members, third-party logistics fleet managers, and EU notified body assessors; and secondary validation through FDA 510(k) filings, EU AI Act implementing act drafts, MIIT smart factory disclosure databases, and customs records for navigation sensor trade flows. Bottom-up unit economics triangulated against top-down sector expenditure estimates across manufacturing, logistics, and healthcare verticals.
Forecast inputs incorporated product type segmentation across industrial, delivery, service, and inspection robot categories; technology stratification spanning SLAM, computer vision, LiDAR, and GPS fusion; and application clustering by warehouse management, healthcare, agriculture, and security end-uses. CAGRs derived from regression against historical fleet deployment trajectories, adjusted for regulatory timeline acceleration in European logistics and FDA device guidance clarity in US hospital corridors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-backed AMR pure-plays or defense contractor commercialization units would shift outcomes beyond modeled ranges. Macroeconomic contraction in German automotive production, abrupt MEMS foundry allocation restrictions, or EU AI Act enforcement variance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Germany Cloud Robotics Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Airport Robots Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Data Center Robotics Market