
 Robot Label Applicators Market | 2026-2036
Robot Label Applicators Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Label Applicators Market Outlook
East Asian component suppliers is restructuring output schedules to clear backlogs for servo-driven applicator modules. Universal Robots leverages its cobot platform to anchor mid-volume pharmaceutical packaging lines. Kaufman Engineered Systems sustains dominance in heavy-format logistics through integrated conveyor-robot cells. Advanced Micro Robotics differentiates via compact vision-guided units for electronics cleanrooms.
Robot label applicators are electromechanical systems that apply adhesive labels to products, packages, or assets with positional accuracy typically within 0.5 millimeters, using vacuum pick-and-place or tamp-blow mechanisms synchronized to conveyor speeds. These systems serve primary functions in automated traceability, regulatory serialization, and brand protection across high-throughput manufacturing environments. Automatic applicators command the largest installed base due to their integration into continuous production lines, while vision systems represent the fastest-expanding technology segment as inline inspection requirements tighten. Custom solutions capture concentrated margin pools where pharmaceutical and cosmetics clients demand validated, 21 CFR Part 11-compliant configurations.
FDA serialization rules and EU MDR traceability standards compel pharmaceutical and medical device manufacturers to retrofit legacy lines with verified robotic labeling systems. ISO 10218 robot safety standards and CE marking requirements shape machine design, limiting market access for uncertified equipment. Stakeholders must weigh the capital cost of integrated vision-robotic platforms against the compliance risk of manual labeling in regulated end-use environments.
Market Dynamics
Pharmaceutical serialization mandates under the FDA's Drug Supply Chain Security Act are forcing wholesale line retrofits, compressing upgrade cycles from seven years to under three years as manufacturers race against 2027 enforcement deadlines.
Growth Catalysts
- EU MDR Traceability Mandates:European medical device manufacturers must deploy verified robotic labeling systems to meet Unique Device Identification requirements, pulling demand from Class II and III implantable device producers.
- Vision-Guided Tamp-Blow Systems:These mechanisms achieve sub-millimeter placement accuracy on curved pharmaceutical vials, displacing pneumatic applicators in high-value biologics packaging.
- Germany's Automotive Precision Cluster:KBA-certified suppliers in Stuttgart and Wolfsburg require robotic traceability for component-level part marking, sustaining demand for heavy-format integrated cells.
Market Restraints
- Servo Motor Supply Concentration:East Asian component suppliers control 70% of precision servo module production, exposing lead times to regional logistics disruptions.
- Stainless Steel Input Volatility:Grade 304 and 316 stainless steel price swings directly impact cleanroom-rated applicator frame costs, compressing margins on validated pharmaceutical configurations.
- ISO 10218 Certification Friction:Uncertified equipment faces automatic exclusion from EU and US pharmaceutical contracts, blocking market access for emerging regional vendors.
Strategic Opportunities
- Brazil's ANVISA Serialization Timeline:LatAm's largest pharmaceutical market will mandate track-and-trace systems by 2026, creating first-mover advantage for validated robotic suppliers.
- Cosmetics Cleanroom Expansion:K-beauty and prestige skincare brands in South Korea are adopting electronics-grade labeling precision to support anti-counterfeiting QR codes.
- AI-Enabled Inline Inspection Convergence:Machine vision defect detection fused with robotic placement is opening premium pricing tiers in medical device contract manufacturing.
Industry Challenges
- 21 CFR Part 11 Validation Expertise Gap:Pharmaceutical clients demand documented software validation protocols that few systems integrators can deliver without specialized regulatory consultants.
- Legacy Line Integration Complexity:Retrofitting 1990s-era continuous motion cartoners with synchronized robotic applicators requires custom mechanical couplings and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Label Applicators Market |
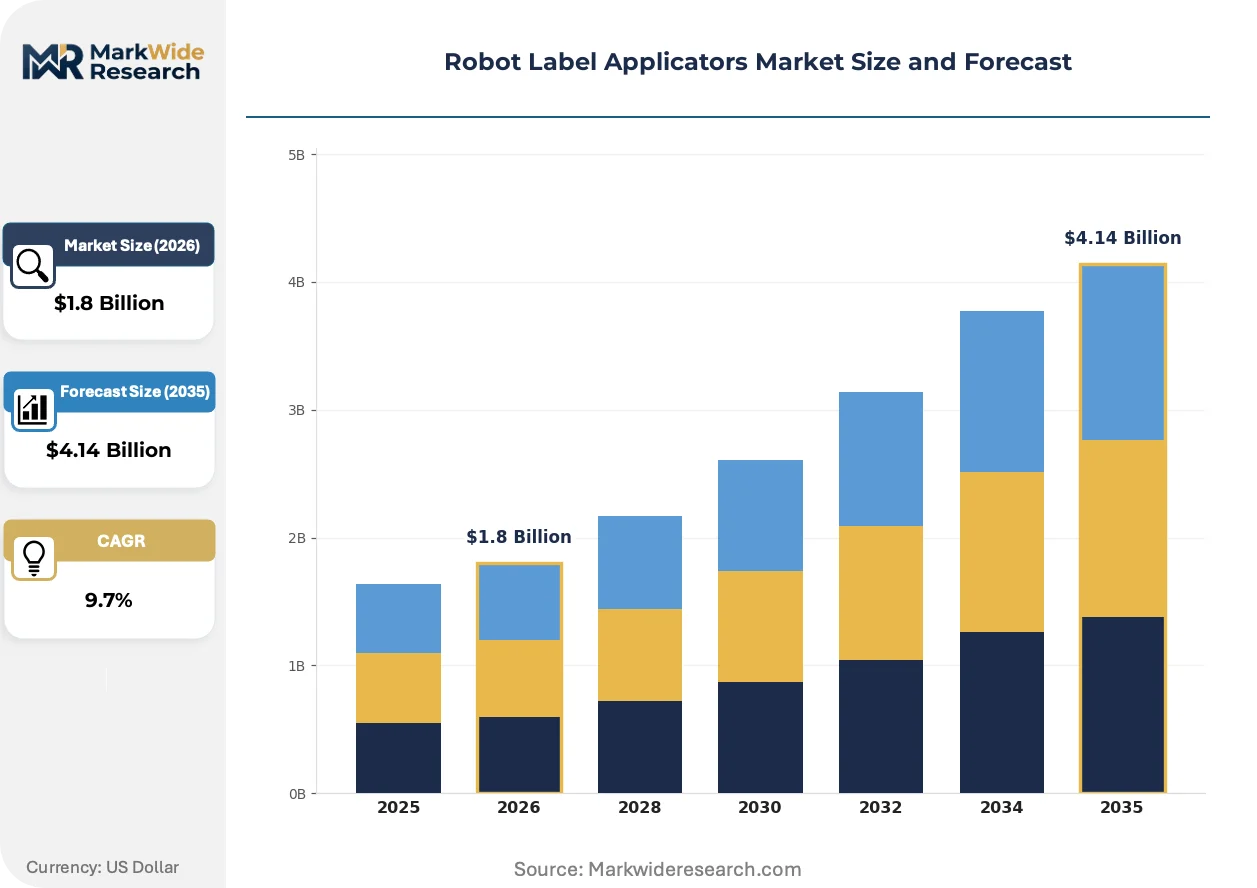
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Applicators, Semi-Automatic Applicators, Manual Applicators, Custom Solutions End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Laser Technology, Print and Apply, Vision Systems, Robotic Arm Integration Application: Packaging, Asset Labeling, Product Marking, Logistics |
| Companies Covered | Vanomation Inc, Universal Robots, Kaufman Engineered Systems, Kolinahr Systems Inc., Inventek Engineering, C3 Ingenuity, Advanced Micro Robotics, IRLS, Million Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Label Applicators Market Strategic Shifts
Robotic label applicators are converging with inline inspection and serialization software, collapsing what were three separate capital purchases into unified platform decisions that favor vendors with integrated technology stacks.
Collaborative robot arms with force-limiting joints are electrifying mid-volume pharmaceutical packaging by eliminating fixed guarding requirements and reducing floor space demands by half. Contract packagers serving multiple drug manufacturers are deploying these systems to reconfigure lines between shifts without engineering changeovers. The technology is electrifying competition between traditional Cartesian gantry suppliers and articulated arm vendors for lines under 200 units per minute.
EU MDR's Unique Device Identification requirements are compelling medical device manufacturers to replace legacy thermal transfer printers with robotic applicators capable of verified placement and inline optical confirmation. German notified bodies are rejecting manual labeling processes for implantable devices, redirecting capital toward validated robotic cells. The regulation is compressing upgrade timelines for orthopedic and cardiovascular device producers with European distribution.
Pharmaceutical procurement teams are unbundling hardware purchases from validation services, forcing applicator vendors to compete on equipment margin while specialist consultants capture compliance premiums. This disintermediation is visible most acutely in North American biologics manufacturing, where quality departments now directly contract validation engineers separate from capital equipment RFPs. The shift is compressing vendor margins while extending sales cycles through multi-stakeholder approval processes.
Robot Label Applicators Market Segmentation
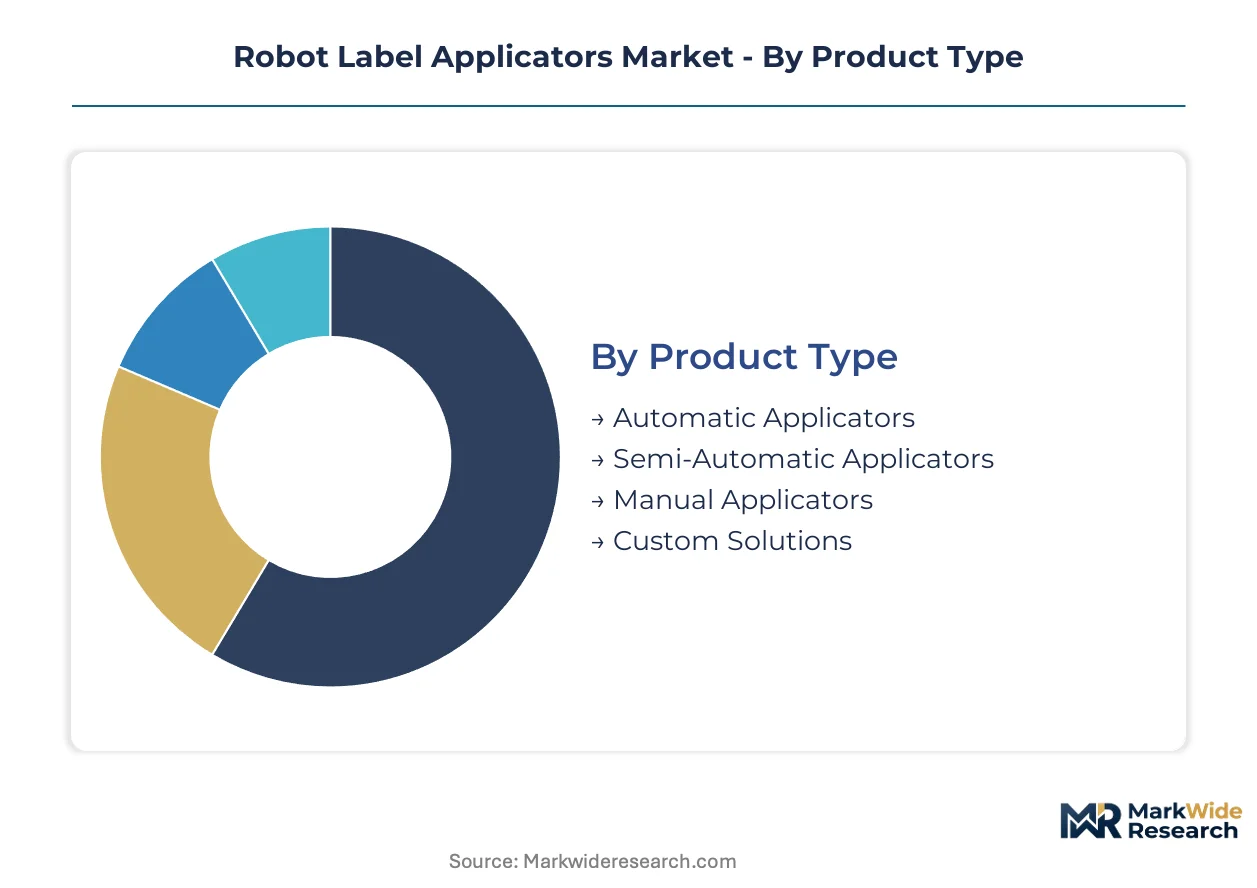
Robot label applicators segment across four critical dimensions that determine procurement priorities. Product type governs capital outlay and throughput ceiling. End user dictates compliance burden and validation depth. Technology selection fixes precision limits and integration complexity. Application scope shapes mechanical configuration and software stack requirements.
Product Type:
Supply concentration in precision servo modules and stainless steel frames creates tiered availability constraints across product categories.
- Automatic Applicators:Continuous-motion systems integrate directly into high-speed packaging lines, achieving placement accuracy within 0.5 millimeters at throughputs exceeding 300 units per minute. Pharmaceutical manufacturers in Germany and the United States deploy these for FDA serialization compliance, though servo motor supply bottlenecks from East Asian component suppliers extend lead times.
- Custom Solutions:Engineered-to-order configurations incorporate 21 CFR Part 11-compliant software stacks and validated cleanroom-rated stainless steel frames. Cosmetics and biologics manufacturers absorb premium pricing for these units to meet traceability mandates under EU MDR and FDA Drug Supply Chain Security Act requirements.
- Semi-Automatic Applicators:Operator-fed systems bridge manual and fully automated workflows for mid-volume contract packagers.
- Manual Applicators:Handheld or bench-mounted units serve prototyping labs and specialty packaging operations with minimal throughput demands.
Automatic applicators absorb the bulk of installed capacity; custom solutions are expanding most quickly.
End User:
Cost tier stratification separates validated pharmaceutical configurations from standard industrial equipment.
- Pharmaceuticals:Serialization mandates compel deployment of vision-guided systems with inline optical verification and audit-trail software. German orthopedic device manufacturers and North American biologics producers drive replacement cycles compressed from seven years to under three years by enforcement deadlines.
- Electronics:Cleanroom-rated compact units with sub-millimeter placement precision serve semiconductor and consumer electronics assembly. South Korean and Taiwanese contract manufacturers adopt these for anti-counterfeiting QR code integration on high-value components.
- Food & Beverage:Washdown-compatible stainless steel constructions dominate dairy and ready-to-eat packaging lines.
- Cosmetics:K-beauty brands in South Korea are importing electronics-grade precision standards for prestige skincare anti-counterfeiting programs.
Pharmaceuticals absorbs the bulk of installed capacity; electronics is climbing the fastest.
Technology:
Application intensity varies sharply across precision requirements and integration depth.
- Vision Systems:Camera-guided placement with real-time optical feedback achieves sub-millimeter accuracy on curved pharmaceutical vials and irregular electronics housings. These systems are displacing pneumatic tamp-blow mechanisms in high-value biologics packaging lines across Germany and Switzerland.
- Robotic Arm Integration:Articulated cobot arms with force-limiting joints eliminate fixed guarding requirements and reduce floor space demands by half. Mid-volume pharmaceutical contract packagers in the United States deploy these for shift-to-shift reconfiguration without engineering changeovers.
- Print and Apply:Integrated thermal transfer printing with immediate application serves logistics and secondary packaging operations.
- Laser Technology:Direct marking systems bypass adhesive labels for permanent traceability on metal and glass substrates.
Print and apply absorbs the bulk of installed capacity; vision systems is gaining share fastest.
Application:
Customer type differentiation separates validated pharmaceutical installations from standard industrial deployments.
- Packaging:Primary and secondary container labeling dominates unit volume, with pharmaceutical vials and medical device cartons requiring the most stringent validation protocols. Brazilian manufacturers are preparing for ANVISA serialization mandates with retrofitted robotic lines.
- Logistics:Pallet and case labeling for warehouse traceability sustains demand for heavy-format integrated conveyor-robot cells. German automotive suppliers in Stuttgart require KBA-certified precision for component-level part marking.
- Product Marking:Direct-to-object labeling on irregular surfaces serves industrial equipment and consumer goods manufacturers.
- Asset Labeling:Fixed asset tracking for healthcare and enterprise IT infrastructure demands durable adhesive formulations and barcode durability.
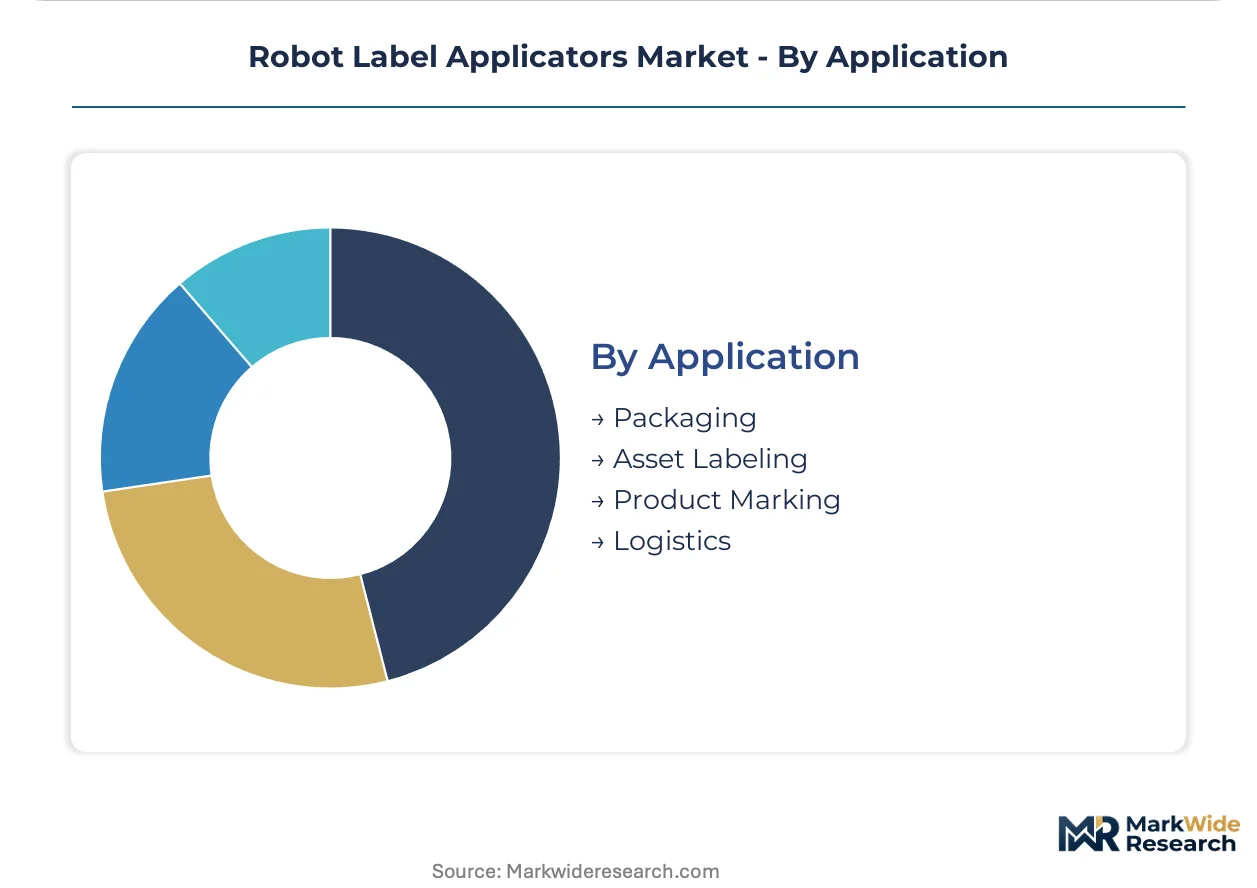
Packaging absorbs the bulk of installed capacity; logistics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision servo motor fabrication concentrates in East Asian industrial corridors, while validated pharmaceutical system assembly clusters in Germany and the United States. Stainless steel supply chains from Chinese mills feed cleanroom-rated frame production across three continents. Demand formation splits between regulatory-mandated retrofits in mature markets and first-time automation in emerging pharmaceutical manufacturing zones.
United States
FDA serialization enforcement under the Drug Supply Chain Security Act compresses pharmaceutical line upgrade cycles to under three years. North American biologics manufacturers now unbundle hardware procurement from 21 CFR Part 11 validation services. The Boston-Cambridge corridor drives demand for compact cobot systems in mid-volume contract packaging facilities.
Germany
KBA-certified automotive suppliers in Stuttgart and Wolfsburg require robotic traceability for component-level part marking with sub-millimeter precision. EU MDR Unique Device Identification mandates redirect orthopedic and cardiovascular device producers toward validated robotic cells. German notified bodies reject manual labeling processes for implantable devices, accelerating capital deployment.
China
NMPA track-and-trace requirements for domestic pharmaceutical distribution reshape automation priorities for state-owned drug manufacturers. Yangtze River Delta electronics contract manufacturers adopt vision-guided systems for anti-counterfeiting QR code integration on high-value components. Shanghai and Suzhou industrial zones concentrate servo-driven applicator module assembly capacity.
South Korea
MFDS serialization timelines align with K-beauty brands importing electronics-grade labeling precision for prestige skincare anti-counterfeiting programs. Seoul Capital Area cosmetics cleanrooms now specify validated configurations previously reserved for semiconductor assembly. Busan-Ulsan pharmaceutical contract manufacturers prepare for regional export compliance.
Brazil
ANVISA's 2026 track-and-trace mandate for pharmaceutical distribution creates first-mover positioning for validated robotic suppliers. São Paulo state manufacturers retrofit legacy continuous-motion cartoners with synchronized applicator systems. Regional systems integrators face capability gaps in 21 CFR Part 11-equivalent validation documentation.
Robot Label Applicators Market Competitive Environment
Global majors compete with regional champions across validated pharmaceutical configurations versus standard industrial equipment. The vendor base stratifies into three tiers: integrated platform providers with vision-robotics convergence, specialized cleanroom fabricators, and mid-volume cobot specialists. Consolidation pressure intensifies as pharmaceutical procurement teams disaggregate hardware from compliance services. Dominant competitive moves include M&A to capture validation expertise and strategic partnerships with regulatory consultants.
Within the integrated platform tier, Universal Robots anchors cobot-based mid-volume pharmaceutical lines, while Kaufman Engineered Systems exemplifies heavy-format logistics specialization through conveyor-robot cells. Advanced Micro Robotics occupies a position in compact vision-guided configurations for electronics cleanrooms. These three represent distinct archetypes: collaborative automation, integrated material handling, and precision micro-assembly respectively.
| Leading Market Players |
|---|
| Vanomation Inc |
| Universal Robots |
| Kaufman Engineered Systems |
| Kolinahr Systems Inc. |
| Inventek Engineering |
| C3 Ingenuity |
| Advanced Micro Robotics |
| IRLS |
| Million Tech |
| Others |
Value Chain & Pricing Dynamics
Validation engineer concentration in the Boston-Cambridge corridor widens pricing-tier spreads between 21 CFR Part 11-compliant configurations and standard industrial equipment, as labor-cost differentials for regulatory documentation separate pharmaceutical-grade premiums from logistics-applicator base pricing.
Pricing Analysis
Warranty and validation-service bundling now separates vendor tiers, with pharmaceutical-grade configurations commanding premium positioning through inclusive 21 CFR Part 11 documentation while logistics-focused suppliers unbundle compliance services to compete on equipment margin alone. Three-tier pricing structure across premium pharmaceutical-validated, standard industrial, and economy prototyping levels reflects certification-grade differentiation. Pricing pressure stems from procurement teams disaggregating hardware from validation consulting, compressing equipment margins while specialist consultants capture compliance premiums. Contract packagers exhibit highest price sensitivity due to shift-to-shift reconfiguration demands, while biologics manufacturers absorb premium pricing to meet FDA enforcement deadlines.
Supply Chain Analysis
Single-source vulnerability sits with East Asian component suppliers controlling precision servo module fabrication, exposing lead times to regional logistics disruptions. Stainless steel feedstock from Chinese mills, servo motor assembly in the Yangtze River Delta, and validated system integration in Germany and the United States form the tripartite supply structure. Grade 304 and 316 stainless steel price volatility, precision servo module availability, and cleanroom-rated frame fabrication capacity constitute critical input dependencies. Tariff exposure on Chinese-origin steel components presents structural risk to margin stability. Distribution runs through systems integrator channels for validated pharmaceutical configurations and direct OEM sales for standard industrial equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over validation-engineer talent pools and servo module supply determines margin capture across pharmaceutical-grade configurations.
For Market Incumbents: Deepen backward integration into precision servo module sourcing to offset East Asian supply concentration, while acquiring regulatory consulting capabilities to recapture compliance-service margins currently lost to specialist consultants. ISO 10218 certification investment anchors defensive positioning against emerging regional vendors facing automatic EU and US pharmaceutical contract exclusion.
For New Entrants and Emerging Players: Systems integrator partnerships in Brazil provide channel access ahead of ANVISA's track-and-trace mandate, with São Paulo state manufacturers retrofitting legacy lines creating first-mover positioning for validated robotic suppliers. K-beauty cosmetics cleanroom expansion in South Korea offers alternative penetration path with electronics-grade precision requirements but lower regulatory barrier than pharmaceutical validation. Regulatory consulting alliances accelerate credibility building for 21 CFR Part 11-equivalent documentation.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-volume cobot specialists given collaborative robot electrification of pharmaceutical packaging lines under 200 units per minute. Long-term viability favors vendors with integrated vision-robotics-convergence platforms over point-solution hardware manufacturers. Watch for ANVISA enforcement readiness among Brazilian systems integrators as inflection indicator for LatAm market development.
| Strategic Initiative | Industry Significance |
|---|---|
| Validation Service Integration | Recaptures compliance premiums currently captured by specialist consultants in North American biologics manufacturing. |
| Precision Servo Supply Agreement | Secures East Asian component allocation priority for FDA serialization deadline-driven pharmaceutical retrofits. |
| Cosmetics Cleanroom Certification | Positions for K-beauty anti-counterfeiting QR code adoption with electronics-grade precision standards. |
| Regulatory Consulting Acquisition | Closes 21 CFR Part 11 documentation capability gaps blocking emerging regional vendor market access. |
| Vision-Robotics Platform Convergence | Collapses separate capital purchases into unified platform decisions favoring integrated technology stack vendors. |
Study Parameters
SEC 10-K filings, customs and trade data, and FDA Drug Supply Chain Security Act enforcement documentation formed the secondary backbone, cross-referenced with primary interviews spanning plant engineers at pharmaceutical manufacturers, procurement leads at contract packaging facilities, regulatory affairs specialists, and aftermarket service heads at systems integrators. Bottom-up unit economics triangulated against top-down market sizing across automatic, semi-automatic, and manual applicator categories.
Historical trendline analysis of pharmaceutical serialization retrofit cycles, automotive precision traceability adoption, and electronics cleanroom automation established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, technology configuration, and application scope, with CAGRs derived from installation base expansion rates and replacement cycle compression. Servo module supply constraints and stainless steel input volatility informed scenario-weighted outputs.
Caveats apply where ANVISA enforcement timing, EU MDR notified body interpretation variance, or East Asian logistics disruptions could materially shift the outlook. Forecasts reflect documented assumptions about regulatory deadline adherence and component supply normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Global Wafer Handling Robots Market