
 Digital Industrial Scales Market | 2026-2036
Digital Industrial Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Industrial Scales Market Insights
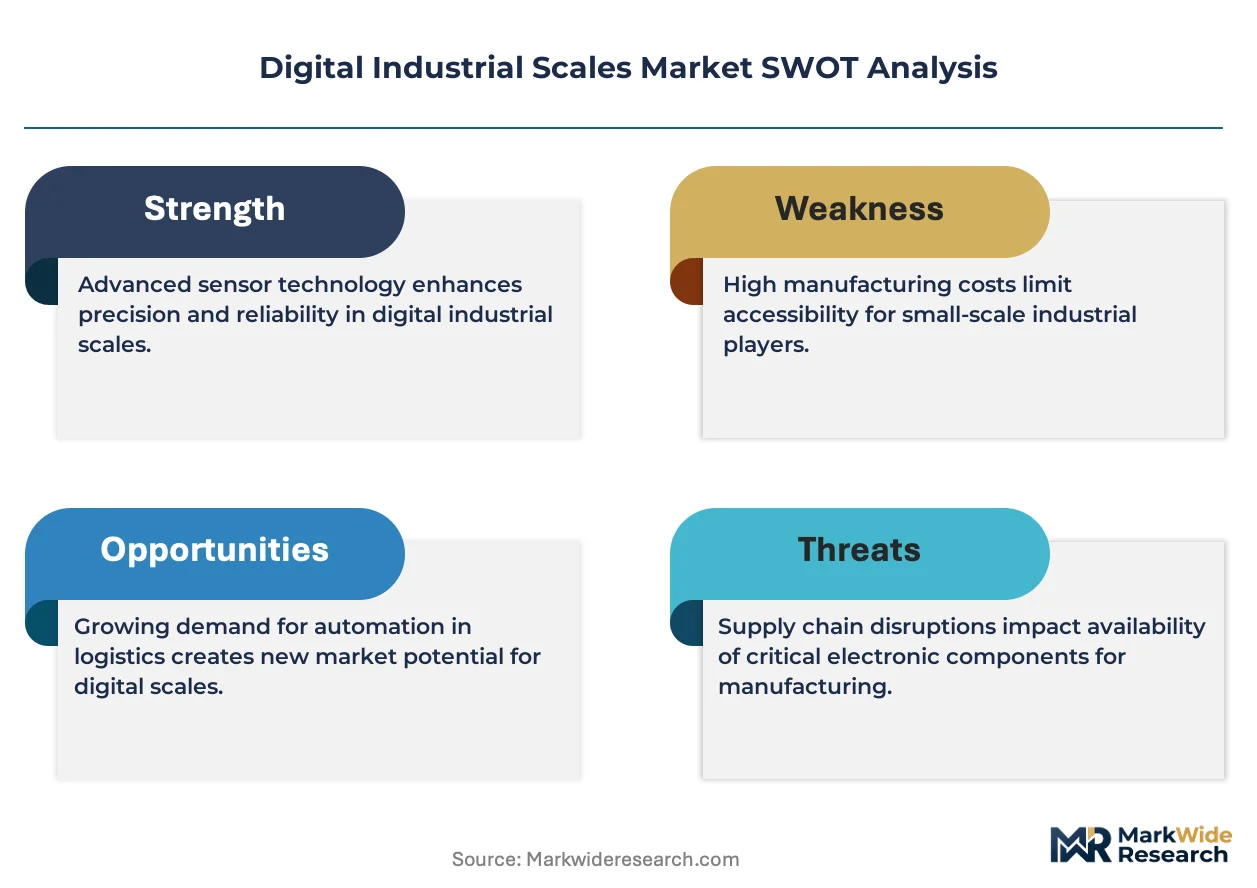
Stainless steel is repositioning aluminum in high-precision load cell housings as corrosion resistance and washdown compatibility become non-negotiable in food and chemical environments. Mettler Toledo leverages its captive strain gauge foundry to sustain margin control across premium bench and precision scale lines. Rice Lake Weighing Systems anchors its competitiveness through deep vertical integration into load cell manufacturing and domestic U.S. fabrication capacity.
Digital industrial scales are electromechanical weighing instruments that convert mechanical force into digital signals via load cells or strain gauges, typically achieving resolutions from 0.1 gram to 50,000 kilograms depending on cell configuration and analog-to-digital converter quality. Their primary purpose centers on legal-for-trade measurement, process control, and inventory verification in regulated production environments. Floor scales and crane scales dominate volume shipments into logistics and warehousing applications where palletized and bulk material throughput demands rugged, high-capacity platforms. Precision scales and electromagnetic-force-compensation units command the strongest margin pools within electronics assemblers and pharmaceutical quality control labs where microgram resolution justifies premium positioning.
NIST Handbook 44 governs legal-for-trade calibration protocols in the United States, compelling scale vendors to maintain accredited service networks or forfeit commercial weighing revenue. The EU Measuring Instruments Directive and OIML R76 standards harmonize conformity assessment across European member states, creating a single certification pathway but raising compliance costs for non-European exporters. Stakeholders must monitor how FDA Hazard Analysis and Critical Control Point rules and evolving FSMA traceability mandates reshape hygienic design requirements in food processing scale procurement.
Market Dynamics
Food processing plants are expanding precision-weighing adoption across production lines, while the EU Green Deal tightens material-efficiency standards for industrial equipment sold across member states. This dual pressure from end-use demand and regulatory compliance is compressing upgrade cycles for legacy weighing infrastructure.
Growth Catalysts
- EU Green Deal material-efficiency mandates:Industrial equipment sold across member states must meet stricter durability and recyclability standards, compelling replacement of aging scale fleets in Germany's chemical and automotive OEM base.
- FSMA traceability mandates:FDA Hazard Analysis and Critical Control Point rules are reshaping hygienic design requirements in food processing scale procurement, driving specification upgrades for washdown-compatible stainless steel housings.
- Load cell resolution advances:Strain gauge and electromagnetic-force-compensation technologies now achieve microgram precision, opening quality control applications in pharmaceutical labs and electronics assemblers.
Market Restraints
- Strain gauge supply concentration:Captive foundry capacity at premium vendors limits independent sourcing options for mid-tier scale manufacturers seeking margin control.
- NIST Handbook 44 compliance costs:Legal-for-trade calibration protocols in the United States compel vendors to maintain accredited service networks, raising operational overhead for commercial weighing revenue.
- Aluminum displacement timeline:Stainless steel repositioning in high-precision load cell housings extends procurement cycles as engineering teams validate corrosion resistance claims against legacy specifications.
Strategic Opportunities
- German chemical sector infrastructure renewal:Upgrades to legacy weighing infrastructure concentrate demand in Europe's largest industrial economy, favoring vendors with EU Measuring Instruments Directive certification pathways.
- IoT-enabled predictive maintenance convergence:Integration of load cell diagnostics with cloud analytics platforms creates recurring revenue streams through subscription-based calibration monitoring.
- India food processing expansion:FSSAI enforcement of hygienic weighing standards in commercial kitchens and production facilities opens import demand for certified bench and floor scale systems.
Industry Challenges
- OIML R76 harmonization friction:Conformity assessment alignment across European member states raises compliance costs for non-European exporters navigating single certification pathways.
- Legacy analog system integration:Digital signal conversion from mechanical force platforms requires retrofit engineering expertise scarce among maintenance teams in mature industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Industrial Scales Market |
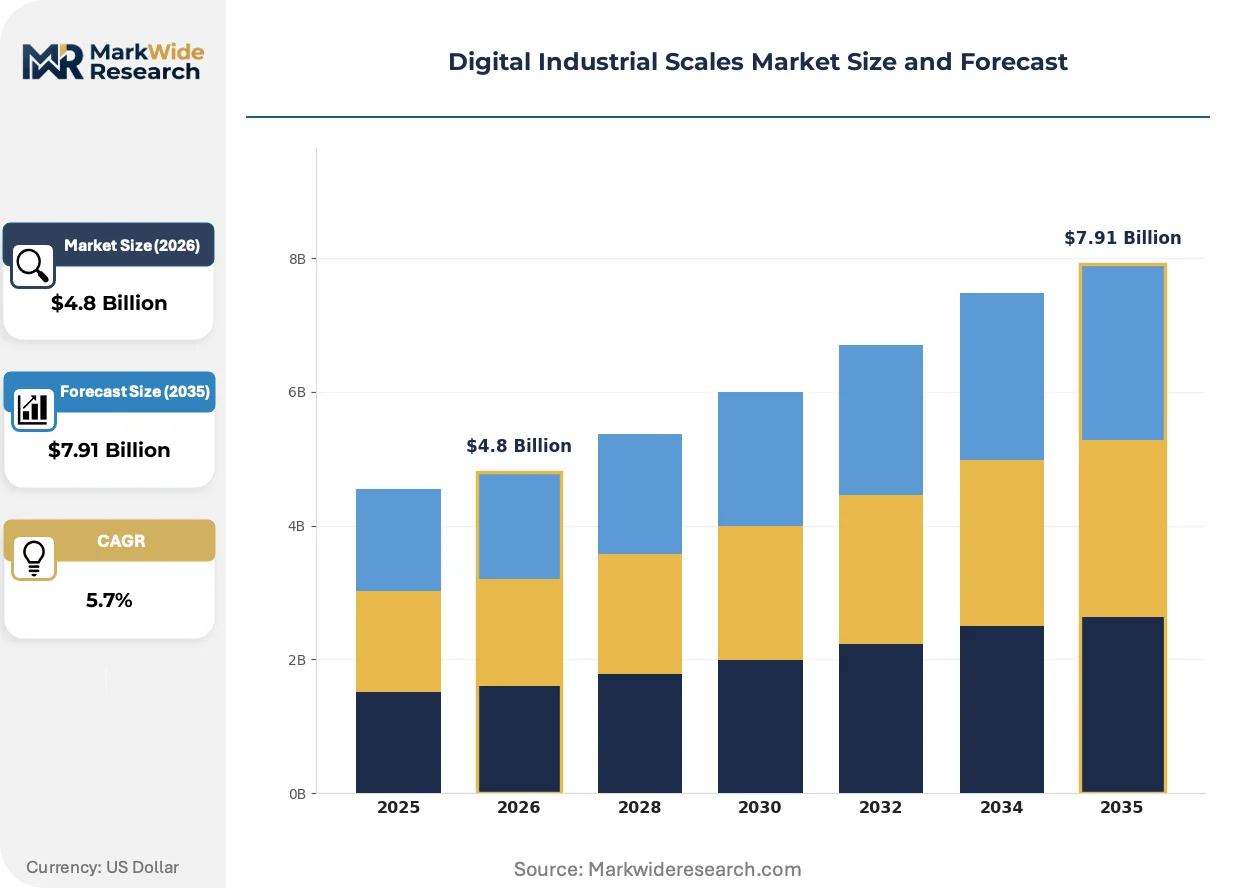
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench Scales, Floor Scales, Crane Scales, Counting Scales, Precision Scales Technology: Load Cell, Electromagnetic, Hydraulic, Pneumatic, Strain Gauge Application: Manufacturing, Logistics, Warehousing, Quality Control, Packaging End User Industry: Automotive OEMs, Food Processing Plants, Textile Mills, Chemical Plants, Electronics Assemblers |
| Companies Covered | Mettler Toledo, A&D Company, Sartorius AG, Ohaus Corporation, Rice Lake Weighing Systems, Avery Weigh-Tronix, Fairbanks Scales, Adam Equipment, Kern & Sohn GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Industrial Scales Market Trends and Innovations
Digital industrial scales are converging with connectivity platforms and advanced materials, reshaping how precision measurement integrates into automated production workflows. Three developments are compressing traditional procurement patterns.
Machine learning algorithms embedded in scale firmware are automating drift detection and self-calibration routines. Pharmaceutical quality control labs in Switzerland and electronics assemblers in South Korea are deploying these systems to reduce manual intervention. This capability is automating the shift from scheduled maintenance toward condition-based service models, compressing vendor service revenue cycles.
REACH substance restrictions and RoHS hazardous material limits are tightening specifications for load cell coatings and circuit board assemblies. Industrial scale manufacturers serving European markets must reformulate supply chains to eliminate restricted substances. Bench and precision scale lines face the steepest reformulation costs due to their higher electronics content and export exposure.
Buyer preference is consolidating around single-source vendors offering bundled calibration, certification, and spare part availability. Food processing procurement teams are disintermediating independent service contractors in favor of manufacturer-direct maintenance agreements. This pattern is most visible in Germany, where chemical and automotive OEMs negotiate enterprise-scale weighing infrastructure contracts with integrated lifecycle terms.
Digital Industrial Scales Market Segmentation
Segmentation in digital industrial scales determines which certification pathways vendors must navigate and where margin pools concentrate. Product type and end-use industry classifications dictate whether NIST Handbook 44, EU Measuring Instruments Directive, or FDA FSMA traceability mandates apply.
Product Type:
Certification burdens vary sharply across product types, with legal-for-trade floor and bench scales requiring accredited calibration networks while precision laboratory units face pharmaceutical validation protocols.
- Floor Scales:Ruggedized platforms engineered for palletized loads up to 50,000 kilograms with NTEP-certified load cells. Demand concentrates in German automotive OEM warehouses where EU Green Deal material-efficiency standards are compressing replacement cycles for aging steel-deck platforms.
- Precision Scales:Electromagnetic-force-compensation systems achieving microgram resolution for pharmaceutical quality control. Electronics assemblers in South Korea and Switzerland are deploying these units with embedded machine learning for automated drift detection.
- Bench Scales:Compact units for portion control and recipe formulation in commercial kitchens.
- Crane Scales:Suspended load monitoring systems for bulk material handling in ports and foundries.
- Counting Scales:Piece-counting instruments for inventory verification in electronics distribution centers.
Floor scales sit at the top of the volume ranking, with precision scales climbing the fastest.
Technology:
Technology selection determines resolution limits, environmental tolerance, and supply chain exposure to captive strain gauge foundries.
- Strain Gauge:Metallic foil sensors bonded to load cell bodies converting mechanical deformation into resistance change. German chemical plants specify stainless steel-housed strain gauge configurations to satisfy EU Green Deal corrosion resistance mandates.
- Electromagnetic:Force-compensation mechanisms using servo motors to maintain null position, enabling sub-milligram precision. Swiss pharmaceutical labs and South Korean electronics assemblers are the primary demand centers for this technology.
- Load Cell:Encompassing shear beam, compression, and tension cell configurations for industrial platforms.
- Hydraulic:Fluid-based force transmission for explosive environments and heavy-capacity mining applications.
- Pneumatic:Air-pressure sensing systems for washdown environments in food processing facilities.
Strain gauge configurations dominate shipment volumes, while electromagnetic systems are gaining share fastest in high-margin laboratory segments.
Application:
Application context dictates ingress protection ratings, platform materials, and integration complexity with enterprise resource planning systems.
- Manufacturing:Process control weighing integrated into production lines for work-in-progress tracking. German automotive OEMs are upgrading legacy analog systems to digital platforms with IoT-enabled predictive maintenance capabilities.
- Quality Control:Verification weighing against specification tolerances with automated rejection protocols. Electronics assemblers in South Korea deploy these systems for component consistency validation.
- Logistics:Freight dimensioning and weight capture for carrier billing compliance.
- Warehousing:Inventory cycle counting and put-away verification in distribution centers.
- Packaging:Fill-level control and net-content verification for regulatory compliance.
Manufacturing applications represent the largest installed base, with quality control expanding most quickly as microgram resolution becomes standard in pharmaceutical and electronics sectors.
End User Industry:
End-use concentration determines whether FSMA food safety mandates, REACH substance restrictions, or automotive IATF quality standards drive procurement specifications.
- Food Processing Plants:Hygienic design scales with IP69K washdown ratings and stainless steel construction. FDA Hazard Analysis and Critical Control Point rules are mandating FSMA-traceable weighing systems across U.S. production facilities.
- Automotive OEMs:Just-in-time inventory weighing and supplier quality verification. German manufacturers are consolidating procurement around single-source vendors offering bundled calibration and spare part availability.
- Chemical Plants:Corrosion-resistant platforms for hazardous material handling with ATEX certification.
- Electronics Assemblers:Precision weighing for solder paste, adhesives, and micro-components in cleanroom environments.
- Textile Mills:Fiber and yarn weighing for dye lot consistency and inventory management.
Food processing plants command the highest volume demand, with electronics assemblers showing the steepest expansion trajectory as microgram resolution requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical and automotive OEM clusters are compressing upgrade cycles for legacy weighing infrastructure as EU Green Deal mandates tighten material-efficiency standards. Demand concentrates across four industrial economies where regulatory frameworks and end-use expansion create differentiated procurement environments.
United States
Food processing plants across the Midwest and Southeast are expanding precision-weighing adoption under FDA Hazard Analysis and Critical Control Point rules. NIST Handbook 44 governs legal-for-trade calibration protocols, compelling vendors to maintain accredited service networks. Chicago and Atlanta industrial corridors show concentrated demand for FSMA-traceable bench and floor scale systems.
Germany
Chemical plants in North Rhine-Westphalia and automotive OEM warehouses in Bavaria are replacing aging steel-deck platforms to satisfy EU Measuring Instruments Directive certification requirements. The EU Green Deal is tightening durability and recyclability standards for industrial equipment sold across member states. Stuttgart and Ludwigshafen production clusters anchor demand for stainless steel-housed strain gauge configurations.
China
Electronics assemblers in the Yangtze River Delta and Pearl River Delta are deploying microgram-resolution systems for solder paste and micro-component weighing. SAMR enforcement of measurement instrument standards is harmonizing conformity assessment with OIML R76 frameworks. Shenzhen and Suzhou cleanroom facilities represent the fastest-expanding demand centers for electromagnetic-force-compensation technology.
India
FSSAI enforcement of hygienic weighing standards is opening import demand for certified bench and floor scale systems in commercial kitchens and food processing facilities. The country's national food safety regulator is mandating traceable measurement across production lines. Maharashtra and Gujarat industrial corridors show concentrated procurement of IP69K-rated stainless steel platforms.
Switzerland
Pharmaceutical quality control labs in Basel and Geneva are deploying machine learning-embedded scales for automated drift detection and self-calibration. Swissmedic oversight of manufacturing equipment validation is elevating specification requirements for laboratory-grade systems. The Basel pharmaceutical cluster anchors European demand for sub-milligram resolution instrumentation.
Digital Industrial Scales Market Competitive Landscape
Global majors compete with regional champions across certification pathways and service network density. The vendor base organizes into three tiers: premium vendors with captive strain gauge foundries, mid-tier fabricators sourcing independent load cells, and regional specialists serving national calibration requirements. Consolidation pressure is mounting as food processing procurement teams disintermediate independent service contractors in favor of manufacturer-direct maintenance agreements. Two dominant competitive moves are reshaping positioning: backward integration into load cell manufacturing and geographic expansion of accredited calibration networks.
Within the premium-tier vector, Mettler Toledo and Sartorius AG exemplify vendors with captive strain gauge foundry capacity. Rice Lake Weighing Systems represents mid-tier competitiveness through upstream control over load cell manufacturing and domestic U.S. fabrication capacity. These three anchors illustrate how supply chain configuration and certification infrastructure determine margin sustainability across bench, precision, and floor scale lines.
| Leading Market Players |
|---|
| Mettler Toledo |
| A&D Company |
| Sartorius AG |
| Ohaus Corporation |
| Rice Lake Weighing Systems |
| Avery Weigh-Tronix |
| Fairbanks Scales |
| Adam Equipment |
| Kern & Sohn GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive strain gauge foundry capacity at Mettler Toledo and Sartorius AG anchors premium-tier pricing power while compressing margin room for mid-tier fabricators sourcing independent load cells. This backward integration into core sensor production simultaneously insulates premium vendors from aluminum-to-stainless steel raw material cost swings and enables bundled calibration service premiums.
Pricing Analysis
Input-cost pass-through from strain gauge metals and stainless steel housings flows unevenly across vendor tiers. Three-tier pricing structure across premium, standard, and economy levels separates NIST-accredited legal-for-trade systems from uncertified bench units. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in mid-tier electromagnetic systems is intensifying because German automotive OEMs negotiate enterprise-scale contracts with lifecycle terms. Food processing procurement teams show highest price sensitivity, while Swiss pharmaceutical labs accept premium positioning for microgram resolution.
Supply Chain Analysis
Strain gauge supply rests on German specialty sensor producers, Swiss precision component manufacturers, and Chinese electronics assembly clusters. Raw material feeds draw from Swedish stainless steel mills, Japanese specialty alloys, and Malaysian circuit board fabricators. Single-source vulnerability concentrates in captive foundry capacity for high-precision load cells. Distribution runs through manufacturer-direct service networks in regulated markets and industrial distributors in price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as food processing plants shift procurement toward FSMA-traceable stainless steel systems with embedded calibration diagnostics.
For Market Incumbents: Lock in German chemical and automotive OEM relationships through EU Measuring Instruments Directive certification investments and captive spare part availability. Defend against mid-tier disintermediation by consolidating manufacturer-direct maintenance agreements that independent service contractors cannot match. Prioritize backward integration into stainless steel load cell housings to capture EU Green Deal material-efficiency upgrade cycles. For New Entrants and Emerging Players: The price-point gap between electromagnetic-force-compensation laboratory systems and strain gauge floor scales offers white-space entry. Target India's FSSAI enforcement wave with IP69K-rated bench scales for commercial kitchens and food processing corridors in Maharashtra and Gujarat. Pursue cloud-enabled predictive maintenance subscriptions as a differentiated go-to-market angle against legacy vendors with analog service models. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier fabricators lack captive load cell capacity and struggle to fund NIST-accredited service network expansion. Long-term viability favors vendors with dual certification pathways and IoT-enabled recurring revenue streams. Watch the pace of EU Green Deal enforcement as the inflection indicator for infrastructure replacement velocity in Europe's largest industrial economy.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Captive strain gauge supply insulates margin control against aluminum displacement costs. |
| EU Measuring Instruments Directive Certification Investment | Single certification pathway opens German chemical and automotive OEM procurement. |
| IoT-Enabled Predictive Maintenance Platform Launch | Cloud diagnostics create recurring revenue streams beyond transactional equipment sales. |
| Stainless Steel Housing Formulation Shift | REACH-compliant material transition satisfies EU Green Deal durability mandates. |
| Manufacturer-Direct Service Network Expansion | Accredited calibration coverage defends against independent contractor disintermediation. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers triangulated against customs data, NIST calibration records, EU Measuring Instruments Directive filings, and SEC 10-K disclosures. Bottom-up shipment analysis and top-down industrial equipment spending patterns were reconciled across the modeling period.
Rate-of-change decomposition anchored the analytical framework across product type, technology, application, and end-use industry dimensions. CAGRs were derived from segment-level volume trajectories and value-per-unit trends. Forecast inputs incorporated EU Green Deal implementation timelines, FSMA traceability mandate phases, and load cell resolution technology diffusion curves.
Caveats apply where regulatory enforcement delays or strain gauge supply disruptions could materially shift the outlook. Forecasts reflect assumptions about certification pathway harmonization and stainless steel raw material availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Intralogistics Market
Industrial Automation
Smart Factory Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Asia Industry 4.0 Market