
 Coffee Pods Market | 2026-2036
Coffee Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Pods Market Analysis
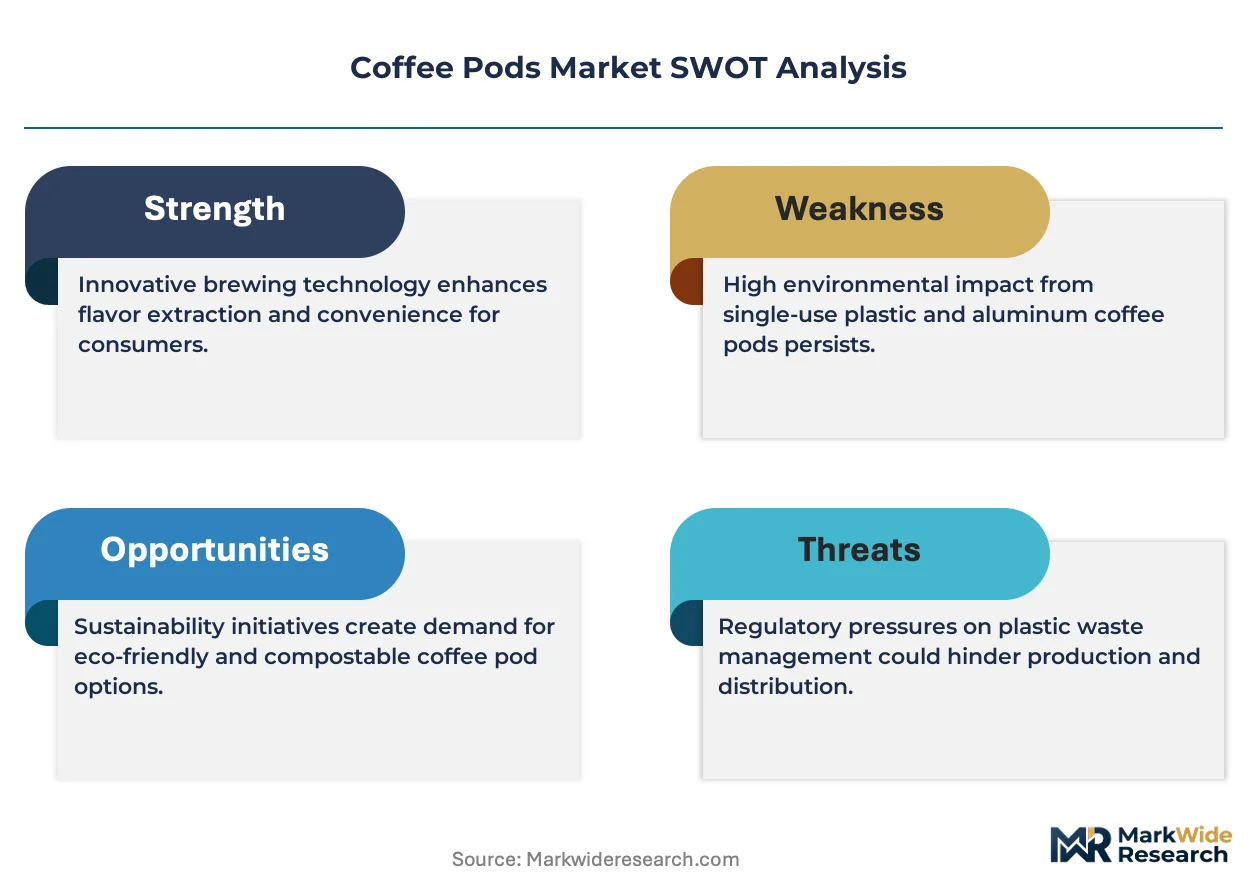
The price-performance gap between aluminum Nespresso-compatible pods and plastic K-Cup alternatives is hardening into a permanent market fracture. Nestlé leverages its proprietary brewing system to sustain premium positioning across European cafés and upscale households. JDE Peet's competes through broad private-label and branded distribution, while Keurig Dr Pepper anchors the North American office and retail consumer base with machine-locked pod economics.
Coffee pods are sealed, pre-portioned single-serve containers—typically seven to ten grams of ground coffee housed in plastic, aluminum, or compostable shells—engineered for pressure-driven extraction at standardized temperatures and bar pressures. Their primary commercial purpose is to deliver consistent beverage quality without trained barista labor or grind calibration. The material segment reveals aluminum pods commanding margin pools through recyclability credentials and perceived flavor preservation, while biodegradable formats are gaining fastest among regulatory-sensitive European retail consumers. K-Cup systems still dominate absolute volume in office settings, though Nespresso-compatible pods lead revenue per unit across café and restaurant channels.
The EU Green Deal and REACH frameworks restrict virgin plastic use and mandate extended producer responsibility for coffee packaging waste, directly reshaping material R&D budgets and product line decisions. The FDA's food-contact substance regulations and state-level extended producer responsibility laws in California and Oregon impose parallel compliance costs on US market entrants. Stakeholders must monitor how rapidly compostability certifications displace recyclability claims as the primary consumer decision factor.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing a wholesale material transition across pod manufacturing, with biodegradable shell development now commanding the majority of R&D expenditure and directly determining which product lines survive compliance deadlines.
Growth Catalysts
- Office coffee program modernization:Workplace beverage services across Germany and the Netherlands are replacing batch brewers with single-serve systems to reduce waste and labor costs.
- REACH framework material restrictions:European chemical regulations are accelerating compostable polymer adoption by disqualifying conventional multi-layer plastics from shelf placement.
- Pressure-driven extraction standardization:Advances in bar-pressure calibration technology enable consistent espresso-quality output without trained operators.
Market Restraints
- Aluminum ingot price volatility:Recyclable pod shells face margin compression when London Metal Exchange aluminum prices spike.
- Compostable certification timeline friction:TÜV Austria and BPI verification processes extend new product launches by 18-24 months.
- Capsule machine lock-in economics:Proprietary brewing systems create switching costs that suppress private-label penetration in installed-base households.
Strategic Opportunities
- Hospitality channel underpenetration:Boutique hotels in Portugal and Greece represent untapped demand for in-room premium pod systems.
- Extended producer responsibility incentives:Germany's VerpackG law creates competitive advantage for manufacturers with closed-loop collection infrastructure.
- Smart machine connectivity convergence:IoT-enabled brewers combined with subscription replenishment algorithms enable predictive restocking models.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with food-contact biopolymer expertise command premium compensation and extended search timelines.
- Legacy machine backward compatibility:New biodegradable materials must perform across aging brewer installed bases with inconsistent pressure profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Pods Market |
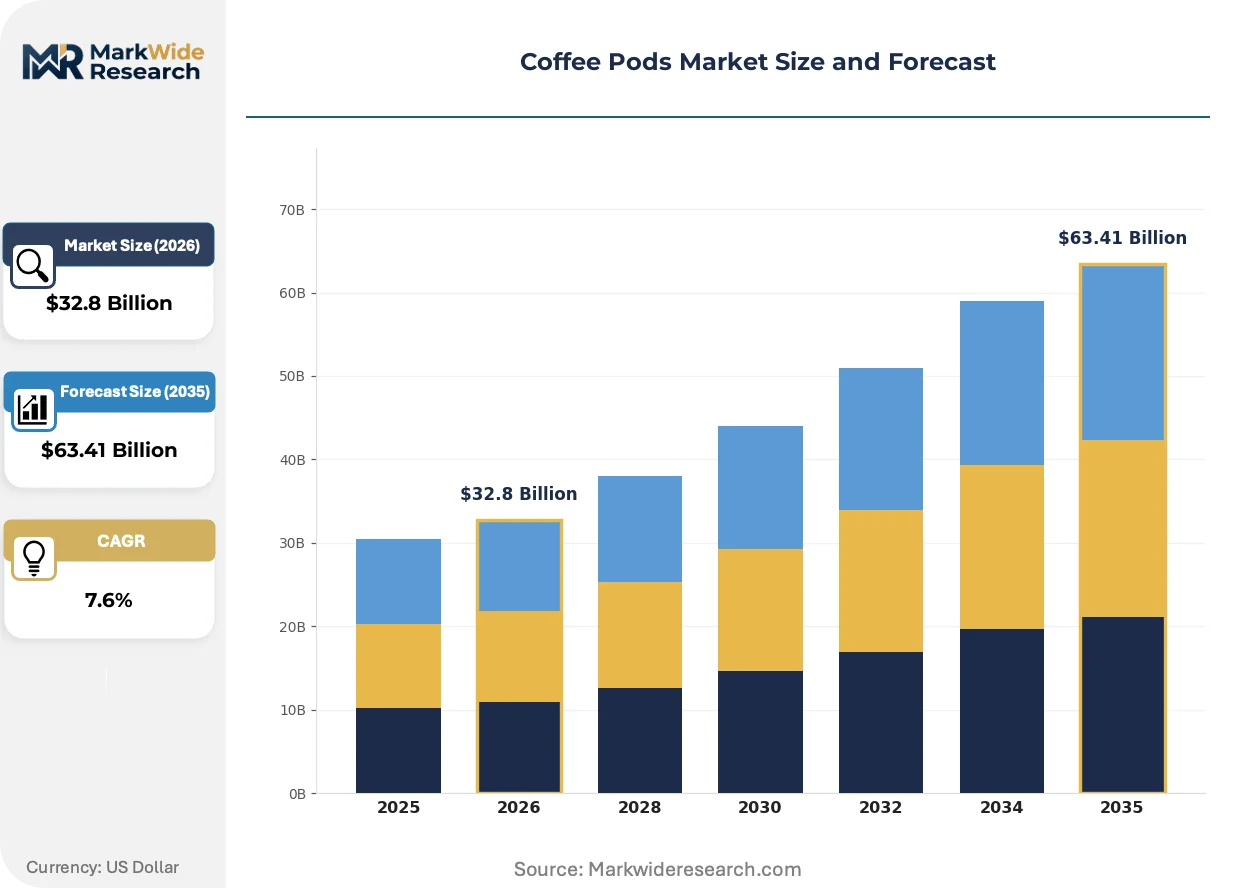
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $63.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: K-Cup, Nespresso, Dolce Gusto, Others Customer Type: Retail Consumers, Office Users, Cafés, Restaurants Flavor Profile: Espresso, Dark Roast, Medium Roast, Flavored Material: Plastic, Aluminium, Biodegradable, Paper |
| Companies Covered | Keurig Dr Pepper, Nestlé, Starbucks Corporation, The Kraft Heinz Company, JDE Peet's, Luigi Lavazza, Illycaffè, J.M. Smucker Company, Peet's Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Pods Market Emerging Trajectories
Material science breakthroughs and regulatory compliance architectures are converging to redefine competitive advantage, with sustainability credentials rapidly displacing convenience as the primary purchase determinant among institutional buyers.
Home-compostable shell formulations utilizing polylactic acid and paper fiber laminates are rewriting the technical specifications for pod barrier properties. German retail chains and Scandinavian office services firms are piloting these materials at scale. The structural consequence is a compression of acceptable shelf-life claims from 18 months to 12 months.
REACH annex XVII restrictions on microplastics are mandating redesigned filtration layers across all EU-distributed products. Industrial consequence includes accelerated partnerships between pod manufacturers and specialty membrane suppliers. Café and restaurant channels face the steepest reformulation costs due to higher extraction temperature requirements.
Corporate procurement departments are consolidating coffee service contracts under facility management umbrellas rather than maintaining separate beverage vendor relationships. Foodservice distributors are capturing this spend by bundling pod supply with equipment maintenance. The shift is most visible in France and Belgium where integrated workplace service contracts now dominate mid-size enterprise accounts.
Coffee Pods Market Segmentation
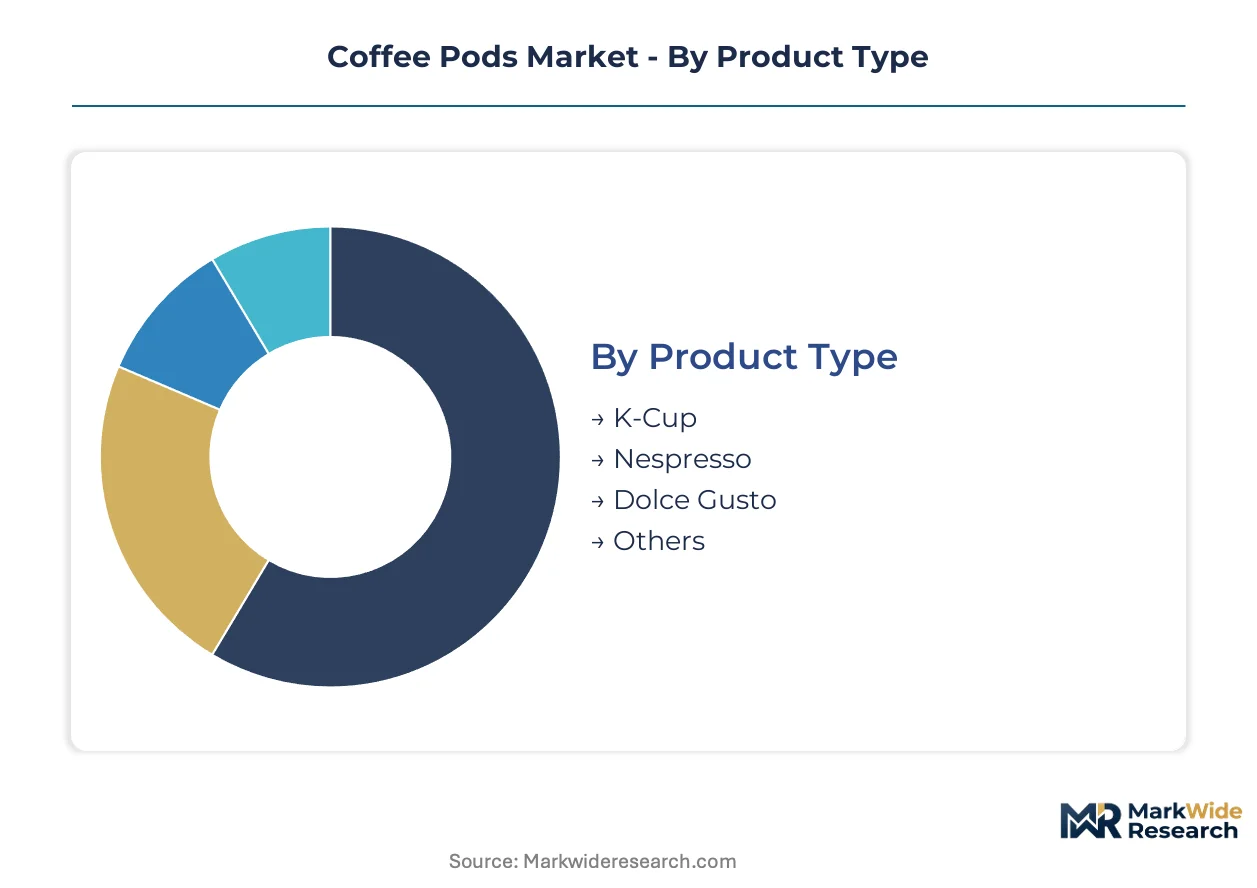
Pod system architecture determines machine compatibility, brewing pressure profiles, and margin capture across the value chain. Material composition and customer channel selection directly shape regulatory compliance burdens and sustainability credentialing requirements.
Product Type:
Volume leadership and premium positioning diverge sharply across proprietary brewing ecosystems, with machine-installed base economics locking consumers into format-specific repurchase cycles.
- K-Cup:Polypropylene shells with puncturable foil lids engineered for gravity-fed drip extraction at low pressure. Office users in the United States drive replenishment volume through Keurig Dr Pepper's locked machine economics, though plastic waste scrutiny intensifies procurement pressure.
- Nespresso:Aluminum capsules with hermetic seals designed for 19-bar pressure extraction and crema formation. European cafés and upscale households sustain premium pricing through recyclability programs and proprietary brewing system control.
- Dolce Gusto:Multi-beverage capsules supporting coffee, chocolate, and milk-based drinks through variable pressure modulation. Latin American and Southern European retail markets concentrate demand for family-oriented beverage variety.
- Others:Includes E.S.E. pods, soft pods, and emerging compostable formats from regional manufacturers. Specialty coffee roasters in Italy and Portugal deploy these for artisan positioning outside multinational system constraints.
Mature deployment sits with K-Cup systems. Newer deployment is concentrated in biodegradable-compatible open-format machines.
Customer Type:
Channel selection dictates contract structure, with institutional accounts demanding consolidated facility management terms while retail consumers respond to subscription algorithms.
- Retail Consumers:Individual households purchasing through supermarkets, e-commerce platforms, and brand-direct subscriptions. German and Dutch consumers demonstrate the highest per-capita pod consumption rates globally.
- Office Users:Workplace beverage programs replacing batch brewers with single-serve systems to reduce labor and waste. Facility management consolidation in France and Belgium now bundles pod supply with equipment maintenance contracts.
- Cafés:High-volume extraction environments requiring consistent espresso quality without trained barista labor. Portugal and Greece boutique hospitality segments show underpenetration relative to Northern European benchmarks.
- Restaurants:Full-service dining operations integrating pod systems for post-meal coffee service standardization. Mid-tier chains across Spain and Italy pilot smart machine connectivity for predictive restocking.
Revenue per unit peaks with café channels. Volume expansion is climbing the fastest among office users under integrated service contracts.
Flavor Profile:
Roast intensity preferences map to regional coffee culture and extraction system capabilities, with pressure-driven machines favoring darker profiles.
- Espresso:Finely ground dark roasts optimized for high-pressure extraction and concentrated output. Italian and Iberian café channels sustain demand for traditional 25-30ml shot formats.
- Dark Roast:Extended roasting profiles emphasizing body and low acidity for American and Northern European palates. K-Cup systems dominate this segment through gravity-fed brewing compatibility.
- Medium Roast:Balanced acidity and origin character preservation appealing to third-wave coffee consumers. Scandinavian retail markets and specialty roasters drive premium positioning.
- Flavored:Vanilla, hazelnut, and seasonal variants targeting casual consumption occasions. United States retail consumers generate disproportionate volume through impulse and gift purchasing.
Established demand centers on dark roast formulations. Steepest expansion trajectory belongs to medium roast single-origin offerings.
Material:
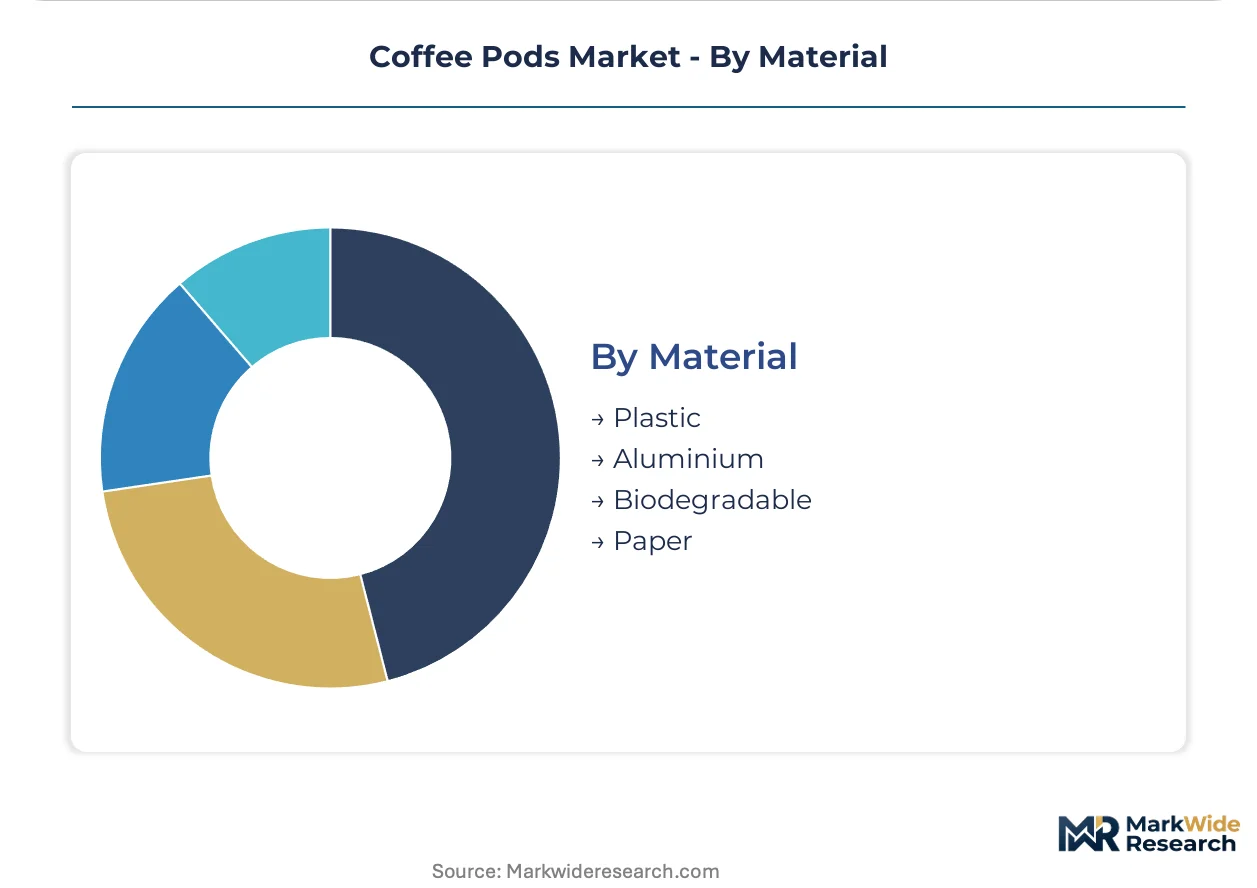
Regulatory deadlines across the EU Green Deal and REACH annex XVII are forcing material transitions that compress shelf-life claims and elevate R&D expenditure.
- Plastic:Multi-layer polypropylene and polyethylene terephthalate constructions with oxygen barrier properties. REACH microplastic restrictions are disqualifying conventional formats from EU shelf placement.
- Aluminium:Recyclable shells with inert surface properties preserving volatile aromatic compounds. Nespresso's closed-loop collection infrastructure in Germany creates competitive advantage under VerpackG extended producer responsibility law.
- Biodegradable:Polylactic acid and compostable polymer formulations certified to TÜV Austria and BPI standards. German retail chains and Scandinavian office services firms pilot these at scale despite 18-24 month certification timelines.
- Paper:Fiber-based shells with bio-laminate barrier layers for home-compostable claims. Shelf-life compression to 12 months limits distribution radius and inventory holding strategies.
Installed base concentration remains with aluminum and plastic. Fastest material transition is occurring in biodegradable formats under regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates Germany's pod manufacturing infrastructure, with Düsseldorf and Cologne hosting formulation labs and packaging engineering centers that supply European retail and office channels.
Germany
Workplace coffee programs in Frankfurt and Hamburg drive single-serve system adoption across banking and professional services sectors. The VerpackG extended producer responsibility law rewards manufacturers operating closed-loop aluminum collection networks. Bavarian technical universities partner with pod makers on compostable polymer barrier research.
United States
Office beverage services in Chicago and Atlanta sustain K-Cup volume through facility management contract consolidation. FDA food-contact substance regulations impose compliance costs on new market entrants. Seattle's specialty roasters develop private-label compatible pods for regional grocery chains.
France
Café channel demand in Paris and Lyon concentrates premium pod procurement for espresso-quality standardization. REACH annex XVII microplastic restrictions accelerate filtration layer redesign across all distributed products. Rhône-Alpes packaging clusters pilot home-compostable shell production at pilot scale.
Netherlands
Corporate headquarters in Amsterdam and Rotterdam consolidate integrated workplace service contracts bundling pod supply with equipment maintenance. EU Green Deal packaging waste directives mandate biodegradable material transitions by fixed deadlines. Eindhoven polymer research institutes collaborate with manufacturers on PLA barrier optimization.
Italy
Traditional espresso culture in Milan and Turin sustains demand for high-pressure extraction systems in hospitality channels. ECHA chemical safety assessments influence food-contact biopolymer approval timelines. Piedmontese engineering firms supply precision brewing equipment to pod system operators.
Coffee Pods Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification and brewing system control dimensions. The market structures around proprietary machine-pod ecosystems and open-format compatibility tiers. Three archetypes dominate: multinational beverage conglomerates with captive brewing systems, private-label manufacturers serving retail chains, and specialty roasters pursuing artisan positioning outside system constraints. Capacity expansion in compostable polymer processing and strategic partnerships with membrane suppliers constitute the primary competitive moves.
Within the multinational tier, Nestlé, Keurig Dr Pepper, and JDE Peet's occupy positions defined by proprietary system control and geographic anchoring. Nestlé represents the premium-aluminum archetype through European café and upscale household penetration. Keurig Dr Pepper exemplifies scale-driven North American office channel dominance through machine-locked economics. JDE Peet's sits within the diversified distribution archetype, spanning private-label supply and branded retail across multiple European markets.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Nestlé |
| Starbucks Corporation |
| The Kraft Heinz Company |
| JDE Peet's |
| Luigi Lavazza |
| Illycaffè |
| J.M. Smucker Company |
| Peet's Coffee |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty roasters in Italy and Portugal now control substantial compostable polymer processing capacity, tightening supply discipline and enabling premium pricing for TÜV Austria-certified pods against commodity plastic alternatives.
Pricing Analysis
Value-based pricing anchored to extraction consistency and crema quality sustains Nespresso-compatible premiums in European cafés. Pricing stratifies across aluminum recyclability tiers, plastic economy alternatives, and biodegradable certification grades. Cost compression in conventional plastic pods is intensifying because REACH microplastic restrictions disqualify multi-layer formats from German and French retail shelves. Office procurement managers in the Netherlands demonstrate highest price sensitivity, while boutique hospitality buyers in Portugal accept material premiums for sustainability credentialing.
Supply Chain Analysis
Reverse-logistics flows for aluminum capsule collection now determine competitive positioning under Germany's VerpackG extended producer responsibility framework. Manufacturing gravity centers on Germany, Italy, and the Netherlands for pod shell production and barrier membrane lamination. Raw material dependencies span aluminum ingots from Norwegian smelters, polylactic acid from Thai agricultural feedstock processors, and specialty oxygen-barrier films from Japanese polymer suppliers. Single-source vulnerability concentrates in compostable certification bodies where TÜV Austria and BPI verification queues extend product launch timelines. Distribution runs through integrated facility management contracts in France and Belgium, with foodservice distributors capturing bundled equipment-maintenance-pod supply relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's packaging waste directives function as a cost-of-compliance moat, advantaging incumbents with closed-loop collection infrastructure and certified biodegradable product lines against undercapitalized challengers.
For Market Incumbents: Deepen backward integration into compostable polymer processing to secure supply continuity as REACH annex XVII restrictions accelerate material transitions. Defend machine-installed base economics through smart connectivity upgrades that embed predictive replenishment algorithms, raising switching costs against private-label entrants. Prioritize certification investment in TÜV Austria and BPI standards to maintain shelf access across German and Scandinavian retail channels. For New Entrants and Emerging Players: Launch via direct-to-subscription models targeting specialty coffee enthusiasts in underpenetrated Portuguese and Greek hospitality markets, bypassing entrenched foodservice distributor relationships. Exploit white-space in home-compostable paper-shell formats where shelf-life compression to twelve months limits incumbent inventory strategies. Anchor go-to-market positioning around single-origin medium roast profiles that align with Scandinavian third-wave consumer preferences outside multinational system constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional compostable-format specialists with pilot-scale production in the Rhône-Alpes packaging cluster, where EU Green Deal deadlines force consolidation among capital-constrained players. Long-term viability over a multi-year window rests on certification pipeline depth and membrane supplier partnerships rather than brand equity alone. Monitor compostability certification timeline compression as the inflection signal indicating regulatory enforcement intensity and viable exit windows.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Material Certification | TÜV Austria and BPI verification secures shelf placement under REACH annex XVII microplastic restrictions. |
| Closed-Loop Collection Infrastructure | Germany's VerpackG law rewards manufacturers operating proprietary aluminum capsule recovery networks. |
| Smart Machine Connectivity Integration | IoT-enabled brewers with predictive replenishment algorithms embed switching costs in office installed bases. |
| Membrane Supplier Partnership | Specialty barrier film collaborations address REACH filtration layer redesign mandates for high-temperature extraction. |
| Direct-to-Subscription Channel Launch | Bypasses consolidated French and Belgian facility management contracts for specialty consumer acquisition. |
Methodological Framework
Document review covered customs trade records, EU packaging waste directive filings, and SEC disclosures from publicly traded beverage conglomerates, complemented by interviews with plant managers at German polymer processing facilities, category buyers at Dutch retail chains, procurement leads at French facility management firms, and R&D directors at Italian specialty roasters. Secondary validation drew from ECHA chemical safety assessments, TÜV Austria certification databases, and VerpackG compliance filings. Bottom-up demand modeling triangulated against top-down value chain analysis across material, machine, and channel dimensions.
Historical consumption patterns cross-referenced against expert panel input from polymer scientists and foodservice distribution executives shaped the analytical framework. Segmentation dimensions modeled include pod system architecture, material composition tier, customer channel, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycle dynamics, and per-capita consumption elasticity across German, Dutch, and Scandinavian markets. Forecast inputs incorporated aluminum price volatility indices and compostable certification queue lengths.
The model assumes a particular technology adoption path for home-compostable shell formulations; alternative pathways for polylactic acid barrier optimization or paper-fiber laminate breakthroughs would alter the outlook for shelf-life claims and distribution radius. Forecasts reflect assumptions regarding REACH enforcement intensity and EU Green Deal deadline adherence. Practitioners should monitor certification body processing times, London Metal Exchange aluminum price spikes, and facility management contract consolidation rates for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Middle East Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
Coffee Extracts Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Espresso Powder Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Nitrogenated Coffee Market
Coffee
Global Cafe Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Crystal Market
Coffee
North America Instant Coffee Market