
 Adaptogen Coffee Market | 2026-2036
Adaptogen Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptogen Coffee Market Insights
Ingredient sourcing and formulation IP is reconfiguring margin pools across the adaptogen coffee value chain. Four Sigmatic Foods leverages its Nordic supply relationships to sustain premium positioning in mushroom-based formulations. Ryze Superfoods anchors its competitive stance through direct-to-consumer channel control, while MUD/WTR differentiates via a caffeine-free positioning that occupies a distinct niche in the functional beverage landscape.
Adaptogen coffee combines roasted coffee or coffee alternatives with powdered medicinal mushrooms, ashwagandha, rhodiola, or other botanical extracts standardized to bioactive compound levels, delivering functional benefits beyond caffeine stimulation. Powder and instant formats dominate current production volumes, though liquid ready-to-drink lines represent the fastest-growing product type as convenience-seeking consumers shift from at-home preparation to on-the-go consumption. Online retailers and specialty stores capture the highest margin pools in distribution channel segmentation, while cafes and wellness centers drive bulk adoption among institutional end users seeking differentiated beverage menus.
FDA oversight of dietary supplement labeling under DSHEA shapes how adaptogen coffee brands structure health claims, while EFSA novel food assessments govern market access for emerging mushroom extracts within Europe. The EU Green Deal's sustainable sourcing requirements are forcing supply chain documentation upgrades across ingredient procurement networks. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether centralized or regional formulation strategies offer superior compliance economics.
Market Dynamics
Workplace wellness mandates from large US employers are pulling adaptogen coffee into institutional procurement channels, compressing the traditional retail-centric distribution model and forcing suppliers to build B2B service capabilities alongside direct-to-consumer infrastructure.
Growth Catalysts
- DSHEA labeling pathways:FDA's dietary supplement framework allows structure-function claims without pre-market approval, enabling faster product iteration than novel food routes.
- Corporate wellness programs:Fortune 500 employers in the United States are adding functional beverages to cafeteria menus as taxable perks, creating recurring institutional demand.
- Hot-water extraction standardization:Advances in beta-glucan quantification are improving batch consistency and reducing quality variance across mushroom supply networks.
Market Restraints
- Chaga and reishi harvest concentration:Wildcrafting operations in Siberia and northern Canada face climate volatility and permit restrictions, creating raw material bottlenecks.
- EFSA novel food assessments:Emerging mushroom extracts require 18-24 month safety evaluations before EU market entry, delaying European rollout timelines.
- Instant coffee price anchoring:Commodity instant coffee sets consumer reference prices far below functional formulation costs, compressing margin expansion potential.
Strategic Opportunities
- Ready-to-drink liquid formats:Convenience-seeking consumers are migrating from powder preparation to chilled single-serve bottles, opening new cold-chain distribution partnerships.
- EU Green Deal sourcing requirements:Sustainable procurement documentation mandates favor suppliers with certified organic supply networks and carbon accounting systems.
- Germany and Netherlands retail placement:Mainstream supermarket listings for mushroom coffee remain sparse in these high-income markets, offering first-mover shelf space advantages.
Industry Challenges
- Adaptogen standardization expertise:Formulation teams with dual competencies in coffee roasting and botanical extraction are scarce, lengthening product development cycles.
- Cross-jurisdiction claim harmonization:Brands must maintain parallel label versions to satisfy FDA structure-function rules, EFSA health claim restrictions, and national advertising standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptogen Coffee Market |
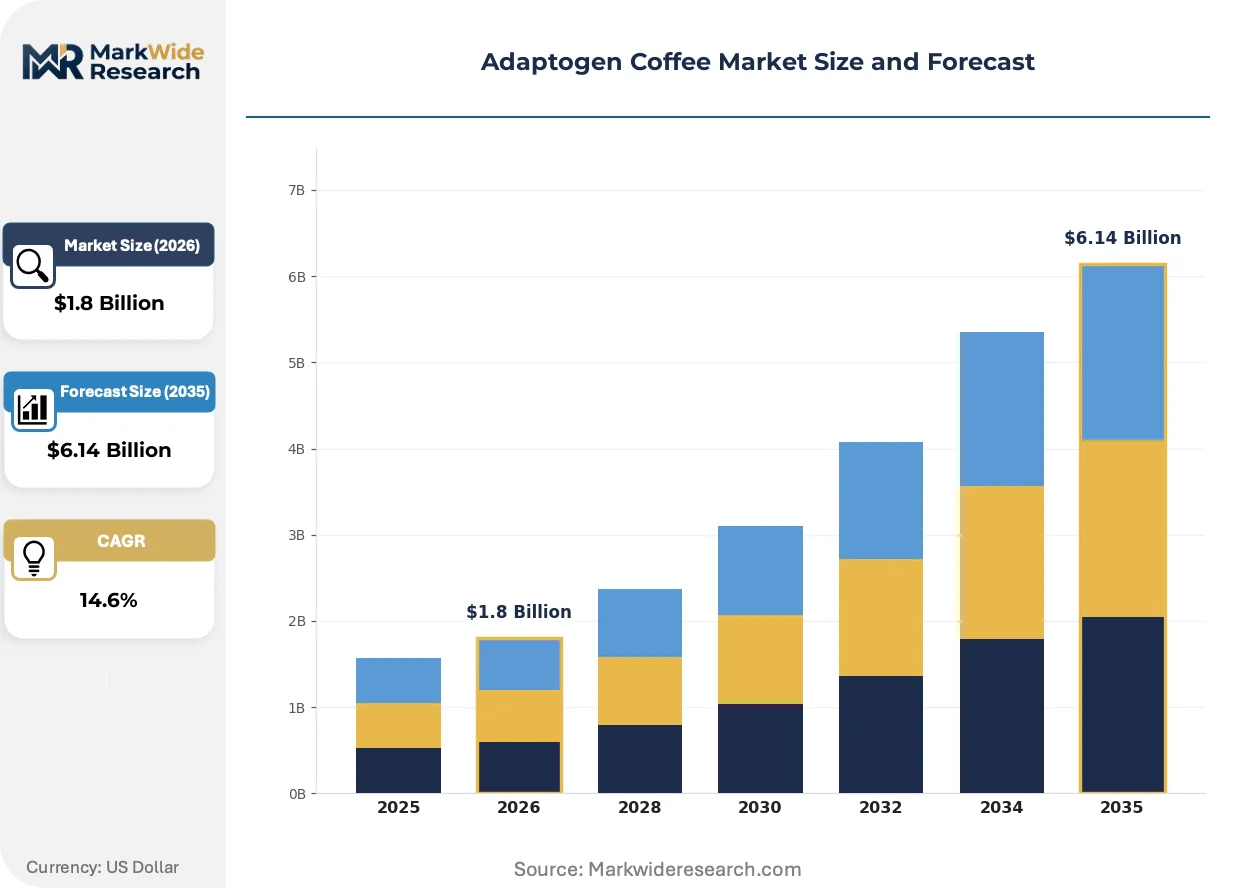
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Instant, Liquid, Capsule, Ground Application: Energy Boost, Stress Relief, Cognitive Enhancement, Immunity Support, Relaxation End User: Cafes, Wellness Centers, Corporate Offices, Hotels, Fitness Studios Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Direct Sales, Health Food Stores |
| Companies Covered | Four Sigmatic Foods, Ryze Superfoods, MUD/WTR, Rasa, Taika, Clevr Blends, La Republica Superfoods, DIRTEA, Everyday Dose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptogen Coffee Market Trends and Innovations
Liposomal delivery systems and precision fermentation are rewriting the bioavailability and scalability assumptions that have governed adaptogen coffee formulation since the category's emergence.
Liposomal encapsulation of ashwagandha and lion's mane extracts is collapsing the absorption gap between functional beverages and pharmaceutical-grade supplements. Wellness-focused consumers in California and New York are adopting these enhanced formats despite 40-60% price premiums, forcing conventional powder brands to reformulate or retreat to value positioning.
EFSA's evolving stance on mushroom beta-glucan health claims is tightening evidentiary requirements for immune and cognitive benefit statements. Brands with existing novel food approvals face retrospective claim audits, while new entrants must commission human intervention studies before market entry, advantaging capitalized incumbents with clinical trial budgets.
Subscription-based replenishment models are displacing one-time retail purchases as the dominant customer acquisition channel. Direct-to-consumer platforms capture higher lifetime value through personalized dosing algorithms, though this shift concentrates customer data risk and increases platform dependency for mid-sized suppliers without owned fulfillment infrastructure.
Adaptogen Coffee Market Segmentation
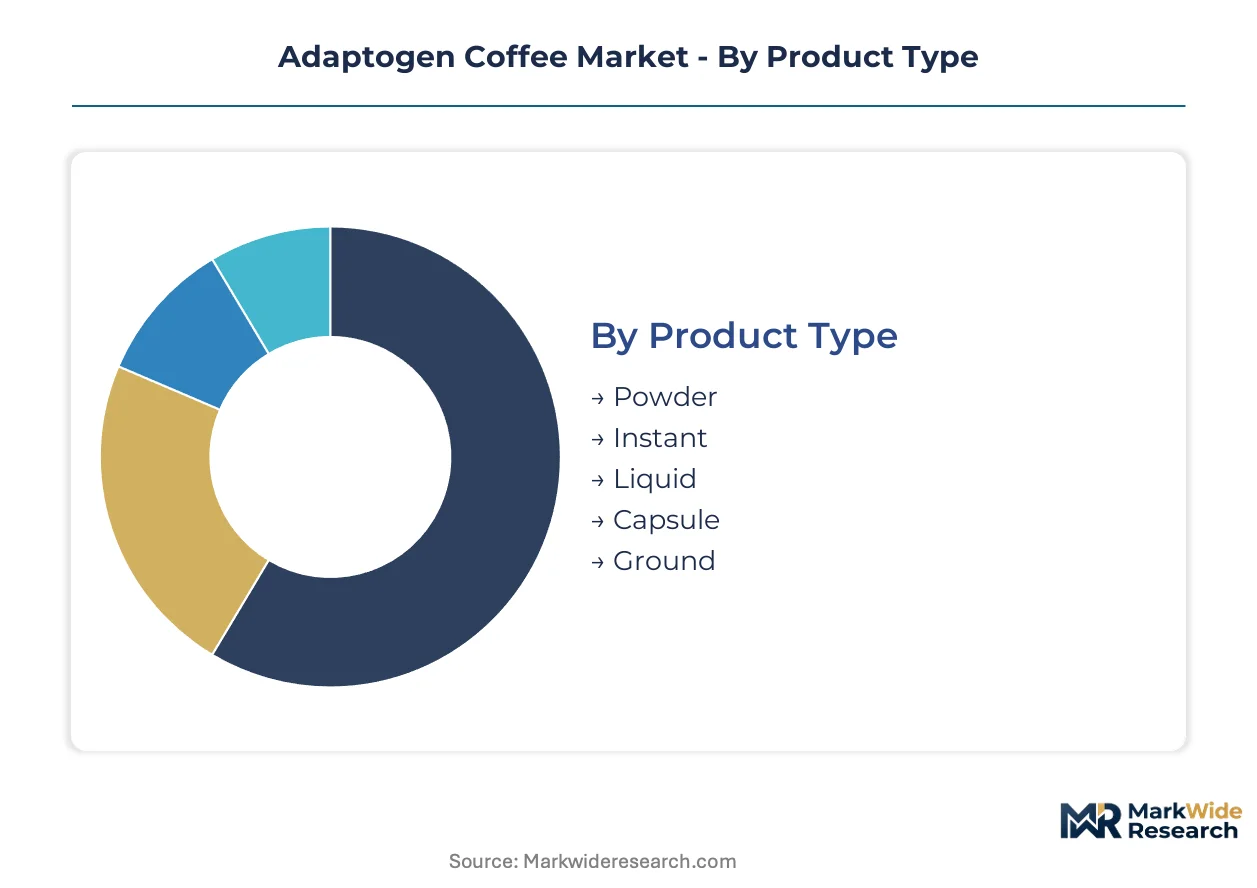
Adaptogen coffee segmentation reveals how formulation format, consumption occasion, and procurement channel intersect to create distinct margin pools. Each dimension carries specific regulatory and logistical constraints that reshape supplier economics.
Product Type:
Powder and instant formats anchor household penetration, while liquid lines capture on-the-go convenience premiums.
- Powder:Dry blends of roasted coffee base with standardized mushroom extracts or ashwagandha powder, requiring consumer preparation with hot water. Demand clusters in United States suburban households seeking ritualized morning routines, constrained by preparation friction that limits office and travel use cases.
- Instant:Soluble granules delivering single-serve convenience with preserved bioactive stability through spray-drying or freeze-drying processes. Corporate break rooms in United States tech corridors are pulling this format into institutional procurement, though EFSA novel food assessments delay European rollout for emerging mushroom varieties.
- Liquid:Ready-to-drink formulations in chilled single-serve bottles, typically combining cold brew coffee with liposomal adaptogen delivery.
- Capsule:Pod-compatible formats for proprietary brewing systems, offering portion control but locking consumers into hardware ecosystems.
- Ground:Traditional roast-and-grind coffee pre-blended with powdered botanicals, appealing to artisanal brewing enthusiasts.
The dominant share belongs to Powder, while Liquid is closing the gap fastest.
Application:
Functional benefit positioning determines pricing architecture and claim substantiation requirements across regulatory jurisdictions.
- Energy Boost:Caffeine-adaptogen synergy formulations targeting sustained alertness without jitters, typically combining coffee with cordyceps or rhodiola. United States fitness studios and CrossFit boxes drive bulk adoption, though FDA structure-function claim boundaries limit explicit performance marketing.
- Stress Relief:Ashwagandha-forward blends with cortisol-modulation positioning, often caffeine-reduced or caffeine-free. Corporate wellness programs in United States Fortune 500 companies are expanding cafeteria placement, constrained by variability in botanical standardization across suppliers.
- Cognitive Enhancement:Lion's mane and bacopa formulations targeting focus and memory support.
- Immunity Support:Beta-glucan-rich chaga and reishi combinations.
- Relaxation:Evening-oriented formulations with L-theanine and reishi for wind-down rituals.
Energy Boost commands the largest addressable base, yet Stress Relief is gaining share fastest among institutional buyers.
End User:
Channel economics diverge sharply between experiential consumption venues and self-directed procurement.
- Cafes:Third-wave coffee shops and wellness-oriented chains incorporating adaptogen shots and lattes into beverage menus. Brooklyn and Los Angeles independent roasters are normalizing mushroom lattes as menu staples, though equipment training and consistency protocols strain smaller operators.
- Wellness Centers:Integrative health clinics and spa facilities dispensing adaptogen coffee as part of holistic treatment protocols. High-income coastal United States markets show strongest penetration, constrained by practitioner education requirements and insurance reimbursement ambiguity.
- Corporate Offices:Employer-subsidized cafeteria and break room installations.
- Hotels:In-room and lobby beverage programs targeting wellness-oriented travelers.
- Fitness Studios:Post-workout retail and membership bundle offerings.
Cafes retain the deepest volume footprint, though Corporate Offices are expanding most quickly as taxable wellness perks.
Distribution Channel:
Margin capture and customer data ownership vary dramatically across route-to-market configurations.
- Online Retailers:Direct-to-consumer platforms and marketplace listings enabling subscription replenishment and personalized dosing algorithms. Ryze Superfoods and similar digitally native brands anchor customer relationships here, though platform dependency and acquisition cost inflation concentrate risk for mid-sized suppliers.
- Specialty Stores:Independent grocers and wellness boutiques with educated staff and sampling capabilities. United States coastal metros and progressive interior cities sustain this channel, constrained by shelf-space competition from established supplement brands.
- Supermarkets:Mainstream grocery retail placement.
- Direct Sales:Brand-owned websites and subscription platforms.
- Health Food Stores:Established natural products retailers with supplement-trained associates.
Online Retailers dominate revenue contribution, while Direct Sales is climbing the fastest as brands invest in owned fulfillment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States consumers absorb premium functional positioning, while European buyers demand regulatory transparency before paying adaptogen markups. Emerging markets anchor volume to commodity coffee pricing.
United States
Corporate wellness procurement and direct-to-consumer subscription models drive demand. FDA's DSHEA framework permits structure-function claims without pre-market approval. Brooklyn and Los Angeles independent roasters normalize mushroom lattes as menu staples, compressing education costs for mainstream adoption.
Germany
Organic certification requirements and sustainability documentation shape buyer expectations. EFSA novel food assessments delay rollout for emerging mushroom extracts. Berlin and Hamburg wellness retailers stock chaga and reishi formulations, though supermarket penetration remains sparse.
Netherlands
High-income urban consumers seek convenience-oriented ready-to-drink formats. EU Green Deal sourcing mandates favor suppliers with carbon accounting systems. Amsterdam specialty grocers pilot functional beverage sections, testing demand before mainstream retail expansion.
United Kingdom
Post-pandemic workplace wellness programs expand cafeteria functional beverage offerings. Advertising Standards Authority scrutiny tightens health claim substantiation. London's third-wave coffee shops integrate adaptogen shots into core menus, establishing consumption rituals.
Canada
Health Canada natural health product licensing creates compliance hurdles for mushroom extract formulations. Wildcrafting permit restrictions in northern provinces constrain chaga supply. Toronto and Vancouver wellness centers dispense adaptogen protocols, bridging retail and clinical channels.
Adaptogen Coffee Market Competitive Landscape
Functional specialists and beverage incumbents split the market into distinct capability territories. The vendor base clusters around three strategic archetypes: Nordic-sourced mushroom formulators, direct-to-consumer platform operators, and caffeine-free niche occupiers. Dominant competitive moves include supply chain certification investments and subscription infrastructure buildouts.
Within the Nordic-sourced tier, Four Sigmatic Foods leverages regional supply relationships to sustain premium positioning. Ryze Superfoods anchors direct-to-consumer channel control, while MUD/WTR occupies the caffeine-free functional niche. These three exemplify how geographic sourcing, platform ownership, and formulation positioning create defensible market territory.
| Leading Market Players |
|---|
| Four Sigmatic Foods |
| Ryze Superfoods |
| MUD/WTR |
| Rasa |
| Taika |
| Clevr Blends |
| La Republica Superfoods |
| DIRTEA |
| Everyday Dose |
| Others |
Pricing and Supply Chain Analysis
Wildcrafting permit volatility in Siberia and northern Canada determines both the spread between certified-organic and conventional sourcing tiers and the geographic shape of supplier networks. Brands absorbing these input cost swings through subscription bundling rather than spot-market exposure capture superior margin stability.
Pricing Analysis
Subscription replenishment revenue drives lifetime value more than initial unit sales. Three-tier pricing structure across premium liposomal delivery, standard powder blends, and economy instant formats separates bioavailability tiers. Cost compression in the instant segment is intensifying because commodity coffee anchors consumer reference prices. Corporate wellness buyers show least price sensitivity; value-conscious suburban households absorb most pricing pressure.
Supply Chain Analysis
Export-control restrictions on dual-use biotechnology equipment constrain extraction technology flows into emerging supplier regions. Chaga and reishi sourcing concentrates in Russia, Canada, and Finland; ashwagandha root supply centers on India and China. Beta-glucan quantification assays and spray-drying equipment dependencies create single-source vulnerability for precision formulations. Distribution runs through direct-to-consumer platforms and certified-organic specialty networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription attach rates and personalized dosing algorithms expand recurring revenue faster than one-time hardware sales in this beverage category. Service-layer economics now dominate valuation frameworks.
For Market Incumbents: Harden novel food approval portfolios against EFSA retrospective audits by commissioning preemptive human intervention studies. Deepen backward integration into Nordic mushroom cultivation to offset wildcrafting permit restrictions. Channel control through owned fulfillment infrastructure defends against platform dependency risk. For New Entrants and Emerging Players: Establish a beachhead in Germany and Netherlands supermarket channels where mushroom coffee shelf space remains sparse. Target ready-to-drink liquid formats in Amsterdam and Berlin convenience retail as the most penetrable white space. Pursue EU Green Deal carbon accounting certification as a differentiated go-to-market angle. For Investors and Strategic Acquirers: FDA structure-function claim enforcement reshapes the acquisition landscape toward brands with substantiated clinical dossiers. Five-to-ten year viability favors suppliers with dual competencies in coffee roasting and botanical extraction. Watch EFSA beta-glucan health claim rulings as the signal for European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Novel Food Approval Investment | EFSA pre-submission dossiers accelerate European rollout timelines for emerging mushroom extracts. |
| Subscription Infrastructure Buildout | Owned fulfillment platforms reduce customer acquisition cost inflation and data concentration risk. |
| Organic Certification Expansion | EU Green Deal sourcing mandates favor suppliers with documented sustainable procurement networks. |
| Liposomal Delivery Development | Enhanced bioavailability formats command 40-60% price premiums in California and New York wellness markets. |
| Corporate Wellness Partnership | Fortune 500 cafeteria placement creates recurring institutional demand with taxable perk status. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation scientists, regulatory affairs leads at adaptogen coffee brands, specialty retailer category buyers, and corporate wellness program managers; and secondary validation through FDA DSHEA guidance documents, EFSA novel food registers, EU Green Deal sourcing mandates, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Forecast inputs span product type, functional application, end-user channel, and distribution route dimensions across the projection horizon. CAGRs derive from regression analysis against historical adoption curves and regulatory approval timelines. Mushroom extraction standardization advances and corporate wellness penetration rates constitute category-specific forecast variables.
Stress conditions across EFSA approval delays, wildcrafting permit restrictions, and instant coffee commodity price spikes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway durations and botanical standardization trajectories. Material shifts in FDA structure-function enforcement posture or EU novel food evidentiary requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Middle East Coffee Market
Coffee
Portable Espresso Machines Market
Coffee
Coffee Grinder Market
Coffee
India Coffee Roaster Market
Coffee
Espresso Tamper Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Coffee Crystal Market
Coffee
Espresso Coffee Market
Coffee
Italy Coffee Market
Coffee
Roast to Order Coffee Market
Coffee
South America Coffee Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Organic Coffee Market
Coffee
Caffeine Market
Coffee
Instant Coffee Market
Coffee
Vietnam Coffee Market