
 North America Instant Coffee Market | 2026-2036
North America Instant Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
North America Instant Coffee Market Intelligence
Market Context
Multi-source green coffee procurement is pivoting toward vertically integrated supply chains as roasters seek origin traceability. Nestle SA leverages its direct-sourcing networks across Latin American estates to secure arabica volumes. JAB Holding Company sustains competitive cost positions through centralized roasting and private-label scale. Starbucks Corporation differentiates via ethical sourcing certifications and reserve-grade instant offerings.
Technical Definition and Segment Structure
North America instant coffee comprises soluble coffee solids produced through freeze-drying or spray-drying of brewed coffee extract, yielding dry particles that reconstitute in water without brewing equipment. The category serves commercial foodservice, workplace hospitality, and at-home consumption occasions where speed and consistency override ritual preparation. Freeze-dried formats command premium shelf positioning due to superior aroma retention and particle integrity, while spray-dried production anchors mass-market volume through lower unit economics. Pods within packaging type concentrate margin pools through recurring consumable purchases tied to proprietary brewing systems. Foodservice end users drive bulk procurement contracts with specified extraction yields and solubility thresholds.
Regulatory Environment and Outlook
The U.S. FDA governs instant coffee labeling, caffeine disclosure, and manufacturing sanitation under 21 CFR food safety standards, while Health Canada/PMRA oversees pesticide residue limits on imported green beans entering Canadian processing facilities. USDA organic certification and Fair Trade USA standards shape premium product positioning and retail placement access across both countries. Stakeholders must monitor evolving single-use packaging regulations in California and New York that threaten pod-based revenue streams.
Market Dynamics
Workplace hospitality programs are consolidating procurement authority across corporate campuses, compressing vendor rosters and demanding origin-verified arabica with specified solubility thresholds. This buyer concentration is forcing roasters to reconfigure fulfillment infrastructure around direct-to-campus distribution models.
Growth Catalysts
- Single-serve pod systems:Proprietary brewing platforms lock in recurring consumable purchases across U.S. Northeast urban corridors where apartment density supports premium format adoption.
- FDA food labeling updates:Revised disclosure requirements under 21 CFR are accelerating clean-label reformulations that strip artificial carriers from spray-dried formulations.
- Freeze-drying technology:Aroma retention improvements in sublimation equipment are expanding premium shelf placement access for specialty-grade instant offerings.
Market Restraints
- Green coffee price volatility:Brazilian arabica futures swings transmit directly into roaster margins, squeezing mass-market spray-dried producers with limited hedging capacity.
- Single-use packaging regulations:California and New York state-level restrictions threaten pod-based revenue streams by mandating recyclable or compostable alternatives.
- Fresh-brew substitution:Cold-brew concentrate systems in foodservice channels capture speed-sensitive occasions without equipment lock-in.
Strategic Opportunities
- Canadian organic certification:USDA organic equivalency agreements open premium placement in Health Canada-regulated retail channels with lower competitive density than U.S. counterparts.
- Ethical sourcing mandates:Fair Trade USA and Rainforest Alliance certification requirements from institutional buyers create margin pools for verified supply chains.
- Direct-to-workplace channels:Bypassing traditional retail through corporate hospitality contracts reduces slotting fee exposure and builds predictable volume commitments.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise for spray-dried aroma recovery systems concentrates among legacy European equipment suppliers, creating hiring bottlenecks for North American capacity expansion.
- Legacy roasting integration:Merging centralized roasting infrastructure with freeze-drying lines requires coordinated shutdowns that disrupt fulfillment continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Instant Coffee Market |
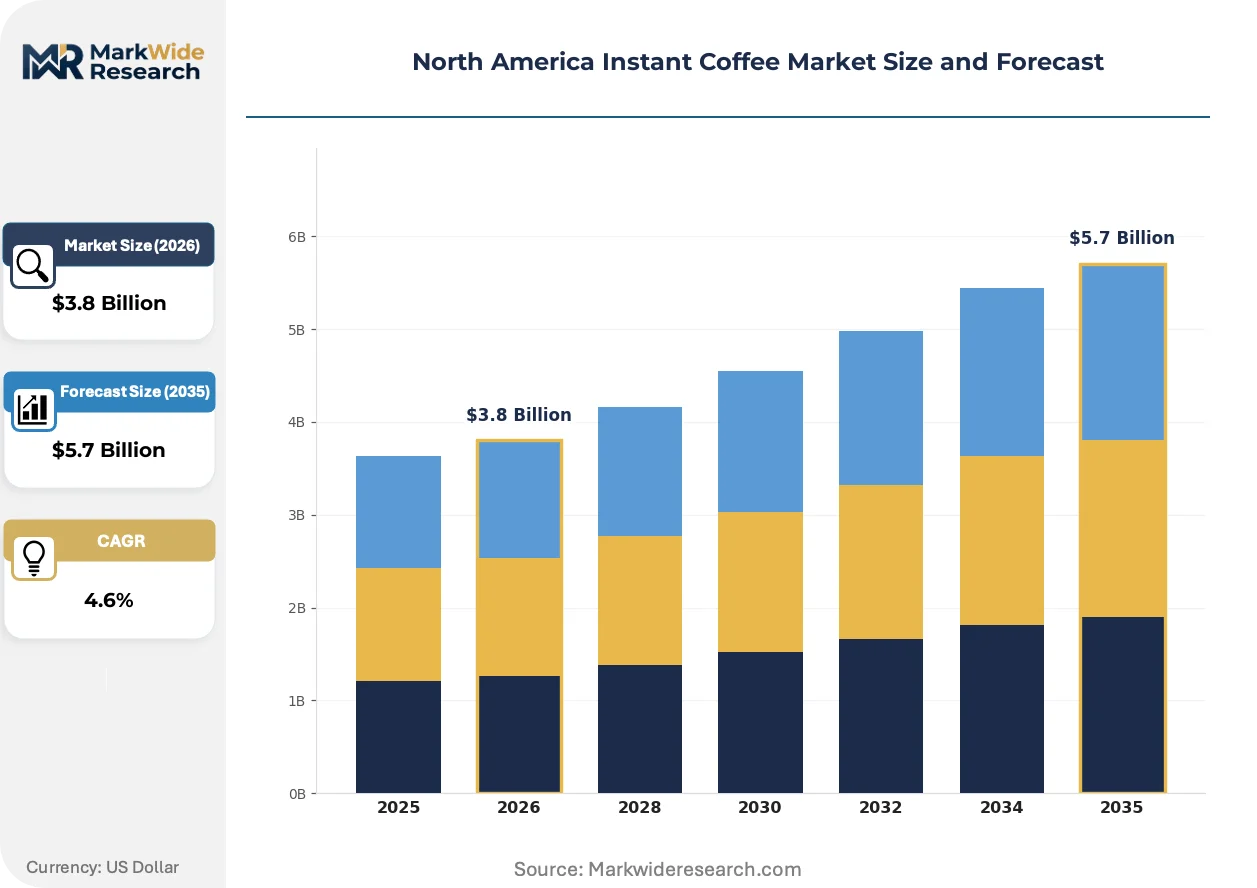
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried, Spray-Dried, Granulated, Liquid End User: Residential, Office, Foodservice, Retail Packaging Type: Pods, Sachets, Jars, Tins Sales Channel: Online, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | The Kraft Heinz Company, JAB Holding Company, Nestle SA, Tim Hortons, Keurig Dr Pepper, Starbucks Corporation, Strauss Group, Dunkin', JDE Peet's, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Instant Coffee Market Strategic Shifts & Innovations
Automation and regulatory disclosure requirements are compressing traditional production timelines while fragmenting procurement authority across new channel structures. These forces are reshaping competitive positioning around speed-to-shelf and supply-chain transparency rather than scale economics alone.
Robotic green-coffee sorting is automating defect detection at receiving terminals, replacing manual cupping protocols that delayed release decisions by days. Mid-size roasters in the U.S. Midwest are adopting these systems fastest, compressing lot-approval cycles from seventy-two hours to four. This velocity is automating just-in-time roasting schedules that minimize working capital tied up in green inventory.
The U.S. FDA's updated 21 CFR food labeling requirements are mandating caffeine content disclosure per serving with standardized formatting. Roasters must reformulate blends or redesign packaging to maintain shelf placement in conventional retail. Premium freeze-dried brands with established clean-label positioning are absorbing compliance costs more easily than value-tier competitors reliant on artificial carriers.
Corporate procurement teams are consolidating coffee program authority under centralized facilities management contracts, displacing decentralized purchasing by individual office managers. Foodservice distributors with campus logistics capabilities are capturing this volume at the expense of retail-centric roasters. This concentration is most visible across tech-sector campuses in Austin, Seattle, and Toronto where amenity competition drives premium format specification.
North America Instant Coffee Market Segmentation
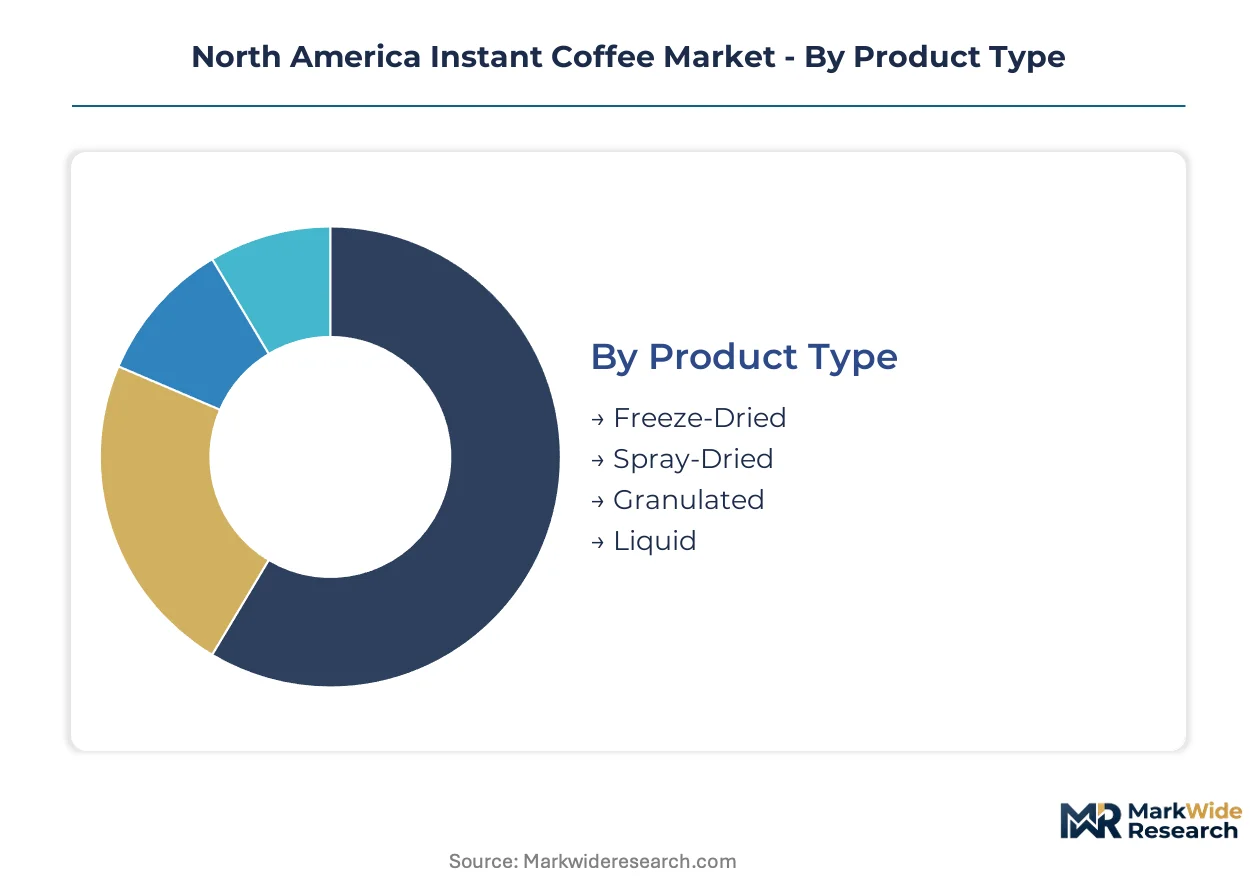
Segmentation in the North America instant coffee market determines which stakeholders bear compliance costs for FDA labeling mandates, organic certification requirements, and state-level packaging regulations. Each category concentrates margin pools and procurement authority differently across freeze-dried premium tiers, workplace hospitality channels, and pod-based recurring revenue streams.
Product Type:
Freeze-dried formats carry heavier USDA organic certification burdens for premium positioning, while spray-dried mass-market production faces FDA scrutiny over artificial carrier disclosures under updated 21 CFR standards.
- Freeze-Dried:Sublimation technology preserves volatile aromatic compounds, yielding porous particles with superior reconstitution speed. Demand concentrates in the U.S. Northeast corridor where urban apartment density supports premium single-serve adoption and ethical sourcing certifications command shelf placement.
- Spray-Dried:Atomized coffee extract dried in hot air streams produces denser, less aromatic granules at lower unit economics. Foodservice bulk procurement contracts in Texas and Florida specify this format for cost-controlled extraction yields in high-volume hospitality settings.
- Granulated:Agglomerated spray-dried particles offer intermediate solubility between powder and freeze-dried formats. Canadian mass-market retail channels favor this grade for price-accessible jarred presentations.
- Liquid:Concentrated coffee extracts requiring refrigeration dominate ready-to-drink hybrid applications. Cold-brew concentrate systems in Seattle and Los Angeles foodservice channels capture speed-sensitive occasions without equipment lock-in.
Spray-Dried sits at the top of the volume ranking, with Freeze-Dried climbing the fastest.
End User:
Cost tier stratification separates premium arabica specifications in corporate hospitality from economy-grade robusta blends in mass residential consumption.
- Residential:At-home consumption spans economy spray-dried jars to premium freeze-dried single-serve formats. Pod system adoption concentrates in dense Northeast urban corridors where counter space constraints favor proprietary brewing platforms.
- Office:Workplace hospitality programs consolidate procurement authority under centralized facilities management contracts. Tech-sector campuses in Austin, Seattle, and Toronto specify origin-verified arabica with solubility thresholds above 95%.
- Foodservice:Commercial kitchens and hospitality chains drive bulk procurement with specified extraction yields. California and New York state regulations threaten single-use pod revenue streams in this channel.
- Retail:Supermarket and specialty store placement demands clean-label positioning compliant with FDA disclosure mandates. Private-label scale advantages concentrate margin pools for centralized roasting operations.
Foodservice anchors current volume leadership, though Office procurement is expanding most quickly.
Packaging Type:
Margin structure varies sharply: recurring consumable purchases through proprietary pod systems generate lifetime value multiples versus one-time jar purchases.
- Pods:Proprietary single-serve cartridges lock users into branded brewing ecosystems. California SB 54 and New York extended producer responsibility laws mandate recyclable or compostable alternatives by specified deadlines.
- Sachets:Individual portion packets dominate foodservice and travel hospitality channels. Canadian hotel chains favor this format for in-room amenity programs with minimal waste handling.
- Jars:Glass and plastic containers anchor mass-market retail shelf presence. FDA 21 CFR labeling requirements mandate caffeine disclosure per serving with standardized formatting.
- Tins:Metal packaging preserves aroma integrity for premium gift and specialty formats. Midwest roasters leverage this presentation for direct-to-consumer holiday seasonal offerings.
Jars maintain volume dominance, while Pods face regulatory headwinds despite steepest historical expansion.
Sales Channel:
Geographic concentration in direct-to-workplace distribution models is displacing traditional retail-centric fulfillment infrastructure.
- Online:Direct-to-consumer platforms enable subscription recurring revenue and origin storytelling. Amazon and specialty coffee portals capture Northeast urban consumers seeking ethical sourcing transparency.
- Supermarkets:Conventional grocery placement requires slotting fee investments and clean-label compliance. USDA organic certification opens premium shelf positioning in Whole Foods and regional chains.
- Convenience Stores:Immediate consumption occasions favor single-serve sachets and ready-to-drink formats. Interstate highway corridors in Texas and Florida support high-velocity turnover.
- Specialty Stores:Curated retail environments emphasize reserve-grade instant and equipment bundling. Toronto and Vancouver independent roasters leverage this channel for premium freeze-dried introductions.
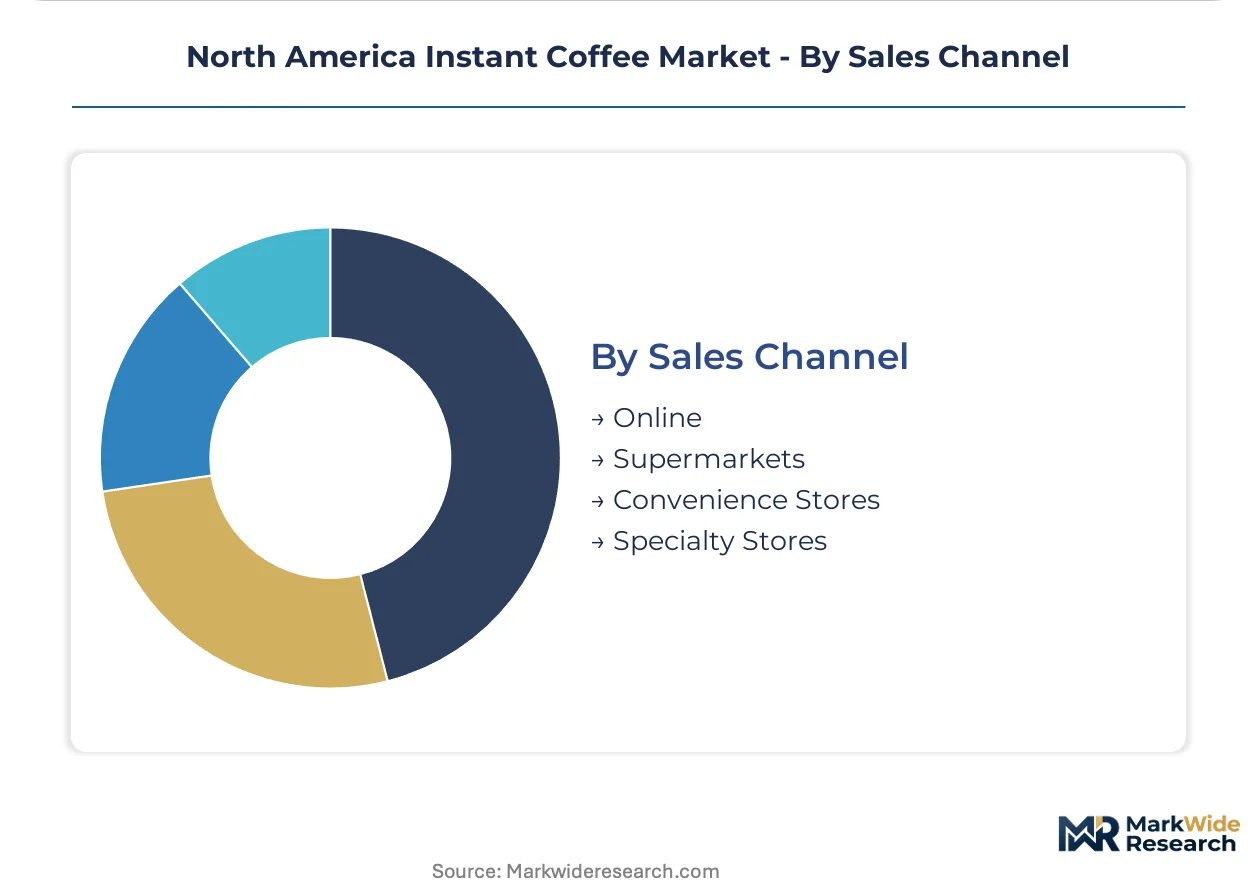
Supermarkets retain volume leadership, though Online subscription models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Northeast corridor anchors North American instant coffee demand through dense urban apartment configurations that favor single-serve pod adoption and premium freeze-dried formats.
United States
Workplace hospitality programs across Austin, Seattle, and Toronto tech campuses consolidate procurement under centralized facilities contracts specifying origin-verified arabica. The FDA governs instant coffee labeling and caffeine disclosure under 21 CFR food safety standards. New York City and Boston metropolitan clusters drive premium single-serve adoption where counter space constraints favor proprietary brewing ecosystems.
Canada
Health Canada and PMRA oversee pesticide residue limits on imported green beans entering Canadian processing facilities. USDA organic equivalency agreements open premium retail placement with lower competitive density than U.S. counterparts. Toronto and Vancouver independent roasters leverage specialty store channels for reserve-grade freeze-dried introductions targeting ethical sourcing transparency.
Mexico
Commercial foodservice chains in Mexico City and Guadalajara drive bulk spray-dried procurement for cost-controlled hospitality operations. The country's national food safety regulator mandates manufacturing sanitation standards for soluble coffee imports. Northern border states concentrate cross-border distribution infrastructure serving U.S. Southwest retail and foodservice channels.
North America Instant Coffee Market Key Industry Players
Global majors compete with regional champions across procurement authority and channel access dimensions in a moderately consolidated structure. Three archetypes dominate: multinational food conglomerates with direct-sourcing networks, coffee-specialist holding companies with centralized roasting scale, and quick-service restaurant chains with captive retail distribution. Competitive moves center on backward integration into green coffee supply chains and strategic consolidation of workplace hospitality contracts.
Within the multinational conglomerate tier, Nestle SA and The Kraft Heinz Company exemplify scale-driven positions leveraging global procurement infrastructure. JAB Holding Company occupies a specialist holding company archetype alongside Keurig Dr Pepper, both representing concentrated roasting and private-label manufacturing capabilities. Starbucks Corporation anchors the premium branded vector with ethical sourcing certification programs.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| JAB Holding Company |
| Nestle SA |
| Tim Hortons |
| Keurig Dr Pepper |
| Starbucks Corporation |
| Strauss Group |
| Dunkin' |
| JDE Peet's |
| Others |
Cost & Logistics Intelligence
Freeze-dried premium certification ladders diverge sharply from spray-dried commodity tiers, with USDA organic and Fair Trade USA credentials commanding shelf placement premiums in Northeast urban corridors while mass-market spray-dried production competes on extraction yield efficiency in Texas and Florida foodservice contracts. This bifurcation concentrates procurement authority among roasters with captive Latin American estate relationships for premium arabica, while spray-dried producers absorb Brazilian futures volatility through centralized roasting scale.
Pricing Analysis
Green coffee futures pass-through from Brazilian arabica exchanges transmits directly into roaster cost structures, squeezing mass-market spray-dried producers with limited hedging capacity against price swings. Three-tier pricing structure across premium freeze-dried, standard granulated, and economy spray-dried levels differentiates on certification grade and origin traceability. Pricing pressure stems from single-use packaging compliance costs in California and New York. Foodservice bulk buyers exhibit highest price sensitivity, while corporate hospitality programs prioritize ethical sourcing transparency over unit economics.
Supply Chain Analysis
Reverse-logistics flows for pod-based systems face mounting complexity as California SB 54 and New York extended producer responsibility laws mandate recyclable or compostable cartridge alternatives with specified collection infrastructure. Green coffee supply concentrates in Brazil, Colombia, and Vietnam, with arabica from Latin American estates feeding premium freeze-dried lines and Vietnamese robusta anchoring spray-dried mass production. Soluble coffee manufacturing depends on freeze-drying sublimation equipment and spray-drying atomization systems concentrated among European suppliers. Single-source vulnerability in flavor chemist expertise for aroma recovery systems creates hiring bottlenecks. Distribution runs through foodservice distributors with campus logistics capabilities and direct-to-workplace channels bypassing retail slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America instant coffee market functions as a stable compounder, with workplace hospitality program consolidation generating predictable volume commitments that insulate premium roasters from retail cycle volatility.
For Market Incumbents: Deepen backward integration into Latin American estate networks to secure origin-verified arabica volumes as Brazilian futures volatility intensifies margin pressure. Lock in corporate hospitality contracts through direct-to-campus distribution infrastructure that displaces retail-centric competitors. Prioritize freeze-drying capacity expansion to capture premium shelf placement as FDA clean-label mandates accelerate artificial carrier elimination from spray-dried formulations. For New Entrants and Emerging Players: Capture Canadian organic certification opportunities where USDA equivalency agreements open premium retail channels with lower competitive density than U.S. counterparts. Target Toronto and Vancouver specialty store placements for reserve-grade freeze-dried introductions emphasizing ethical sourcing transparency. Leverage direct-to-consumer subscription platforms with origin storytelling to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size roasters lack captive green coffee supply and struggle to fulfill corporate hospitality solubility specifications. The five-to-ten year viability window favors vertically integrated specialists with freeze-drying technology and direct-sourcing networks over pure-play brand aggregators. Monitor California and New York single-use packaging enforcement timelines as inflection indicators for pod-based revenue stream disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Estate Networks | Direct-sourcing relationships with Colombian and Brazilian growers secure origin traceability for premium freeze-dried positioning. |
| Freeze-Drying Capacity Expansion | Sublimation equipment investments capture FDA clean-label compliance advantages as artificial carrier scrutiny intensifies. |
| Direct-to-Workplace Channel Development | Campus logistics capabilities bypass retail slotting fees and build predictable volume commitments from corporate hospitality programs. |
| Canadian Organic Certification Pursuit | USDA equivalency agreements unlock premium placement in Health Canada-regulated channels with lower competitive density. |
| Compostable Pod Format Transition | California SB 54 compliance preserves pod-based revenue streams as extended producer responsibility mandates tighten. |
Research Approach
Bottom-up workplace hospitality and residential consumption modeling reconciled against top-down green coffee import and roasting capacity tracking forms the analytical core of this study. Primary interviews with brand managers at multinational roasters, category buyers at foodservice distributors, facilities management procurement leads at tech-sector campuses, and flavor formulation chemists combined with secondary validation from FDA 21 CFR filings, USDA organic certification databases, Brazilian arabica futures exchange data, and Health Canada pesticide residue monitoring records. Triangulation across these sources ensures segmentation integrity across freeze-dried, spray-dried, granulated, and liquid product tiers.
Input-output matrices map green coffee procurement volumes through processing technology types to end-use channel consumption across the projection horizon. Segmentation dimensions modeled include product type, end user category, packaging format, and sales channel, with geographic regulatory clusters capturing FDA, Health Canada/PMRA, and state-level packaging compliance variations. CAGRs derive from trend extrapolation of workplace hospitality contract expansion, single-serve pod adoption velocity in Northeast urban corridors, and clean-label reformulation timelines. Forecast inputs incorporate Brazilian arabica futures volatility patterns and corporate procurement consolidation trajectories.
Underlying measurement precision varies by segment; workplace hospitality contract volumes carry tighter precision than residential pod adoption forecasts given procurement centralization visibility. Projections reflect assumptions regarding FDA enforcement timelines, state packaging regulation implementation, and green coffee price stability that could revise outcomes. Practitioners should monitor California SB 54 compliance deadlines, Brazilian climate conditions affecting arabica harvests, and corporate return-to-office policies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Cherry Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Instant Coffee Market
Coffee
Sparkling Coffee Market
Coffee
Encapsulated Caffeine Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
Green Coffee Bean Extract Market
Coffee
Smart Coffee Maker Market
Coffee
UK Coffee Roaster Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Coffee Fruit Extract Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market