
 Ready to Drink (RTD) Tea and Coffee Market | 2026-2036
Ready to Drink (RTD) Tea and Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Drink (RTD) Tea and Coffee Market Insights
Subscription-based replenishment models is realigning how RTD tea and coffee reaches repeat buyers, shifting volume from impulse single-serve to predictable household inventory cycles. Nestlé S.A. leverages its Nespresso and Nescafé direct-to-consumer infrastructure to anchor recurring revenue streams in European and North American markets. Starbucks Corporation competes through its Rewards-integrated mobile ordering ecosystem, which controls pickup timing and reduces third-party platform dependency. Tingyi (Cayman Islands) Holding Corp. dominates Greater China's mass-market bottled tea segment through deep traditional retail penetration and region-specific flavor portfolios.
Ready to drink tea and coffee denotes commercially prepared, shelf-stable or refrigerated beverages brewed from Camellia sinensis leaves or Coffea arabica/robusta beans, then formulated with water, sweeteners, dairy or plant-based milks, and stabilizers before aseptic or hot-fill processing into sealed containers. These products serve the need for portable, consistent caffeine and polyphenol delivery without equipment, preparation time, or trained barista labor. The tea segment sustains volume leadership across Asian markets where unsweetened green and oolong variants occupy everyday consumption occasions, while the coffee segment records faster growth in North American and European convenience channels as cold brew and nitro-infused formats expand. Bottles command the packaging category due to resealability and premium perception, though aluminum cans gain share in on-premise and event-oriented foodservice channels where portability and chill speed matter.
The FDA governs ingredient safety, caffeine disclosure, and nutrition fact panel accuracy for US-bound RTD beverages, while the EU's F-Gas Regulation and packaging waste directives constrain refrigerant choices and mandate recyclability targets for European distribution. China's SAMR enforces GB standards for food contact materials and additive permissions, creating compliance differentiation between export-oriented and domestic-only producers. Stakeholders must monitor how diverging sugar taxation regimes and emerging extended producer responsibility laws reshape formulation investment and packaging material selection across their priority markets.
Market Dynamics
Subscription-based replenishment models are consolidating repeat purchase behavior into predictable inventory cycles, compressing traditional impulse-driven retail velocity and forcing reformulation of distribution economics across metropolitan retail corridors.
Growth Catalysts
- Urban convenience infrastructure:China's tier-one cities and Japan's vending-machine networks create high-frequency purchase touchpoints for cold-brew and unsweetened variants. Metro density supports refrigerated last-mile logistics that sustain product integrity.
- Formulation transparency mandates:The FDA's updated nutrition labeling requirements and China's GB standards for food contact materials accelerate clean-label investment. Compliance differentiation rewards early adopters with premium shelf positioning.
- Plant-based milk integration:Oat and almond protein stabilization technologies enable dairy-free RTD coffee expansion. Barista-quality foam replication through enzymatic processing opens lactose-intolerant consumer segments.
Market Restraints
- Input cost volatility:Arabica coffee futures and tea leaf auction prices fluctuate with Brazilian frost cycles and Kenyan rainfall patterns. Margin compression forces hedging complexity for mid-scale processors.
- Supply concentration risk:Aseptic carton and aluminum can sourcing clusters in Southeast Asian manufacturing hubs. Geopolitical friction or port congestion disrupts packaging availability for export-oriented brands.
- Refrigeration infrastructure gaps:Cold-chain penetration remains uneven across India's tier-two cities and Indonesia's archipelago geography. Ambient-stable formulations sacrifice taste perception for distribution reach.
Strategic Opportunities
- Functional ingredient convergence:Adaptogenic mushrooms and nootropic amino acids merge with RTD coffee for cognitive positioning. Early entrants capture wellness-oriented professional demographics in urban coworking channels.
- Extended producer responsibility tailwinds:The EU's packaging waste directives and deposit-return schemes incentivize rPET and aluminum loop systems. Compliance-ready operators secure retail listing priority in European convenience chains.
- Direct-to-consumer channel innovation:Micro-fulfillment centers and subscription apps bypass traditional retail slotting fees. Cold-brew concentrate formats reduce shipping weight and enable customization of dilution ratios.
Industry Challenges
- Flavor stability expertise scarcity:Retaining volatile aromatic compounds through ultra-high-temperature processing requires specialized food chemistry talent. Competition with pharmaceutical and fragrance sectors limits recruitment pipelines.
- Multi-jurisdiction compliance timelines:Synchronizing FDA caffeine disclosure, EU F-Gas refrigeration standards, and China's additive permission lists extends product launch windows. Parallel regulatory submissions strain smaller R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Drink (RTD) Tea and Coffee Market |
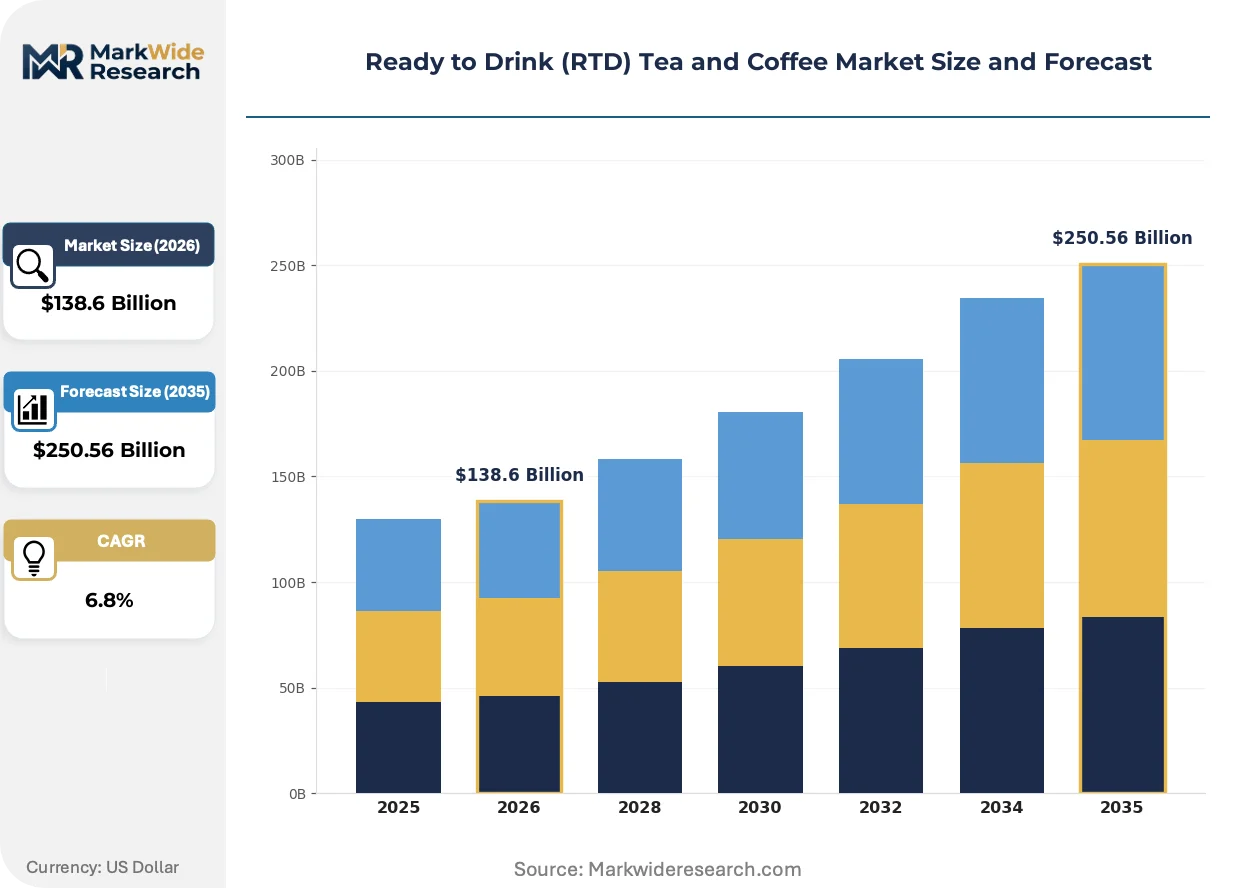
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea, Coffee, Mixed, Flavored Packaging Type: Bottles, Cans, Boxes, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online, Foodservice Price Tier: Premium, Mid-range, Economy, Discount |
| Companies Covered | Nestlé S.A., The Coca-Cola Company, PepsiCo, Inc., Suntory Holdings Ltd., Unilever NV, Asahi Group Holdings Ltd., Starbucks Corporation, Keurig Dr Pepper, Inc., Tingyi (Cayman Islands) Holding Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Drink (RTD) Tea and Coffee Market Trends and Innovations
Cold-brew extraction and nitrogen infusion technologies are elevating sensory profiles while aseptic processing advances extend ambient shelf life, reshaping competitive differentiation around texture and convenience rather than price alone.
High-pressure cold-brew systems is unifying extraction efficiency with flavor preservation in RTD coffee manufacturing. Specialty coffee roasters and contract manufacturers adopt these systems to scale batch consistency without thermal degradation. The technology is unifying small-batch artisan credibility with national distribution feasibility, compressing the premium-mass-market gap.
The EU's F-Gas Regulation constrains hydrofluorocarbon refrigerant choices for European RTD cold-chain logistics. Beverage distributors face retrofitting costs for transport refrigeration units and retail display cases. Northern European markets with stricter enforcement timelines accelerate adoption of CO2 transcritical systems, creating compliance-driven equipment upgrade cycles.
Mobile-integrated replenishment apps are displacing spontaneous convenience-store purchases with scheduled subscription deliveries. Young professionals in Seoul, Shanghai, and San Francisco preload consumption calendars, reducing brand switching at point-of-sale. This behavioral lock-in concentrates volume with platforms that control pickup timing and reduce third-party delivery dependency.
Ready to Drink (RTD) Tea and Coffee Market Segmentation
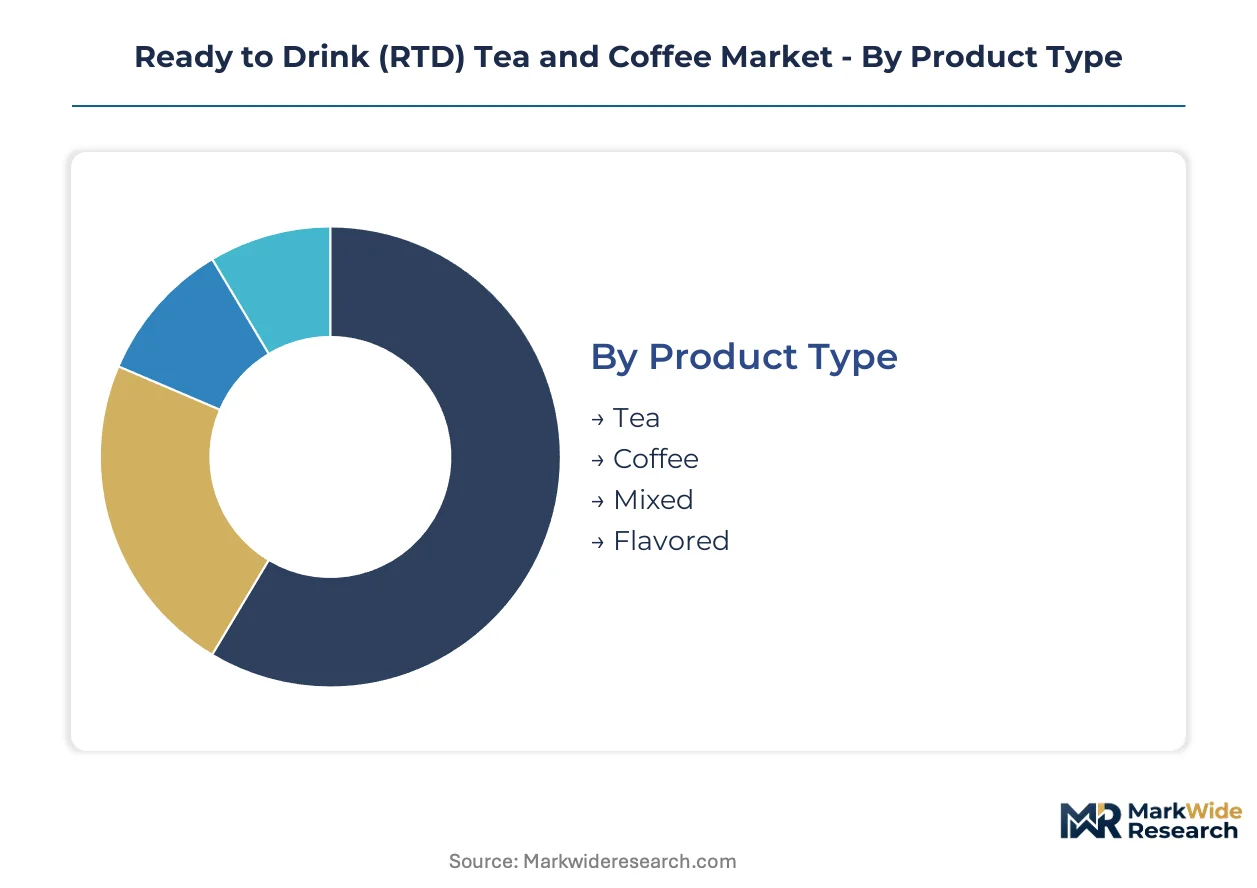
RTD tea and coffee segmentation reveals how formulation chemistry, packaging engineering, and channel economics fragment demand across distinct consumption occasions. Manufacturers optimize production lines and inventory deployment by matching product specifications to purchasing contexts rather than treating the category as uniform.
Product Type:
Caffeine source and extraction method define formulation investment, shelf-stability requirements, and regional taste preference alignment.
- Tea:Camellia sinensis extracts processed through hot-fill or aseptic methods dominate Asian metropolitan markets where unsweetened green and oolong variants sustain daily consumption rituals. China's tier-one cities and Japan's vending corridors concentrate volume for heritage brands with established leaf sourcing relationships.
- Coffee:Cold-brew and nitro-infused arabica/robusta formulations command North American and European convenience channels, with high-pressure extraction systems preserving volatile aromatic compounds through ambient distribution. Barista-quality foam replication via enzymatic processing opens lactose-intolerant segments.
- Mixed:Blended tea-coffee hybrids target experimental consumers seeking novel caffeine delivery without single-origin commitment.
- Flavored:Fruit, spice, and botanical infusions capture younger demographics in Southeast Asian retail corridors.
Mature deployment sits with Tea. Newer deployment is concentrated in Coffee.
Packaging Type:
Material science and logistics economics determine shelf positioning, chill speed, and circular economy compliance trajectories.
- Bottles:Resealable PET and glass containers sustain premium perception in supermarket and convenience retail, with rPET integration advancing under EU packaging waste directives. Deposit-return schemes in Northern European markets accelerate loop system adoption.
- Cans:Aluminum formats gain foodservice and event-channel share where portability and rapid chilling outweigh resealability needs. Southeast Asian manufacturing hub concentration creates supply vulnerability during port congestion.
- Boxes:Aseptic cartons enable ambient-stable distribution across India's tier-two cities and Indonesia's archipelago geographies where cold-chain gaps persist.
- Pouches:Flexible formats reduce shipping weight for direct-to-consumer concentrate deliveries and subscription replenishment models.
Volume leadership rests with Bottles. Fastest share gains are occurring in Cans.
Distribution Channel:
Purchase context and inventory velocity shape margin structures and brand switching exposure.
- Supermarkets:Multi-SKU shelf sets sustain household stock-up behavior with promotional pricing cycles. Greater China's traditional retail penetration rewards deep distribution networks.
- Convenience Stores:Impulse-driven single-serve velocity concentrates in urban corridors with refrigerated last-mile logistics. Japan's vending-machine ecosystem exemplifies high-frequency touchpoint density.
- Online:Subscription apps and micro-fulfillment centers bypass slotting fees while enabling customization of dilution ratios and delivery timing.
- Foodservice:On-premise and event-oriented channels favor aluminum can formats with rapid chill requirements.
Established volume flows through Supermarkets. Channel innovation is concentrating in Online.
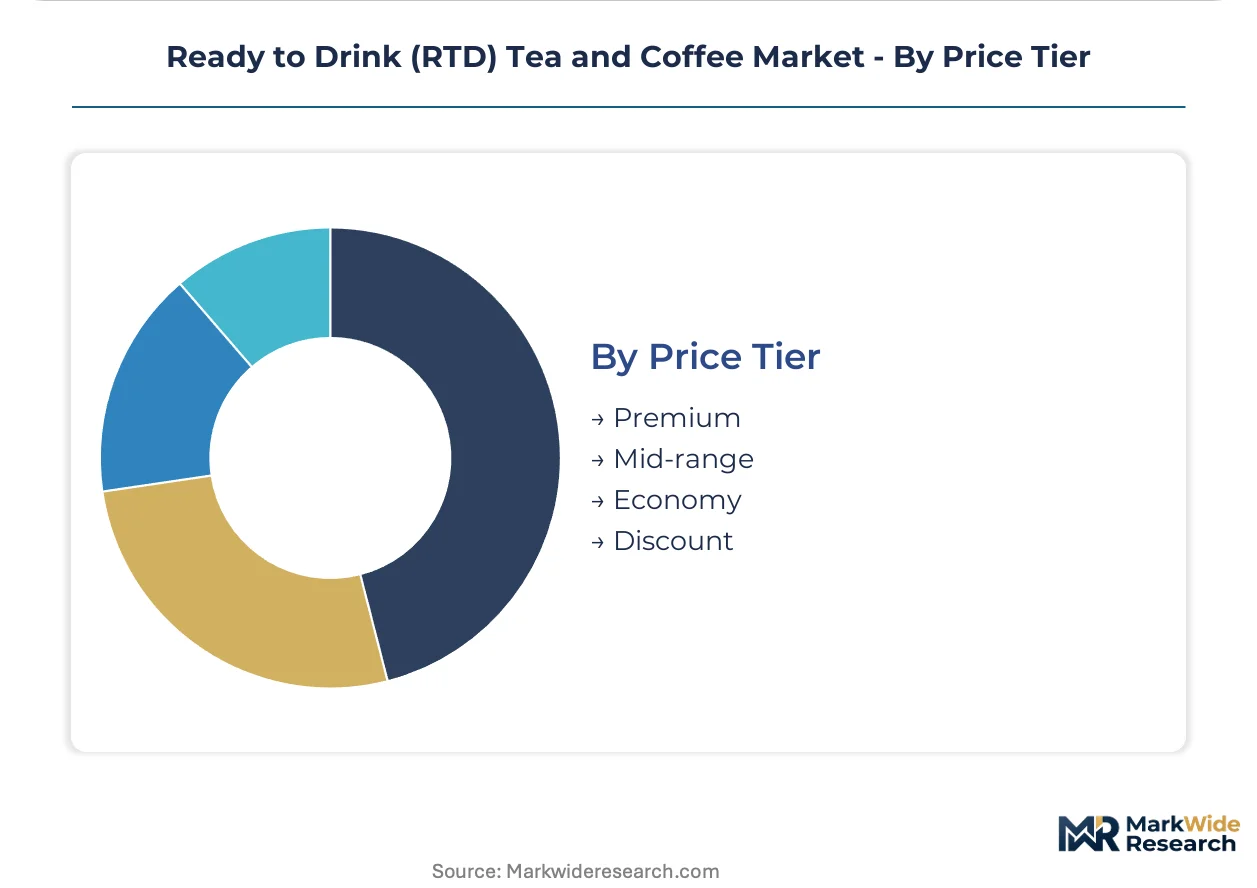
Price Tier:
Ingredient provenance, processing complexity, and certification status stratify consumer access and margin capture.
- Premium:Single-origin beans, ceremonial-grade matcha, and organic certifications command shelf positioning in specialty retail and direct-to-consumer channels. Clean-label compliance with FDA nutrition disclosure and China's GB standards creates differentiation.
- Mid-range:Blended formulations with functional ingredient additions target wellness-oriented professionals in urban coworking channels.
- Economy:Mass-market bottled tea dominates Greater China through deep traditional retail penetration and region-specific flavor portfolios.
- Discount:Price-competitive ambient-stable formats sacrifice taste perception for distribution reach in cold-chain-deficient geographies.
Revenue concentration aligns with Premium. Volume scale sits with Economy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta corridor anchors cold-chain distribution for premium RTD coffee, with refrigerated last-mile networks enabling nitro-infused formats to reach convenience shelves within four hours of production.
United States
Seattle and Los Angeles metro areas drive cold-brew adoption through specialty retail penetration. FDA nutrition labeling mandates accelerate clean-label reformulation timelines. California's Central Valley hosts aseptic processing clusters where contract manufacturers stabilize oat-protein emulsions for dairy-free lines.
China
Tier-one cities of Beijing, Shanghai, and Shenzhen concentrate unsweetened tea consumption in vending-machine corridors. SAMR enforces GB standards for food contact materials, creating compliance differentiation between export and domestic producers. Guangdong province houses aluminum can manufacturing hubs serving Southeast Asian export markets.
Japan
Tokyo and Osaka metropolitan areas sustain the world's highest vending-machine density for RTD beverages. METI efficiency standards for refrigeration equipment shape cold-chain infrastructure investment. Kyushu region's tea-growing prefectures supply ceremonial-grade matcha for premium bottling operations.
Germany
Berlin and Hamburg anchor European demand for organic-certified RTD coffee through specialty retail channels. EU F-Gas Regulation constrains hydrofluorocarbon refrigerant choices, accelerating CO2 transcritical system adoption. Bavaria's dairy cooperatives supply protein-stabilization expertise for barista-quality foam replication.
India
Mumbai and Delhi-NCR demonstrate fastest adoption of ambient-stable chai formulations where cold-chain gaps persist. FSSAI additive permissions and labeling requirements extend product launch windows for multinational entrants. Karnataka's coffee-growing regions supply arabica beans for domestic roasting and extraction operations.
Ready to Drink (RTD) Tea and Coffee Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the RTD tea and coffee landscape. Integrated beverage conglomerates with captive bottling networks face pressure from specialty roasters outsourcing aseptic processing to contract manufacturers. Three archetypes dominate: multinational CPG platforms with deep retail distribution, Asian heritage tea houses leveraging leaf-sourcing relationships, and coffee-forward brands built on direct-to-consumer subscription infrastructure. Competitive intensity concentrates on portfolio diversification into functional ingredients and geographic expansion through regional formulation tailoring.
Within the multinational platform tier, Nestlé S.A. and The Coca-Cola Company exemplify scale-driven market presence through established cold-chain partnerships and retail slotting leverage. Tingyi (Cayman Islands) Holding Corp. occupies a distinct position as a Greater China-focused operator with deep traditional retail penetration. Starbucks Corporation represents the coffee-specialist archetype, anchoring recurring revenue through mobile-integrated replenishment ecosystems rather than third-party retail dependency.
| Leading Market Players |
|---|
| Nestlé S.A. |
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Suntory Holdings Ltd. |
| Unilever NV |
| Asahi Group Holdings Ltd. |
| Starbucks Corporation |
| Keurig Dr Pepper, Inc. |
| Tingyi (Cayman Islands) Holding Corp. |
| Others |
Pricing and Supply Chain Analysis
Subscription-heavy metropolitan households concentrate purchasing power in RTD tea and coffee, locking volume into predictable replenishment cycles that compress spot-market pricing volatility and reward contract-based supplier relationships over transactional procurement.
Pricing Analysis
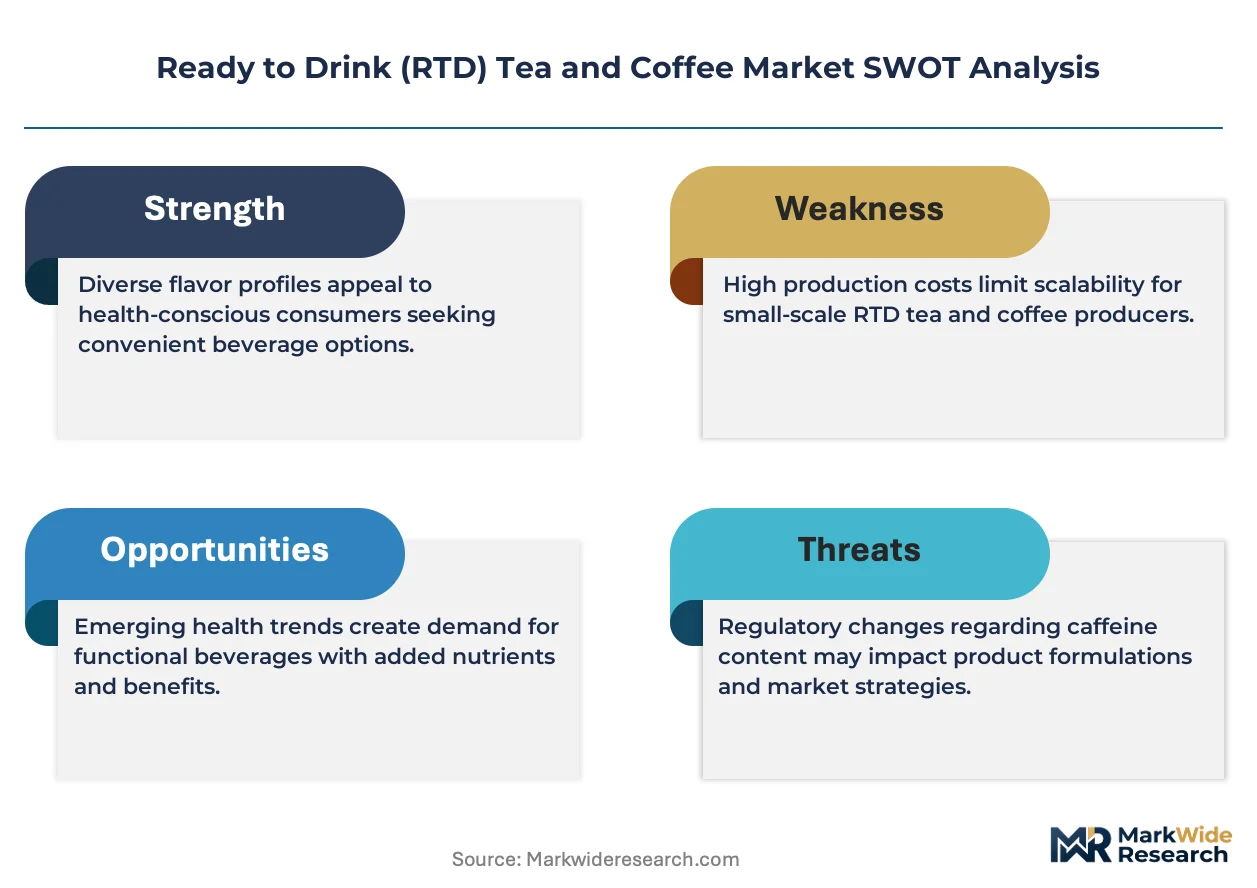
Value-based pricing anchored to convenience outcomes and caffeine delivery reliability dominates premium RTD coffee tiers, where subscription platforms capture recurring revenue through timed replenishment guarantees. Certification grade under FDA nutrition disclosure and China's GB standards creates tier separation, while brand premium and volume scale differentiate mass-market bottled tea. Pricing pressure stems from Arabica futures volatility and aseptic packaging cost spikes, compressing margins for mid-scale processors. Economy-tier buyers exhibit highest price sensitivity, while premium subscription subscribers prioritize consistency over per-unit cost.
Supply Chain Analysis
Local-content mandates in China's GB standards for food contact materials and the EU's packaging waste directives reshape sourcing toward domestic rPET and aluminum loop systems. Raw material flows draw from Brazil and Colombia for arabica beans, Kenya and Sri Lanka for tea leaf auctions, and Southeast Asian hubs for aseptic carton and can manufacturing. Single-source vulnerability concentrates in aluminum can supply clusters around Guangdong province and Thai manufacturing zones. Distribution runs through refrigerated last-mile networks in tier-one cities and ambient-stable corridors in cold-chain-deficient geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RTD tea and coffee sits in a technology-transition phase where high-pressure cold-brew extraction and nitrogen infusion systems displace conventional hot-fill processing, rewarding capital investment in flavor-preservation infrastructure.
For Market Incumbents: Deploy captive bottling network expansion to defend against contract-manufacturing commoditization. Nestlé and Coca-Cola should deepen aseptic processing partnerships in California and Bavaria to secure oat-protein stabilization capacity. Counter Starbucks' subscription lock-in by accelerating mobile-integrated replenishment app development with pickup-timing control.
For New Entrants and Emerging Players: Wellness-oriented professionals in urban coworking channels represent an underserved buyer archetype ripe for adaptogenic and nootropic-functional RTD coffee launches. India's tier-two cities offer penetrable white space for ambient-stable chai formulations where cold-chain gaps persist. Pursue direct-to-consumer concentrate formats with customizable dilution ratios to bypass retail slotting fees.
For Investors and Strategic Acquirers: The window for entry favors specialty roasters with high-pressure extraction technology and established leaf-sourcing relationships over asset-light brand designers. Long-term viability hinges on compliance-ready operators with rPET loop systems and FDA-EU-China regulatory synchronization capabilities. Watch for inflection when deposit-return scheme adoption in Northern European markets accelerates aluminum loop investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Brew Extraction Scale-Up | High-pressure systems from California contract manufacturers preserve volatile aromatics for national distribution feasibility. |
| Subscription Platform Integration | Mobile-integrated replenishment apps in Seoul and San Francisco reduce third-party delivery dependency and brand switching. |
| rPET Loop System Adoption | EU packaging waste directives and deposit-return schemes in Germany prioritize compliance-ready operators for retail listings. |
| Functional Ingredient Convergence | Adaptogenic mushrooms and nootropic amino acids target wellness professionals in urban coworking channels. |
| Regional Formulation Tailoring | Guangdong can manufacturing hubs and Kyushu matcha sourcing enable Greater China and Japan flavor portfolio customization. |
Research Methodology
Document review covered FDA nutrition labeling guidance, EMA food contact material regulations, and China's SAMR GB standards, complemented by interviews with RTD beverage brand managers, category buyers at convenience chains, aseptic processing plant engineers, and cold-chain logistics operators. Secondary validation drew from Nielsen retail audit data, customs import records for coffee and tea leaf shipments, and SEC filings of integrated beverage conglomerates. Bottom-up volume modeling triangulated against top-down category spending estimates.
Market size outputs across the projection horizon reflect segment-level modeling by caffeine source, packaging material, distribution channel, and price tier. CAGRs derived from historical volume trajectories and penetration rate assumptions for subscription replenishment and cold-brew formats. Forecast inputs incorporated Arabica futures volatility patterns, aseptic carton supply lead times, and regulatory compliance timeline differentials between export-oriented and domestic-only producers.
Revisions become necessary when Brazilian frost cycles or Kenyan rainfall disruptions spike input costs, when EU F-Gas Regulation enforcement accelerates refrigeration retrofit requirements, or when China's SAMR tightens additive permission lists. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Global Nespresso Capsules Market
Coffee
Office Coffee Service (OCS) Market
Coffee
GCC Instant Coffee Market
Coffee
Espresso Tamper Market
Coffee
Encapsulated Caffeine Market
Coffee
United States Coffee Pods and Capsules Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Out-Of-Home Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Coffee Cherry Market
Coffee
Australia Coffee Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Europe Coffee Market
Coffee
Canned Coffee Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Reusable Coffee Cup Market