
 Middle East Coffee Market | 2026-2036
Middle East Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Coffee Market Insights
The divergence between premium single-origin offerings and commodity-grade bulk supply is realigning procurement strategies across the Middle East. Starbucks Corporation leverages its licensed store network to dominate high-traffic retail corridors in Dubai and Riyadh. Nestlé SA anchors the instant and capsule segments through deep grocery distribution. Saudi Coffee Company controls domestic sourcing pipelines as the kingdom cultivates local arabica production in the Asir highlands.
Middle East coffee encompasses roasted and unroasted seeds of Coffea arabica and Coffea canephora species, typically processed through wet or dry milling to achieve moisture content below 12 percent prior to export or local roasting for beverage preparation. Arabica commands premium positioning in specialty cafes and hospitality channels across the Gulf, while Robusta underpins cost-competitive instant formulations and commercial espresso blends. Distribution through supermarkets sustains volume turnover for mainstream brands, whereas specialty stores capture margin-rich consumers seeking traceable provenance and small-batch roasting.
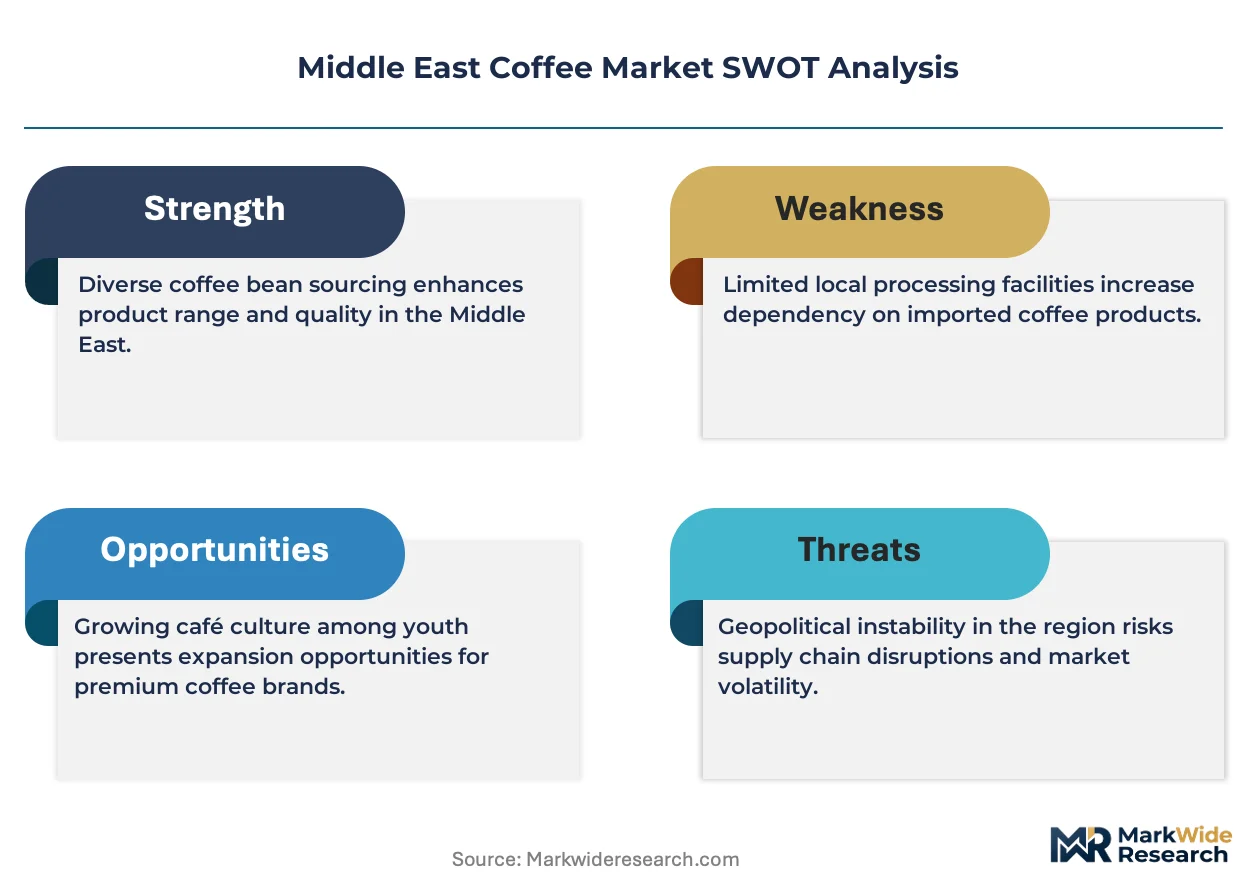
SFDA import regulations mandate detailed origin documentation and residue testing for roasted coffee entering Saudi Arabia, while UAE Ministry of Climate Change and Environment enforces halal certification and labeling standards across Emirates retail channels. These frameworks elevate compliance costs for smaller traders while rewarding vertically integrated operators with in-house quality laboratories. Stakeholders must monitor evolving domestic roasting capacity in Saudi Arabia and shifting consumer willingness to pay for provenance-verified supply as local production scales.
Market Dynamics
The Saudi Food and Drug Authority's tightening traceability mandates for imported roasted beans are compressing procurement timelines and forcing distributors to rebuild documentation systems from origin to retail shelf.
Growth Catalysts
- SFDA Documentation Mandates:Saudi Arabia's residue testing and origin documentation requirements are accelerating quality infrastructure investments among licensed importers.
- Specialty Café Density:Hospitality chains in Riyadh and Dubai are expanding single-origin programs, pulling premium arabica through direct-trade channels.
- Domestic Cultivation:Asir highlands arabica production is reducing import dependency and creating localized supply alternatives for roasters.
Market Restraints
- Green Bean Price Volatility:Brazilian and Vietnamese arabica futures swings transmit directly to Middle East roasting economics.
- Import Concentration Risk:Jeddah and Jebel Ali ports handle the majority of regional coffee volume, creating single-point vulnerability.
- Halal Certification Friction:UAE Ministry of Climate Change and Environment labeling standards add processing delays for European and Latin American suppliers.
Strategic Opportunities
- Direct-to-Consumer Subscription:Roasters in Dubai are bypassing traditional retail through mobile-first delivery platforms targeting home brewing segments.
- Traceability Technology Convergence:Blockchain verification combined with IoT moisture sensors is enabling real-time provenance claims for hospitality buyers.
- Underpenetrated Kuwait Market:Café density per capita remains half the Riyadh level, presenting whitespace for specialty format expansion.
Industry Challenges
- Q-Grader Talent Scarcity:Licensed cupping professionals are concentrated in Dubai and Riyadh, constraining quality control scaling in secondary cities.
- Roasting Equipment Lead Times:German and Italian manufacturer backlogs extend to 14 months, delaying Saudi domestic capacity buildout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Coffee Market |
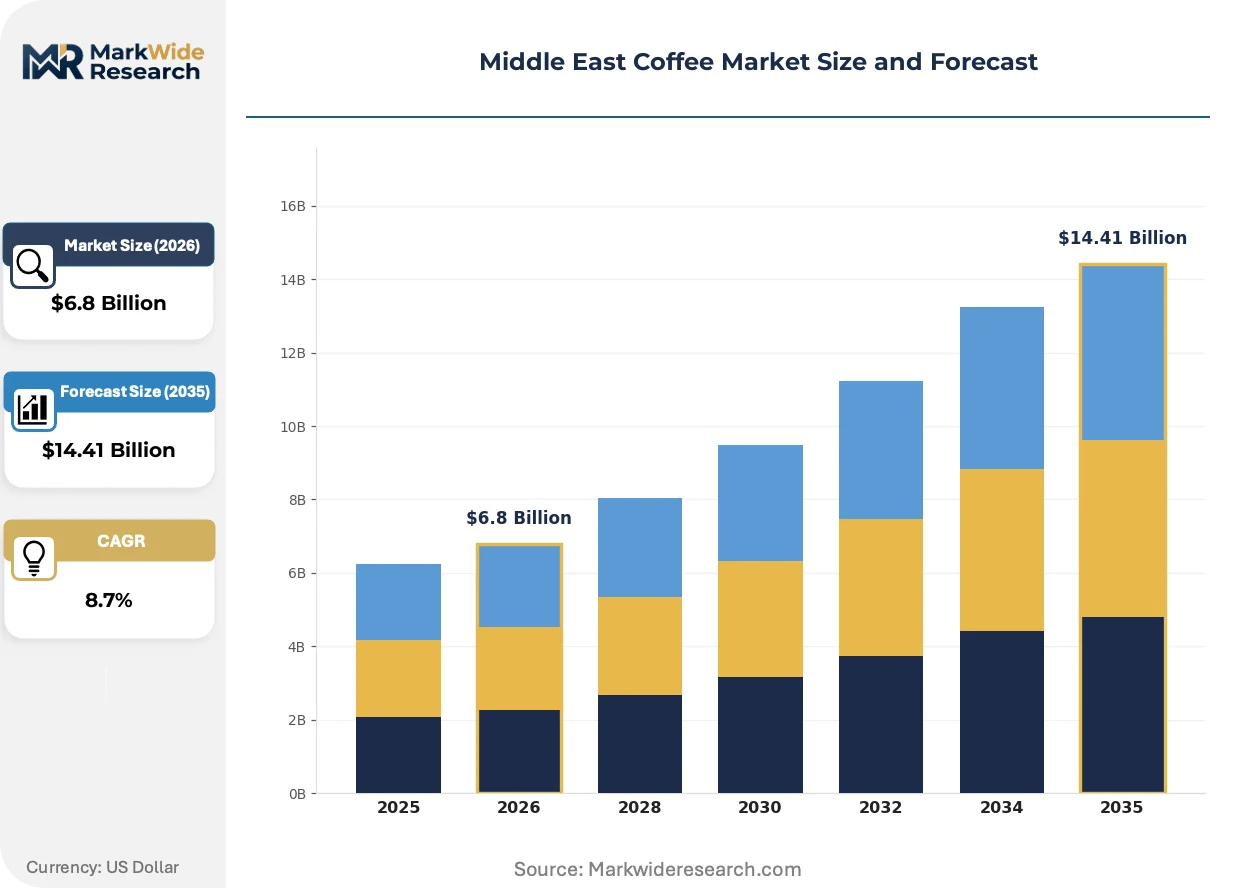
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Blend, Decaffeinated Distribution Channel: Online Retail, Supermarkets, Cafes, Specialty Stores Customer Type: Individual Consumers, Businesses, Hospitality, Retail Chains Roast Level: Light, Medium, Dark, Espresso |
| Companies Covered | Luigi Lavazza S.p.A., RAW Coffee Company, Starbucks Corporation, The Espresso Lab, Coffee Planet, Nestlé SA, Saudi Coffee Company, % Arabica, JDE Peet’s N.V., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Coffee Market Trends and Innovations
Digital traceability infrastructure and shifting consumption occasions are restructuring how coffee moves from origin to cup across Gulf markets.
Precision roasting software paired with crop-year data analytics is rewriting how Saudi roasters calibrate profiles for Asir highlands beans. Specialty chains in Jeddah are adopting these systems within 18-month replacement cycles. The technology is compressing the traditional trial-and-error period for new origin integration from months to weeks.
SFDA's phased implementation of electronic traceability submission requirements is forcing importers to reconfigure supplier onboarding workflows. The regulation mandates blockchain-verified documentation for all roasted coffee entries by 2026. Smaller trading houses are consolidating into larger licensed entities to absorb compliance infrastructure costs.
Home espresso equipment purchases are accelerating as remote work patterns persist in Dubai and Riyadh professional services sectors. Specialty roasters are responding with grind-specific subscription tiers and brewing education content. This shift is most visible among dual-income households in Saudi Arabia's Eastern Province compounds.
Middle East Coffee Market Segmentation
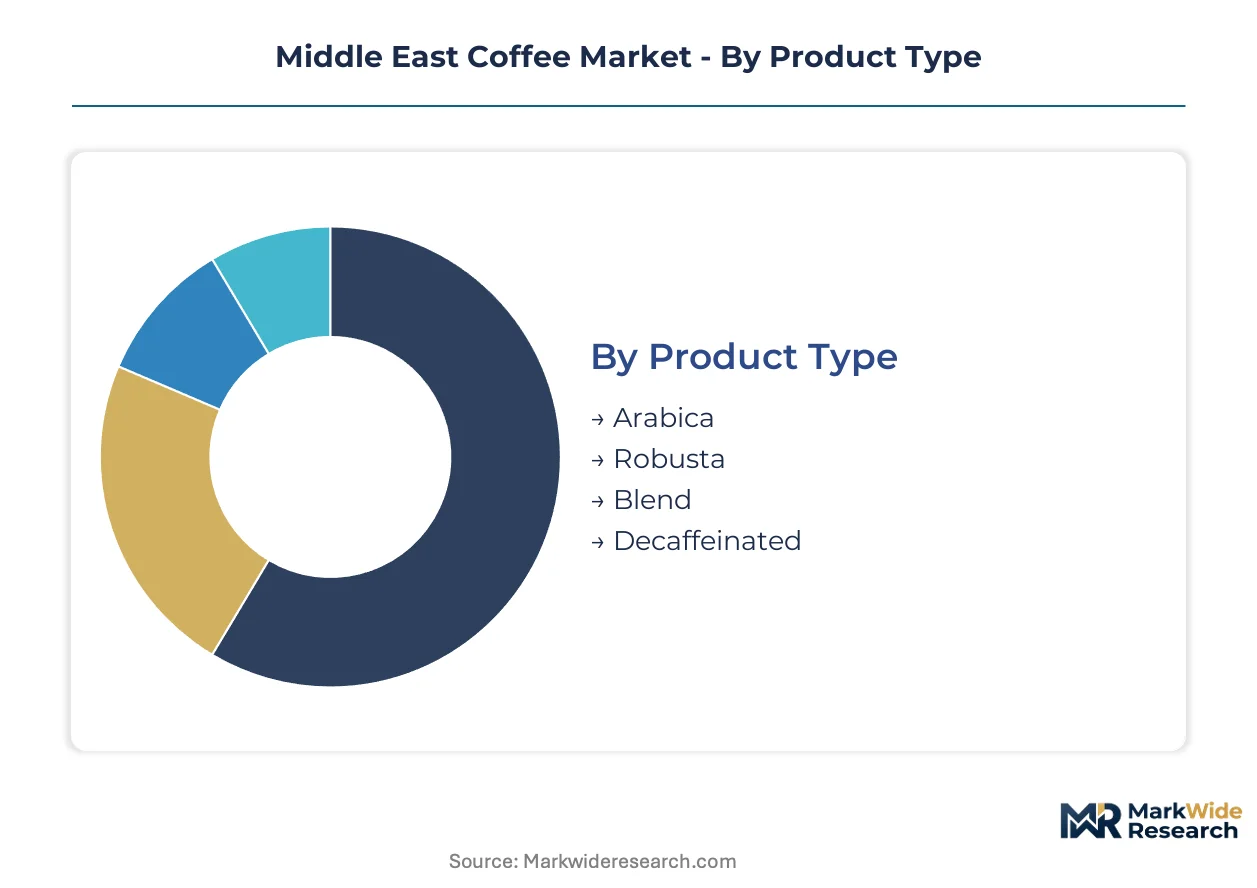
Segmentation across the Middle East coffee market reveals how procurement priorities diverge between hospitality buyers seeking traceable arabica and cost-driven instant manufacturers. Understanding these splits enables suppliers to align roasting capacity and certification investments with the highest-margin demand clusters.
Product Type:
Bean chemistry and terroir characteristics define pricing power and end-use suitability across Gulf roasting operations.
- Arabica:Higher acidity and complex aromatic profiles characterize these high-altitude beans. Specialty cafés in Dubai and Riyadh source single-origin arabica through direct-trade relationships, with SFDA residue testing requirements favoring suppliers with in-house laboratory infrastructure.
- Robusta:Elevated caffeine content and fuller body suit commercial espresso blends and instant formulations. Nestlé SA anchors procurement volumes for this segment through grocery channel distribution across Saudi Arabia and the UAE.
- Blend:Roasters combine arabica and robusta ratios to balance cost with cup quality for mid-market hospitality clients. Saudi Coffee Company leverages domestic Asir highlands arabica in proprietary blends to reduce import dependency.
- Decaffeinated:Solvent or water-processed beans address health-conscious consumption in professional services sectors. Limited local processing capacity forces reliance on European decaffeination facilities.
Arabica leads on scale; decaffeinated leads on momentum.
Distribution Channel:
Channel selection determines margin capture and consumer touchpoint control for roasters competing across urban Gulf markets.
- Online Retail:Mobile-first subscription platforms enable direct-to-consumer relationships bypassing traditional retail markups. Dubai-based roasters target home espresso equipment owners with grind-specific delivery tiers.
- Supermarkets:High-volume turnover for mainstream brands depends on shelf placement negotiations with Carrefour, Lulu, and Tamimi chains. Private-label programs are expanding as retailers develop captive coffee offerings.
- Cafes:Third-wave specialty formats in Jeddah and Riyadh drive single-origin premiums through experiential brewing rituals. Chains like Starbucks Corporation dominate high-traffic retail corridors with licensed store networks.
- Specialty Stores:Small-batch roasters in Dubai's Al Quoz industrial district sell traceable provenance to enthusiasts seeking crop-year specificity. These outlets command price multiples over supermarket equivalents through education-driven purchasing.
Supermarkets dominate volume throughput; online retail is expanding most quickly.
Customer Type:
Buyer sophistication and procurement scale vary sharply between individual households and institutional hospitality operators.
- Individual Consumers:Home brewing adoption accelerates among dual-income Saudi households in Eastern Province compounds, with equipment purchases driving bean subscription attachments.
- Businesses:Corporate pantry services and office coffee systems prioritize consistent supply contracts over origin complexity. Procurement teams negotiate annual volumes with limited quality variation tolerance.
- Hospitality:Hotels and restaurant groups in Riyadh and Dubai expand specialty coffee programs as competitive differentiation. Chains source Q-Grader verified lots through tender processes requiring blockchain documentation.
- Retail Chains:Licensed and franchised café operators balance standardization with localized menu adaptations. Saudi Food and Drug Authority labeling mandates force documentation system investments across this buyer class.
Hospitality leads on scale; individual consumers lead on momentum.
Roast Level:
Thermal profile selection reflects regional taste preferences and brewing equipment compatibility across consumption occasions.
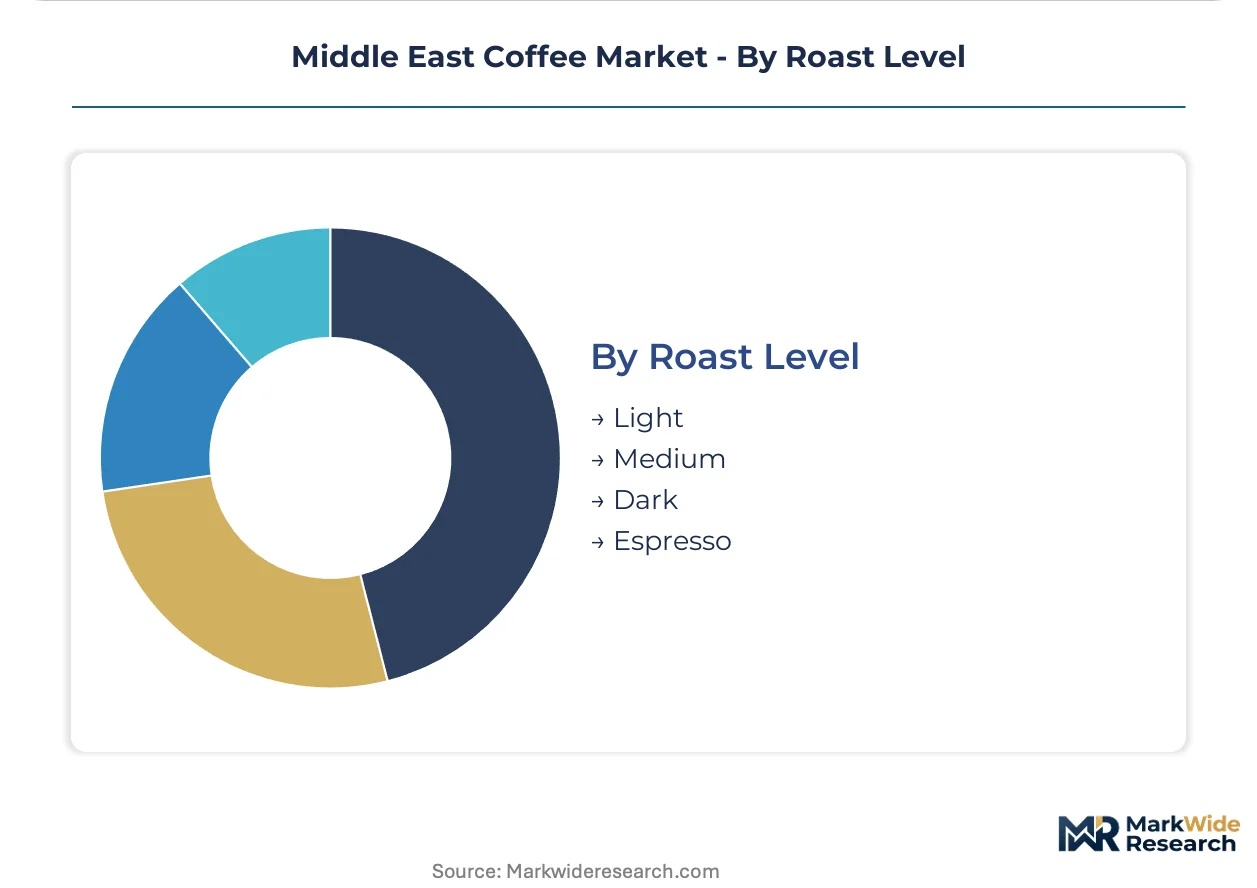
- Light:Preserved origin character and pronounced acidity appeal to specialty enthusiasts in Dubai's Jumeirah district. Precision roasting software enables profile consistency for small-batch operations.
- Medium:Balanced development suits drip and pour-over methods common in Saudi professional settings. This roast level dominates grocery shelf placement for mainstream brands.
- Dark:Extended caramelization masks bean defects and delivers the bold profile preferred for traditional Arabic coffee preparations. Robust supply concentration supports cost-competitive dark roast production.
- Espresso:Optimized for high-pressure extraction with tailored solubility and crema stability. Italian equipment manufacturers supply roasting systems calibrated to this specification for Gulf hospitality clients.
Medium roast leads on scale; light roast leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands the largest addressable base, while the UAE punches above its weight in per-capita specialty consumption. Kuwait and Qatar present concentrated high-income pockets with underdeveloped café infrastructure. The region's regulatory fragmentation around halal certification and traceability mandates shapes cross-border supply strategies.
Saudi Arabia
Riyadh and Jeddah drive arabica procurement through hospitality expansion and corporate foodservice contracts. SFDA residue testing and origin documentation requirements are compressing import timelines and favoring licensed distributors with in-house laboratory infrastructure. The Asir highlands cultivation initiative is reducing import dependency while creating localized supply alternatives for domestic roasters.
United Arab Emirates
Dubai's café density per capita exceeds Riyadh levels, with specialty chains pulling single-origin volumes through direct-trade relationships. MOCCAE halal certification and labeling standards add processing friction for European and Latin American suppliers. Al Quoz industrial district clusters small-batch roasters selling traceable provenance to enthusiasts seeking crop-year specificity.
Kuwait
Café density remains approximately half the Riyadh level despite comparable household income profiles. Limited domestic roasting capacity forces reliance on UAE and Saudi supply chains. Salmiya and Kuwait City districts show early specialty format adoption among expatriate professional communities.
Qatar
High-income concentration supports premium positioning, though market scale constrains dedicated roasting investment. Doha's hospitality sector sources through UAE intermediaries rather than direct origin relationships. FIFA-related infrastructure spending created temporary demand spikes that normalized post-2022.
Egypt
Cairo and Alexandria sustain robust traditional coffee consumption with limited specialty penetration. Import financing constraints and currency volatility favor lower-grade robusta formulations for price-sensitive segments. Local roasting capacity concentrates in informal supply chains outside regulatory purview.
Middle East Coffee Market Competitive Landscape
Top-tier vendors anchor licensed retail and grocery distribution, while mid-tier roasters compete on traceability claims and direct-trade narratives. The market structure stratifies across three tiers: multinational beverage conglomerates with Gulf-wide logistics networks, regional specialists with origin relationships, and emerging domestic roasters leveraging local cultivation narratives. Two dominant competitive moves are reshaping positioning: backward integration into green bean sourcing to control quality documentation for SFDA compliance, and technology licensing for precision roasting software to compress profile development cycles.
Within the multinational tier, Starbucks Corporation and Nestlé SA occupy positions defined by channel dominance rather than product overlap. Starbucks exemplifies licensed retail expansion through high-traffic corridor saturation in Dubai and Riyadh. Nestlé SA anchors instant and capsule segments through deep grocery distribution. Among regional specialists, Saudi Coffee Company represents the state-backed vertical integration archetype, while % Arabica sits within the premium single-origin format. Luigi Lavazza S.p.A. and JDE Peet's N.V. exemplify European roasters adapting Gulf-specific halal certification and labeling requirements for supermarket placement.
| Leading Market Players |
|---|
| Luigi Lavazza S.p.A. |
| RAW Coffee Company |
| Starbucks Corporation |
| The Espresso Lab |
| Coffee Planet |
| Nestlé SA |
| Saudi Coffee Company |
| % Arabica |
| JDE Peet's N.V. |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers like Saudi Coffee Company anchor supply discipline through captive Asir highlands cultivation, compressing import dependency while creating pricing power through localized arabica availability. This ownership pattern feeds directly into how roasters negotiate green bean contracts and pass through SFDA compliance costs.
Pricing Analysis
The bundled-vs-unbundled service split separates hospitality procurement from retail subscription models across Gulf markets. Three-tier pricing structure across premium, standard, and economy levels tracks quality grade and certification level, with SFDA residue testing tier commanding clear premiums. Cost compression in commodity robusta is intensifying because Vietnamese futures volatility transmits directly to instant formulation economics. Corporate pantry services show highest price sensitivity, while specialty café chains absorb provenance premiums for competitive differentiation.
Supply Chain Analysis
Saudi Arabia's domestic-content mandate through Asir cultivation initiatives is reshaping sourcing patterns for licensed roasters seeking import substitution. Geographic supply concentrates in Brazil, Vietnam, and Colombia for green arabica and robusta, with Ethiopian direct-trade volumes growing for specialty tiers. Raw material dependencies rest on fertilizer inputs, moisture-controlled shipping containers, and precision roasting equipment. Single-source vulnerability runs through Jeddah and Jebel Ali port concentration. Distribution runs through supermarket chains, licensed café networks, and mobile-first subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East coffee market functions as a stable compounder, with hospitality sector premiumization driving steady value expansion across Riyadh and Dubai corridors.
For Market Incumbents: Lock in Q-Grader talent pools through accredited training partnerships before scarcity spreads to secondary cities. Deepen backward integration into Asir highlands cultivation to control origin documentation for SFDA compliance. Capture channel control through direct-trade relationships that bypass commodity exchange volatility. For New Entrants and Emerging Players: Dual-income Saudi households in Eastern Province compounds represent an underserved buyer archetype with accelerating home espresso equipment penetration. Kuwait's café density gap versus Riyadh offers the most penetrable geography for specialty format rollout. Mobile-first grind-specific subscription tiers provide the clearest go-to-market angle for bypassing established retail shelf negotiations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier roasters with underutilized precision roasting software licenses and nascent direct-to-consumer infrastructure. Five-to-ten year viability hinges on regulatory compliance scalability rather than commodity trading acumen. Acquisition targets should show proven SFDA documentation workflows and hospitality tender track records. The signal to watch is consolidation velocity among smaller trading houses absorbing electronic traceability infrastructure costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Cultivation | Saudi Coffee Company's Asir expansion reduces import dependency while satisfying SFDA origin documentation mandates. |
| Precision Roasting Software Licensing | German and Italian manufacturer partnerships compress profile development cycles for new arabica integrations. |
| Direct-to-Consumer Subscription Launch | Dubai-based mobile platforms target home espresso owners with grind-specific tiers bypassing retail markups. |
| Blockchain Traceability Implementation | SFDA's electronic submission requirements favor roasters with real-time provenance verification for hospitality buyers. |
| Q-Grader Training Program Expansion | Licensed cupping professional scarcity in secondary cities constrains quality control scaling for emerging roasters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with green bean importers, roasting operations managers, hospitality procurement directors, and SFDA compliance officers with secondary validation. Trade data from Saudi Customs and UAE Federal Customs Authority anchored volume estimates, while specialty coffee association publications and hospitality sector tender databases provided pricing benchmarks. Bottom-up roaster capacity assessments triangulated against top-down import flow analysis.
Comparable-period anchoring tied projection models to historical import volumes and café density trajectories across the analysis window. Segmentation dimensions modeled include product chemistry, distribution channel, customer type, and roast level, with additional granularity for SFDA regulatory tier and halal certification status. CAGRs derived from trend extrapolation of hospitality program expansion rates and home equipment penetration curves. Green bean futures volatility and domestic cultivation yield assumptions fed sensitivity testing.
Underlying measurement precision varies by segment; specialty arabica direct-trade volumes carry tighter precision than informal Egyptian roasting channel estimates. Forecasts reflect documented assumptions about SFDA implementation timelines and Asir cultivation scaling. Currency volatility, port congestion events, and Q-Grader training pipeline constraints present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Middle East and Africa Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Decaf Coffee Market
Coffee
United States Coffee Pods and Capsules Market
Coffee
Coffee Fruit Extract Market
Coffee
GCC Instant Coffee Market
Coffee
Coffee Extracts Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Take Out Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Coffee Cherry Market
Coffee
Cold Brew Coffee Pots Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Europe Coffee Market
Coffee
Encapsulated Caffeine Market