
 Nitrogenated Coffee Market | 2026-2036
Nitrogenated Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogenated Coffee Market Outlook
Market Context with Strategic Players
The nitrogenated coffee category is shifting along a widening gap between draft-premium experiences and mass-market canned convenience. Starbucks Corporation leverages its global store footprint to normalize nitro cold brew as a standard menu fixture, while RISE Brewing Co. sustains independent retail credibility through organic certification and clean-label positioning. Stumptown Coffee Roasters anchors the super-premium tier with direct-trade sourcing narratives that justify higher per-unit pricing in specialty channels.
Technical Definition and Structural Segments
Nitrogenated coffee infuses cold-brewed coffee with nitrogen gas under high pressure, typically at 30-40 psi, producing a cascading visual effect and creamy mouthfeel without dairy additives. The primary commercial purpose is to differentiate ready-to-drink and foodservice coffee offerings through sensory novelty and perceived premium quality. Canned nitro coffee dominates volume flows through supermarkets and convenience stores, while draft nitro coffee commands superior margin pools in specialty coffee shops where equipment installation creates captive demand. Online retail represents the fastest-growing distribution channel as direct-to-consumer brands bypass traditional wholesale markups.
Regulatory Framework and Forward Outlook
FDA oversees nitrogenated coffee as a conventional food product, requiring accurate ingredient labeling and adherence to Good Manufacturing Practices, while state-level health departments regulate draft dispensing equipment sanitation. The USDA Organic seal and FDA nutrition panel compliance function as dual gatekeepers for shelf placement in mainstream retail. Stakeholders must monitor evolving FDA guidance on nitrogen gas classification as an ingredient versus processing aid, a determination that would reshape labeling obligations across all packaging formats.
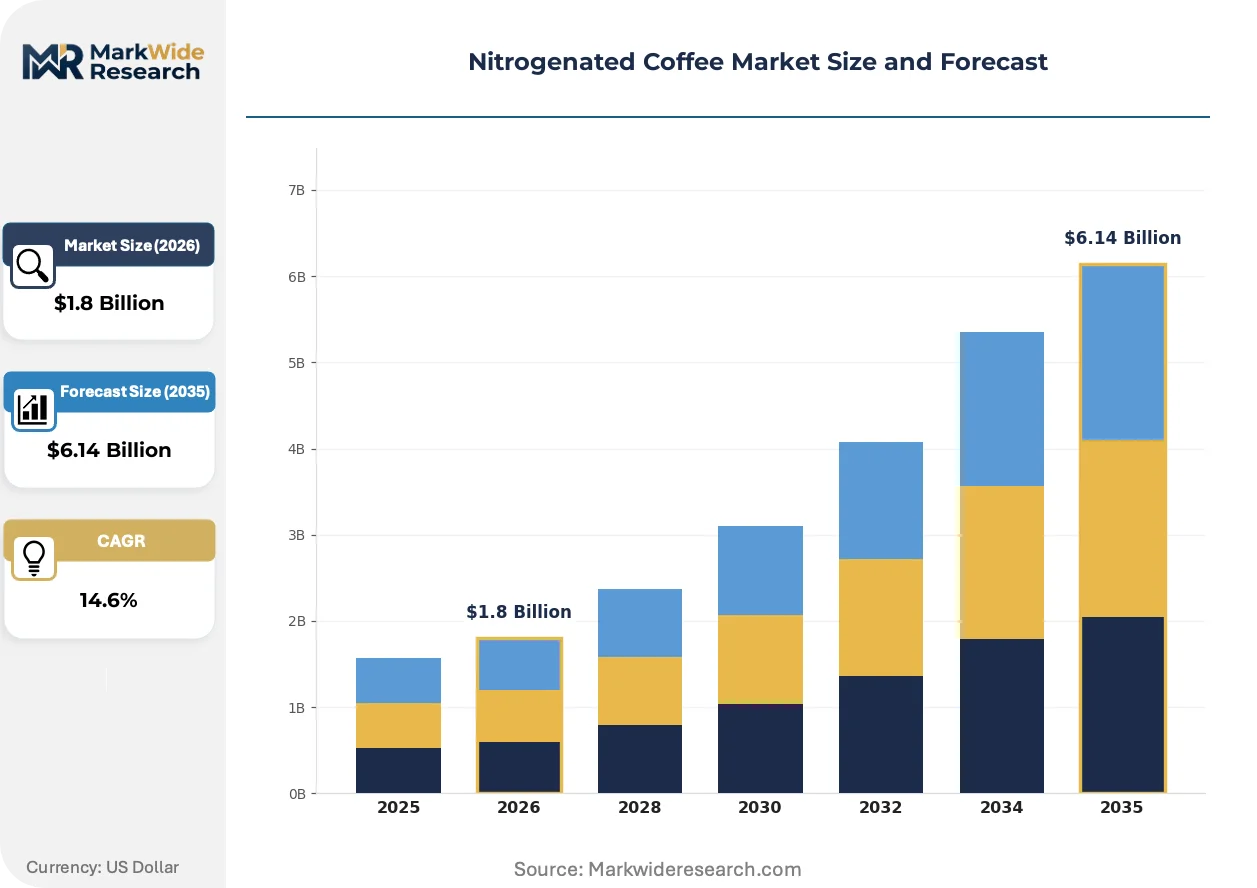
Market Dynamics
Draft nitrogen dispensing systems are creating a bifurcated market structure where foodservice operators with installed equipment capture margin premiums, while canned formats compete on velocity through conventional retail. Equipment concentration in specialty cafés is reshaping upstream supplier relationships.
Growth Catalysts
- Experiential beverage consumption:Urban café clusters in Portland, Brooklyn, and Los Angeles are normalizing nitrogenated coffee as a standard format, pulling equipment investment into secondary metropolitan markets.
- FDA labeling clarity:Draft guidance on nitrogen classification as processing aid rather than ingredient is reducing compliance ambiguity for manufacturers reformulating for clean-label positioning.
- Organic certification penetration:USDA Organic seal requirements are driving ingredient sourcing upgrades that align with premium pricing strategies in specialty channels.
Market Restraints
- Draft equipment capex barriers:High-pressure nitrogen systems requiring 30-40 psi installation create fixed-cost thresholds that exclude independent operators with limited capital access.
- Gas supply concentration:Food-grade nitrogen sourcing concentrates among industrial gas suppliers with regional distribution monopolies, exposing operators to input price volatility.
- Refrigerated logistics complexity:Cold-chain requirements for draft keg distribution impose spoilage risk and route density constraints on rural market penetration.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channel expansion enables canned nitro brands to bypass wholesale markups and capture first-party consumer data.
- Clean-label convergence:Nitrogen's dairy-mimicking mouthfeel creates formulation pathways for plant-based latte alternatives without stabilizer additives.
- Secondary city café expansion:Underpenetrated markets in Austin, Nashville, and Denver present first-mover advantages for draft equipment placement ahead of competitive saturation.
Industry Challenges
- Equipment technician scarcity:Specialized nitrogen system maintenance requires certified technicians with beverage gas handling credentials, creating service coverage gaps in emerging markets.
- Sanitation protocol standardization:State health department draft line cleaning requirements vary by jurisdiction, complicating multi-location operator compliance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogenated Coffee Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Nitro Coffee, Draft Nitro Coffee, Bottled Nitro Coffee, Nitro Cold Brew Distribution Channel: Supermarkets, Specialty Coffee Shops, Online Retail, Convenience Stores Packaging Type: Cans, Glass Bottles, Plastic Bottles, Kegs End User: Consumers, Cafés, Restaurants, Food Trucks |
| Companies Covered | Starbucks Corporation, RISE Brewing Co., International Coffee & Tea, LLC, Stumptown Coffee Roasters, NITRO Beverage Co., Califia Farms, Bona Fide Nitro Coffee and Tea, Blackeye Roasting Co., High Brew Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogenated Coffee Market Strategic Shifts
Nitrogenated coffee is experiencing format innovation at the intersection of equipment miniaturization and packaging chemistry. These developments are compressing the traditional divide between draft experiential quality and retail convenience accessibility.
Widget-integrated can technology is electrifying the at-home nitro experience by replicating cascading pour dynamics without draft equipment dependency. Premium canned brands are adopting this packaging at scale, while convenience store buyers are expanding shelf space allocations for widget-enabled SKUs. The technology is electrifying margin compression in the super-premium tier as sensory parity with draft formats becomes achievable at mass-market price points.
REACH chemical registration requirements in Europe are tightening scrutiny on food-contact materials in nitrogen dispensing equipment. Manufacturers serving EU export markets are reformulating gaskets and seals to eliminate SVHC substances ahead of sunset date enforcement. Draft system suppliers with EU certification precedence are capturing specification advantages in North American markets where buyers anticipate regulatory convergence.
Third-party delivery platform integration is restructuring café demand patterns as nitrogenated coffee becomes a photographed shareable moment rather than purely functional caffeine delivery. Specialty operators are redesigning bar layouts to optimize pour visibility for customer-generated content. This behavioral shift concentrates in coastal metropolitan markets where social media influence on beverage selection is most pronounced.
Nitrogenated Coffee Market Segmentation
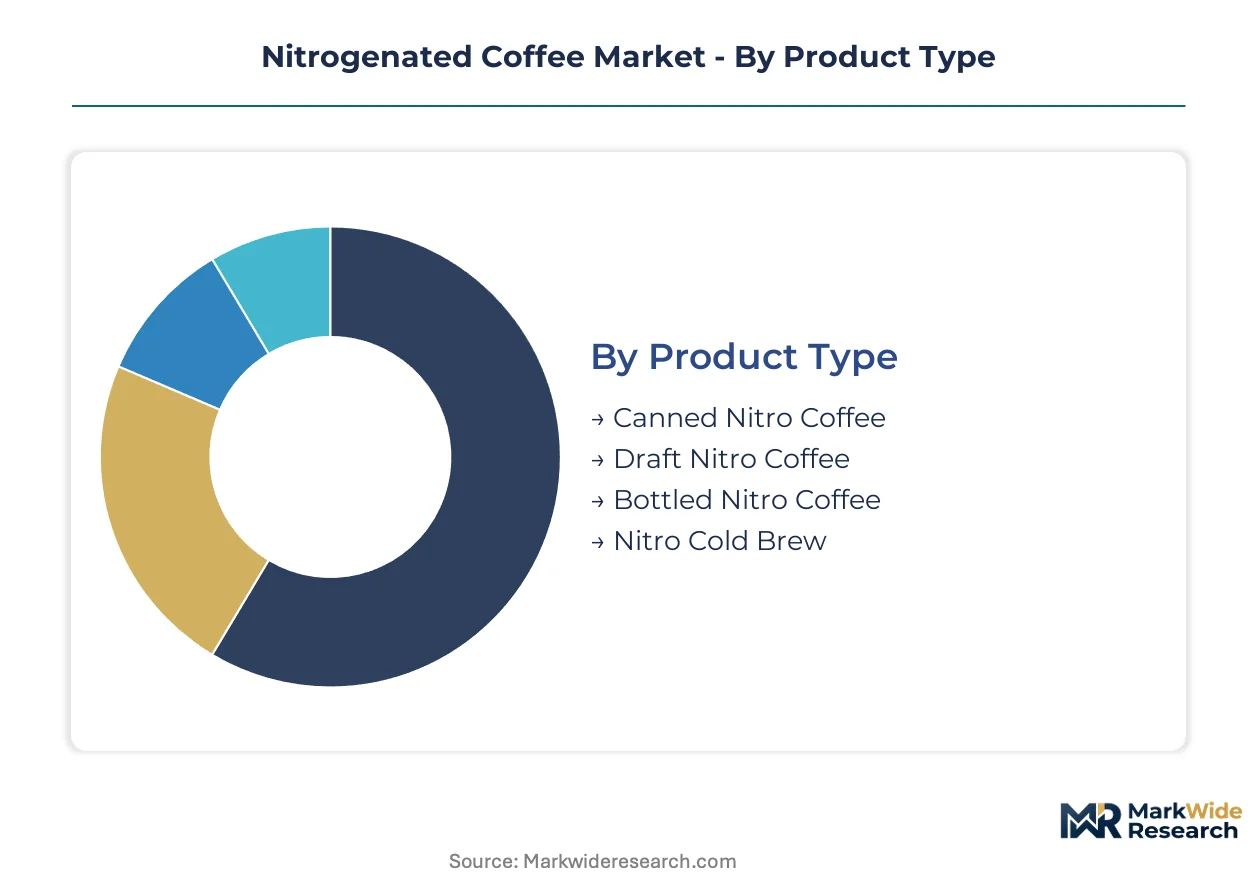
Nitrogenated coffee segmentation reveals divergent margin structures between experiential draft formats and convenience-oriented retail packaging. Equipment requirements and cold-chain intensity create distinct competitive arenas that reshape supplier relationships across each category.
Product Type:
Buyers choose between sensory experience and portability, with equipment access determining format selection in foodservice versus retail contexts.
- Canned Nitro Coffee:Widget-integrated aluminum cans replicate cascading pour dynamics through internal nitrogen-release mechanisms. Convenience store buyers in the United States are expanding shelf space for widget-enabled SKUs as at-home consumption normalizes.
- Draft Nitro Coffee:High-pressure dispensing at 30-40 psi delivers the signature creamy mouthfeel without dairy additives. Specialty coffee shops in Portland, Brooklyn, and Los Angeles capture margin premiums through installed equipment that creates captive demand.
- Bottled Nitro Coffee:Glass and PET formats target premium retail placement with extended shelf stability. Grocery channel buyers favor bottled variants for refrigerated section density.
- Nitro Cold Brew:Extended steeping protocols produce concentrated bases for on-tap dilution or ready-to-drink formulation. Café operators value batch consistency and labor efficiency in high-volume service windows.
Canned formats lead on scale; draft formats lead on momentum.
Distribution Channel:
Route-to-market selection determines margin capture, with direct channels bypassing wholesale markups while traditional retail secures velocity.
- Supermarkets:Refrigerated aisle placement demands slotting fees and promotional compliance that favor scaled suppliers with trade marketing budgets. Chains in urban clusters negotiate exclusive regional SKUs.
- Specialty Coffee Shops:Draft equipment installation creates recurring keg relationships with higher lifetime value than transactional retail. Barista training and maintenance contracts deepen supplier lock-in.
- Online Retail:Direct-to-consumer subscriptions enable first-party data capture and margin retention absent distributor tiers. This channel is expanding most quickly as digital-native brands bypass traditional wholesale structures.
- Convenience Stores:Grab-and-go placement prioritizes package durability and extended ambient stability for non-refrigerated fixtures. Petroleum retailers are testing nitro coffee fountain installations at flagship locations.
Specialty coffee shops lead on scale; online retail leads on momentum.
Packaging Type:
Material selection balances sensory performance against logistics cost, with food-contact regulations constraining format innovation.
- Cans:Aluminum dominates widget-integrated formats with superior nitrogen retention and recyclability credentials. REACH chemical registration requirements in Europe are tightening scrutiny on interior coatings.
- Glass Bottles:Premium positioning leverages transparency and heft cues, though weight increases freight cost and breakage risk. Craft-oriented brands favor glass for specialty channel differentiation.
- Plastic Bottles:PET and rPET formats reduce shipping weight and enable shatterproof distribution to outdoor events and food trucks. Recycled content mandates in California and Oregon are accelerating material transitions.
- Kegs:Stainless steel and disposable plastic kegs serve draft installations with divergent capital intensity. Food-grade nitrogen sourcing concentrates among industrial gas suppliers with regional distribution control.
Cans lead on scale; kegs lead on momentum.
End User:
Consumption occasion and service format dictate packaging and equipment requirements across fragmented demand points.
- Consumers:At-home and on-the-go consumption favors single-serve portability with minimal preparation. Subscription models are capturing recurring revenue through auto-replenishment algorithms.
- Cafés:Draft installations require technician-certified maintenance and line cleaning protocols that vary by state health department jurisdiction. Equipment financing programs reduce capital barriers for independent operators.
- Restaurants:Menu integration as dessert or breakfast pairings drives portion-controlled formats. Fine dining establishments are specifying nitrogen systems for tableside presentation theater.
- Food Trucks:Mobile service constraints favor canned formats or compact keg systems with generator-compatible refrigeration. Festival and event circuits create concentrated demand spikes.
Consumers lead on scale; cafés lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty barista talent concentrates in coastal metropolitan clusters, pulling equipment investment toward experiential café formats and away from conventional retail. This workforce distribution shapes nitrogenated coffee penetration patterns across national markets.
United States
Urban café density in Portland, Brooklyn, and Los Angeles normalizes draft nitro as a standard format, pulling secondary market adoption. FDA labeling requirements for nitrogen-infused beverages tighten ingredient disclosure standards nationwide. Equipment installation concentrates in Pacific Northwest and Northeast corridor metro clusters where experiential beverage consumption intensifies.
Canada
Specialty coffee shop expansion in Toronto and Vancouver drives draft system demand among independent operators. Health Canada oversees nitrogenated beverages under food safety frameworks with provincial health department sanitation protocols for draft equipment. Western provinces anchor initial penetration, with Ontario café clusters accelerating equipment placement.
Germany
Third-wave coffee culture in Berlin and Hamburg creates receptive channels for nitrogenated formats among quality-focused consumers. REACH chemical registration requirements tighten scrutiny on food-contact materials in dispensing equipment. Bavaria and North Rhine-Westphalia house industrial gas suppliers controlling regional nitrogen distribution.
United Kingdom
London specialty coffee density supports draft installation economics for multi-location operators. Food Standards Agency regulations govern nitrogen use in beverages with local authority environmental health oversight of café equipment. Independent roasters in Manchester and Bristol test canned formats for retail channel expansion.
Australia
Melbourne's café culture leadership positions the city for draft nitro adoption among experiential beverage seekers. Food Standards Australia New Zealand regulates nitrogen classification in beverage processing with state-level food act enforcement. Sydney and Brisbane roasters experiment with widget-integrated cans for beach and outdoor consumption occasions.
Nitrogenated Coffee Market Competitive Environment
Top-tier vendors anchor mass-market scale, while independent roasters and organic-certified specialists occupy premium niches with divergent margin structures. The competitive terrain splits between multinational beverage corporations with retail velocity advantages and craft-oriented operators with direct-trade sourcing credibility. Three archetypes dominate: global café chains normalizing draft formats, independent organic brands commanding clean-label premiums, and regional roasters leveraging origin narratives. Capacity expansion and strategic equipment financing partnerships constitute the dominant competitive moves reshaping foodservice penetration.
Among North American specialists, Starbucks Corporation exemplifies the normalization archetype through global footprint deployment, while RISE Brewing Co. and Stumptown Coffee Roasters occupy positions within the organic-superpremium tier. These three entities represent distinct strategic postures: scale-driven format standardization, independent retail credibility through certification, and direct-trade sourcing justification for elevated pricing.
| Leading Market Players |
|---|
| Starbucks Corporation |
| RISE Brewing Co. |
| International Coffee & Tea, LLC |
| Stumptown Coffee Roasters |
| NITRO Beverage Co. |
| Califia Farms |
| Bona Fide Nitro Coffee and Tea |
| Blackeye Roasting Co. |
| High Brew Coffee |
| Others |
Value Chain & Pricing Dynamics
Captive nitrogen supply contracts anchor both cost predictability and margin defense for draft-format operators, while canned-format competitors outsource gas procurement to industrial distributors with regional pricing power. This integration choice separates foodservice operators capturing equipment-locked premiums from retail brands exposed to commodity nitrogen volatility and aluminum tariff pass-through.
Pricing Analysis
Bundled equipment-service contracts dominate draft nitro economics, unbundled per-can transactions drive retail velocity. Three-tier pricing structure across super-premium draft, premium widget-integrated cans, and mass-market standard cans reflects certification grade and experiential access. Cost compression in the mass tier is intensifying because widget technology erodes draft format exclusivity. Convenience store buyers exhibit highest price sensitivity; specialty café operators demonstrate lowest sensitivity due to captive demand mechanics.
Supply Chain Analysis
Single-source vulnerability sits with industrial gas suppliers controlling regional food-grade nitrogen distribution. Manufacturing concentration spans the United States for draft system assembly, China for widget-integrated can components, and Germany for precision dispensing valves. Raw material dependencies include food-grade nitrogen, aluminum sheet stock, and nitrile gaskets subject to REACH chemical scrutiny. Tariff exposure on Chinese can components presents structural risk. Distribution runs through refrigerated logistics networks for draft kegs and ambient freight for shelf-stable cans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nitrogenated coffee category has entered late-cycle quality competition where experiential differentiation commands sustainable premiums, as consumer demand shifts decisively toward certified organic and clean-label specifications that justify price elevation.
For Market Incumbents: To counter widget-enabled can technology eroding draft format exclusivity, deepen equipment financing partnerships with independent cafés to lock in keg supply relationships, and accelerate USDA Organic certification coverage across product lines to defend clean-label positioning against emerging certified entrants. For New Entrants and Emerging Players: Widget-integrated can innovation offers a technology-first wedge into secondary metropolitan markets in Austin, Nashville, and Denver where draft equipment penetration remains sparse. Target direct-to-consumer subscription models with auto-replenishment algorithms to bypass wholesale margin extraction and capture first-party consumer data. For Investors and Strategic Acquirers: Roll-up economics work for regional organic-certified roasters because fragmented specialty coffee shop supply relationships concentrate purchasing power under consolidated ownership. Five-to-ten-year viability hinges on experiential format normalization; monitor FDA nitrogen classification determinations as the signal indicating regulatory clarity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment Financing Partnership Expansion | Reduces capital barriers for independent cafés and locks in recurring keg revenue streams. |
| USDA Organic Certification Acceleration | Aligns with clean-label consumer preferences and secures premium shelf placement in specialty channels. |
| Widget-Integrated Can Technology Adoption | Replicates draft sensory experience at mass-market price points, compressing super-premium tier margins. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale markup tiers and enables first-party data capture for personalization algorithms. |
| Secondary City Café Equipment Placement | Captures first-mover advantage in underpenetrated markets ahead of competitive saturation. |
Study Parameters
Direct dialogue with specialty coffee shop owners, draft system technicians, industrial gas procurement managers, and retail category buyers grounded qualitative findings in operational reality. Secondary validation drew from FDA guidance documents, USDA organic certification databases, refrigerated logistics trade publications, and aluminum packaging industry reports. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Top-down macroeconomic framing anchored volume projections while bottom-up channel-by-channel build-ups tested price and volume assumptions. Segmentation dimensions modeled include product format, distribution channel, packaging material, and end-user occasion. CAGRs derived from fitted growth curves incorporating equipment installation rates, organic certification penetration trajectories, and widget technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA nitrogen classification rulings, REACH chemical registration enforcement, and aluminum tariff regime shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Ground Coffee Market
Coffee
RTD Coffee Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Vietnam Coffee Market
Coffee
High Protein Coffee Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Coffee Bags Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Grinder Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Robusta Coffee Beans Market
Coffee
Coffee Bottle Market
Coffee
Espresso Powder Market