
 Pepper Market | 2026-2036
Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
Pepper Market Intelligence
The premium pepper segment is decoupling from commodity grades on traceability, origin certification, and volatile oil content. Givaudan SA leverages its captive sourcing networks in Madagascar and Indonesia to secure high-piperine lots for flavor extraction. McCormick & Company, Inc. anchors North American retail through controlled supply agreements with Vietnamese processors. Olam International Limited dominates bulk trade flows while extending traceability platforms into farm-gate procurement.
Pepper comprises the dried fruit of Piper nigrum and related species, valued commercially for piperine alkaloid content typically ranging from two to seven percent by dry weight, plus essential oil fractions that determine aromatic intensity in industrial extraction. Food Seasoning applications lead volume consumption across institutional and retail channels, while Botanical Extracts represent the fastest-expanding margin pool as pharmaceutical and nutraceutical buyers standardize on specified piperine concentrations. The Essential Oil and Oleoresin forms command pricing premiums over ground powder in processed food and cosmetic formulations.
The FDA maintains pesticide residue tolerances for imported pepper under the Food Safety Modernization Act, while the EPA regulates fumigant applications in post-harvest storage. India's Spices Board enforces mandatory testing for aflatoxin and salmonella under its export certification regime. Stakeholders must monitor evolving mycotoxin thresholds across importing jurisdictions and calibrate sourcing strategies between origin-differentiated premium lots and standardized commodity grades.
Market Dynamics
The EU F-Gas Regulation and EU Green Deal are forcing energy-intensive steam sterilization and solvent extraction facilities to retrofit or relocate, compressing processing margins and redrawing competitive maps among Vietnamese, Indian, and Indonesian processors.
Growth Catalysts
- Clean-label reformulation mandates:European food manufacturers under EFSA scrutiny are substituting synthetic preservatives with piperine-rich pepper extracts in shelf-stable sauces and ready meals.
- India's Spices Board certification:Mandatory aflatoxin and salmonella testing protocols are unlocking premium retail shelf space for compliant exporters in EU and North American channels.
- Pharmaceutical standardization:USP-grade piperine specifications for bioavailability enhancement in nutraceuticals are pulling dedicated extraction capacity online in Vietnam and Indonesia.
Market Restraints
- Input cost volatility:Natural gas and biomass fuel prices for steam sterilization swing with Indonesian coal export policies, squeezing processor margins unpredictably.
- Supply concentration risk:Vietnam's Binh Phuoc and Dak Lak provinces control over sixty percent of global black pepper export volume, exposing buyers to monsoon-driven crop failures.
- Regulatory friction:The FDA's Food Safety Modernization Act traceability rules impose eighteen-month compliance windows that smaller Indian exporters struggle to fund.
Strategic Opportunities
- Brazilian cultivation expansion:Para and Bahia states offer underdeveloped acreage with favorable rainfall patterns for organic certification pipelines targeting North American natural channel buyers.
- Cosmetic oleoresin applications:K-beauty and J-beauty formulators in South Korea and Japan are specifying piperine for melanin-inhibition claims in premium skincare SKUs.
- EU Green Deal agricultural incentives:Carbon border adjustment mechanisms reward Vietnamese processors deploying solar thermal drying, creating first-mover certification premiums.
Industry Challenges
- Specialized extraction engineering talent:Supercritical CO2 and ethanol extraction operators with piperine concentration expertise command wage premiums that mid-scale processors cannot match.
- Legacy fumigation infrastructure:Phosphine and methyl bromide chambers face accelerated depreciation under EPA and EU biocide restrictions, forcing capital-intensive cold plasma or controlled atmosphere replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pepper Market |
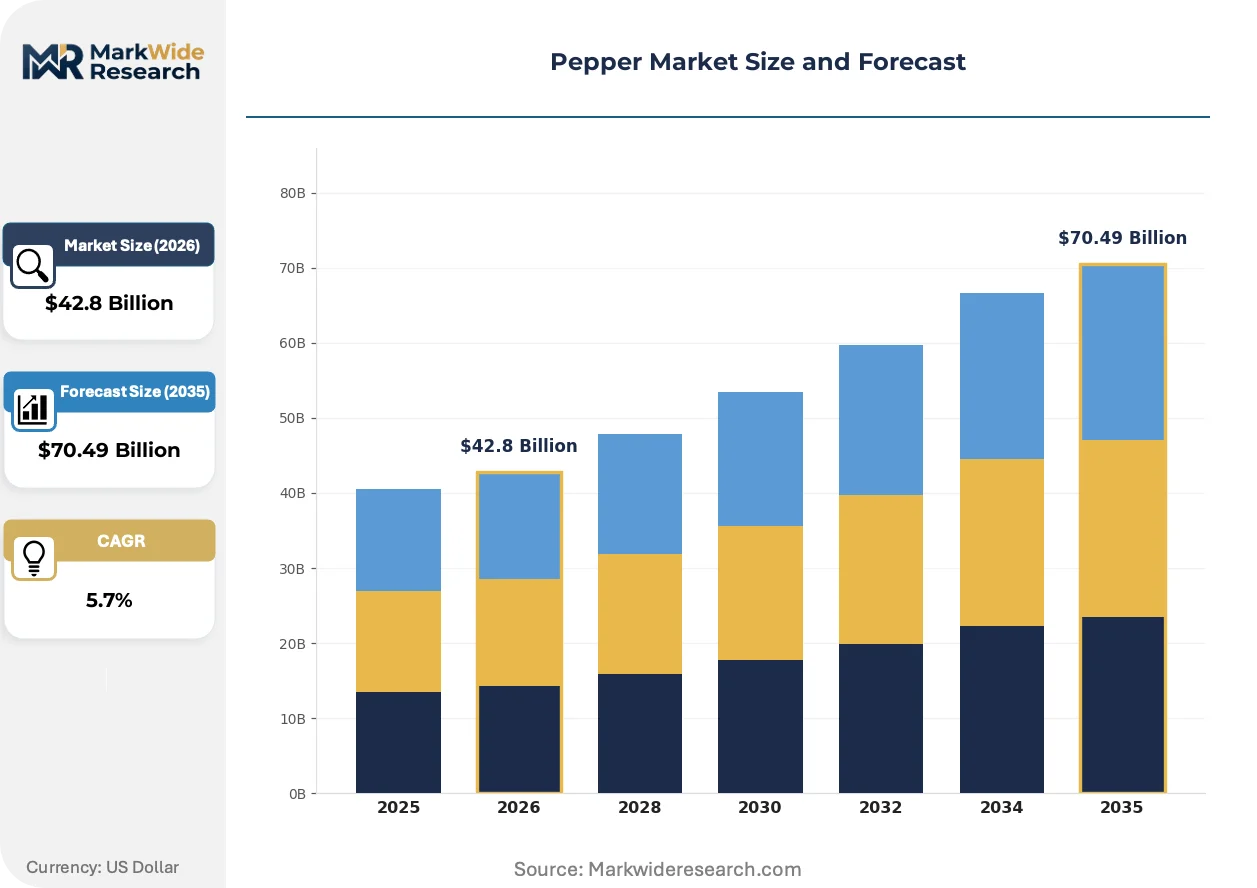
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Pepper, White Pepper, Green Pepper, Long Pepper, Cubeb Pepper Application: Food Seasoning, Pharmaceutical Use, Spice Blends, Cosmetics, Botanical Extracts Form: Whole Peppercorns, Ground Powder, Crushed, Essential Oil, Oleoresin Customer Type: Food Manufacturers, Herbal Product Makers, Cosmetic Producers, Retail Consumers, Research Institutions |
| Companies Covered | Givaudan SA, Ajinomoto Co. Inc., Olam International Limited, Kancor Ingredients Ltd., Synthite Industries Private Limited, McCormick & Company, Inc., Kerry Group plc, V. Sudhakar Group, Everest Spices Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pepper Market Strategic Shifts & Innovations
Processing technology and procurement transparency are converging to compress quality verification cycles and disintermediate traditional auction-based spot markets.
Supercritical CO2 extraction is overtaking steam distillation for high-value oleoresin production. Pharmaceutical and cosmetic buyers in Germany and Switzerland now specify CO2-derived piperine for residual-solvent compliance. This technology is overtaking conventional methods by enabling precise terpene fractionation that steam cannot achieve, compressing the premium-standard price spread.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based refrigeration is forcing cold storage operators in Rotterdam and Hamburg to adopt ammonia or transcritical CO2 systems. Sterilization and drying facilities face parallel pressure to decarbonize thermal energy inputs. Vietnamese processors with EU export exposure are responding by clustering solar thermal arrays near Binh Duong industrial zones.
Blockchain-enabled farm-gate traceability is displacing paper-based origin certificates in premium segment procurement. Retail and foodservice buyers in the Netherlands and United Kingdom now require lot-level GPS coordinates and pesticide application logs. This shift is most visible in Madagascar and Indonesia, where specialty exporters leverage digital traceability to capture thirty-to-fifty percent price premiums over commodity auction grades.
Pepper Market Segmentation
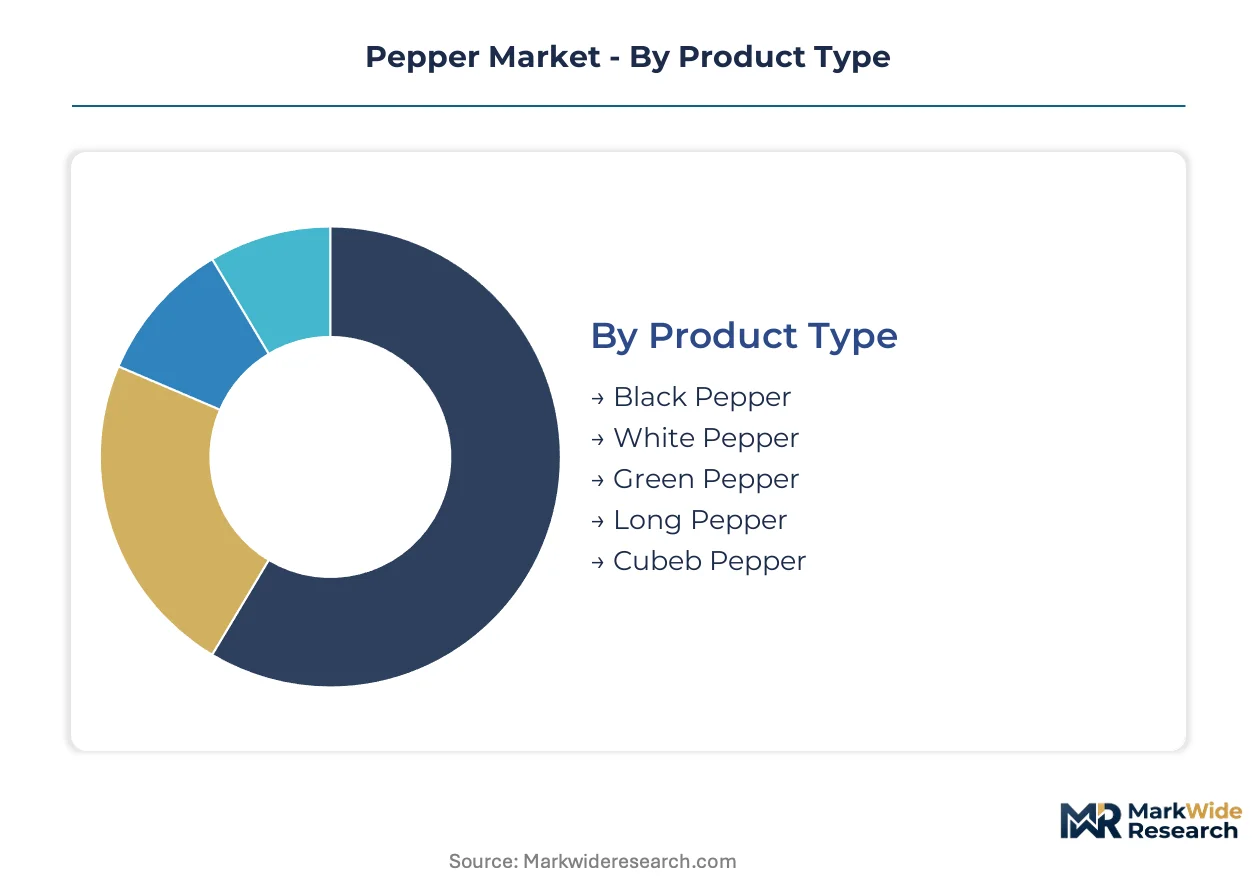
Pepper market participants face divergent technical specifications across extraction-grade oleoresins, retail-ready powders, and pharmaceutical-standard piperine concentrates. Segmentation reveals how procurement priorities split between volatile oil content, traceability certification, and residual solvent compliance.
Product Type:
Buyers differentiate by piperine alkaloid concentration, essential oil fractions, and origin-certification premiums rather than color alone.
- Black Pepper:Dried unripe berries with piperine content typically ranging two to seven percent by dry weight, plus terpene-rich essential oils. Vietnamese processors in Binh Phuoc province dominate export volume, though monsoon-driven crop failures expose buyers to supply concentration risk.
- White Pepper:Fermented and skin-removed berries offering milder flavor profiles for European sauce manufacturers under EFSA clean-label scrutiny. Indonesia's Lampung region supplies premium lots with controlled fermentation protocols that command traceability premiums.
- Green Pepper:Freeze-dried or brined unripe berries targeting high-end foodservice channels in France and Switzerland.
- Long Pepper:Piper longum species with distinct alkaloid profiles used in Ayurvedic formulations and specialty spice blends.
- Cubeb Pepper:Indonesian-origin Piper cubeba with cubebin content specified in traditional medicine applications across South and Southeast Asia.
Volume sits with Black Pepper; growth tilts toward White Pepper as European reformulation mandates accelerate.
Application:
End-use specifications range from institutional foodservice batch consistency to USP-grade pharmaceutical purity requirements.
- Food Seasoning:Institutional and retail channels consuming ground powders and whole peppercorns for flavor intensity. North American retail chains anchor demand through controlled supply agreements with Vietnamese processors.
- Botanical Extracts:Standardized piperine concentrates for nutraceutical bioavailability enhancement. Pharmaceutical buyers in Germany and Switzerland now specify supercritical CO2-derived material for residual-solvent compliance.
- Pharmaceutical Use:USP-grade specifications for drug delivery systems and therapeutic formulations.
- Spice Blends:Pre-mixed formulations for industrial sauce and ready-meal manufacturers.
- Cosmetics:Oleoresin fractions for melanin-inhibition claims in South Korean and Japanese premium skincare SKUs.
Food Seasoning commands absolute volume; Botanical Extracts are climbing the fastest on margin expansion.
Form:
Processing intensity determines pricing tiers from raw agricultural commodity to refined extraction outputs.
- Oleoresin:Solvent-extracted or supercritical CO2-derived concentrated resin containing piperine and essential oil fractions. Cosmetic and pharmaceutical formulators in Germany specify this form for precise dosing and residual-solvent compliance.
- Essential Oil:Steam-distilled or CO2-extracted terpene fractions for flavor and fragrance applications. Swiss and German buyers drive specification tightening on pesticide residue thresholds.
- Whole Peppercorns:Premium retail and foodservice segments requiring origin-verified, non-irradiated lots.
- Ground Powder:Mass-market retail and institutional channels with standardized mesh sizes.
- Crushed:Coarse fractions for visual texture in premium foodservice applications.
Ground Powder moves the most units; Oleoresin gains share fastest on functional ingredient demand.
Customer Type:
Procurement scale and specification rigor separate commodity spot buyers from contract-based premium segment purchasers.
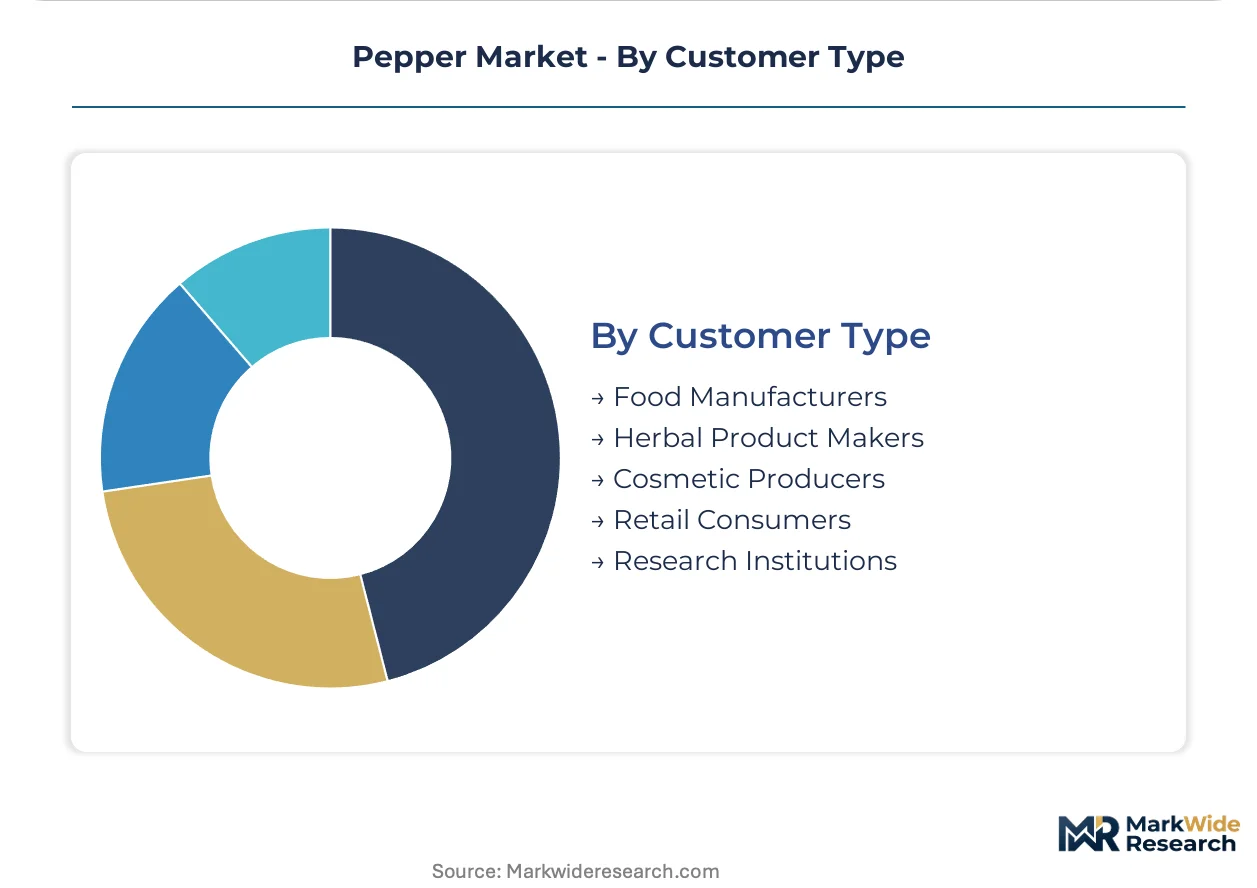
- Food Manufacturers:Industrial-scale buyers requiring batch consistency, aflatoxin certification, and FSSAI or FDA-compliant documentation. India's Spices Board mandatory testing protocols unlock premium retail shelf space for compliant suppliers.
- Cosmetic Producers:K-beauty and J-beauty formulators specifying piperine concentrations for melanin-inhibition claims with full traceability documentation.
- Herbal Product Makers:Ayurvedic and traditional medicine processors requiring specific alkaloid profiles.
- Retail Consumers:Supermarket and e-commerce channels with origin and organic certification preferences.
- Research Institutions:Academic and clinical trial suppliers needing analytical-grade material with full phytochemical characterization.
Food Manufacturers absorb the bulk of commodity volume; Cosmetic Producers drive the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Binh Phuoc province anchors global black pepper processing, with industrial zones around Dong Xoai hosting steam sterilization and oleoresin extraction facilities serving pharmaceutical buyers in Germany and Switzerland.
Vietnam
Food manufacturers in Binh Duong and Dong Nai provinces drive demand for aflatoxin-certified pepper powders under India's Spices Board protocols. The EU F-Gas Regulation pressures processors to retrofit steam sterilization lines with solar thermal arrays. Dak Lak province's highland cultivation zones supply premium piperine-rich lots to extraction specialists.
Indonesia
Lampung region's controlled fermentation protocols produce white pepper lots commanding traceability premiums from Dutch and British retail buyers. The country's national food safety regulator enforces pesticide residue thresholds aligned with EFSA standards. North Sumatra's Medan industrial corridor hosts oleoresin extraction capacity targeting South Korean cosmetic formulators.
India
Kerala's Wayanad and Idukki districts supply black pepper for USP-grade piperine extraction under FSSAI mandatory testing regimes. The Spices Board's aflatoxin certification unlocks premium shelf space in EU retail channels. Karnataka's Coorg region concentrates organic cultivation pipelines targeting North American natural channel buyers.
Brazil
Para and Bahia states offer underdeveloped acreage for organic certification pipelines serving institutional foodservice buyers in the United States. The country's national agricultural regulator monitors pesticide applications under Mercosur trade alignment pressures. Espirito Santo's emerging processing clusters experiment with cold plasma sterilization replacing legacy fumigation chambers.
Germany
Pharmaceutical formulators in Hamburg and Frankfurt specify supercritical CO2-derived piperine for residual-solvent compliance in nutraceutical applications. The EU Green Deal's carbon border adjustment mechanisms reward Vietnamese suppliers deploying decarbonized drying technologies. Rotterdam-connected traders in the Rhine-Ruhr corridor coordinate blockchain-enabled traceability platforms for premium segment procurement.
Pepper Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and extraction-technology dimensions. The market structures into three tiers: flavor houses with captive sourcing networks, bulk traders extending traceability platforms, and regional processors competing on sterilization compliance. Strategic moves concentrate on backward integration into farm-gate procurement and supercritical CO2 extraction capacity expansion.
Within the flavor extraction tier, Givaudan SA and McCormick & Company, Inc. exemplify archetypes differentiated by sourcing geography and end-use concentration. Olam International Limited occupies a position bridging bulk commodity flows with premium traceability services. Kerry Group plc and Kancor Ingredients Ltd. represent ingredient-systems specialists integrating pepper extracts into broader clean-label portfolios. These five entities anchor competitive dynamics across pharmaceutical-standard, foodservice, and retail channel specifications.
| Leading Market Players |
|---|
| Givaudan SA |
| Ajinomoto Co. Inc. |
| Olam International Limited |
| Kancor Ingredients Ltd. |
| Synthite Industries Private Limited |
| McCormick & Company, Inc. |
| Kerry Group plc |
| V. Sudhakar Group |
| Everest Spices Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Natural gas and biomass fuel costs for steam sterilization swing with Indonesian coal export policies, feeding directly into processor margin compression and forcing Vietnamese facilities to tier output across premium-certified, standard-grade, and economy lots.
Pricing Analysis
Piperine concentration thresholds anchor value-based pricing for pharmaceutical and cosmetic buyers. Three-tier pricing structure across premium, standard, and economy levels separates USP-grade oleoresin from food-grade powders and commodity auction material. Cost compression in standard-grade sterilization is intensifying because EU F-Gas Regulation compliance requires thermal retrofit investment. Institutional food manufacturers exhibit highest price sensitivity, while German pharmaceutical formulators accept premiums for residual-solvent compliance.
Supply Chain Analysis
Freight cost volatility on Vietnam-Europe routes exposes Rotterdam traders to bunker fuel surcharge swings and Red Sea logistics disruptions. Raw material sourcing draws from Binh Phuoc province cultivation, Lampung region white pepper fermentation, and Wayanad district organic pipelines. Single-source vulnerability concentrates in Vietnamese processing clusters dependent on monsoon-dependent harvests. Distribution runs through Hamburg and Rotterdam cold storage hubs serving Rhine-Ruhr pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around processors with capital to fund EU Green Deal sterilization retrofits, squeezing mid-scale competitors into contract manufacturing roles.
For Market Incumbents: Cement backward integration into Binh Phuoc farm-gate procurement to lock high-piperine supply before extraction competition intensifies. Expand supercritical CO2 capacity in Dong Nai industrial zones to capture pharmaceutical-grade premiums as steam-distillation margins erode under carbon border adjustment exposure.
For New Entrants and Emerging Players: Enter via Brazilian organic certification pipelines in Para state, where underdeveloped acreage and favorable rainfall patterns bypass Vietnamese supply concentration. Target North American natural channel buyers with traceability platforms that capture the premium spread over commodity auction grades.
For Investors and Strategic Acquirers: Vietnamese processor deployment of solar thermal drying arrays is the leading indicator that carbon-adjusted cost structures will separate viable exporters from stranded sterilization assets. Acquire mid-scale Indian exporters with Spices Board certification infrastructure but underutilized extraction capacity. Watch for EU carbon border adjustment mechanism enforcement timelines as consolidation triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Solar Thermal Retrofit | Vietnamese processors in Binh Duong zones capture EU carbon border adjustment premiums ahead of competitors. |
| Blockchain Traceability Platform | Madagascar and Indonesia specialty exporters secure thirty-to-fifty percent price premiums over commodity grades. |
| Supercritical CO2 Capacity Expansion | German pharmaceutical buyers specify residual-solvent-compliant piperine for nutraceutical formulations. |
| Organic Certification Pipeline | Brazilian Para state acreage unlocks North American natural channel procurement outside Vietnamese supply concentration. |
| Cold Plasma Sterilization Replacement | Espirito Santo processors depreciate legacy phosphine chambers ahead of EPA and EU biocide restrictions. |
Research Approach
Trade statistics from Vietnam's General Statistics Office, Indian Spices Board export certifications, and EU customs declarations formed the secondary backbone. Primary interviews with oleoresin extraction plant managers, pharmaceutical procurement leads at German formulators, Dutch retail category buyers, and Indonesian fermentation facility operators combined with this documentary base. Bottom-up cultivation area estimates and top-down trade flow analysis were triangulated against processor capacity disclosures.
Historical trendline analysis of Vietnamese export volumes, Indonesian white pepper premiums, and Indian oleoresin extraction capacity informed the analytical framework across the projection horizon. Segmentation dimensions modeled include piperine concentration grade, application end-use, extraction technology type, and regional regulatory cluster. CAGRs were derived from supply-demand balance equations incorporating sterilization retrofit timelines and pharmaceutical standardization trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under monsoon failure scenarios in Binh Phuoc and Dak Lak provinces or accelerated EU F-Gas Regulation phase-down schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Onion Essential Oil Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Global Clove Market