
 Vacuum Frying Machine Market | 2026-2036
Vacuum Frying Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Frying Machine Market Insights
Specialty snack manufacturers are reorganizing capital allocation toward vacuum frying lines as clean-label positioning becomes essential. Labh Group leverages its Indian manufacturing base to dominate domestic fruit chip processor contracts. Henan Huafood Machinery Technology Co., Ltd anchors the Chinese market through extensive R&D in automated batch systems. Vi Vacuum competes on compact footprint designs that suit emerging Southeast Asian processors with limited factory space.
A vacuum frying machine lowers the boiling point of water inside a sealed chamber operating at sub-atmospheric pressure, typically between 3–8 kPa absolute pressure, which permits frying at oil temperatures of 80–110°C rather than conventional 160–200°C ranges. This thermal reduction preserves heat-sensitive vitamins and limits acrylamide formation in finished chips. Batch vacuum fryers occupy the largest installed base due to lower capital barriers for entry-level processors, while continuous vacuum fryers represent the fastest-growing category as scaled snack brands pursue throughput above 500 kg per hour. Infrared heating technology segments command premium positioning because they reduce thermal degradation of frying oil and extend production runs between filter cycles.
EFSA oil oxidation thresholds and EU MDR-equivalent food contact material rules shape equipment design requirements for European exports. India's FSSAI enforcement of acrylamide limits in processed snacks is compelling domestic processors to replace atmospheric fryers with vacuum systems. Stakeholders must monitor how BIS certification timelines for imported vacuum chambers affect competitive lead times in the Indian market.
Market Dynamics
Clean-label snack positioning is forcing processors to retire atmospheric frying lines as EFSA acrylamide thresholds and FSSAI enforcement tighten simultaneously across Europe and India.
Growth Catalysts
- EFSA oil oxidation limits:European snack manufacturers face mandatory equipment replacement cycles as oxidation thresholds harden, accelerating vacuum fryer procurement.
- India's fruit chip boom:Domestic brands scaling processing capacity drive concentrated demand for batch systems suited to tropical fruit varieties.
- Infrared heating modules:Premium fryer configurations incorporating infrared technology extend oil life cycles and reduce filtration downtime.
Market Restraints
- Stainless steel price volatility:Vacuum chamber fabrication costs fluctuate with nickel and chromium input markets, compressing margins for equipment fabricators.
- Batch-to-continuous upgrade path:Entry-level processors face stranded asset risk when scaling beyond 200 kg per hour output thresholds.
- BIS certification timelines:Indian import clearance delays for pressure-rated vacuum vessels extend competitive lead times for foreign suppliers.
Strategic Opportunities
- Southeast Asian contract manufacturers:Compact footprint vacuum fryers address factory space constraints in Vietnam and Thailand's emerging snack processing clusters.
- PLI scheme alignment:India's production-linked incentive framework for food processing machinery rewards localized assembly of vacuum frying systems.
- Pharmaceutical-grade oil recovery:Convergence of vacuum frying with molecular distillation enables high-value oil reclamation for nutraceutical applications.
Industry Challenges
- Vacuum seal engineering talent:Specialized technicians capable of maintaining sub-atmospheric pressure integrity across production cycles remain scarce in emerging manufacturing bases.
- Legacy fryer integration:Retrofitting existing oil handling infrastructure to vacuum system specifications demands custom engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Frying Machine Market |
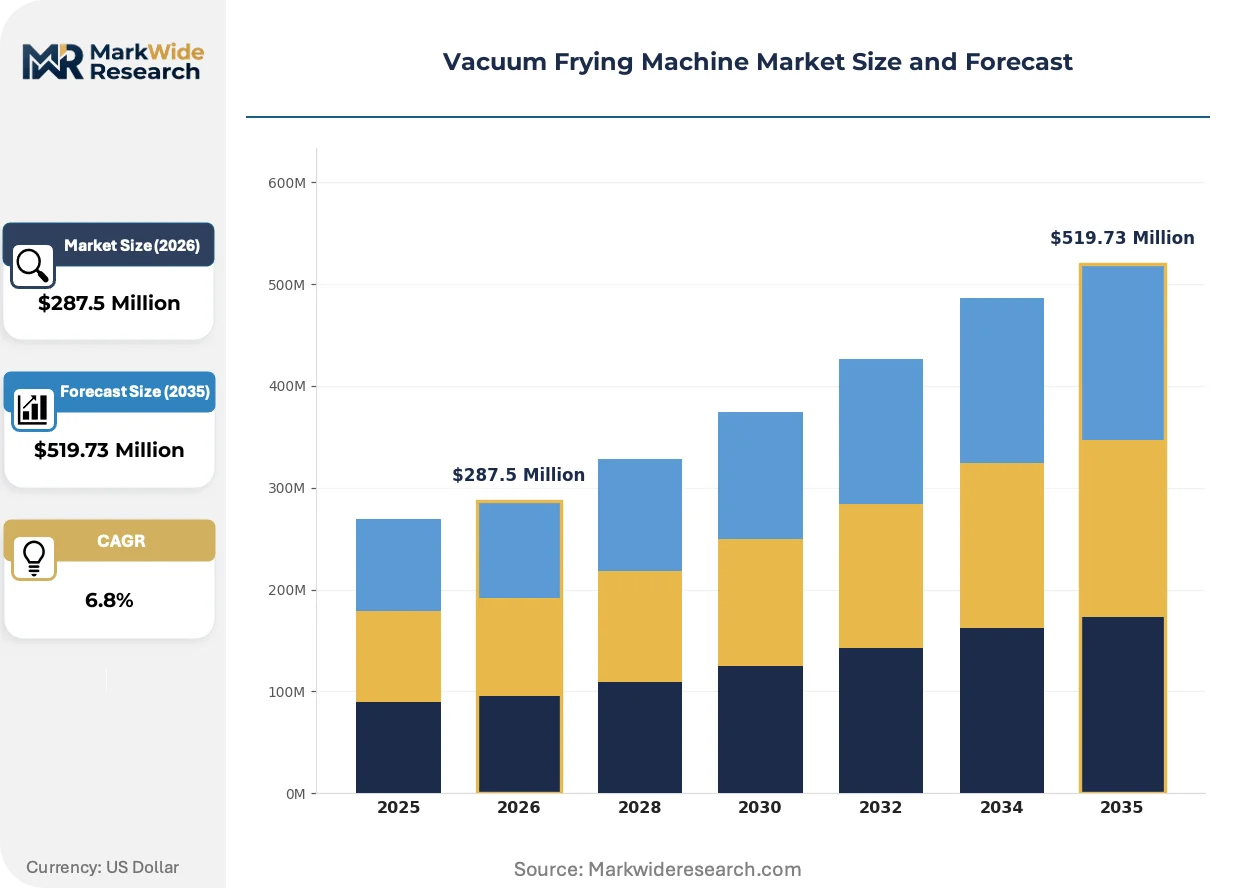
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $519.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Vacuum Fryers, Continuous Vacuum Fryers, Semi-Continuous Vacuum Fryers, Conveyor Vacuum Fryers Technology: Vacuum Pump System, Steam Heating, Oil Heating System, Infrared Heating, Microwave-Assisted Frying Application: Snack Food Production, Fruit Chips Processing, Vegetable Chips Processing, Meat Product Frying, Pet Food Preparation End User: Food Processing Plants, Specialty Snack Manufacturers, Industrial Kitchens, Catering Services |
| Companies Covered | Labh Group, Vi Vacuum, Henan Huafood Machinery Technology Co., Ltd, Qingdao Liuyi Machinery Co., Ltd., Jinan Tindo International Co., Ltd, Focus Technology Co., Ltd., Future Tech Foods India Private Limited, Dyna Vac Systems, Romiter Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Frying Machine Market Trends and Innovations
Equipment architecture is pivoting toward energy recovery and closed-loop oil management as operating cost pressures intensify and regulatory scrutiny on thermal emissions hardens.
Infrared-assisted heating arrays are displacing conventional thermal oil circulation in premium vacuum fryer configurations. Mid-scale snack processors in South Korea and Japan are adopting these systems to compress energy consumption per kilogram of finished product. The technology is displacing older resistance-heated designs in facilities where electricity costs exceed natural gas parity thresholds.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to abandon hydrofluorocarbon-based vacuum pumps in favor of dry screw or liquid ring alternatives. Equipment suppliers serving the European export market must redesign vacuum generation subsystems to maintain pumping speed at reduced refrigerant volumes. Batch fryer lines destined for EFTA markets now ship with dry pump configurations as standard.
Indian fruit chip processors are consolidating equipment procurement through equipment-leasing cooperatives rather than direct capital purchase. This channel innovation spreads vacuum fryer access to processors below 50 crore annual revenue thresholds. The model concentrates most visibly in Maharashtra and Karnataka, where horticultural cooperatives aggregate demand for shared processing infrastructure.
Vacuum Frying Machine Market Segmentation
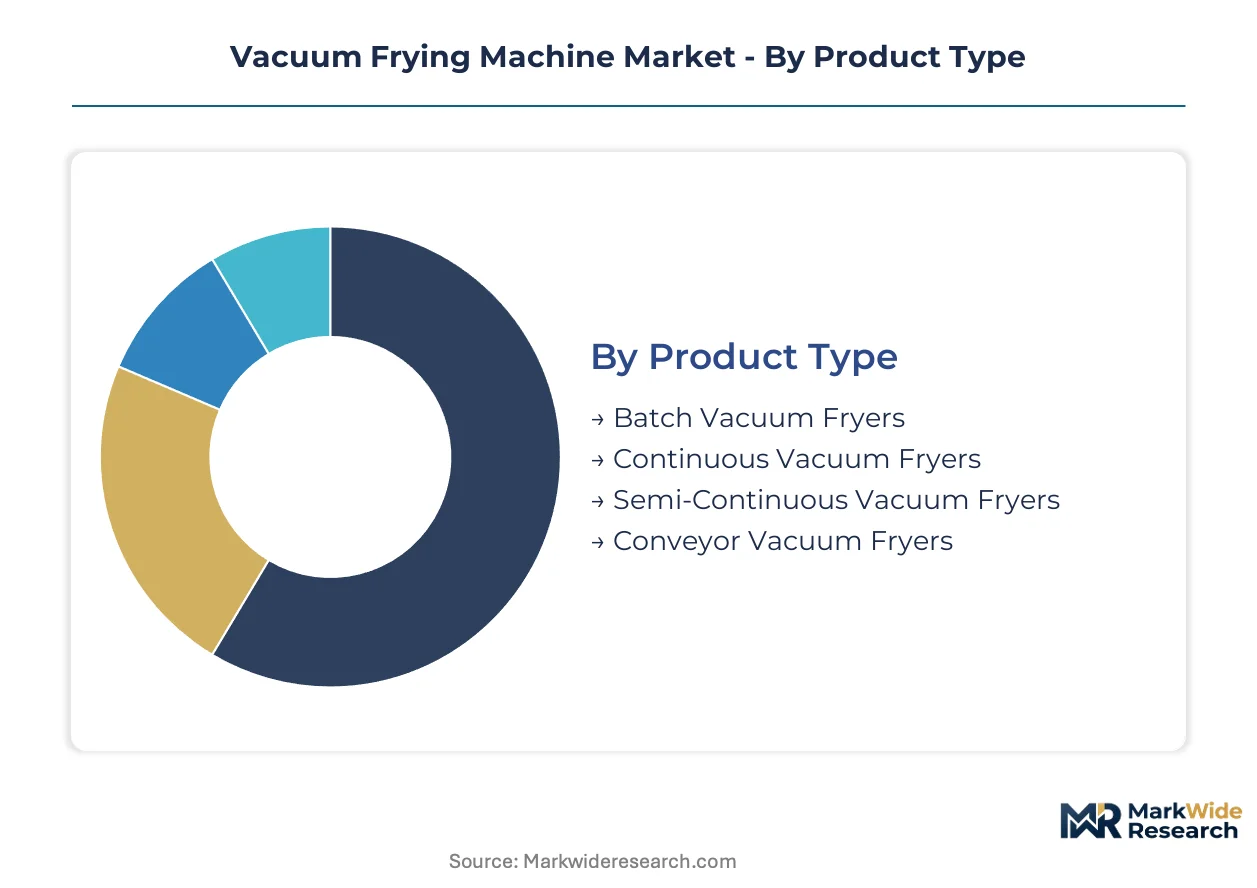
Vacuum frying machine segmentation reveals distinct procurement patterns across emerging and mature markets. Equipment specifications diverge sharply between export-oriented processors scaling for international certification and domestic operators optimizing for local fruit varieties.
Product Type:
Batch systems dominate procurement in India and Southeast Asian markets where factory footprints constrain installation options. Continuous lines concentrate in EU-facing export facilities where throughput requirements exceed 500 kg per hour.
- Batch Vacuum Fryers:Sealed chamber units operating at 3–8 kPa absolute pressure with manual loading cycles. Indian fruit chip processors in Maharashtra and Karnataka favor these systems for mango, banana, and jackfruit varieties where batch flexibility preserves texture integrity across seasonal harvest windows.
- Continuous Vacuum Fryers:Automated conveyor-fed systems enabling uninterrupted production runs. Vietnamese and Thai contract manufacturers serving European private-label brands deploy these configurations to meet EFSA acrylamide thresholds while sustaining volume commitments.
- Semi-Continuous Vacuum Fryers:Hybrid architectures with automated loading and batch-style frying chambers. Mid-scale South Korean processors use these for premium vegetable chip lines requiring frequent product changeovers.
- Conveyor Vacuum Fryers:Belt-driven continuous systems with integrated de-oiling stations. Japanese snack manufacturers specify these for delicate root vegetable applications where structural preservation determines export acceptance.
Batch Vacuum Fryers holds the largest share; momentum sits with Continuous Vacuum Fryers.
Technology:
Heating modality selection tracks energy pricing differentials and regulatory pressure on thermal emissions. Infrared and microwave-assisted configurations command premium positioning where electricity costs exceed natural gas parity.
- Infrared Heating:Radiant energy transfer reducing thermal degradation of frying oil and extending filter cycles. EU export-oriented processors specify these arrays to compress energy consumption per kilogram while satisfying F-Gas Regulation phase-down schedules through reduced thermal load on vacuum pumps.
- Vacuum Pump System:Sub-atmospheric pressure generation using dry screw or liquid ring alternatives. European installations now ship dry pump configurations as standard following refrigerant volume restrictions under EFTA market rules.
- Oil Heating System:Conventional thermal fluid circulation with resistance elements. Entry-level Indian processors favor these for lower capital barriers despite higher operating costs.
- Steam Heating:Indirect heat transfer through jacketed vessels. Japanese facilities with captive boiler infrastructure specify these for integration with existing steam distribution networks.
- Microwave-Assisted Frying:Electromagnetic energy supplementation accelerating moisture removal. South Korean R&D facilities pilot these configurations for experimental low-temperature meat product applications.
Vacuum Pump System configurations anchor the installed base; Infrared Heating is climbing the fastest.
Application:
End-use segmentation reflects raw material availability and export market access. Fruit chip processing concentrates in tropical supply zones while snack food production distributes across manufacturing clusters with brand development capabilities.
- Fruit Chips Processing:Vacuum frying of moisture-dense tropical and temperate fruits at 80–110°C. Indian domestic brands scaling capacity in Karnataka and Tamil Nadu drive concentrated equipment demand for mango, pineapple, and papaya varieties.
- Snack Food Production:Broad category encompassing extruded and formed products. European manufacturers retrofitting atmospheric lines to meet EFSA acrylamide limits represent the primary replacement market.
- Vegetable Chips Processing:Root vegetable and leafy green applications requiring precise moisture control. Japanese and South Korean processors lead adoption of infrared-heated systems for sweet potato and lotus root products.
- Meat Product Frying:Low-temperature protein processing for jerky and crisp applications. Limited deployment concentrated in specialized Thai and Vietnamese facilities serving regional markets.
- Pet Food Preparation:Novel protein and vegetable treat manufacturing. Emerging segment with pilot installations in US and EU specialty pet nutrition facilities.
Snack Food Production retains the broadest footprint; Fruit Chips Processing is gaining share fastest.
End User:
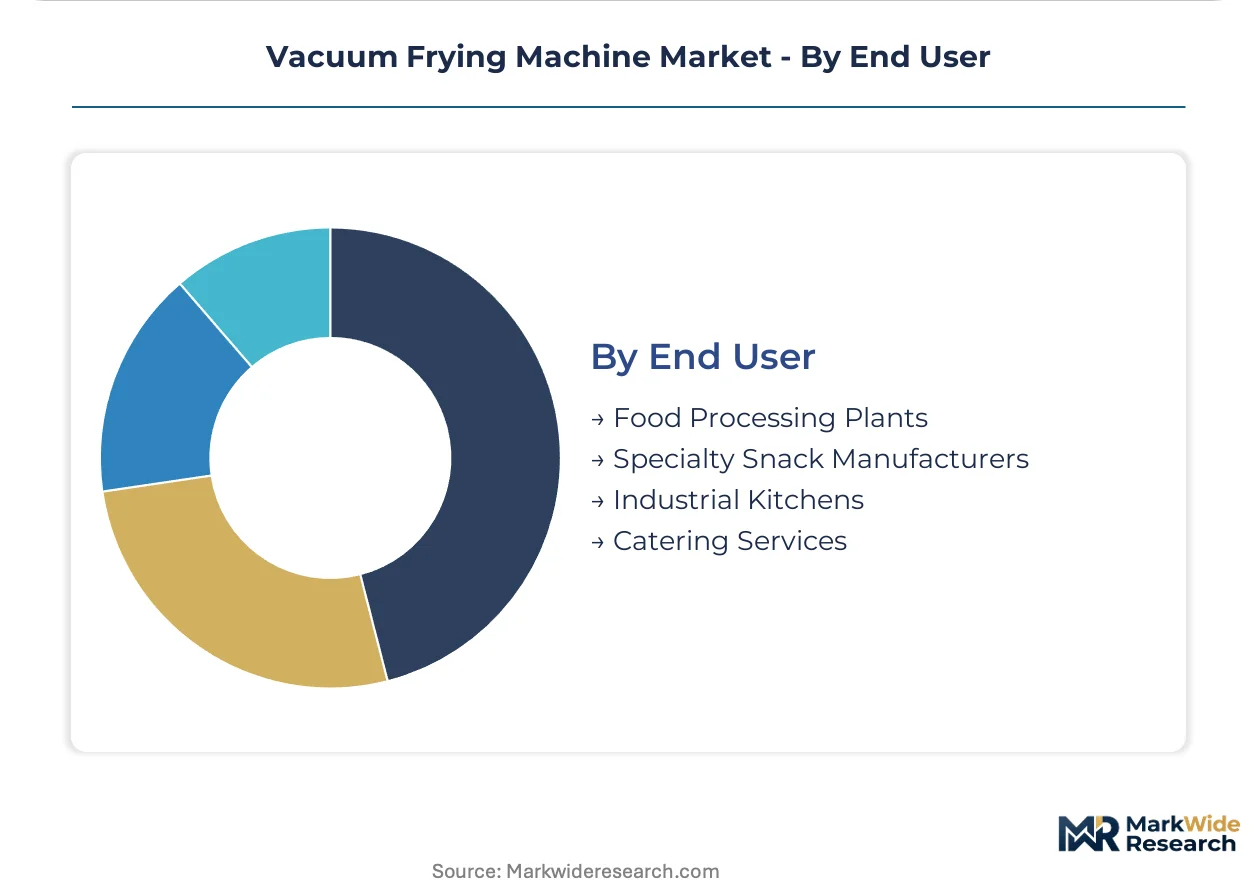
Customer type determines procurement channel and financing structure. Equipment-leasing cooperatives in India are reshaping access patterns for smaller processors below 50 crore annual revenue thresholds.
- Specialty Snack Manufacturers:Brand owners with clean-label positioning requirements. These operators prioritize infrared configurations and oil recovery systems to support premium pricing and extended production runs.
- Food Processing Plants:Integrated facilities with multiple product lines. Large-scale Indian and Southeast Asian operators in this category drive continuous fryer adoption for throughput above 500 kg per hour.
- Industrial Kitchens:Centralized preparation facilities for institutional feeding. Limited penetration concentrated in Japanese and South Korean corporate catering infrastructure.
- Catering Services:Small-batch operators with minimal current deployment. Potential expansion segment as equipment miniaturization reduces footprint requirements.
Food Processing Plants represent the largest installed base; Specialty Snack Manufacturers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Maharashtra handles critical stainless steel imports for vacuum chamber fabrication across South Asian manufacturing clusters. This maritime infrastructure underwrites India's dominant procurement position for tropical fruit processing equipment. The European network of inland waterways and the Rhine-Alpine corridor similarly enables just-in-time component delivery to German and Dutch fabricators serving EFSA-compliant export markets.
India
Maharashtra and Karnataka horticultural cooperatives are aggregating demand through equipment-leasing models that bypass traditional capital purchase barriers. FSSAI enforcement of acrylamide limits in processed snacks is compelling domestic processors to retire atmospheric fryers. Nashik and Bengaluru industrial corridors concentrate the fastest scaling fruit chip manufacturing capacity for mango, banana, and jackfruit varieties.
China
Henan and Shandong provinces anchor automated batch system production for both domestic snack brands and Southeast Asian export markets. SAMR oversight of food contact materials and pressure vessel safety standards shapes equipment design specifications. Zhengzhou and Qingdao manufacturing clusters are expanding continuous fryer output for Vietnamese and Thai contract manufacturers seeking EFSA-aligned throughput capabilities.
Germany
EFSA oil oxidation thresholds and EU F-Gas Regulation phase-down schedules are accelerating equipment replacement cycles among European snack manufacturers. The country's precision engineering base supplies dry screw vacuum pump configurations that displace hydrofluorocarbon-dependent alternatives. Bavarian and North Rhine-Westphalian industrial zones concentrate R&D investment in energy recovery systems for premium fryer configurations.
Vietnam
Emerging contract manufacturers serving European private-label brands are deploying continuous vacuum fryers to meet volume commitments above 500 kg per hour. The country's national food safety regulator is harmonizing domestic standards with EFSA acrylamide benchmarks. Ho Chi Minh City and Binh Duong processing clusters are absorbing compact footprint designs suited to constrained factory spaces.
Japan
Premium vegetable chip processors in Kanto and Kansai regions specify infrared-heated systems for sweet potato and lotus root applications where structural preservation determines export acceptance. METI energy efficiency guidelines are compressing adoption timelines for resistance-heated design replacements. Nagoya industrial corridors integrate vacuum frying lines with captive boiler infrastructure through steam heating configurations.
Vacuum Frying Machine Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D scale, creating a tiered structure where public company balance sheets fund continuous system development while private fabricators retain agility in batch configuration customization. The vendor base clusters around three strategic archetypes: diversified food machinery conglomerates with cross-product line synergies, vacuum technology pure-plays leveraging sub-atmospheric pressure engineering depth, and regional fabricators capturing procurement proximity advantages. Dominant competitive moves include backward integration into stainless steel component forging to hedge nickel price volatility, and strategic partnerships with horticultural cooperatives to secure equipment-leasing distribution channels.
Within the diversified machinery tier, Labh Group and Henan Huafood Machinery Technology Co., Ltd represent contrasting geographic anchors for Indian and Chinese market capture respectively. Vi Vacuum exemplifies the compact footprint specialization vector targeting Southeast Asian processors with spatial constraints. These three fabricators illustrate how competitive positioning diverges between scale-driven continuous system deployment and flexible batch configuration responsiveness to seasonal tropical fruit harvest windows.
| Leading Market Players |
|---|
| Labh Group |
| Vi Vacuum |
| Henan Huafood Machinery Technology Co., Ltd |
| Qingdao Liuyi Machinery Co., Ltd. |
| Jinan Tindo International Co., Ltd |
| Focus Technology Co., Ltd. |
| Future Tech Foods India Private Limited |
| Dyna Vac Systems |
| Romiter Machinery Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day BIS certification lead times for pressure-rated vacuum vessels imported into India compress pricing power for foreign fabricators while amplifying margin capture for domestic suppliers with forged stainless steel capabilities. This inventory friction concentrates procurement decisions around regional assembly footprints and shapes how equipment tiers compete on total landed cost versus specification parity.
Pricing Analysis
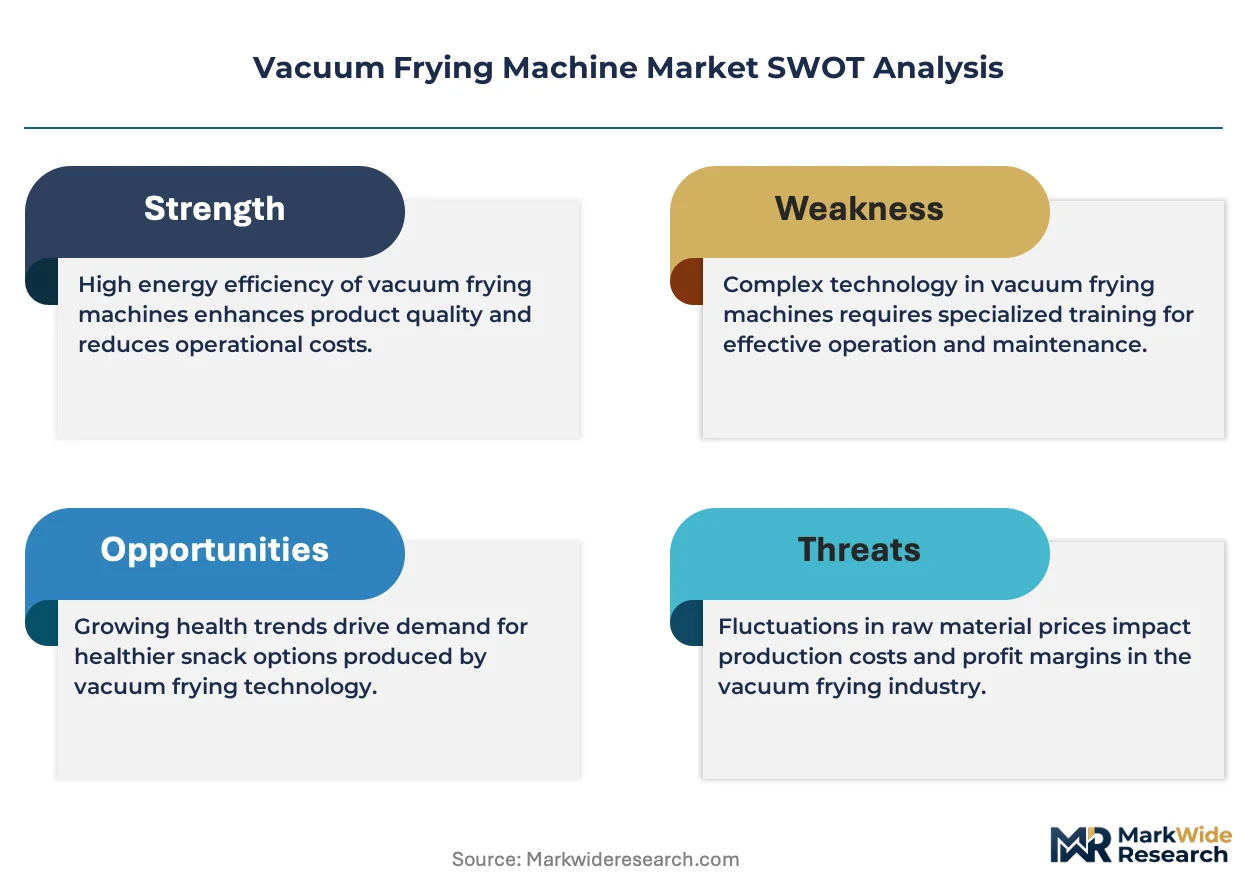
Three-tier pricing structure across premium, standard, and economy levels segments the vacuum frying machine market by certification grade and after-sales bundling intensity. Premium infrared-heated configurations with EU F-Gas Regulation-aligned dry pump systems command substantial markups over resistance-heated economy tiers favored by entry-level Indian fruit chip processors. Pricing pressure stems from nickel and chromium volatility in stainless steel feedstock costs, which compresses fabricator margins across all tiers. Small-scale horticultural cooperatives below 50 crore annual revenue exhibit the highest price sensitivity, while export-oriented contract manufacturers in Vietnam and Thailand prioritize specification compliance over unit economics.
Supply Chain Analysis
Jawaharlal Nehru Port Trust stainless steel import throughput anchors vacuum chamber fabrication capacity across South Asian manufacturing clusters. Equipment assembly draws from Chinese precision components, Indian forged vessel production, and German dry screw vacuum pump engineering. Single-source vulnerability concentrates in specialty nickel alloys for corrosion-resistant chamber linings, where Indonesian and Philippine mining output fluctuations transmit directly to fabrication cost curves. Distribution runs through equipment-leasing cooperatives in Maharashtra and Karnataka that aggregate demand from fragmented domestic processors, alongside direct OEM sales to scaled export facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum frying machine adoption sits in early-cycle expansion as FSSAI acrylamide enforcement and EFSA oil oxidation thresholds simultaneously compel atmospheric fryer replacement across India and Europe. Clean-label snack positioning has crossed from premium niche to baseline procurement criterion, widening the addressable equipment base beyond early-mover specialty manufacturers.
For Market Incumbents: Consolidate backward integration into stainless steel component forging to hedge nickel price volatility and compress BIS certification timelines for Indian market access. Lock in exclusive equipment-leasing partnerships with Maharashtra and Karnataka horticultural cooperatives before foreign competitors establish local assembly footprints. Prioritize dry screw vacuum pump R&D to maintain specification leadership as EU F-Gas Regulation phase-down schedules harden. For New Entrants and Emerging Players: CE marking fast-track programs for compact footprint batch systems open immediate access to Vietnamese and Thai contract manufacturers with constrained factory space. Target semi-continuous configurations for South Korean mid-scale processors requiring frequent product changeovers, where established players have underinvested in flexible automation. Lead with infrared heating module retrofit kits as lower-capital entry points that demonstrate oil life extension before full system replacement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food machinery conglomerates with underperforming vacuum technology divisions that lack clean-label snack market focus. Five-to-ten-year viability hinges on regulatory harmonization trajectories rather than commodity demand cycles. Monitor BIS certification timeline compression as the inflection signal for competitive repositioning in Indian procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forging | Captive nickel alloy supply hedges raw material volatility for vacuum chamber fabrication. |
| Equipment-Leasing Cooperative Partnerships | Channel control in Maharashtra and Karnataka aggregates fragmented horticultural processor demand. |
| Dry Screw Vacuum Pump R&D Investment | EFTA market access requires F-Gas Regulation compliance without hydrofluorocarbon dependency. |
| Compact Footprint Batch System Launch | Vietnamese and Thai factory space constraints favor sub-100 square meter installation footprints. |
| Infrared Heating Retrofit Kit Development | Low-capital entry path demonstrates oil life extension before full continuous system commitment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade records, SAMR pressure vessel safety filings, and FSSAI processed snack enforcement circulars. Equipment manufacturer interviews with plant engineers and aftermarket service heads combined with snack processor discussions with maintenance directors and procurement leads. Secondary validation drew from BIS certification databases, EFSA acrylamide monitoring reports, and EU F-Gas Regulation implementation guidance. Bottom-up installation base counts triangulated against top-down capital expenditure estimates from food processing machinery trade associations.
Segmentation dimensions modeled include product type architecture, heating modality technology, end-use application, and customer scale tier across the projection horizon. CAGRs derived from equipment shipment trajectories weighted by regional regulatory enforcement intensity and replacement cycle timing. Industry-specific forecast inputs incorporated PLI scheme disbursement schedules for Indian food processing machinery and seasonal tropical fruit harvest windows that drive batch system utilization rates.
Decision-makers should treat outputs as directional under stable nickel pricing and sustained FSSAI enforcement intensity assumptions; material deviation would warrant model refresh. Specific risks that could revise forecasts include abrupt BIS certification timeline extensions, EU F-Gas Regulation acceleration, or horticultural cooperative leasing model collapse. Practitioners should keep alternative scenarios live as clean-label snack penetration rates and stainless steel supply chain reconfiguration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Ribbon Blenders Market