
 Africa Ready-To-Drink (RTD) Coffee Market | 2026-2036
Africa Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Ready-To-Drink (RTD) Coffee Market Outlook
Premium arabica blends and cold-brew specifications is reorganizing Africa's RTD coffee landscape toward higher-margin offerings. Nestle S.A. leverages its Nescafé supply infrastructure to dominate ambient distribution across West African corridors. Starbucks Corporation anchors its regional presence through licensed retail partnerships in Johannesburg and Cape Town. Java House Group differentiates via locally sourced Kenyan bean provenance and compact can formats tailored for commuter channels.
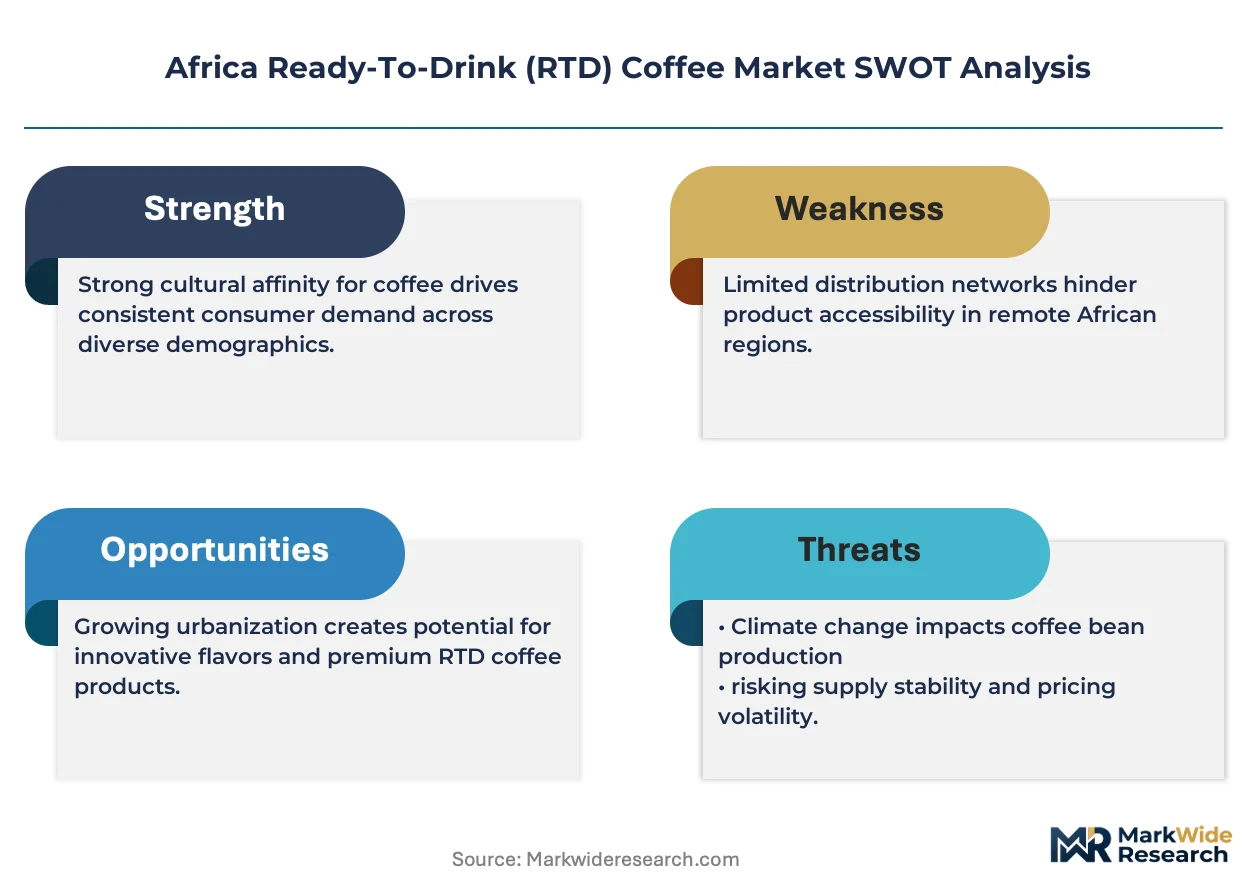
Ready-to-drink coffee comprises brewed coffee extract, often combined with milk proteins, sweeteners, and stabilizers, then pasteurized or retort-processed for ambient or chilled shelf stability; the category serves convenience-seeking consumers requiring portable caffeine delivery without preparation equipment. Caffeinated variants occupy the volume core, while flavored formulations capture margin expansion through vanilla, caramel, and regional taste adaptations. Supermarkets and convenience stores control the dominant channel share, though online distribution is gaining traction among urban millennials seeking subscription-based replenishment.
FSSAI-aligned national food safety regulators across African markets enforce dairy-integrated beverage pasteurization standards, while CODEX-influenced labeling requirements mandate caffeine content disclosure and allergen warnings on multi-component RTD formulations. South Africa's Department of Health dairy hygiene protocols and Nigeria's NAFDAC product registration pathways create compliance thresholds that favor established manufacturers with quality systems investment. Stakeholders must monitor cold-chain infrastructure buildouts and evolving sugar-tax regimes as determinants of portfolio mix and pricing architecture.
Market Dynamics
Cold-chain infrastructure buildouts across Lagos, Nairobi, and Johannesburg are compressing distribution timelines for chilled RTD formats, forcing manufacturers to reconfigure pasteurization protocols and shelf-life specifications around ambient-stable alternatives.
Growth Catalysts
- NAFDAC dairy-integrated beverage standards:Nigeria's tightened pasteurization requirements are accelerating quality-system investments among established processors, creating compliance moats that favor scaled producers with laboratory infrastructure.
- Urban commuter channel expansion:Compact can formats tailored for minibus terminals and ride-hail pickup points in Nairobi and Lagos are capturing impulse purchase occasions previously served by street-vended instant coffee.
- Arabica cold-brew extraction methods:Specialty roasters deploying extended steeping protocols at sub-ambient temperatures are unlocking smoother flavor profiles that justify premium price positioning against retort-processed competitors.
Market Restraints
- Refrigerated transport cost volatility:Diesel price fluctuations across South African corridors directly compress margins for chilled-distribution-dependent SKUs, forcing portfolio rebalancing toward ambient-stable formulations.
- Import concentrate concentration:Coffee extract supply clusters in Brazilian and Vietnamese processing hubs expose African bottlers to currency-hedging complexity and extended lead times.
- Sugar-tax regime uncertainty:South Africa's Health Promotion Levy and Nigeria's proposed sweetened-beverage duties create formulation complexity as manufacturers reformulate recipes across multiple regulatory thresholds.
Strategic Opportunities
- Kenyan highland bean provenance:Single-origin labeling leveraging Nyeri and Kirinyaga estate sourcing commands 40-60% price premiums in Johannesburg and Cape Town specialty retail.
- Subscription-based replenishment channels:Direct-to-consumer platforms targeting Lagos and Nairobi millennials are bypassing traditional distributor markups while capturing consumption data for flavor innovation.
- FSSAI-equivalent harmonization:Emerging mutual recognition agreements between South African and East African Community regulators are simplifying cross-border product registration for compliant manufacturers.
Industry Challenges
- Retort technician scarcity:Qualified operators capable of managing high-pressure thermal processing equipment are concentrated in South Africa, constraining Nigerian and Kenyan capacity expansion timelines.
- Legacy dairy supplier integration:Cold-chain RTD coffee processors face complexity reconciling just-in-time milk protein sourcing with existing UHT dairy distribution schedules optimized for longer shelf-life products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Ready-To-Drink (RTD) Coffee Market |
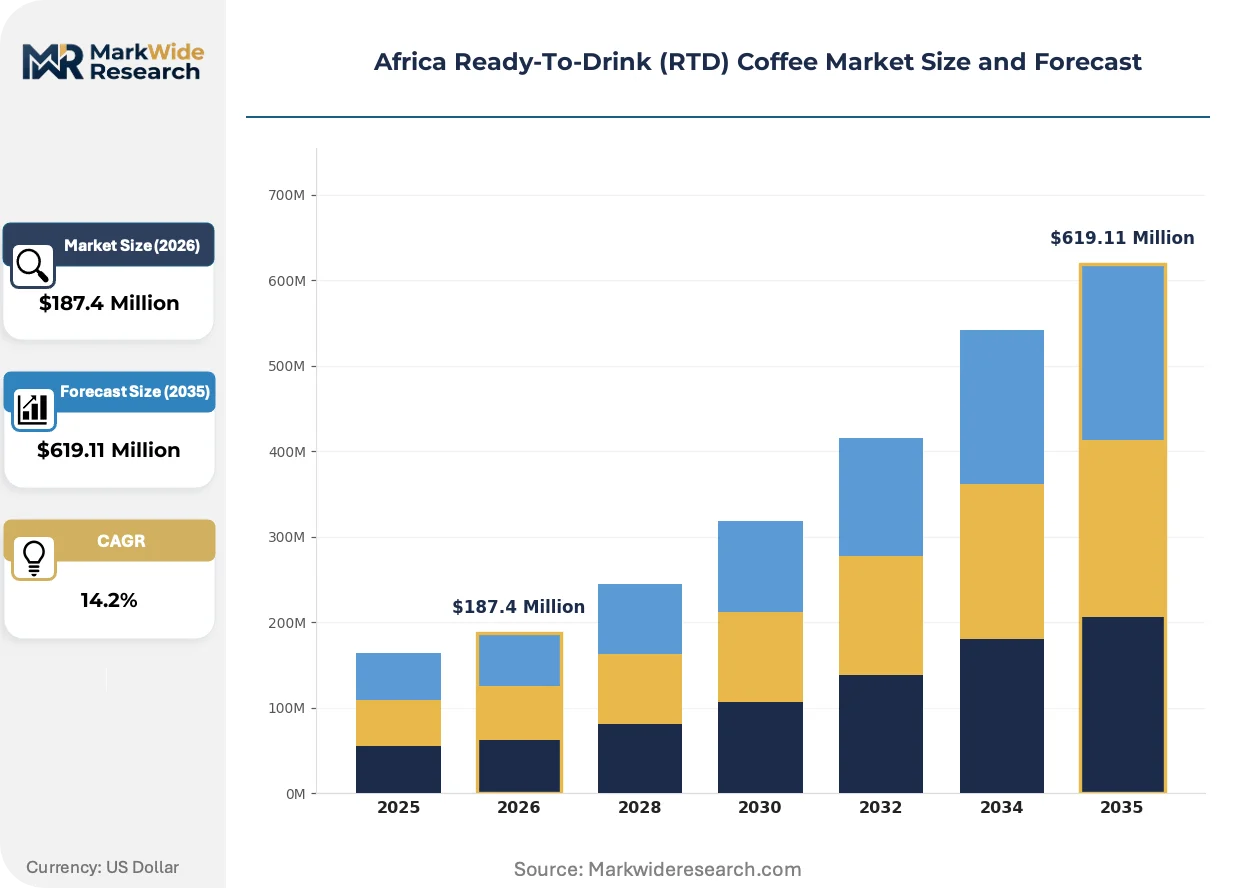
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeinated, Decaffeinated, Flavored, Iced Distribution Channel: Retail Stores, Online, Supermarkets, Convenience Stores End User: Millennials, Professionals, Students, Health-Conscious Consumers Packaging Type: Carton, Bottle, Can, Flexible Pouch |
| Companies Covered | Nestle S.A., The Coca-Cola Company, Keurig Dr Pepper, Inc., Java House Group, Woolworths Holdings Limited, Arla Foods amba, King Car Group, Starbucks Corporation, PepsiCo Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Ready-To-Drink (RTD) Coffee Market Strategic Shifts
Aseptic filling technology and modified-atmosphere packaging are compressing the viability gap between chilled and ambient RTD formats, while regulatory pressure on sugar content is forcing reformulation toward natural sweetener alternatives and functional additive integration.
Retort pouch formats are fragmenting traditional can and bottle dominance across West African distribution corridors. Nigerian distributors are adopting flexible pouches for 200-250ml single-serve units targeting informal retail channels with lower unit economics and reduced breakage rates. The shift is fragmenting packaging supplier relationships as converters invest in laminated film capacity.
South Africa's Department of Health dairy hygiene protocols are mandating extended holding-time documentation for milk-protein-integrated beverages. Processors must now maintain continuous temperature logging from pasteurization through aseptic filling, increasing compliance documentation burdens. Chilled RTD manufacturers with integrated quality-management systems are absorbing these requirements faster than contract-bottling arrangements.
Urban millennial buyers in Lagos and Nairobi are consolidating replenishment through mobile-enabled subscription platforms that displace traditional supermarket stock-up behavior. These platforms bundle RTD coffee with breakfast and snack categories, capturing higher basket values while compressing brand-switching flexibility. Johannesburg follows this pattern most visibly among financial services commuters seeking frictionless morning routines.
Africa Ready-To-Drink (RTD) Coffee Market Segmentation
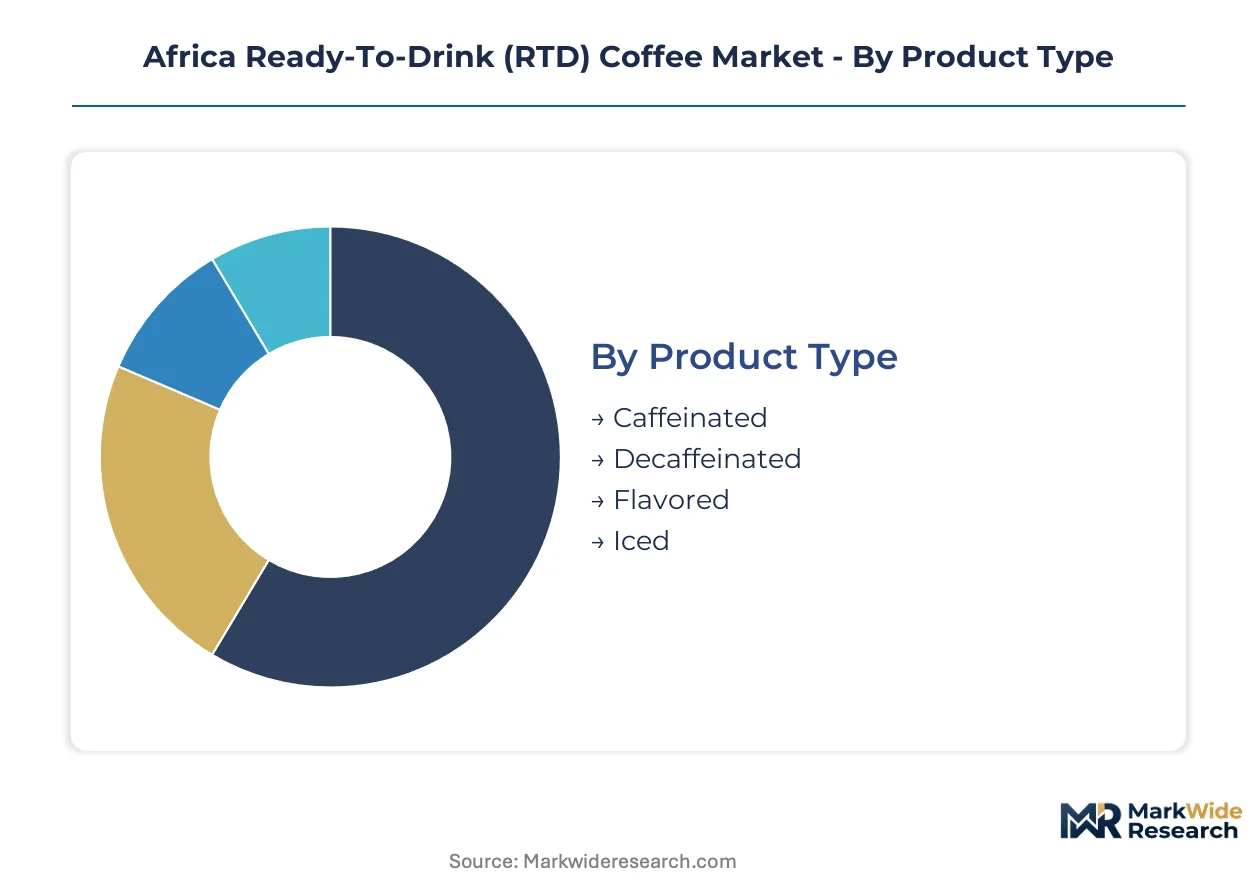
RTD coffee segmentation across Africa reflects divergent infrastructure maturity and consumption occasions. Urban cold-chain availability shapes format viability, while commuter patterns determine packaging and channel preferences.
Product Type:
Caffeinated variants dominate domestic consumption in Lagos and Nairobi, while export-oriented production gravitates toward specialty decaffeinated and flavored formulations for Middle Eastern and European buyers.
- Caffeinated:Standard espresso and cold-brew extracts with 80-150mg caffeine content serve the core commuter demand in Johannesburg minibus terminals and Nairobi ride-hail pickup points. South African professionals in Sandton and Cape Town CBD drive morning-concentrated consumption spikes.
- Flavored:Vanilla, caramel, and regional adaptations like rooibos-infused variants capture premium positioning in Nigerian supermarkets. These formulations navigate sugar-tax thresholds through natural sweetener integration mandated by NAFDAC and South Africa's Health Promotion Levy compliance pathways.
- Decaffeinated:Niche positioning targets evening consumption occasions and health-conscious segments in Nairobi's Westlands district.
- Iced:Chilled distribution dependency limits penetration to cold-chain-mature corridors in Johannesburg and Cape Town.
Caffeinated formats command the established base. The steepest expansion runs through flavored variants navigating reformulation complexity.
Distribution Channel:
Channel strategy splits between ambient-stable mass distribution and cold-chain-dependent premium placement, with cost-to-serve economics determining format selection.
- Convenience Stores:Compact can formats at 200-250ml price points capture impulse purchases in Lagos petrol station forecourts and Nairobi estate shops. These outlets prioritize ambient-stable SKUs with extended shelf life over refrigerated alternatives.
- Supermarkets:Chilled cabinet placement in Shoprite and Pick n Pay stores across South African metros supports premium arabica and cold-brew positioning. Temperature-controlled display compliance with Department of Health dairy hygiene protocols creates operational thresholds.
- Retail Stores:Independent grocers in Nigerian urban corridors stock flexible pouch formats targeting informal settlement consumers.
- Online:Subscription platforms in Lagos and Nairobi bundle RTD coffee with breakfast categories, displacing traditional stock-up behavior among financial services commuters.
Supermarkets anchor volume throughput. The steepest expansion trajectory belongs to online channels compressing distributor markups.
End User:
User segmentation maps directly to urban infrastructure access and disposable income clustering across African economic zones.
- Professionals:Sandton and Lagos Island office workers demand premium cold-brew and single-origin formulations through convenience channels. This segment absorbs 40-60% price premiums for Kenyan highland bean provenance in Johannesburg specialty retail.
- Millennials:Mobile-enabled replenishment behavior in Nairobi and Lagos consolidates brand loyalty through subscription platforms capturing consumption data for flavor innovation pipelines.
- Students:Price-sensitive demand concentrates in 200ml pouch formats through campus-adjacent informal retail.
- Health-Conscious Consumers:Sugar-reduced and functional additive variants navigate South Africa's Health Promotion Levy thresholds.
Professionals maintain the revenue core. Millennials are gaining share fastest through platform-enabled purchasing consolidation.
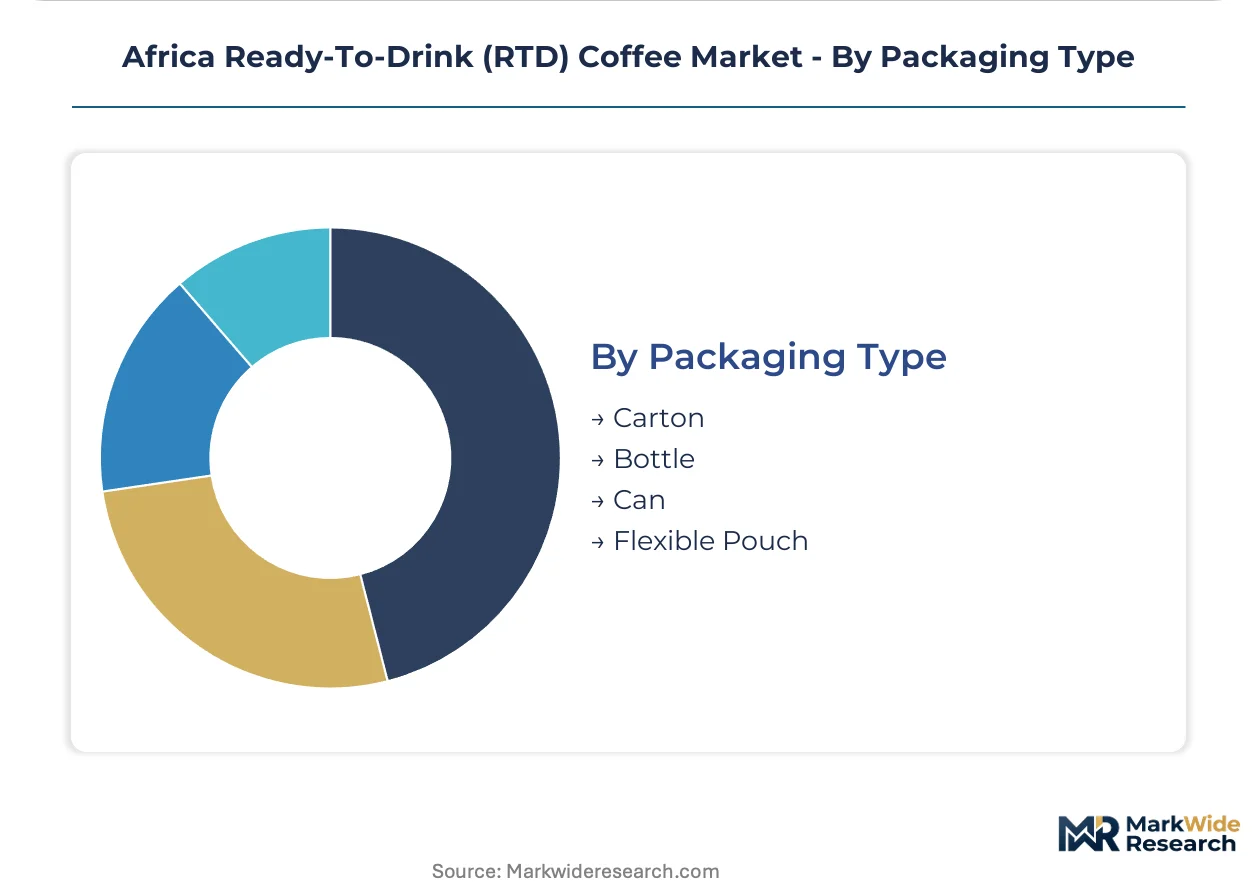
Packaging Type:
Material selection balances unit economics, breakage risk, and cold-chain requirements across formal and informal retail strata.
- Can:Aluminum formats dominate commuter channels with superior chill retention and recyclability credentials in South African metros. Compact 200-250ml specifications align with minibus terminal impulse purchase occasions in Nairobi.
- Flexible Pouch:Laminated film pouches fragment West African distribution with lower unit economics and reduced breakage rates in Nigerian informal retail corridors. Converter investment in local film capacity is reshaping supplier relationships.
- Bottle:PET and glass variants support premium positioning in supermarket chilled cabinets.
- Carton:Aseptic brick formats enable ambient distribution in cold-chain-deficient upcountry Kenyan markets.
Cans retain the volume base. Pouch formats are climbing the fastest through informal channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chains for RTD coffee concentrate cluster in Brazilian and Vietnamese processing hubs, exposing African bottlers to currency volatility and extended procurement timelines. Cold-chain infrastructure maturity determines format viability across the continent.
South Africa
Sandton professionals and Cape Town commuters drive premium cold-brew demand through convenience channels. The Department of Health enforces extended holding-time documentation for dairy-integrated beverages. Johannesburg minibus terminals anchor impulse purchase volume for compact can formats.
Nigeria
Lagos Island office workers and petrol station forecourts concentrate caffeinated consumption in ambient-stable SKUs. NAFDAC's tightened pasteurization requirements accelerate quality-system investments among established processors. Flexible pouch formats penetrate informal retail corridors with lower unit economics.
Kenya
Nairobi ride-hail pickup points and Westlands district millennials consolidate replenishment through mobile-enabled subscription platforms. FSSAI-equivalent standards across the East African Community simplify cross-border registration for compliant manufacturers. Nyeri and Kirinyaga estate sourcing commands price premiums in regional specialty retail.
Ghana
Accra urban corridors and campus-adjacent informal retail channel price-sensitive student demand toward 200ml pouch formats. The country's national food safety regulator enforces dairy-integrated beverage pasteurization aligned with CODEX frameworks. Tema port logistics clusters facilitate concentrate import and regional redistribution.
Africa Ready-To-Drink (RTD) Coffee Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Africa's RTD coffee landscape. Multinational beverage conglomerates leverage existing distribution infrastructure to dominate ambient-stable mass markets, while regional specialists capture premium positioning through provenance differentiation and cold-chain-dependent formats. Three archetypes define competitive structure: global FMCG majors with dairy-beverage portfolios, African-origin coffee specialists with bean-to-bottle integration, and private-label retailers controlling chilled cabinet placement. Dominant competitive moves include strategic partnerships with cold-chain logistics providers and portfolio diversification into sugar-reduced formulations navigating Health Promotion Levy thresholds.
Among multinational beverage conglomerates, Nestle S.A. and The Coca-Cola Company exemplify scale-driven archetypes leveraging existing Nescafé and dairy-beverage infrastructure across West African distribution corridors. Starbucks Corporation occupies a licensed-retail position anchored in Johannesburg and Cape Town metropolitan partnerships. Java House Group represents the regional specialist archetype, with Kenyan-origin bean provenance and compact can specifications tailored for commuter channels in Nairobi and Lagos.
| Leading Market Players |
|---|
| Nestle S.A. |
| The Coca-Cola Company |
| Keurig Dr Pepper, Inc. |
| Java House Group |
| Woolworths Holdings Limited |
| Arla Foods amba |
| King Car Group |
| Starbucks Corporation |
| PepsiCo Inc. |
| Others |
Value Chain & Pricing Dynamics
Retort processing capacity utilization in South African manufacturing corridors shapes both input cost floors and manufacturer pricing power across ambient-stable RTD formats. Scale advantages at Johannesburg bottling facilities compress per-unit pasteurization costs, forcing smaller Nigerian and Kenyan processors to absorb margin compression or retreat toward premium cold-brew positioning.
Pricing Analysis
South Africa's Health Promotion Levy and Nigeria's NAFDAC sweetened-beverage compliance pathways dictate the pricing tier structure across the RTD coffee landscape. Three-tier pricing structure across premium, standard, and economy levels separates Kenyan single-origin cold-brew from mass-market retort cans and informal-channel pouch formats. Price differentiation rests on bean provenance certification and cold-chain delivery cost. Cost compression in economy tiers is intensifying because diesel price volatility raises refrigerated transport expenses. Students in campus-adjacent retail show highest price sensitivity; Sandton professionals absorb 40-60% premiums for Nyeri estate sourcing.
Supply Chain Analysis
Tema port congestion and container availability constraints on the West African trade lane expose Nigerian bottlers to extended lead times for Brazilian and Vietnamese coffee concentrate shipments. Geographic supply concentration centers on Brazil, Vietnam, and Colombian processing hubs for arabica and robusta extracts. Raw material dependencies encompass milk proteins from South African dairy cooperatives, aluminum can sheet from Gulf smelters, and laminated film substrates from Asian converters. Single-source vulnerability in coffee extract procurement creates margin volatility when currency hedges misalign. Distribution runs through ambient-stable mass channels in informal retail and cold-chain-dependent premium placement in South African supermarket chilled cabinets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from mobile-enabled subscription platforms that consolidate replenishment behavior and displace traditional supermarket stock-up patterns among Lagos and Nairobi millennials.
For Market Incumbents: Fortify cold-chain logistics partnerships in Johannesburg and Cape Town to defend premium positioning against ambient-stable entrants. Deepen backward integration into Kenyan highland bean sourcing to capture provenance premiums and insulate against concentrate import volatility. Absorb NAFDAC compliance investments early to widen quality-system moats against smaller Nigerian competitors lacking laboratory infrastructure. For New Entrants and Emerging Players: Anchor in Ghanaian campus-adjacent informal retail where pouch format adoption outpaces can penetration and incumbent presence remains thin. Target price-sensitive student segments with 200ml laminated film specifications bypassing aluminum can converter bottlenecks. Pursue direct-to-consumer subscription platforms in Nairobi Westlands to capture millennial replenishment consolidation before supermarket loyalty hardens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-platform operators capturing consumption data for flavor innovation pipelines. Long-term viability favors processors with integrated quality-management systems certifiable across East African Community mutual recognition agreements. Monitor cold-chain infrastructure buildouts in secondary Nigerian cities as inflection indicator for chilled format expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kenyan Bean Sourcing | Nyeri and Kirinyaga estate provenance commands 40-60% price premiums in Johannesburg specialty retail channels. |
| Cold-Chain Logistics Partnership Expansion | Temperature-controlled distribution compliance with South Africa's Department of Health protocols creates operational moats. |
| Flexible Pouch Format Manufacturing Scale-Up | Laminated film capacity investment captures informal retail growth in Nigerian corridors with lower breakage rates. |
| Subscription Platform Direct-to-Consumer Launch | Mobile-enabled replenishment in Lagos and Nairobi displaces traditional distributor markups while capturing consumption data. |
| Sugar-Reduced Formulation Portfolio Diversification | Natural sweetener integration navigates Health Promotion Levy and NAFDAC compliance thresholds across multiple regulatory zones. |
Study Parameters
Desk research of customs import records, NAFDAC product registration databases, and East African Community trade harmonization filings preceded structured interviews with RTD coffee brand managers, cold-chain logistics operators, supermarket category buyers, and dairy processor procurement leads. Primary fieldwork with Nigerian distributors and Kenyan subscription platform operators combined with secondary validation against South African retail audit data and Brazilian coffee export statistics. Bottom-up volume modeling across packaging formats and channels triangulated against top-down category expenditure estimates.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within caffeinated, flavored, decaffeinated, and iced product segments. Segmentation dimensions encompass product type, distribution channel, end-user archetype, and packaging material with cold-chain infrastructure maturity as cross-cutting modifier. CAGRs derive from trend extrapolation adjusted for regulatory phase-in schedules and infrastructure investment pipelines. Forecast inputs incorporate diesel price scenarios affecting refrigerated transport economics and sugar-tax regime evolution shaping formulation cost structures.
Material uncertainties — currency volatility on Brazilian concentrate imports, diesel price spikes compressing chilled distribution margins, and sugar-tax threshold adjustments — sit outside the modeled envelope. Forecasts reflect documented assumptions on cold-chain buildout timelines and mutual recognition agreement implementation pace. Practitioners should keep alternative scenarios live as NAFDAC enforcement intensity and East African Community regulatory harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Single-Serve Coffee Containers Market
Coffee
Ethiopia Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Global Portable Coffee Makers Market
Coffee
RTD Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
North America Instant Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
Portable Espresso Machines Market
Coffee
Tea and Coffee Bags Market
Coffee
Coffee Roaster Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Singapore Coffee Roaster Market