
 Asia-Pacific Coffee Franchise Market | 2026-2036
Asia-Pacific Coffee Franchise Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Coffee Franchise Market Insights
Barista workforce shortages across Indonesia and Vietnam are reorganizing how franchises approach training pipelines and automation. Starbucks Corporation leverages its global academy infrastructure to sustain talent quality in premium locations. Kopi Kenangan anchors its expansion in Jakarta and Surabaya through localized recruitment programs. Cotti Coffee competes aggressively on speed-to-hire, differentiating through simplified equipment that reduces skill barriers for new staff.
The Asia-Pacific coffee franchise sector comprises licensed business formats where operators pay fees to replicate branded cafe concepts, typically requiring espresso machines with pressure ratings of 9-15 bars and bean-to-cup cycle times under 60 seconds for throughput targets. The franchise model segment splits across single-unit licenses and multi-unit development agreements, with area development rights commanding higher upfront capital but delivering faster regional penetration. Product offering dynamics favor specialty coffee and cold brew formats where margin pools exceed instant coffee by significant multiples, while service type evolution pushes delivery and online ordering infrastructure as the fastest-growing revenue channel.
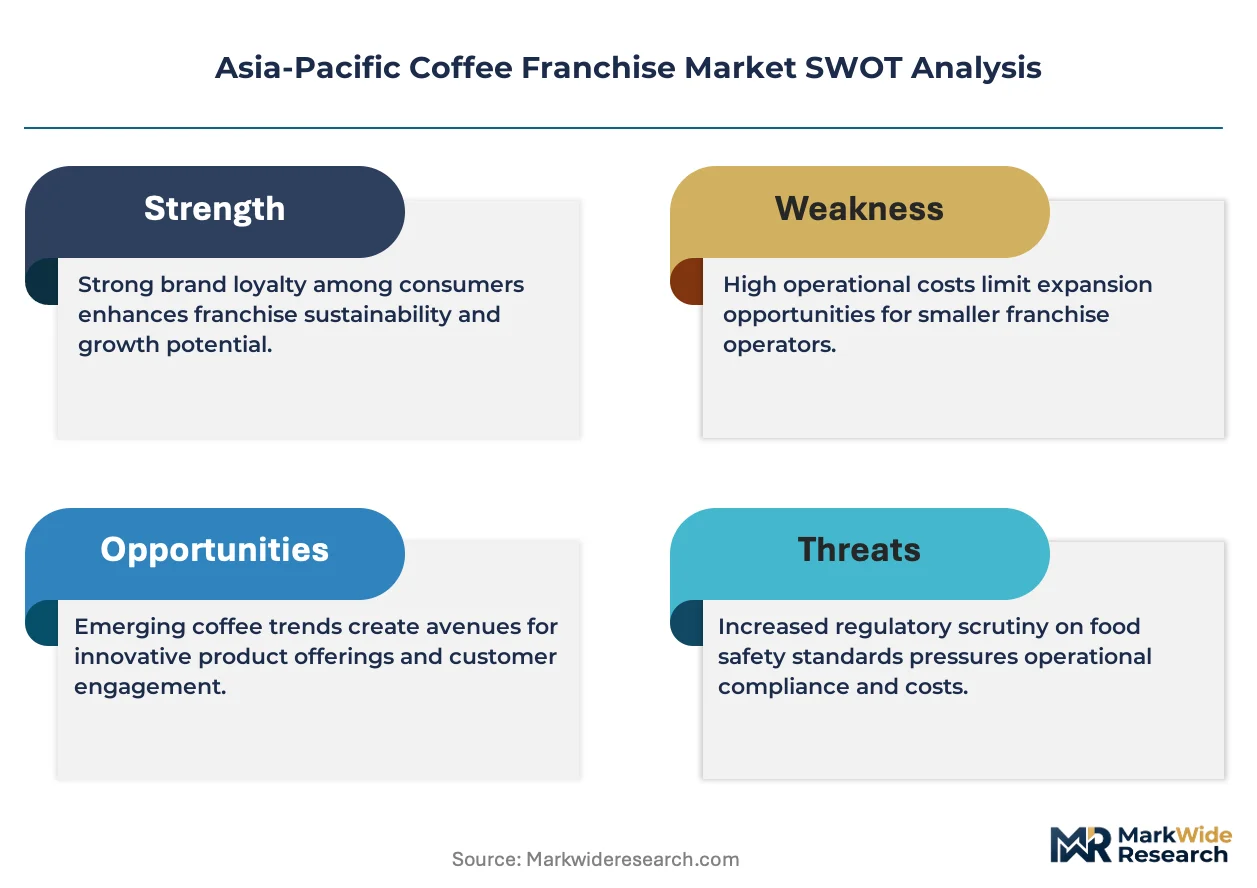
China's SAMR enforces food safety licensing for all coffee franchise outlets, while Indonesia's BPOM regulates ready-to-drink formulations under processed food standards. Japan's Food Sanitation Act shapes equipment cleaning protocols that franchisees must embed in standard operating procedures. Stakeholders should monitor how evolving digital payment compliance across ASEAN markets affects capital requirements for new store technology stacks.
Market Dynamics
Delivery-first consumption habits among urban millennials are restructuring capital allocation across Asia-Pacific coffee franchises, forcing operators to prioritize digital infrastructure over physical seating capacity.
Growth Catalysts
- China's SAMR food safety licensing:Standardized outlet certification accelerates franchise network expansion by reducing regulatory uncertainty for multi-unit developers in tier-two cities.
- Mobile payment integration:QR-code transaction ecosystems in Indonesia and Vietnam eliminate cash-handling friction, compressing checkout times below fifteen seconds during peak morning hours.
- Cold brew equipment automation:Bean-to-cup cycle times under sixty seconds enable throughput targets that justify premium real estate rents in Seoul and Tokyo commercial districts.
Market Restraints
- Arabica futures volatility:Exchange-traded coffee contracts in London and New York transmit price shocks directly to franchise margin structures, compressing gross profit on standard espresso offerings.
- Barista workforce concentration:Indonesia's hospitality training pipeline produces insufficient certified candidates relative to Jakarta and Surabaya outlet openings, inflating recruitment premiums.
- Equipment import duties:Vietnam's customs classification for commercial espresso machines triggers fifteen to twenty-five percent landed cost penalties versus domestic assembly alternatives.
Strategic Opportunities
- Philippines provincial cities:Cebu and Davao exhibit café density ratios below one per ten thousand residents, creating whitespace for area development agreements with lower rent burdens than Metro Manila.
- Japan's Food Sanitation Act equipment protocols:Mandated cleaning automation creates demand for self-sanitizing brew heads that franchisees can market as hygiene differentiators.
- GrabFood and Foodpanda integration:Third-party delivery platform APIs enable cloud-kitchen formats that eliminate front-of-house capital requirements entirely.
Industry Challenges
- Pressure calibration certification:Nine-to-fifteen-bar espresso machine maintenance requires technician credentials that training programs in Vietnam and Indonesia issue at insufficient volume.
- Multi-unit development agreement complexity:Area development rights demand upfront capital commitments that strain regional operator balance sheets during initial store ramp periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Coffee Franchise Market |
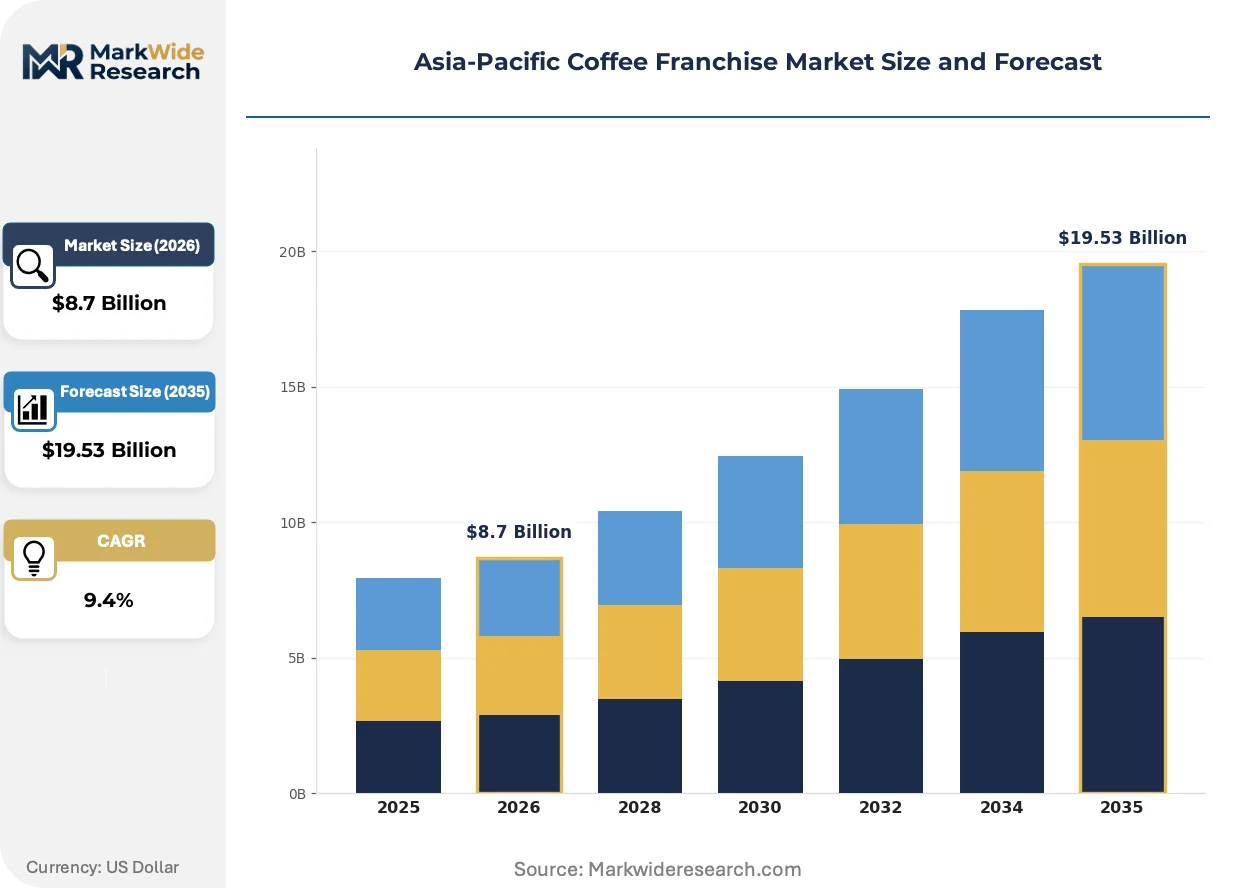
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Franchise Model: Single Unit, Multi-Unit, Area Development, Master Franchise Product Offering: Espresso, Cold Brew, Specialty Coffee, Instant Coffee Consumer Segment: Young Adults, Professionals, Students, Families Service Type: Dine-In, Takeaway, Delivery, Online Ordering |
| Companies Covered | Highlands Coffee, % Arabica, Luckin Coffee, JDE Peet's, Kopi Kenangan, Starbucks Corporation, Doutor Coffee, Cotti Coffee, Nestlé S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Coffee Franchise Market Trends and Innovations
Digital ordering infrastructure is compressing the traditional café experience into app-mediated transactions, reordering how franchises design kitchen workflows and customer touchpoints across Southeast Asian metropolitan corridors.
Automated milk steaming technology is decomposing the traditional barista skill hierarchy in South Korean and Japanese markets. Premium franchise locations in Seoul adopt robotic wands that replicate microfoam texture without human calibration. This capability compression enables shift staffing with entry-level hires rather than certified baristas, reducing labor cost per outlet by eliminating premium wage tiers.
Japan's Food Sanitation Act is mandating automated equipment cleaning cycles that franchise operators must embed in standard operating procedures. Commercial espresso manufacturers now ship machines with integrated backflush programming to satisfy METI inspection protocols. Premium locations in Tokyo and Osaka absorb higher equipment costs to preempt compliance penalties during unannounced health audits.
Urban millennials in Jakarta and Manila are substituting café visitation with subscription-based ready-to-drink delivery, fragmenting traditional foot-traffic revenue models. Cold brew concentrate shipments through refrigerated logistics now capture morning caffeine occasions that physical outlets previously monopolized. Franchise operators respond by licensing format rights to dark-kitchen facilities that produce exclusively for delivery platforms, reducing rent exposure in central business districts.
Asia-Pacific Coffee Franchise Market Segmentation
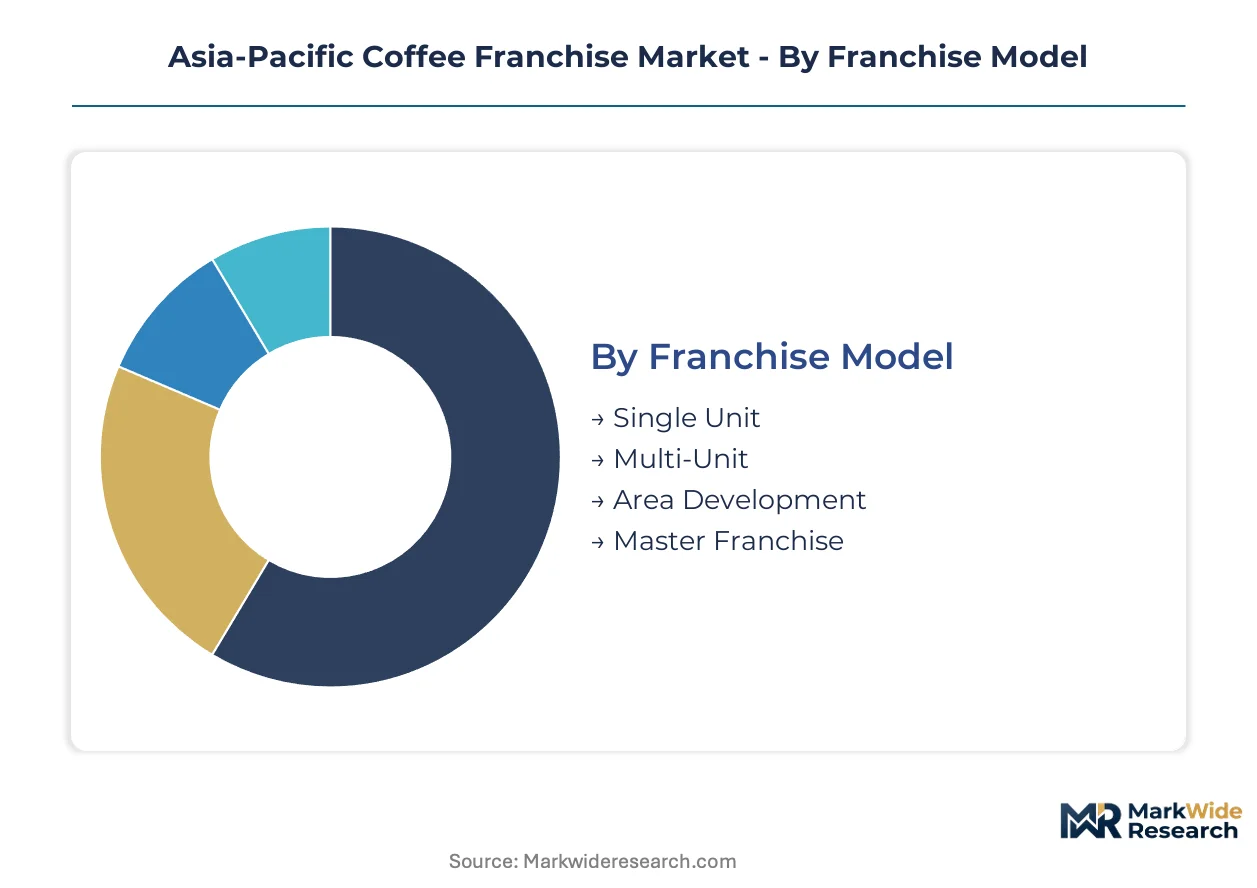
Franchise operators across Asia-Pacific calibrate capital deployment and operational workflows against distinct segment profiles. Each dimension reveals divergent margin structures, technology requirements, and geographic concentration patterns that shape expansion strategy.
Franchise Model:
Single-unit licenses concentrate in domestic Indonesian and Vietnamese markets where local entrepreneurs test café concepts. Area development rights dominate cross-border expansion into Philippine provincial cities and China's tier-two markets.
- Single Unit:Individual operators license one outlet under strict brand compliance protocols. Demand clusters in Jakarta and Surabaya where Kopi Kenangan recruits owner-operators through localized training pipelines.
- Multi-Unit:Franchisees commit to sequential store openings within defined territories. This format accelerates penetration across Seoul's commercial districts where rent premiums justify clustered outlet economics.
- Area Development:Developers secure exclusive territorial rights with aggressive build-out schedules. China's SAMR food safety licensing reduces regulatory uncertainty for multi-unit operators in Chengdu and Hangzhou.
- Master Franchise:Sub-franchising authority extends to national or regional scales. This structure enables rapid scaling across Vietnam's secondary cities where direct corporate presence remains limited.
Single-unit and multi-unit formats command the established base. The steepest expansion runs through area development agreements.
Product Offering:
Margin pools separate sharply across preparation methods, with cold extraction and specialty roasting commanding premium positioning over commodity formats.
- Espresso:Pressure-calibrated extraction at 9-15 bars defines core menu architecture. Equipment import duties in Vietnam inflate landed costs for commercial machines, compressing operator margins on standard offerings.
- Cold Brew:Extended steeping protocols produce concentrate formats with extended shelf stability. Urban millennials in Tokyo and Seoul drive subscription delivery models that fragment traditional foot-traffic revenue.
- Specialty Coffee:Single-origin sourcing and third-wave preparation techniques anchor premium positioning. Bean-to-cup cycle times under sixty seconds enable throughput targets in high-rent Tokyo districts.
- Instant Coffee:Soluble formulations serve price-sensitive segments through retail and foodservice channels. This category retains volume concentration in Philippine provincial markets where café infrastructure remains underdeveloped.
Espresso and instant coffee command the established base. The steepest expansion runs through cold brew formats.
Consumer Segment:
Demographic targeting determines location strategy, with younger cohorts driving digital-first service adoption and professional segments sustaining premium pricing.
- Young Adults:Digital-native consumers aged 18-30 prioritize mobile ordering and social media integration. This segment concentrates in Seoul and Jakarta where delivery platform penetration exceeds 70 percent.
- Professionals:White-collar workers sustain morning peak demand and meeting-oriented consumption. Tokyo's central business districts generate concentrated revenue from this cohort during weekday hours.
- Students:Price-sensitive demand centers near university clusters in Manila and Ho Chi Minh City. Extended dwell times and WiFi dependency shape outlet design requirements for this segment.
- Families:Group-oriented occasions drive weekend traffic and food-paired transactions. This segment supports suburban location economics in Australian and Japanese metropolitan peripheries.
Young adults and professionals command the established base. The steepest expansion runs through student-targeted formats.
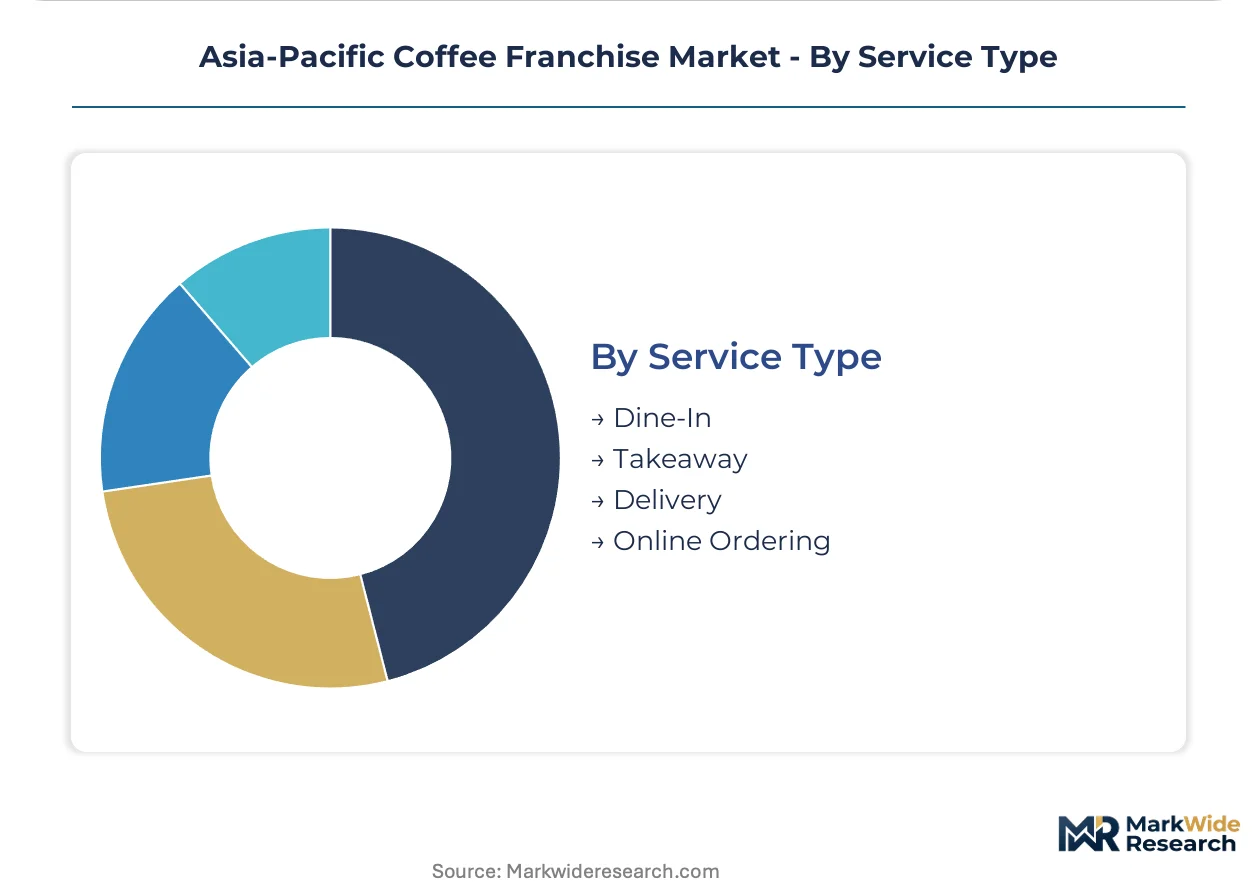
Service Type:
Capital allocation shifts dramatically as delivery infrastructure displaces traditional seating capacity across Southeast Asian markets.
- Dine-In:Full-service café experience with front-of-house seating and ambiance design. Premium locations in Tokyo and Osaka absorb higher equipment costs to satisfy Japan's Food Sanitation Act protocols.
- Takeaway:Counter-service formats optimized for speed and minimal dwell time. This structure dominates Jakarta's central business district where rent compression favors reduced footprint.
- Delivery:Third-party platform integration through GrabFood and Foodpanda APIs. Cloud-kitchen formats eliminate seating capital entirely while capturing urban millennial demand in Manila and Bangkok.
- Online Ordering:Direct-to-consumer channels bypass platform fees and capture customer data. Mobile payment integration in Indonesia and Vietnam compresses checkout friction below fifteen seconds.
Dine-in and takeaway command the established base. The steepest expansion runs through delivery-integrated formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR food safety licensing anchors regulatory frameworks across the Asia-Pacific coffee franchise sector, creating standardized pathways for multi-unit developers while tier-two cities drive continental expansion momentum.
China
Urban millennials in Chengdu and Hangzhou accelerate delivery-first adoption through mobile payment ecosystems. SAMR's standardized outlet certification reduces regulatory uncertainty for area development agreements. Luckin Coffee and Cotti Coffee compete aggressively for store density in these tier-two markets.
Indonesia
Jakarta and Surabaya concentrate franchise demand among young adults seeking digital-native café experiences. BPOM regulates ready-to-drink formulations under processed food standards, shaping product development pipelines. Kopi Kenangan anchors expansion through localized recruitment programs in these metropolitan clusters.
Japan
Tokyo and Osaka sustain professional-segment demand during concentrated weekday morning peaks. METI inspection protocols under the Food Sanitation Act mandate automated equipment cleaning cycles in standard operating procedures. Premium locations absorb higher equipment costs to preempt compliance penalties.
South Korea
Seoul's commercial districts generate clustered outlet economics justified by rent premiums and throughput targets. Automated milk steaming technology decomposes traditional barista skill hierarchies, enabling shift staffing with entry-level hires. Robotic wands replicate microfoam texture without human calibration.
Philippines
Cebu and Davao exhibit café density ratios below one per ten thousand residents, creating whitespace for area development agreements. Students near university clusters in Manila drive price-sensitive demand with extended dwell times. GrabFood and Foodpanda integration enables cloud-kitchen formats that eliminate front-of-house capital requirements.
Asia-Pacific Coffee Franchise Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with global beverage conglomerates and regional digital-native chains occupying distinct competitive strata. The market structure fragments across single-unit domestic operators and multi-unit development specialists, each deploying divergent capital allocation strategies. Three archetypes dominate: delivery-optimized digital platforms, premium experiential formats, and automated throughput specialists. Competitive moves concentrate on geographic licensing expansion and technology stack integration rather than direct price confrontation.
Within the integrated leader tier, Starbucks Corporation and Nestlé S.A. exemplify divergent strategic positions—one emphasizing physical experiential density, the other anchoring retail packaged presence. Among Asia-Pacific digital-native specialists, Luckin Coffee and Kopi Kenangan occupy positions defined by mobile-first infrastructure and localized market penetration. Cotti Coffee represents the speed-to-hire automation archetype competing aggressively on operational velocity.
| Leading Market Players |
|---|
| Highlands Coffee |
| % Arabica |
| Luckin Coffee |
| JDE Peet's |
| Kopi Kenangan |
| Starbucks Corporation |
| Doutor Coffee |
| Cotti Coffee |
| Nestlé S.A. |
| Others |
Pricing and Supply Chain Analysis
Sixty-day green coffee inventory cycles in Vietnamese port warehouses tether franchise margin stability to arabica futures volatility on London and New York exchanges. This lead-time exposure concentrates pricing power with commodity traders while forcing operators to absorb or pass through cost spikes across tiered menu architectures.
Pricing Analysis
Jakarta-to-Tokyo price spreads of thirty to fifty percent separate premium single-origin positioning from mass-market espresso formats. Pricing stratifies across premium, standard, and economy tiers with differentiation anchored in bean provenance certification and equipment automation levels. Cost compression in the standard tier intensifies because Luckin Coffee and Cotti Coffee deploy subsidized customer acquisition in Chinese tier-two cities. Students in Manila and Ho Chi Minh City exhibit highest price sensitivity, while professionals in Tokyo's central business districts sustain premium tolerance.
Supply Chain Analysis
Forty-five-day ocean freight cycles from Brazilian and Colombian origin ports to regional roasting hubs in Vietnam and Indonesia shape working capital requirements for franchise operators. Green coffee sourcing concentrates in Brazil, Colombia, and Vietnam with roasting and distribution anchored in regional processing facilities. Equipment import dependencies rest on Italian and German espresso machine manufacturers with Vietnam's fifteen-to-twenty-five percent landed cost penalties creating tariff exposure. Distribution runs through centralized commissary kitchens supplying multiple outlets with prepared cold brew concentrate and baked goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Franchise network economics increasingly hinge on recurring-revenue layers including subscription delivery programs and equipment maintenance contracts expanding faster than per-unit beverage sales. Service-attach revenue streams now determine capital efficiency in high-rent metropolitan corridors.
For Market Incumbents: Consolidate area development rights in Philippine provincial cities before digital-native competitors establish density. Lock in multi-year green coffee forward contracts to neutralize arabica futures volatility. Deepen backward integration into regional roasting capacity to preempt supply disruption from single-source Brazilian dependency.
For New Entrants and Emerging Players: SAMR food safety certification fast-tracks enable rapid outlet deployment in Chengdu and Hangzhou without incumbent regulatory overhead. White-space concentrates in Cebu and Davao where café density ratios sit below one per ten thousand residents. Cloud-kitchen formats eliminating front-of-house capital requirements offer the most penetrable go-to-market angle for delivery-first urban millennials.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-owned domestic coffee chains seeking to monetize non-core foodservice assets. Long-term viability favors operators with integrated digital payment infrastructure and proprietary delivery platform relationships rather than pure physical footprint plays. Monitor barista certification program graduation rates across Indonesia and Vietnam as inflection indicators for labor-constrained expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Equipment Deployment | Robotic milk steaming and self-sanitizing brew heads reduce METI compliance costs in Tokyo premium locations. |
| Delivery Platform Integration | GrabFood and Foodpanda API connectivity enables cloud-kitchen formats with zero seating capital in Manila. |
| Green Coffee Forward Contracting | Long-term offtake agreements with Brazilian and Colombian exporters neutralize exchange-traded price volatility exposure. |
| Localized Recruitment Pipeline | Kopi Kenangan's Jakarta training programs demonstrate scalable approaches to Indonesia's barista shortage constraints. |
| Tier-Two City Area Development | SAMR standardized licensing reduces regulatory uncertainty for multi-unit developers in Chengdu and Hangzhou markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of franchise disclosure documents, customs trade records, and food safety regulatory filings. Interviews with franchise operations directors, equipment procurement managers, and BPOM compliance officers combined with bottom-up outlet counting and top-down market sizing triangulation. Secondary sources include SAMR licensing databases, Indonesian BPOM processed food standards, and Japan's Food Sanitation Act implementation guidelines.
Segmentation dimensions modeled span franchise model type, product offering category, consumer demographic segment, and service delivery format across the analysis window. CAGRs derived from outlet expansion trajectories, same-store sales velocity, and average transaction value progression. Forecast inputs incorporate mobile payment penetration rates, delivery platform market share shifts, and arabica futures curve structures.
Decision-makers should treat outputs as directional under assumptions of continued urban millennial adoption and stable ASEAN digital payment infrastructure; material deviation in commodity price volatility or regulatory licensing timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Mushroom Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Global Professional Coffee Machine Market
Coffee
Coffee Roaster Market
Coffee
Global Coffee Shop Market
Coffee
Single Origin Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Green Coffee Bean Extract Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Coffee Bottle Market
Coffee
Portable Espresso Machines Market
Coffee
Butter Coffee Market
Coffee
Caffeine Market
Coffee
Global Coffee Market
Coffee
Global Nespresso Capsules Market