
 South Korea Coffee and Tea Capsules Market | 2026-2036
South Korea Coffee and Tea Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Coffee and Tea Capsules Market Intelligence
Buyer concentration among South Korean office coffee service providers is shifting toward smaller independent workplaces and remote-work households. Nespresso Korea Co., Ltd. anchors the premium segment through boutique retail presence in Seoul's Gangnam and Jongno districts. KFCC Co., Ltd. leverages its domestic manufacturing base to compete on freshness and localized flavor profiles. Keurig Korea Ltd. sustains volume leadership through partnerships with major electronics retailers.
Coffee and tea capsules are sealed, pre-portioned containers—typically aluminum, plastic, or plant-based biopolymer—designed for pressure-brewing systems at bars per square inch exceeding nine, delivering standardized extraction for commercial and home use. Coffee Capsules dominate current revenue, while Eco-friendly Packs represent the fastest-growing Packaging Type as MFDS biopolymer certification becomes a purchasing gate. Specialty Blends command margin premiums, though Arabica-based formulations remain the largest Ingredient Type by volume.
MFDS sets food-contact safety thresholds for capsule materials, while Korea's Ministry of Environment enforces extended producer responsibility rules that reshape packaging R&D budgets. The Korea Consumer Agency monitors labeling accuracy for origin and caffeine content claims. Stakeholders must track how Seoul Metropolitan Government's zero-waste district pilots affect single-serve format acceptance before committing to capacity expansion.
Market Dynamics
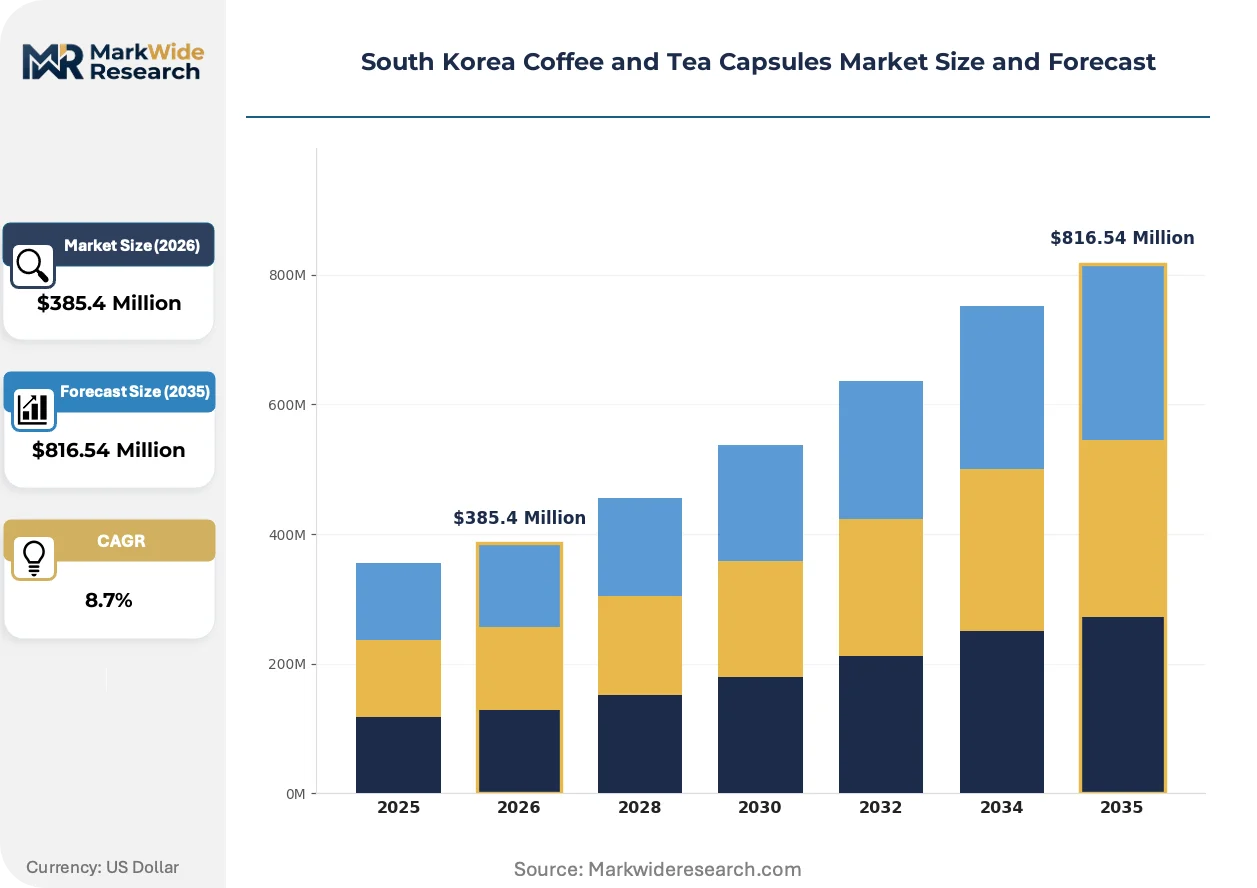
MFDS biopolymer certification requirements and Seoul Metropolitan Government's zero-waste district pilots are forcing manufacturers to reallocate R&D budgets toward compliant packaging formats before capacity expansion decisions.
Growth Catalysts
- Urban office-worker adoption:Single-serve brewing systems penetrate smaller independent workplaces and remote-work households throughout Seoul and Gyeonggi Province.
- MFDS food-contact standards:Tightened safety thresholds for aluminum and plant-based materials accelerate certified supplier qualification timelines.
- Specialty blend premiums:Arabica-forward formulations command margin expansion in Gangnam and Jongno retail corridors.
Market Restraints
- Aluminum input volatility:Capsule shell material costs fluctuate with global metal commodity indexes, compressing gross margins for non-integrated producers.
- Domestic supply concentration:Gyeonggi Province hosts the majority of domestic manufacturing, creating regional disruption risk from localized logistics constraints.
- Plastic reduction roadmap friction:Korea's Ministry of Environment extended producer responsibility rules impose compliance cost burdens ahead of biopolymer scale economies.
Strategic Opportunities
- Busan-Ulsan corridor penetration:Premium capsule consumption remains underdeveloped in Korea's southeastern manufacturing belt relative to Seoul saturation.
- Electronics retailer partnerships:Bundled system-plus-capsule distribution through major appliance chains opens household acquisition channels.
- Zero-waste district alignment:Seoul Metropolitan Government pilot programs create early-mover advantage for compostable-format suppliers.
Industry Challenges
- Biopolymer certification timelines:MFDS food-contact approval cycles extend product launch schedules by quarters.
- Legacy system integration:Pressure-brewing equipment incompatibility across proprietary capsule geometries fragments consumer lock-in.
- Flavor R&D specialization:Localized palate adaptation requires dedicated sensory science capabilities scarce in domestic talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Coffee and Tea Capsules Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee Capsules, Tea Capsules, Herbal Capsules, Specialty Blends Ingredient Type: Arabica, Robusta, Green Tea, Infusions Packaging Type: Single Serve, Multi-pack, Eco-friendly Packs, Bulk Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Coffee Shops |
| Companies Covered | KFCC Co., Ltd., Keurig Korea Ltd., Nespresso Korea Co., Ltd., K-Konic Co. Ltd., JARO Co. Ltd., Lavazza Korea Co., Ltd., Coffee Bay Co., Ltd., KAFFA INT Co., Ltd., Dongsuh Companies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Coffee and Tea Capsules Market Strategic Shifts & Innovations
Packaging material science and brewing system architecture are converging to reshape competitive positioning across South Korea's premium and mass-market tiers.
Plant-based biopolymer capsules are modularizing the supply chain by enabling regional compounding and localized thermoforming. Domestic manufacturers adopt these materials to bypass aluminum import dependency. The structural consequence is compressing lead times from formulation to retail shelf.
MFDS food-contact material standards are tightening extractable limits for both aluminum and novel biopolymers. Manufacturers must submit migration testing documentation before market authorization. Specialty blend producers face the steepest compliance burden due to oil-based flavor carrier interactions.
Remote-work households are fragmenting traditional office coffee service procurement. Individual subscribers replace centralized workplace contracts through direct-to-door replenishment apps. This pattern concentrates in Seoul's apartment-dense districts where single-serve convenience outweighs bulk brewing economics.
South Korea Coffee and Tea Capsules Market Segmentation
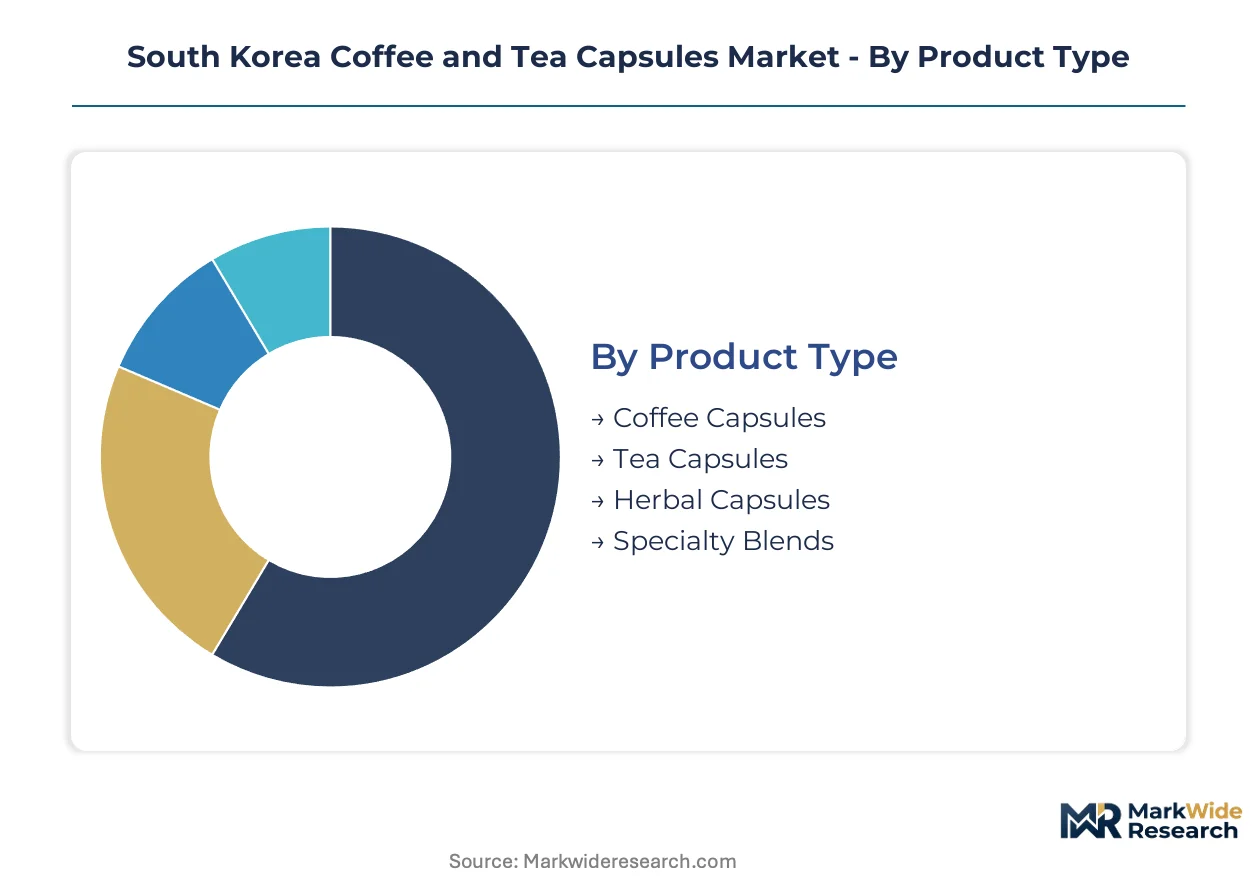
Segmentation in South Korea's coffee and tea capsules market reveals how brewing system compatibility, MFDS packaging compliance, and Seoul-centric consumption patterns fragment procurement decisions across commercial and household buyers.
Product Type:
Purchase decisions hinge on extraction pressure compatibility and workplace versus home brewing frequency.
- Coffee Capsules:Aluminum and biopolymer shells engineered for nine-plus bar pressure extraction dominate commercial installations. Seoul office towers and Gangnam district cafes drive replacement volume through centralized procurement contracts.
- Specialty Blends:Arabica-forward formulations with origin-specific roasting profiles command premium positioning in Jongno and Gangnam retail corridors. MFDS labeling requirements for caffeine content and origin claims shape formulation transparency.
- Tea Capsules:Lower-pressure compatible formats targeting green tea and oolong extraction sequences. Gyeonggi Province households favor these for morning consumption rituals.
- Herbal Capsules:Caffeine-free infusions packaged for evening consumption segments. Limited brewing system compatibility constrains addressable base.
Volume sits with Coffee Capsules; growth tilts toward Specialty Blends.
Ingredient Type:
Raw material sourcing geography and flavor oil stability determine supplier qualification timelines under MFDS food-contact standards.
- Arabica:High-altitude sourced beans with lower caffeine density and complex acid profiles. Roasters in Seoul prioritize Ethiopian and Colombian origins for premium capsule lines.
- Green Tea:Jeju Island and Boseong-region leaf sources supply domestic tea capsule production. Seasonal harvest compression affects year-round formulation consistency.
- Robusta:Higher caffeine content and crema-stabilizing lipids support espresso-style extraction. Blended into mass-market formulations for cost management.
- Infusions:Non-camellia botanicals including chrysanthemum and barley. Niche positioning limits scale economies for dedicated production lines.
Arabica commands the largest procurement volumes; Green Tea claims the steepest expansion trajectory as domestic origin marketing intensifies.
Packaging Type:
Extended producer responsibility rules and Seoul zero-waste district pilots are reallocating R&D budgets toward compliant formats.
- Eco-friendly Packs:Plant-based biopolymer capsules with MFDS food-contact certification enable compostable disposal pathways. Domestic manufacturers adopt regional compounding to bypass aluminum import dependency.
- Single Serve:Individual aluminum or plastic shells optimized for freshness preservation in humid climates. Electronics retailer bundled distribution drives household penetration.
- Multi-pack:Ten-to-twenty unit configurations targeting remote-work household replenishment cycles. Direct-to-door apps concentrate in Seoul's apartment-dense districts.
- Bulk:Fifty-plus unit formats for office coffee service providers. Procurement consolidation among smaller independent workplaces is fragmenting traditional contract structures.
Single Serve maintains installed base dominance; Eco-friendly Packs are gaining share fastest as biopolymer scale economies emerge.
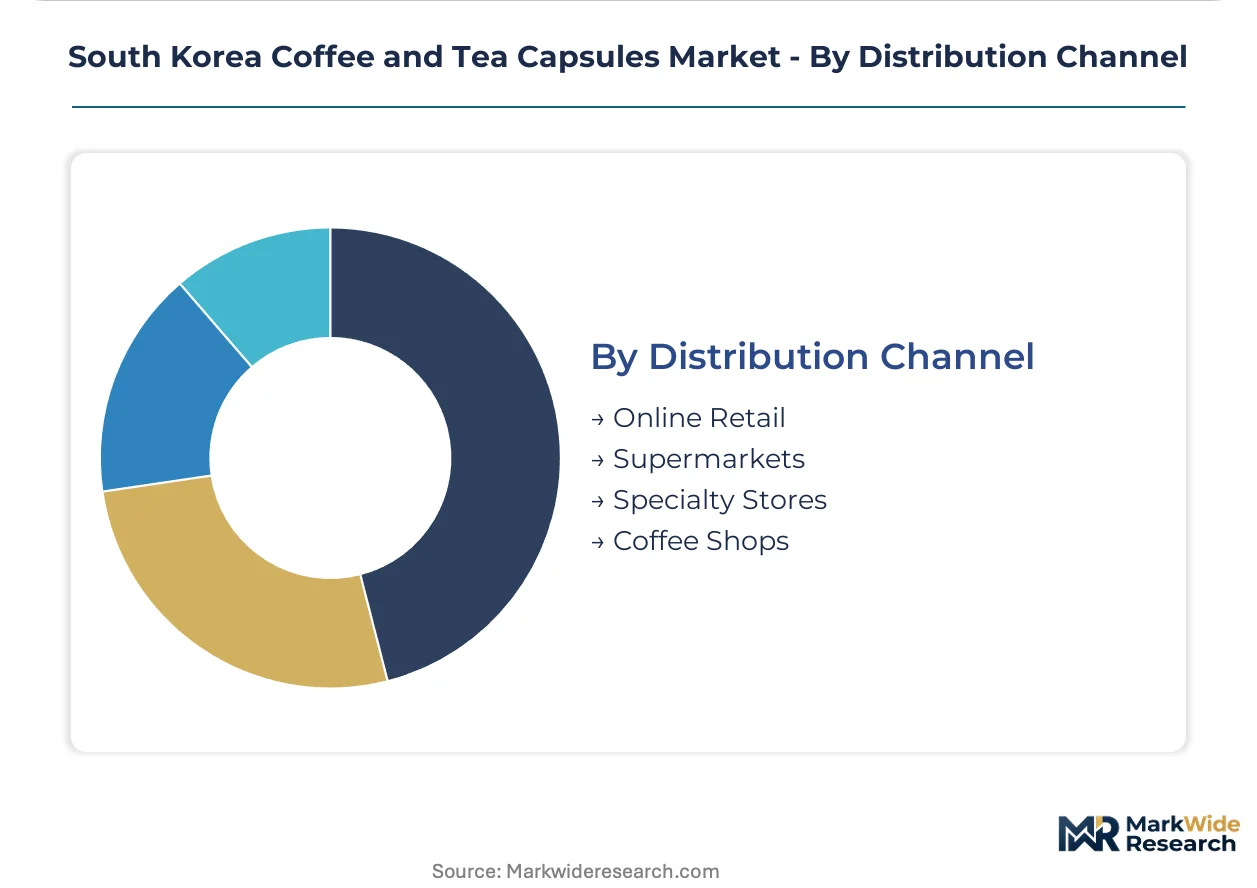
Distribution Channel:
System-plus-capsule bundling and replenishment app interfaces are restructuring how brewing equipment and consumables reach end users.
- Online Retail:Direct-to-door subscription apps with algorithmic replenishment timing. Remote-work households in Seoul's dense apartment corridors favor convenience over bulk brewing economics.
- Specialty Stores:Boutique retail presence in Gangnam and Jongno districts with sensory tasting infrastructure. Nespresso Korea anchors this channel through experiential flagship locations.
- Supermarkets:Mass-market shelf placement for multi-pack and bulk configurations. Price transparency compresses margins for non-differentiated formulations.
- Coffee Shops:On-premise brewing system trials with attached capsule retail. Limited penetration outside Seoul metropolitan core.
Online Retail captures the fastest volume growth; Specialty Stores defend the highest margin positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates the bulk of premium capsule demand, with urban office workers and remote-work households driving single-serve adoption. MFDS food-contact standards and the national plastic reduction roadmap are reshaping packaging compliance requirements across all sub-regions.
Seoul Capital Area
Gangnam and Jongno district boutiques anchor premium capsule retail, with Nespresso Korea flagship locations driving experiential purchasing. Seoul Metropolitan Government's zero-waste district pilots impose compostable-format mandates on suppliers. Gyeonggi Province manufacturing clusters supply freshness-competitive domestic production to this demand core.
Busan-Ulsan Corridor
Southeastern manufacturing belt workers show underdeveloped premium capsule penetration relative to Seoul saturation. Korea's Ministry of Environment extended producer responsibility rules apply uniform compliance costs across this logistics-constrained region. Ulsan industrial zones host limited specialty coffee service infrastructure compared to the capital.
Daegu-Gyeongbuk
Textile and machinery industry concentrations generate mid-tier office coffee service demand. MFDS biopolymer certification requirements extend product launch timelines for regional distributors. Daegu metropolitan area electronics retailers bundle system-plus-capsule offerings to household purchasers.
Daejeon-Sejong
Government complex and research institute concentrations create institutional procurement opportunities. National plastic reduction roadmap compliance pressures reshape public sector tender specifications. Sejong administrative city development attracts direct-to-door replenishment app logistics investment.
Gwangju-Honam
Agricultural economy and smaller urban scale limit premium capsule infrastructure density. Domestic tea capsule demand concentrates in traditional morning consumption rituals. Honam region logistics constraints elevate landed costs for aluminum-dependent imported formats.
South Korea Coffee and Tea Capsules Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biopolymer certification and zero-waste district alignment. The vendor base clusters around three archetypes: multinational premium specialists, domestic freshness-focused manufacturers, and electronics retailer-integrated volume players. Competitive dynamics center on MFDS food-contact material approval speed and Seoul Metropolitan Government pilot program positioning.
Within the premium specialist tier, Nespresso Korea Co., Ltd. and Lavazza Korea Co., Ltd. exemplify experiential retail anchoring through Gangnam and Jongno boutique presence. KFCC Co., Ltd. represents the domestic manufacturing archetype, leveraging Gyeonggi Province production proximity to compete on freshness and localized flavor adaptation. Keurig Korea Ltd. occupies the electronics retailer-integrated position, sustaining volume leadership through major appliance chain partnerships.
| Leading Market Players |
|---|
| KFCC Co., Ltd. |
| Keurig Korea Ltd. |
| Nespresso Korea Co., Ltd. |
| K-Konic Co. Ltd. |
| JARO Co. Ltd. |
| Lavazza Korea Co., Ltd. |
| Coffee Bay Co., Ltd. |
| KAFFA INT Co., Ltd. |
| Dongsuh Companies, Inc. |
| Others |
Cost & Logistics Intelligence
Captive aluminum sourcing from Gyeonggi Province manufacturers anchors supply positioning while insulating domestic producers from LME volatility, yet this same concentration compresses margin flexibility when biopolymer R&D compliance costs surge under MFDS timelines.
Pricing Analysis
Volume leadership sits with mass-market single-serve configurations through electronics retailer bundles, while margin expansion concentrates in Gangnam and Jongno specialty retail corridors where origin-transparent Arabica formulations command premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and freshness proximity, with biopolymer MFDS approval status now functioning as a price floor gate. Pricing pressure stems from aluminum commodity index swings and extended producer responsibility compliance burdens, with remote-work households in Seoul's apartment corridors exhibiting highest price sensitivity and boutique experiential purchasers showing lowest.
Supply Chain Analysis
Freight cost differentials between Gyeonggi Province manufacturing clusters and Busan-Ulsan corridor distribution points elevate landed costs for aluminum-dependent imported formats in southeastern Korea. Domestic production draws from Jeju Island green tea leaf, Ethiopian and Colombian Arabica bean imports, and regional petrochemical feedstocks for biopolymer compounding. Single-source vulnerability concentrates in aluminum shell supply from China and specialty flavor oil carriers from European suppliers. Distribution runs through electronics retailer system-plus-capsule bundling, direct-to-door replenishment apps, and boutique flagship experiential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
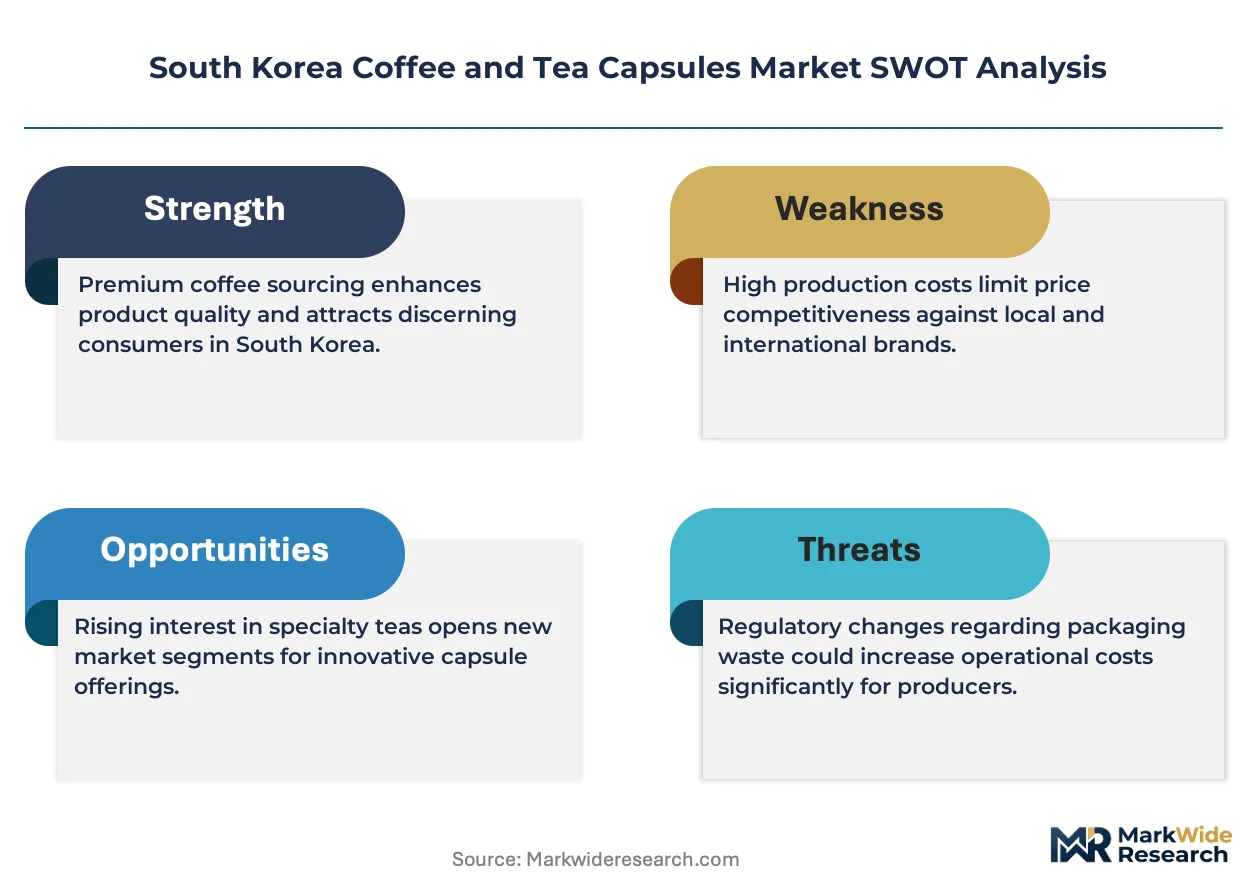
This market functions as a cost-of-compliance story where MFDS biopolymer certification timelines extend product launch schedules by quarters, erecting barrier-to-entry moats for capitalized incumbents who have already secured approval pathways.
For Market Incumbents: To counter biopolymer certification bottlenecks, accelerate backward integration into regional compounding capabilities in Gyeonggi Province to compress lead times from formulation to retail shelf. Secure zero-waste district pilot program alignment with Seoul Metropolitan Government to lock in early-mover compostable-format positioning before capacity expansion decisions.
For New Entrants and Emerging Players: Enter via Busan-Ulsan corridor penetration where premium capsule consumption remains underdeveloped relative to Seoul saturation, targeting electronics retailer bundled distribution partnerships to bypass boutique retail infrastructure gaps. Pursue localized flavor R&D specialization for domestic palate adaptation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational premium specialists seeking Gyeonggi Province manufacturing footprint and MFDS-approved biopolymer capabilities. Long-term viability favors vertically integrated domestic manufacturers with captive regional compounding over pure-brand marketing plays. Watch Seoul Metropolitan Government zero-waste district pilot expansion velocity as the signal for compostable-format inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Certification Investment | MFDS food-contact approval accelerates market authorization timelines against aluminum-dependent competitors. |
| Zero-Waste District Alignment | Seoul Metropolitan Government pilot programs create preferential procurement pathways for compostable-format suppliers. |
| Electronics Retailer Partnership | System-plus-capsule bundling through major appliance chains opens household acquisition channels beyond boutique retail. |
| Regional Compounding Capacity | Gyeonggi Province thermoforming proximity compresses lead times from formulation to retail shelf. |
| Specialty Blend Localization | Domestic sensory science capabilities enable palate-specific formulations for Seoul and Gyeonggi Province demand clusters. |
Research Approach
Document review covered MFDS food-contact material standards documentation, Korea Ministry of Environment extended producer responsibility rule filings, and Seoul Metropolitan Government zero-waste pilot program specifications, complemented by interviews with capsule manufacturing plant managers, specialty coffee roaster R&D directors, electronics retailer category buyers, and office coffee service procurement leads. Secondary validation drew from Korea Consumer Agency labeling guidance, customs import records for aluminum and green tea leaf, and appliance chain sales disclosures. Bottom-up demand modeling across brewing system installed base and replacement rates triangulated against top-down market value reconstructions.
Cross-referencing historical volume trajectories against expert panel input on biopolymer adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, ingredient sourcing geography, packaging compliance tier, and distribution channel structure. CAGRs derived from pressure-brewing system penetration rates in Seoul office towers and remote-work household fragmentation patterns, with aluminum commodity index volatility and MFDS approval cycle duration as key forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated zero-waste district mandate rollout or sustained aluminum price spikes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
India Coffee Roaster Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Specialty Coffee Market
Coffee
Butter Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Smart Coffee Maker Market
Coffee
Coffee Roaster Market
Coffee
Mushroom Coffee Market
Coffee
Latin America Coffee Market
Coffee
Organic Coffee Market
Coffee
Coffee Brewers Market
Coffee
China Coffee Market
Coffee
United States Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
North America Specialty Coffee Market
Coffee
Global Automatic Coffee Machines Market