
 Global Cafe Market | 2026-2036
Global Cafe Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cafe Market Analysis
Brazilian arabica harvest volatility is shifting sourcing strategies across the roasted coffee supply chain. Starbucks Corporation leverages its vertically integrated coffee purchasing to stabilize bean costs across volatile growing seasons. JDE Peet's sustains a dominant position in European retail coffee through its multi-brand portfolio spanning instant to premium roast. Luckin Coffee anchors its competitive stance through technology-driven store formats that minimize labor and real estate overhead.
A cafe constitutes a foodservice establishment primarily preparing and serving brewed coffee, espresso-based beverages, and light food items, typically operating equipment maintaining 9-bar extraction pressure and 90-96°C brewing temperatures for optimal flavor compound dissolution. The commercial purpose centers on delivering prepared beverages and accompaniments for immediate consumption within branded environments designed for social interaction, work, or transit. Coffee within product type segments captures the largest revenue pool, while delivery within service type segments represents the fastest structural expansion as digital ordering platforms reconfigure last-mile economics. Premium price tiers concentrate margin pools in urban core locations, whereas budget tiers compete on throughput velocity in transport hubs and secondary markets.
The FDA enforces food safety standards under the Food Safety Modernization Act, directly shaping ingredient traceability requirements and supplier verification protocols for cafe operators sourcing across multiple jurisdictions. The EU Green Deal and REACH regulations mandate progressive reductions in single-use packaging, compelling chains to redesign cup formats and invest in reusable container infrastructure. Stakeholders must monitor how divergent national sustainability timelines fragment compliance costs and determine whether to standardize operations globally or localize supply chain and packaging strategies by market.
Market Dynamics
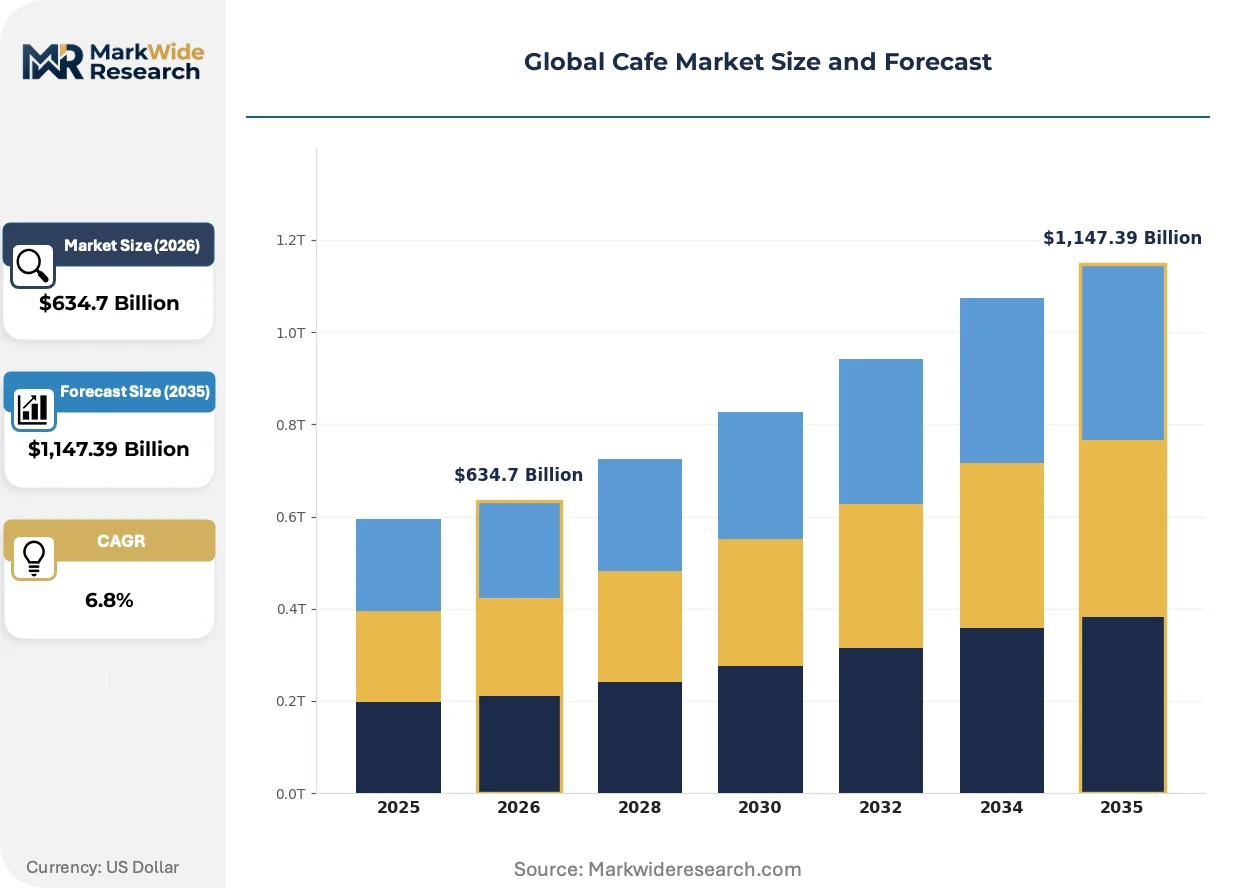
Digital ordering infrastructure is compressing the traditional cafe operating model, forcing operators to reconfigure labor deployment and real estate footprints around fulfillment velocity rather than in-seat experience.
Growth Catalysts
- Remote work normalization:Knowledge workers now populate cafes during traditional off-peak hours, flattening demand curves and improving asset utilization rates for operators with WiFi-optimized layouts.
- EU Green Deal packaging mandates:Regulatory pressure to eliminate single-use cups is accelerating investment in reusable container ecosystems and deposit-return infrastructure across member states.
- Cellular agriculture proteins:Precision fermentation-derived dairy alternatives are reducing ingredient cost volatility and enabling consistent foam stability for plant-based milk beverages.
Market Restraints
- Arabica price volatility:Brazilian harvest fluctuations driven by frost and drought cycles are destabilizing green coffee procurement budgets for non-integrated operators.
- Barista wage compression:Labor shortages in urban core markets are inflating personnel costs faster than menu price elasticity permits absorption.
- Commercial real estate repricing:Post-pandemic rent resets in prime foot-traffic corridors are eroding unit economics for street-level formats.
Strategic Opportunities
- Lower-tier China expansion:Tier-3 and Tier-4 cities remain underpenetrated by organized cafe chains, offering first-mover positioning ahead of domestic competitor saturation.
- Dark kitchen formats:Delivery-only production nodes without customer-facing space unlock real estate cost structures incompatible with traditional dine-in economics.
- US Inflation Reduction Act energy credits:Electrification incentives for commercial kitchen equipment reduce capex burdens for roasting and espresso infrastructure upgrades.
Industry Challenges
- Equipment technician scarcity:Specialized repair capacity for 9-bar espresso systems and precision grinders lags fleet expansion, extending downtime intervals.
- Multi-jurisdiction allergen compliance:Divergent labeling mandates between FDA, EFSA, and China's SAMR create formulation complexity for chains operating across borders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cafe Market |
| Market Size in 2026 | $634.7 Billion |
| Market Size in 2035 | $1,147.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee, Tea, Pastries, Snacks Service Type: Dine-in, Takeaway, Drive-thru, Delivery Customer Type: Students, Professionals, Families, Tourists Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | Starbucks Corporation, Dunkin', Costa Coffee, McDonald's Corporation, Tim Hortons, Luckin Coffee, JDE Peet's, The Coffee Bean & Tea Leaf, Peet's Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cafe Market Emerging Trajectories
Automation and sustainability imperatives are converging to redefine capital deployment priorities, with operators reallocating spending from aesthetic differentiation toward backend efficiency and compliance infrastructure.
Automated espresso systems with integrated grind-by-weight dosing and self-calibrating tamping are overtaking traditional semi-automatic machines in high-throughput urban locations. Chains operating 50-plus units are adopting these systems to reduce training dependency and shot-to-shot variance. Labor substitution is overtaking craft positioning as the primary equipment selection criterion for new store builds.
REACH regulations governing chemical safety in food contact materials are compelling cup and lid manufacturers to reformulate polymer compositions and accelerate migration testing protocols. Suppliers serving EU markets must now maintain dual material streams—compliant formulations for Europe and legacy specifications for less regulated jurisdictions. Single-use paperboard suppliers are absorbing the bulk of compliance costs and extending lead times for certified stock.
Subscription-based beverage programs with fixed monthly fees for unlimited drip coffee are displacing per-transaction purchasing among commuters in dense metropolitan corridors. Corporate accounts and transport-hub locations are piloting these models to lock in baseline revenue and reduce peak-hour queuing friction. Seoul and Tokyo represent the most advanced testing grounds for this consumption-pattern shift.
Global Cafe Market Segmentation
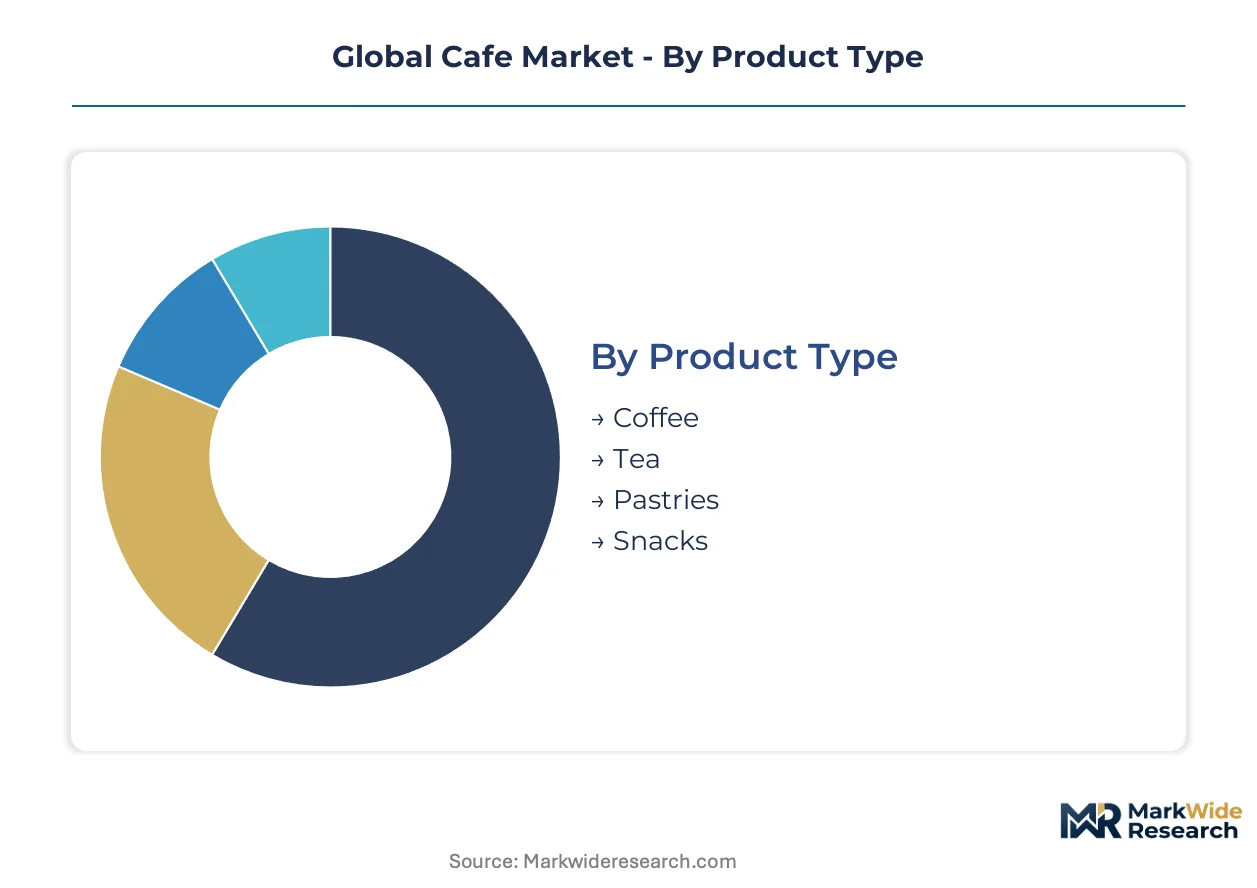
Cafe operators configure product portfolios and service formats around distinct consumption occasions and spending thresholds. Segmentation discipline determines real estate selection, labor deployment, and equipment specification across diverse customer microclimates.
Product Type:
Supply concentration in arabica sourcing shapes margin architecture across beverage categories, with roast profiles and brewing methods defining equipment investment and staff training intensity.
- Coffee:Espresso-based preparations requiring 9-bar extraction systems and precise grind calibration dominate equipment footprints. Demand concentrates in urban professional corridors where Luckin Coffee and Starbucks compete on throughput velocity during morning peaks.
- Tea:Specialty loose-leaf and bubble tea formats demand controlled-temperature brewing infrastructure distinct from coffee systems. Growth clusters in East Asian markets where Gongfu brewing rituals support premium pricing in dedicated tea houses.
- Pastries:Baked goods sourced through central commissary models or local bakery partnerships extend dwell time and average transaction value.
- Snacks:Pre-packaged and prepared savory items fill incremental dayparts with minimal kitchen labor overhead.
Coffee absorbs the bulk of installed capacity; tea is expanding most quickly in specialized formats.
Service Type:
Customer type dictates format selection, with remote workers and commuters driving divergent real estate and technology configurations.
- Dine-in:Seated consumption with WiFi-optimized layouts targets remote workers flattening demand curves across traditional off-peak hours. Operators in Seoul and Tokyo pilot subscription models to lock in baseline revenue from this segment.
- Takeaway:Counter-service formats with minimal seating maximize throughput in transport hubs and dense commercial districts where rent per square meter compresses dwell time economics.
- Drive-thru:Vehicle-based ordering and pickup infrastructure dominates suburban and highway-adjacent locations across the United States and Australia.
- Delivery:Digital ordering platforms reconfigure last-mile economics through dark kitchen production nodes without customer-facing space.
Delivery is climbing the fastest as platform infrastructure matures; dine-in retains the largest revenue pool in premium urban locations.
Customer Type:
Volume concentration varies sharply by time-of-day and location type, requiring dynamic pricing and promotional scheduling.
- Students:Price-sensitive demand clusters near university campuses with extended operating hours and study-conducive seating configurations.
- Professionals:Morning peak concentration and loyalty program participation drive subscription pilot programs in metropolitan corridors.
- Families:Weekend and holiday occasion-based visits favor locations with play areas and menu variety spanning generational preferences.
- Tourists:Transient demand in destination cities supports premium pricing for signature beverages and localized merchandise.
Professionals generate the highest frequency of visits; tourists produce the largest per-transaction values.
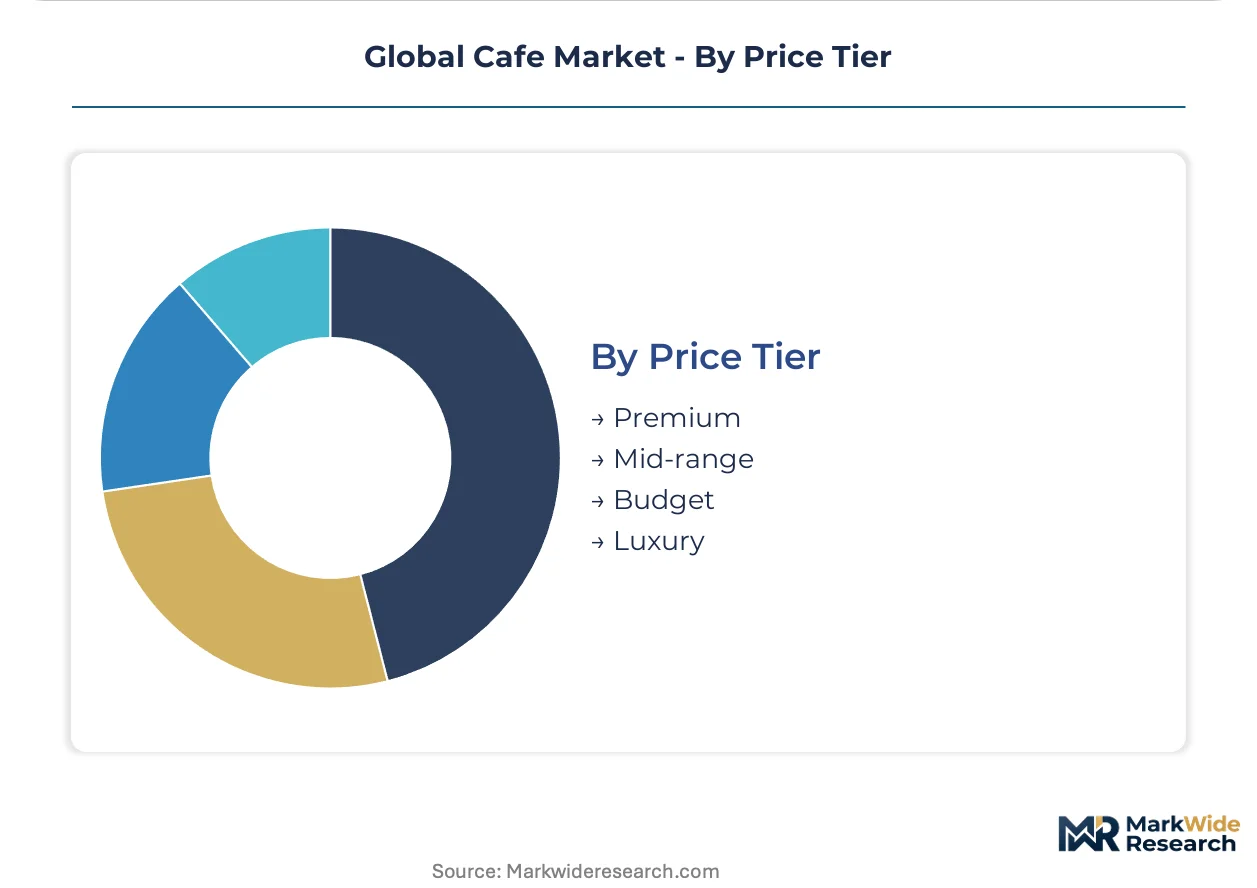
Price Tier:
Margin structure stratifies across equipment specification, ingredient sourcing, and real estate positioning.
- Premium:Single-origin sourcing and manual brewing methods justify elevated price points in urban core locations with high foot traffic and competitive differentiation requirements.
- Mid-range:Blended offerings and automated systems balance quality perception with operational efficiency in secondary commercial districts.
- Budget:High-velocity formats with standardized recipes and minimal customization compete on convenience and accessibility in transport hubs and lower-tier cities.
- Luxury:Rare varietals and ceremonial service rituals target experiential consumption in flagship locations and hospitality partnerships.
Budget tiers dominate unit count expansion; premium tiers capture disproportionate margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian arabica harvests anchor supply-side volatility, forcing procurement diversification across Southeast Asian and East African origins. Demand concentration now tilts toward Chinese lower-tier cities and US suburban drive-thru corridors.
United States
Remote workers populate suburban cafes during traditional off-peak hours, flattening demand curves for operators with WiFi-optimized layouts. FDA food safety modernization mandates shape supplier verification protocols across multi-state chains. Drive-thru formats dominate Texas and Florida corridors where vehicle-based ordering maximizes throughput velocity.
China
Knowledge workers in Tier-3 and Tier-4 cities drive first-mover expansion opportunities ahead of domestic competitor saturation. SAMR allergen labeling requirements create formulation complexity for chains operating across provincial jurisdictions. Luckin Coffee anchors technology-driven store deployment in Chengdu and Wuhan with minimized labor overhead.
Germany
EU Green Deal packaging mandates accelerate reusable container infrastructure investment across Berlin and Hamburg metropolitan networks. REACH regulations governing food contact materials compel cup manufacturers to reformulate polymer compositions. JDE Peet's sustains retail dominance through multi-brand portfolio spanning instant to premium roast segments.
Japan
Subscription-based beverage programs with fixed monthly fees displace per-transaction purchasing among Tokyo and Osaka commuters. METI energy efficiency standards shape commercial equipment specification for roasting and espresso infrastructure. Precision fermentation-derived dairy alternatives reduce ingredient cost volatility for plant-based milk formulations.
Brazil
Frost and drought cycles in Minas Gerais and São Paulo growing regions destabilize green coffee procurement budgets for non-integrated operators. The country's national agricultural regulator enforces phytosanitary export certification protocols. Roasting clusters in Campinas and Ribeirão Preto concentrate value-add processing capacity for international distribution.
Global Cafe Market Vendor Landscape
Global majors compete with regional champions across format specialization and technology integration. The vendor base stratifies into three tiers: vertically integrated coffee purchasers stabilizing bean costs, technology-driven operators minimizing real estate overhead, and multi-brand portfolio owners spanning instant to premium roast segments. Dominant competitive moves include geographic expansion into underpenetrated lower-tier cities and backend automation investments reducing training dependency.
Within the technology-driven tier, Luckin Coffee exemplifies labor-minimizing store formats, while Starbucks Corporation anchors vertically integrated sourcing strategies. JDE Peet's occupies a position representing multi-brand retail dominance across European markets. These three entities collectively illustrate the strategic archetypes reshaping capital deployment priorities from aesthetic differentiation toward backend efficiency and compliance infrastructure.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Dunkin' |
| Costa Coffee |
| McDonald's Corporation |
| Tim Hortons |
| Luckin Coffee |
| JDE Peet's |
| The Coffee Bean & Tea Leaf |
| Peet's Coffee |
| Others |
Supply Flow & Price Mechanics
Automated espresso systems with integrated grind-by-weight dosing are compressing labor costs and flattening price differentiation between mid-range and budget tiers, while simultaneously concentrating equipment procurement power among Italian and Swiss manufacturers. This technology shift tightens margins for operators locked into legacy semi-automatic fleets while rewarding early adopters with throughput velocity advantages during morning peak compression.
Pricing Analysis
Equipment leasing bundled with preventive maintenance contracts dominates capital deployment, separating total cost of ownership from upfront capex decisions. Three-tier pricing structure across premium, standard, and economy levels tracks arabica grade certification and real estate positioning, with urban core locations commanding rent premiums that absorb into beverage pricing. Cost compression in budget tiers is intensifying because Luckin Coffee's technology-driven formats reset labor efficiency benchmarks. Students and remote workers in university-adjacent markets exhibit highest price sensitivity, while tourists in destination corridors show least elasticity.
Supply Chain Analysis
Green coffee supply rests on Brazilian arabica harvests, Vietnamese robusta volume, and Colombian specialty-grade production, creating geographic diversification imperatives for risk management. Roasted coffee draws from centralized production hubs in Brazil, Vietnam, and Indonesia, with logistics networks feeding into regional distribution centers. Single-source vulnerability concentrates in Brazilian frost-exposed growing regions, where climate volatility disrupts procurement budgets for non-integrated operators. Distribution runs through multi-temperature controlled networks serving both retail chains and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
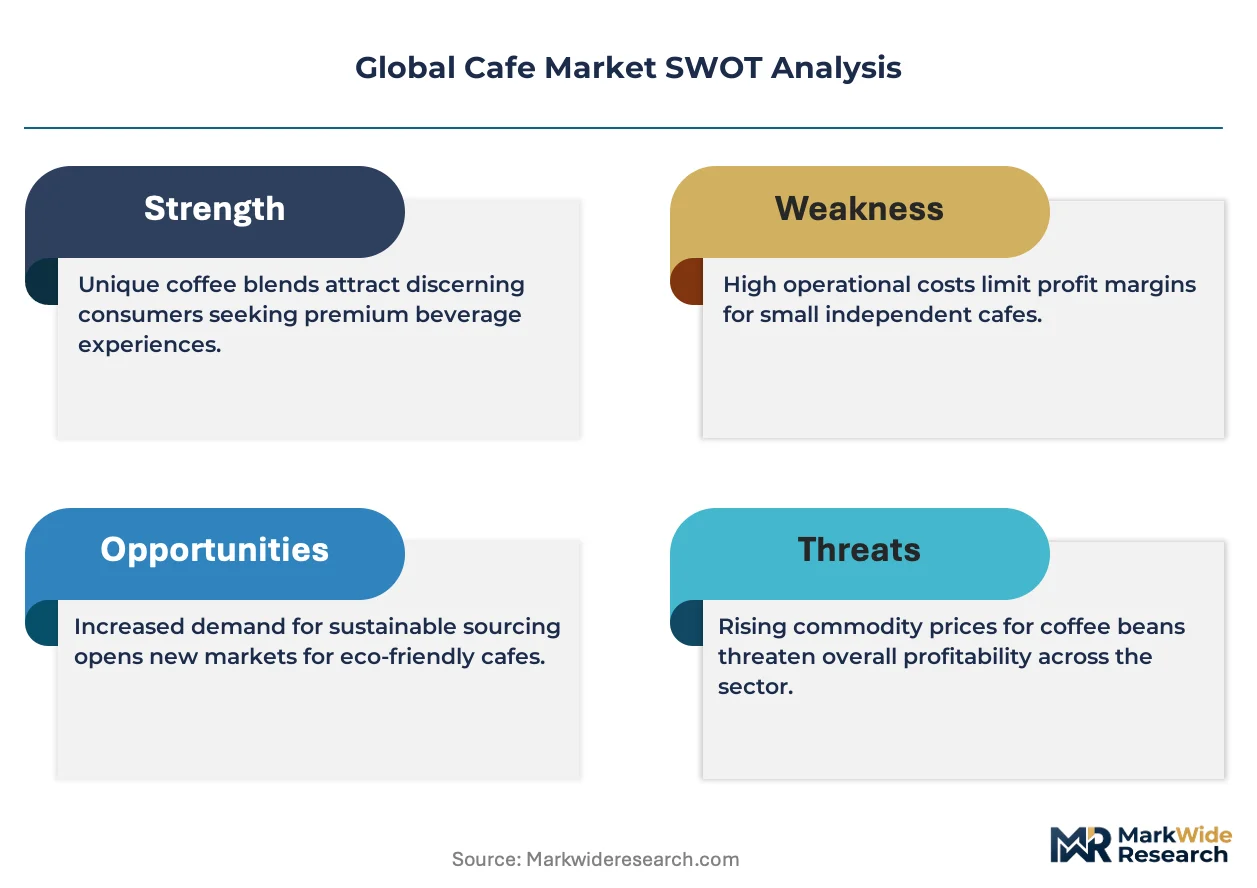
The Global Cafe Market operates as a cost-of-compliance story where EU Green Deal packaging mandates and FDA Food Safety Modernization Act traceability requirements erect regulatory moats favoring operators with capital reserves for infrastructure retrofitting.
For Market Incumbents: Deepen backward integration into roasting capacity across Southeast Asian origins to insulate procurement budgets from Brazilian climate volatility. Consolidate supplier verification protocols ahead of FDA enforcement waves targeting multi-jurisdiction sourcing networks. Lock in reusable container infrastructure partnerships across EU metropolitan networks before deposit-return mandates harden. For New Entrants and Emerging Players: Begin with dark kitchen formats in Tier-3 and Tier-4 Chinese cities where domestic competitor saturation remains incomplete and real estate costs permit viable unit economics. Target remote worker segments with subscription-based unlimited beverage programs piloted in Seoul and Tokyo corridors. Deploy technology-driven ordering platforms as primary go-to-market infrastructure rather than retrofitting legacy dine-in formats. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-driven operators with demonstrated labor efficiency metrics and scalable digital infrastructure. Long-term viability favors vertically integrated coffee purchasers with captive supply chains spanning volatile growing regions. Watch arabica price volatility spikes as inflection indicators for distressed acquisition opportunities among non-integrated regional chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backend Automation Investment | Reduces training dependency and shot-to-shot variance across high-throughput urban locations. |
| Reusable Container Infrastructure | Positions operators ahead of EU Green Deal deposit-return mandates across member states. |
| Dark Kitchen Format Expansion | Unlocks real estate cost structures incompatible with traditional dine-in economics in lower-tier cities. |
| Precision Fermentation Sourcing | Stabilizes plant-based milk ingredient costs and ensures consistent foam stability for barista beverages. |
| Multi-Origin Procurement Diversification | Insulates green coffee budgets from Brazilian frost and drought cycle volatility. |
Methodological Framework
Multi-period observation of store format evolution, equipment deployment cycles, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with cafe chain operations directors, espresso equipment procurement managers, foodservice distribution channel heads, and sustainability compliance officers at multi-jurisdiction operators. Secondary validation drew from FDA enforcement documentation, EU Green Deal implementation progress reports, SEC 10-K filings by publicly traded chains, and customs records tracking green coffee import volumes. Bottom-up unit economics modeling triangulated against top-down market sizing across geographic clusters.
Segment-weighting approaches distributed value estimates across product type, service format, customer archetype, and price tier dimensions, with additional stratification by urban density classification and regulatory jurisdiction cluster. CAGRs were derived from fitted growth curves applied to historical trajectory data across the projection horizon. Forecast inputs incorporated arabica futures price volatility indices, commercial real estate repricing patterns in prime foot-traffic corridors, and platform-mediated delivery volume growth rates.
Underlying measurement precision varies by segment; delivery and dark kitchen formats carry tighter precision than luxury experiential locations due to digital transaction traceability. Forecasts reflect documented assumptions regarding remote work normalization persistence, regulatory implementation timelines, and equipment technology adoption curves. Arabica harvest disruption, barista wage inflation spikes, and reusable container infrastructure cost overruns represent specific risk factors that could revise projections. A small set of named triggers—SAMR enforcement intensity in China, METI equipment efficiency standard updates in Japan, and US Inflation Reduction Act credit allocation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
United States Coffee Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Global Nespresso Capsules Market
Coffee
Mushroom Coffee Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Ethiopia Coffee Market
Coffee
Oceania Coffee Market
Coffee
Take Out Coffee Market
Coffee
Specialty Coffee Market
Coffee
China Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
Vietnam Coffee Market
Coffee
Coffee Beans Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market