
 Dairy-Free RTD Coffee Products Market | 2026-2036
Dairy-Free RTD Coffee Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy-Free RTD Coffee Products Market Outlook
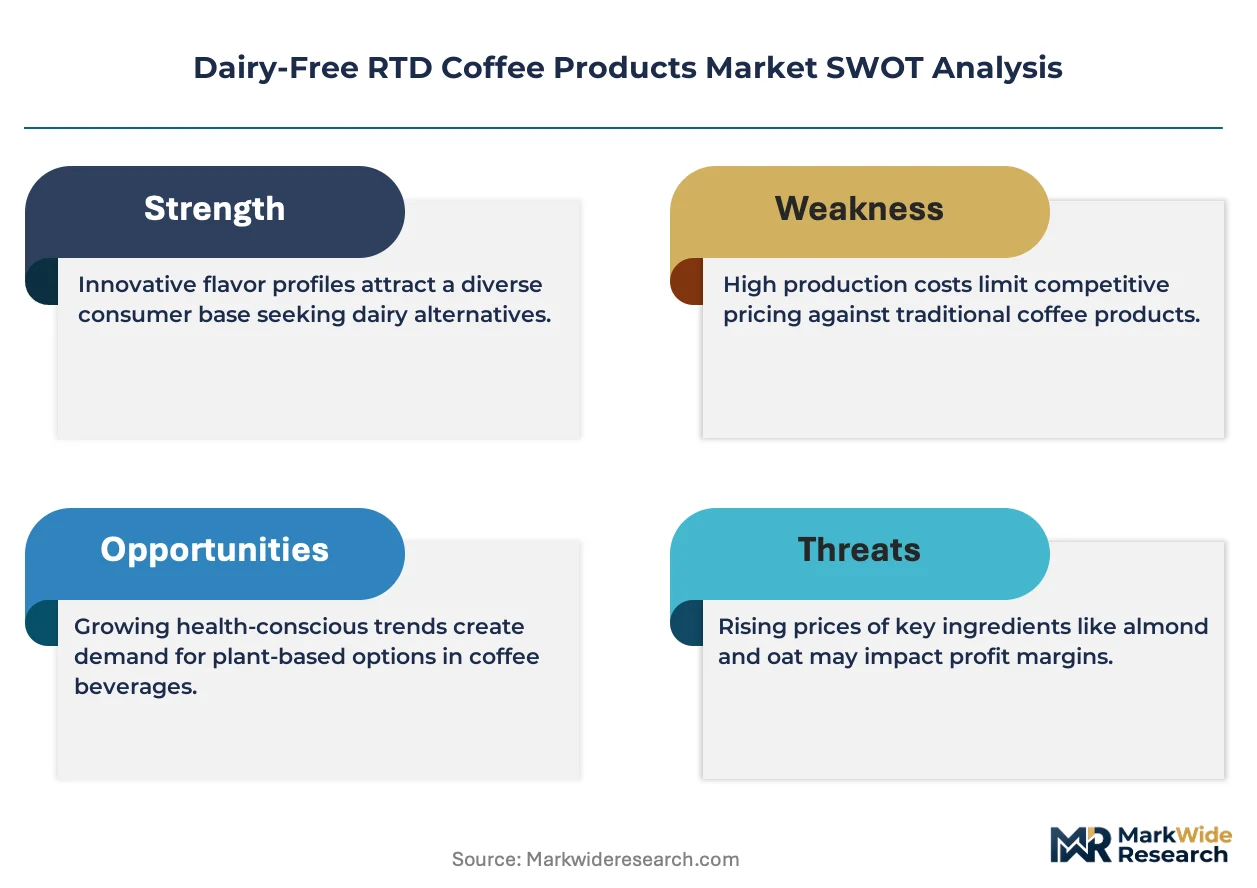
Oat milk is decoupling from almond as the default dairy alternative in RTD coffee, reducing input cost volatility for manufacturers while improving foam stability in cold brew applications. Califia Farms leverages its vertically integrated almond and oat supply chains to sustain margin control across West Coast distribution networks. Oatly Group AB anchors European retail penetration through branded refrigerated sets, while Danone competes in multi-source plant-based portfolios spanning coconut and soy bases.
Dairy-free RTD coffee denotes pre-packaged, shelf-stable or refrigerated coffee beverages formulated with plant-based emulsions rather than lacteal derivatives, typically containing 1-3% plant protein, adjusted pH between 4.5-6.5, and high-pressure processing or hot-fill sterilization for ambient distribution. Cold brew and nitro coffee segments lead volume as lower-acidity extraction methods accommodate oat and almond protein stability without astringency defects. Oat-based ingredient sources capture the fastest expansion as enzymatic hydrolysis improves mouthfeel parity with dairy, while carton packaging dominates retail economics through aseptic filling lines and lightweight logistics.
USDA organic certification, FDA nutrition labeling rules, and EU EFSA health claim frameworks shape formulation transparency and cross-border market access for dairy-free RTD coffee brands. The FDA's updated guidance on plant-based milk labeling creates compliance thresholds for protein and micronutrient fortification claims that directly influence R&D allocation. Stakeholders must monitor evolving EU packaging waste directives and state-level extended producer responsibility laws that will determine material choices for multi-serve cartons and single-serve cans.
Market Dynamics
Enzymatic hydrolysis of oat proteins is compressing formulation cycles while EU clean-label mandates force ingredient disclosure granularity that favors single-source plant bases over blended emulsions.
Growth Catalysts
- USDA Organic Certification:Premium shelf positioning in United States grocery channels accelerates as certification thresholds align with consumer willingness-to-pay for verified sourcing claims.
- High-pressure processing:Ambient-stable cold brew formats achieve 90-day shelf life without thermal degradation, unlocking convenience store distribution previously blocked by refrigeration requirements.
- Foodservice channel expansion:Specialty coffee chains in California and New York are dedicating permanent refrigerated sets to branded dairy-free RTD lines, creating pull-through for retail velocity.
Market Restraints
- Oat protein concentrate supply:Scandinavian milling capacity constraints create input cost volatility for manufacturers dependent on enzymatically treated oat bases.
- EU Packaging Waste Directive:Extended producer responsibility frameworks impose material recovery obligations that increase per-unit cost for multi-serve carton formats.
- Almond pollination dependency:California apiary availability fluctuations introduce crop yield risk that propagates through nut milk supply chains.
Strategic Opportunities
- Nitro coffee formats:Widget-can technology from craft beer packaging is crossing over into dairy-free cold brew, creating texture differentiation in United States convenience retail.
- FDA plant-based milk labeling guidance:Fortification thresholds for protein and calcium create compliance-based segmentation that rewards R&D investment in micronutrient parity formulations.
- South Korean café culture:RTD penetration in Seoul's convenience store network remains underdeveloped relative to Japan, presenting first-mover shelf space for oat-based entrants.
Industry Challenges
- Clean-label formulation expertise:Food science talent capable of stabilizing oat emulsions without synthetic hydrocolloids commands premium compensation in tight labor markets.
- Aseptic line certification:FDA process authority approvals for high-acid coffee beverages require 18-24 month validation timelines that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy-Free RTD Coffee Products Market |
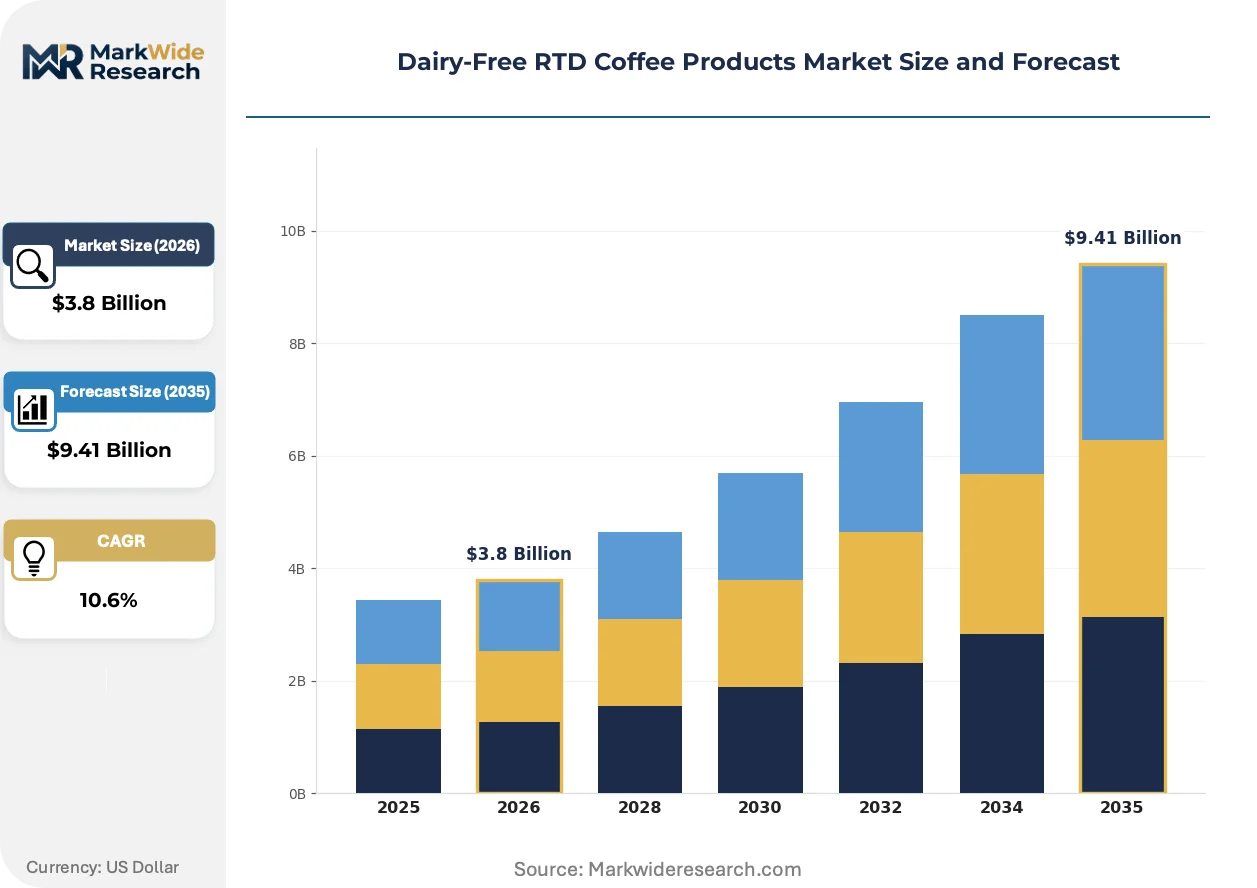
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.41 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Brew, Iced Coffee, Espresso Drink, Nitro Coffee Ingredient Source: Almond, Oat, Coconut, Soy Flavor Profile: Vanilla, Mocha, Hazelnut, Caramel Packaging Type: Carton, Bottle, Can, Tetra Pack |
| Companies Covered | Starbucks Corporation, Califia Farms, Oatly Group AB, Danone, Nestlé, Minor Figures, Blue Bottle Coffee, La Colombe Coffee Roasters, RISE Brewing Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy-Free RTD Coffee Products Market Strategic Shifts
Formulation science and packaging engineering are converging to collapse the quality gap between refrigerated and ambient dairy-free coffee, while regulatory transparency mandates reshape competitive moats around ingredient provenance.
Enzymatic hydrolysis of oat starches is electrifying texture engineering in plant-based emulsions. Barista-style RTD brands in the United States are adopting this technology at accelerating pace to achieve foam stability parity with dairy. The structural consequence is compression of R&D differentiation cycles as mouthfeel patents expire and become table stakes.
EU EFSA health claim frameworks are tightening substantiation requirements for protein and micronutrient fortification claims in plant-based beverages. This regulatory friction is forcing reformulation of legacy soy and almond portfolios to meet disclosure thresholds. Cold brew segments in Germany and Netherlands are responding fastest, with clean-label oat bases capturing refrigerated set resets.
Direct-to-subscription models are fragmenting traditional grocery velocity patterns. United States millennials are displacing weekly supermarket trips with curated delivery boxes featuring rotating single-origin cold brew SKUs. This channel shift is most visible in coastal metropolitan markets where convenience premiumization justifies subscription economics.
Dairy-Free RTD Coffee Products Market Segmentation
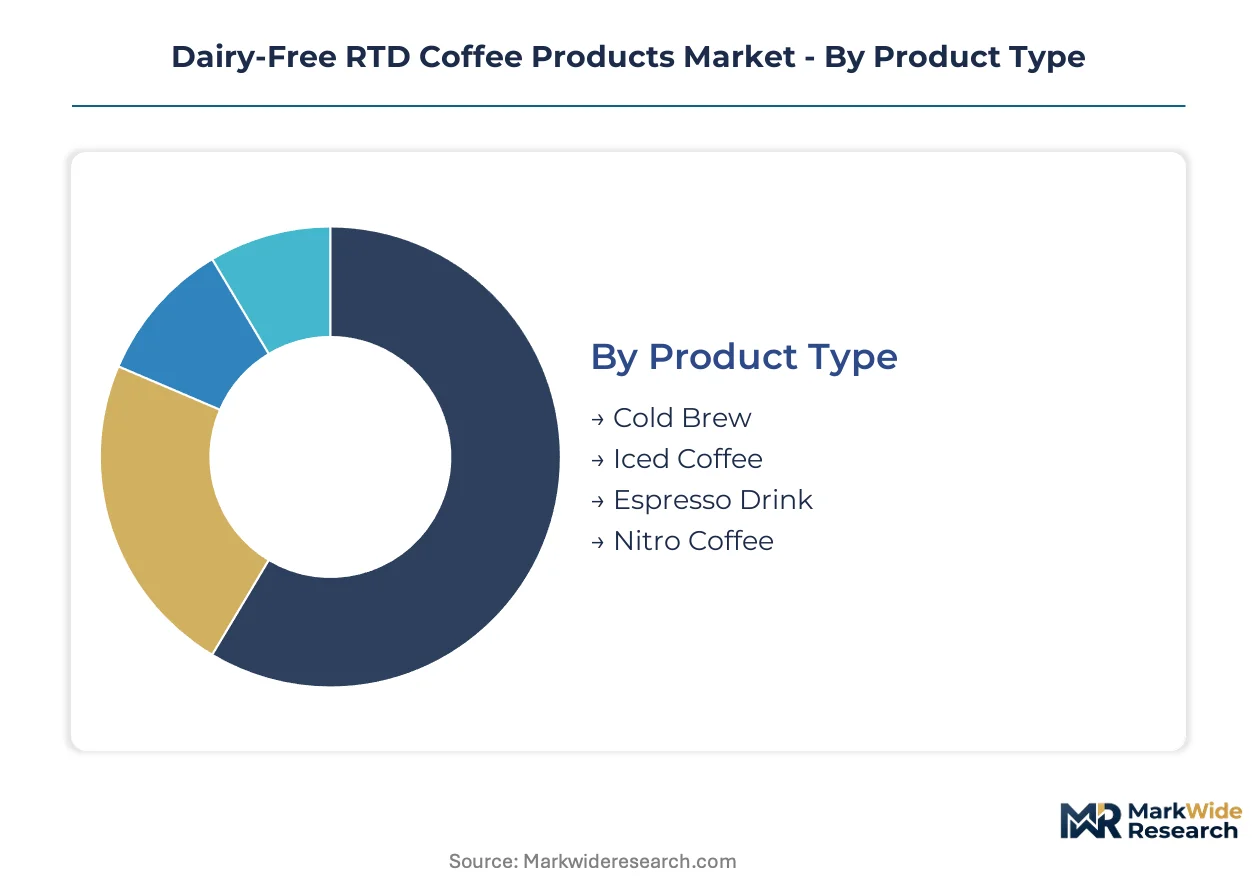
Segmentation in dairy-free RTD coffee determines which formulation and packaging combinations unlock specific retail channels and price tiers. Certification requirements vary sharply across segments, with ambient-stable formats demanding FDA process authority validation while refrigerated sets compete on USDA organic positioning.
Product Type:
Cold brew and nitro formats carry heavier regulatory burdens than thermal-processed alternatives, requiring high-pressure processing validation or nitrogen dosing equipment certification depending on shelf-life claims.
- Cold Brew:Lower-acidity extraction preserves oat protein stability without astringency defects. Demand clusters in United States convenience retail where 90-day ambient shelf life unlocks distribution previously blocked by refrigeration requirements.
- Nitro Coffee:Widget-can technology from craft beer packaging crosses over to create texture differentiation. California and New York specialty chains dedicate permanent refrigerated sets to these formats, pulling through retail velocity.
- Iced Coffee:Thermal-processed base with higher acidity tolerance enables simpler hot-fill sterilization and faster FDA approval timelines.
- Espresso Drink:Concentrated formulations face stricter caffeine disclosure thresholds under FDA nutrition labeling rules.
Cold Brew sits at the top of the volume ranking, with Nitro Coffee climbing the fastest.
Ingredient Source:
Input cost structures diverge dramatically based on agricultural geography and processing intensity, with enzymatic hydrolysis adding capital intensity to oat while almond faces pollination risk.
- Oat:Enzymatic hydrolysis of starches and proteins achieves mouthfeel parity with dairy. Scandinavian milling capacity constraints create supply volatility for manufacturers dependent on treated bases.
- Almond:California apiary availability fluctuations introduce crop yield risk that propagates through supply chains. Vertically integrated processors maintain margin control through captive orchards.
- Coconut:Southeast Asian sourcing requires EFSA contaminant screening for aflatoxin compliance in EU distribution.
- Soy:Legacy portfolios face reformulation pressure as EFSA health claim frameworks tighten protein substantiation requirements.
Oat commands the volume lead, with Coconut expanding most quickly in European clean-label resets.
Flavor Profile:
Flavor selection drives formulation complexity and clean-label compliance costs, with natural extract sourcing subject to EU EFSA additive scrutiny.
- Vanilla:Madagascar and Tahitian extract sourcing faces supply concentration risk and price volatility.
- Mocha:Cocoa powder integration requires pH balancing with coffee acidity for protein stability in oat bases.
- Hazelnut:Turkish and Italian nut paste suppliers dominate premium positioning in German refrigerated sets.
- Caramel:Clean-label caramelization without synthetic colorants demands longer processing cycles and tighter process control.
Vanilla maintains volume leadership, with Hazelnut gaining share fastest in European barista-format launches.
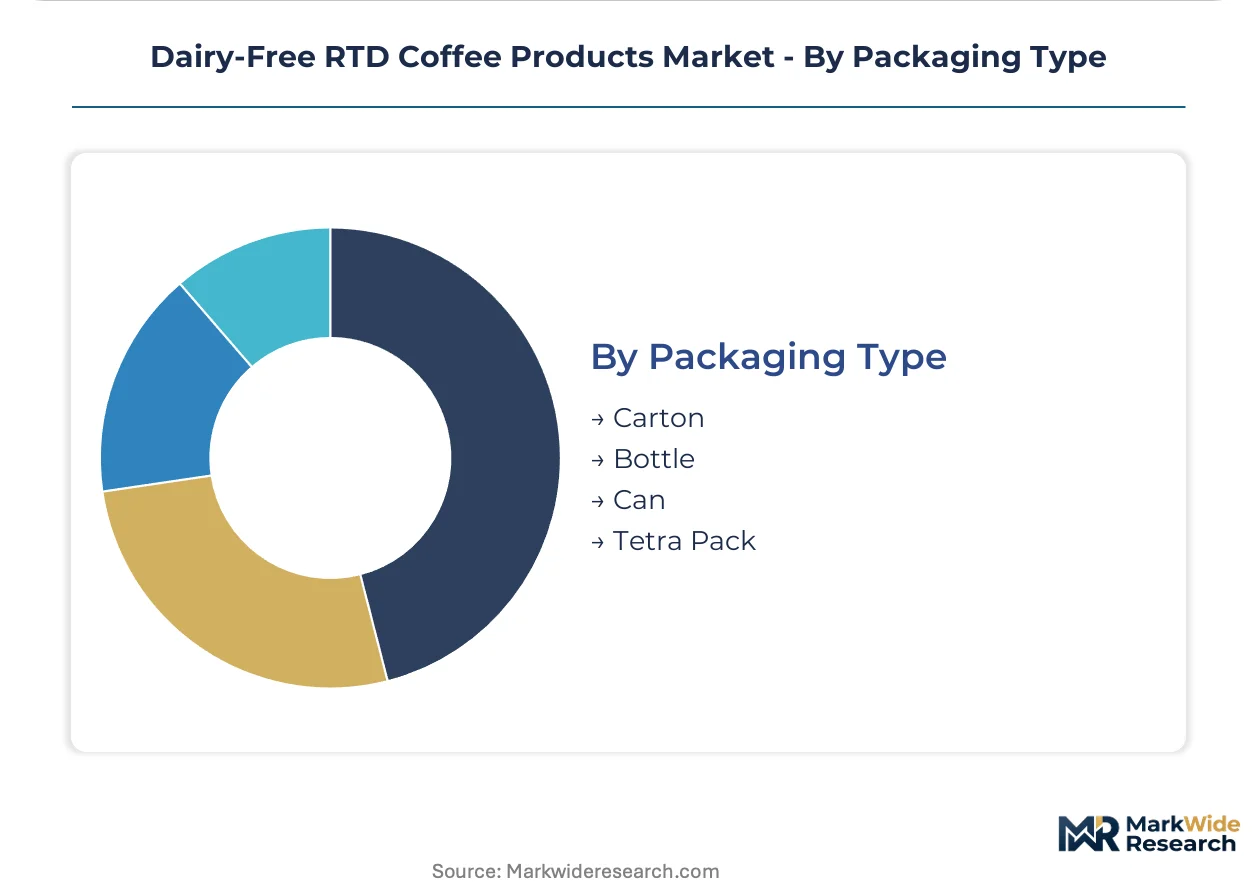
Packaging Type:
Material selection determines extended producer responsibility obligations under EU Packaging Waste Directive and state-level EPR laws in the United States.
- Carton:Aseptic filling lines and lightweight logistics dominate retail economics. Multi-serve formats face material recovery cost increases under EU extended producer responsibility frameworks.
- Can:Aluminum recycling infrastructure supports circular economy claims, though nitro widget technology adds manufacturing complexity.
- Bottle:PET and rPET options trade off clarity against recycled content mandates in California and EU markets.
- Tetra Pack:Established aseptic technology with global filling equipment base reduces capital barriers for new market entrants.
Carton holds the volume position, with Can climbing fastest through nitro coffee adoption in United States convenience retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's specialty coffee corridor drives format innovation for barista-style RTD products, while regulatory divergence across major economies fragments compliance strategies for multinational portfolios.
United States
Convenience retail chains in California and New York dedicate permanent refrigerated sets to branded dairy-free lines, accelerating velocity pull-through. FDA plant-based milk labeling guidance creates fortification thresholds that reshape R&D allocation toward micronutrient parity formulations. Pacific Northwest brewing clusters concentrate enzymatic hydrolysis expertise for oat protein stabilization.
Germany
Clean-label oat bases capture refrigerated set resets in Berlin and Hamburg as EFSA health claim frameworks tighten protein substantiation requirements. EU EFSA additive scrutiny forces reformulation of legacy soy portfolios toward single-source plant bases. Bavarian food science clusters develop enzymatic processing methods for mouthfeel parity.
United Kingdom
London's café culture normalizes premium cold brew positioning across grocery and foodservice channels. Extended producer responsibility frameworks under EU Packaging Waste Directive increase per-unit costs for multi-serve carton formats. Southeast England distribution hubs optimize lightweight logistics for aseptic filling networks.
South Korea
Seoul's convenience store network remains underdeveloped for oat-based RTD penetration relative to Japan, presenting first-mover shelf space opportunities. MFDS food labeling standards shape ingredient disclosure requirements for imported plant-based beverages. Gangnam district specialty retailers test nitro widget-can formats for texture differentiation.
Canada
Health Canada nutrition labeling rules align with FDA frameworks on protein fortification claims for cross-border product harmonization. Ontario and British Columbia grocery channels expand refrigerated sets for organic-certified oat formulations. Vancouver's clean-label consumer base accelerates demand for enzymatically processed single-source bases.
Dairy-Free RTD Coffee Products Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers compress R&D cycles to match expiring mouthfeel patents. The vendor base clusters around three strategic archetypes: vertically integrated agricultural processors, specialty beverage pure-plays, and multinational dairy conglomerates with plant-based extensions. M&A activity concentrates on enzymatic hydrolysis technology acquisition, while capacity expansion targets Scandinavian oat milling to circumvent supply volatility.
Within the specialty beverage pure-play tier, Califia Farms and Oatly Group AB exemplify contrasting geographic anchoring strategies for margin control. Califia occupies a position tied to West Coast distribution density and captive almond supply chains. Oatly exemplifies European retail penetration through branded refrigerated set partnerships. Among multinational conglomerates, Danone represents the portfolio diversification archetype spanning coconut, soy, and oat bases across multiple price tiers.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Califia Farms |
| Oatly Group AB |
| Danone |
| Nestlé |
| Minor Figures |
| Blue Bottle Coffee |
| La Colombe Coffee Roasters |
| RISE Brewing Co. |
| Others |
Value Chain & Pricing Dynamics
Specialty coffee chain procurement concentration in California and New York anchors contract-based pricing for barista-format RTD lines, while enzymatic oat processing costs stratify tiers across premium organic and standard conventional positioning. Three-tier pricing structure across premium, standard, and economy levels reflects USDA certification status, enzymatic hydrolysis intensity, and refrigerated versus ambient distribution requirements.
Pricing Analysis
Input-cost pass-through from Scandinavian oat protein concentrate supply volatility compresses margins for mid-tier manufacturers lacking backward integration into milling operations. Price differentiation hinges on USDA organic certification tier and enzymatic processing depth for mouthfeel parity. Pricing pressure stems from California almond pollination cost fluctuations propagating through nut milk supply chains. Convenience retail buyers exhibit highest price sensitivity, while direct-to-subscription channels tolerate premium positioning.
Supply Chain Analysis
Refrigerated freight cost premiums for cold chain distribution constrain geographic radius for barista-format products, favoring regional production clusters over centralized manufacturing. Supply concentration centers on Sweden and Finland for enzymatically treated oat bases, California for almond processing, and Southeast Asia for coconut cream sourcing. Raw material dependencies include enzymatic hydrolysis enzymes, nitrogen dosing equipment for nitro formats, and aseptic carton packaging substrates. Single-source vulnerability in Scandinavian milling capacity creates input disruption risk. Distribution runs through direct-store-delivery networks for refrigerated sets and warehouse club channels for ambient multi-serve formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy-free RTD coffee functions as a stable compounder anchored by permanent shelf space allocation in specialty coffee chains, where beverage category resets favor plant-based line extensions with proven velocity.
For Market Incumbents: Anchor margin control through backward integration into enzymatic processing capacity or captive oat milling partnerships in Scandinavia. Defend refrigerated set positioning against emerging nitro-format entrants by accelerating FDA process authority approvals for high-pressure processed ambient alternatives. Prioritize certification investment in USDA organic tiers where consumer willingness-to-pay sustains price premiums. For New Entrants and Emerging Players: Direct-to-subscription channels offer the lowest customer acquisition cost for single-origin cold brew SKUs targeting coastal metropolitan millennials. Seoul convenience store networks present underpenetrated white space relative to Japanese RTD coffee maturity. Target South Korean café culture through MFDS-compliant oat-based formulations with nitro texture differentiation. For Investors and Strategic Acquirers: Multinational dairy conglomerates with plant-based extension strategies are the most active acquirer in this space, seeking enzymatic hydrolysis technology to compress R&D cycles. Long-term viability rests on patent expiration timelines for mouthfeel technologies and clean-label formulation expertise scarcity. Monitor FDA plant-based milk labeling guidance finalization as inflection indicator for fortification investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Backward integration into Scandinavian milling secures oat protein concentrate supply against capacity constraints. |
| Nitro Widget-Can Format Launch | Crossover craft beer packaging technology creates texture differentiation in United States convenience retail. |
| USDA Organic Certification Investment | Premium shelf positioning accelerates velocity in California and New York grocery channel resets. |
| Direct-to-Subscription Channel Buildout | Curated delivery boxes displace weekly supermarket trips among coastal metropolitan millennials. |
| South Korean Market Entry | First-mover shelf space in Seoul convenience networks captures café culture normalization. |
Study Parameters
Multiple input streams — primary interviews with plant-based beverage R&D directors, specialty coffee chain category managers, and aseptic packaging equipment suppliers; secondary validation through FDA process authority filings, USDA organic certification databases, and Nielsen retail audit data — were reconciled through bottom-up SKU-level volume builds and top-down category spend analysis.
Data-stream reconciliation across product type, ingredient source, flavor profile, and packaging format dimensions generated volume and value outputs across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs incorporated enzymatic hydrolysis technology adoption curves and EU Packaging Waste Directive compliance cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for enzymatic oat protein stabilization would alter the outlook if patent expirations accelerate competitive entry. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Raw Coffee Beans Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Global Coffee Market
Coffee
Coffee Syrup Market
Coffee
Global Cafe Market
Coffee
Global Coffee Machine Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Single Origin Coffee Market
Coffee
Germany Coffee Market
Coffee
North America Coffee Market
Coffee
Ethiopia Coffee Market
Coffee
Coffee and Tea Capsule Market
Coffee
Australia Coffee Market
Coffee
South America Coffee Market
Coffee
US Instant Coffee Market