
 Flavored Cold-Brew Coffee Market | 2026-2036
Flavored Cold-Brew Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored Cold-Brew Coffee Market Insights
Market Context
The gap between premium single-origin cold-brew and mass-market commodity offerings is expanding as consumers stratify by price sensitivity and ingredient transparency. Starbucks Corporation leverages its global roasting infrastructure to sustain volume leadership across both tiers. Califia Farms specializes in plant-based flavored formulations that anchor its position in the dairy-alternative cold-brew segment. Blue Bottle Coffee dominates the ultra-premium channel through direct-to-café distribution and small-batch positioning.
Technical Definition and Segment Structure
Flavored cold-brew coffee refers to coffee extracted with room-temperature or chilled water over 12–24 hours, then infused with natural or artificial flavoring agents and packaged for ambient or refrigerated distribution. The extended steeping process yields lower acidity and reduced bitterness compared with hot-brewed counterparts, making the format suitable for ready-to-drink retail and foodservice dispensing systems. Vanilla and caramel formulations lead volume in the product type dimension, reflecting their compatibility with both dairy and oat milk bases, while bottled packaging commands the widest retail footprint despite faster growth in canned formats driven by convenience-oriented consumption occasions. Online retailers represent the fastest-expanding distribution channel, though supermarkets still concentrate the bulk of margin pools through slotting fees and promotional programming.
Regulatory Environment and Outlook
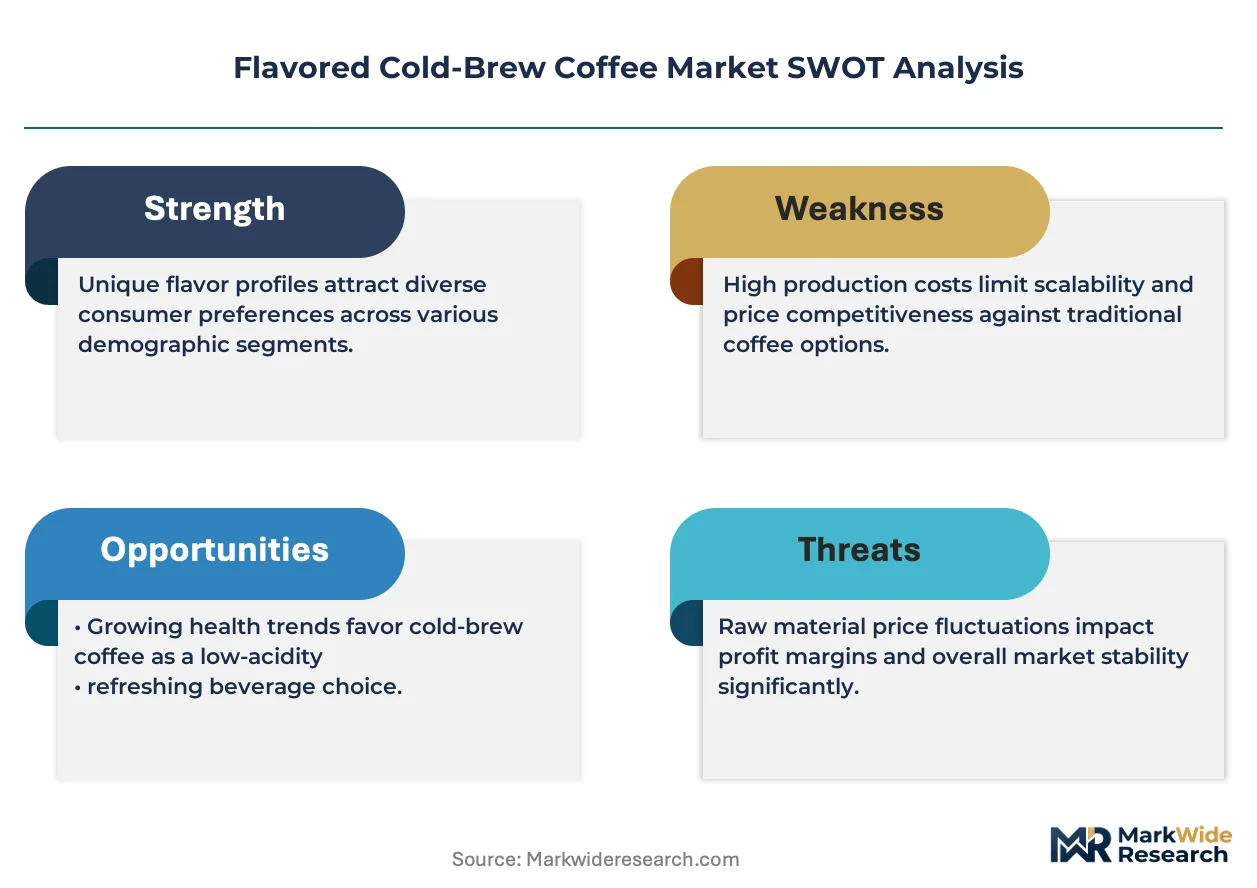
FDA nutrition labeling mandates and state-level bottle deposit legislation in California, New York, and Oregon shape compliance costs and packaging material selection across the supply chain. USDA organic certification and non-GMO verification standards increasingly filter market access for premium entrants targeting health-conscious consumers. Stakeholders must monitor evolving caffeine disclosure requirements and sugar taxation proposals that could force reformulation trade-offs between taste profile and regulatory compliance.
Market Dynamics
Refrigerated supply chain expansion is compressing distribution timelines for perishable cold-brew formats, forcing bottlers to co-locate extraction facilities near metropolitan demand clusters rather than centralized roasting hubs.
Growth Catalysts
- Convenience store shelf-space reallocation:C-store operators in the United States dedicate incremental cooler doors to ready-to-drink coffee, capturing commuter traffic that previously favored fountain soda.
- Oat milk compatibility:Barista-grade oat formulations from Swedish suppliers enable cleaner flavor integration than earlier almond or soy bases, expanding addressable consumers with dairy restrictions.
- FDA added-sugar disclosure mandates:Transparent labeling requirements accelerate reformulation toward naturally sweetened profiles, creating first-mover advantage for brands with pre-existing clean-label positioning.
Market Restraints
- Arabica price volatility:Brazilian frost cycles and Colombian labor disruptions transmit directly to cold-brew input costs, compressing margin at the commodity tier.
- Glass bottle supply concentration:Domestic container manufacturing clusters in Ohio and Pennsylvania create geographic vulnerability to logistics shocks.
- Refrigerated trucking capacity scarcity:Driver shortages in the temperature-controlled freight sector limit expansion into secondary markets.
Strategic Opportunities
- Direct-to-office subscription channels:Corporate beverage programs in Austin and Denver bypass retail slotting fees while securing predictable volume.
- Nitrogen-infusion technology convergence:Draft-system hardware from Irish equipment suppliers merges with ambient retail formats, enabling on-premise dispensing without keg infrastructure.
- California bottle-deposit expansion:State-level redemption value increases incentivize aluminum can migration, opening shelf-stable distribution pathways previously blocked by deposit complexity.
Industry Challenges
- Cold-chain HACCP certification timelines:FDA hazard analysis protocols for refrigerated beverages extend facility qualification periods, delaying new entrant market entry.
- Flavor chemist talent scarcity:Formulation expertise bridging coffee roasting science and beverage flavor systems concentrates among a handful of consultants in Portland and San Francisco.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored Cold-Brew Coffee Market |
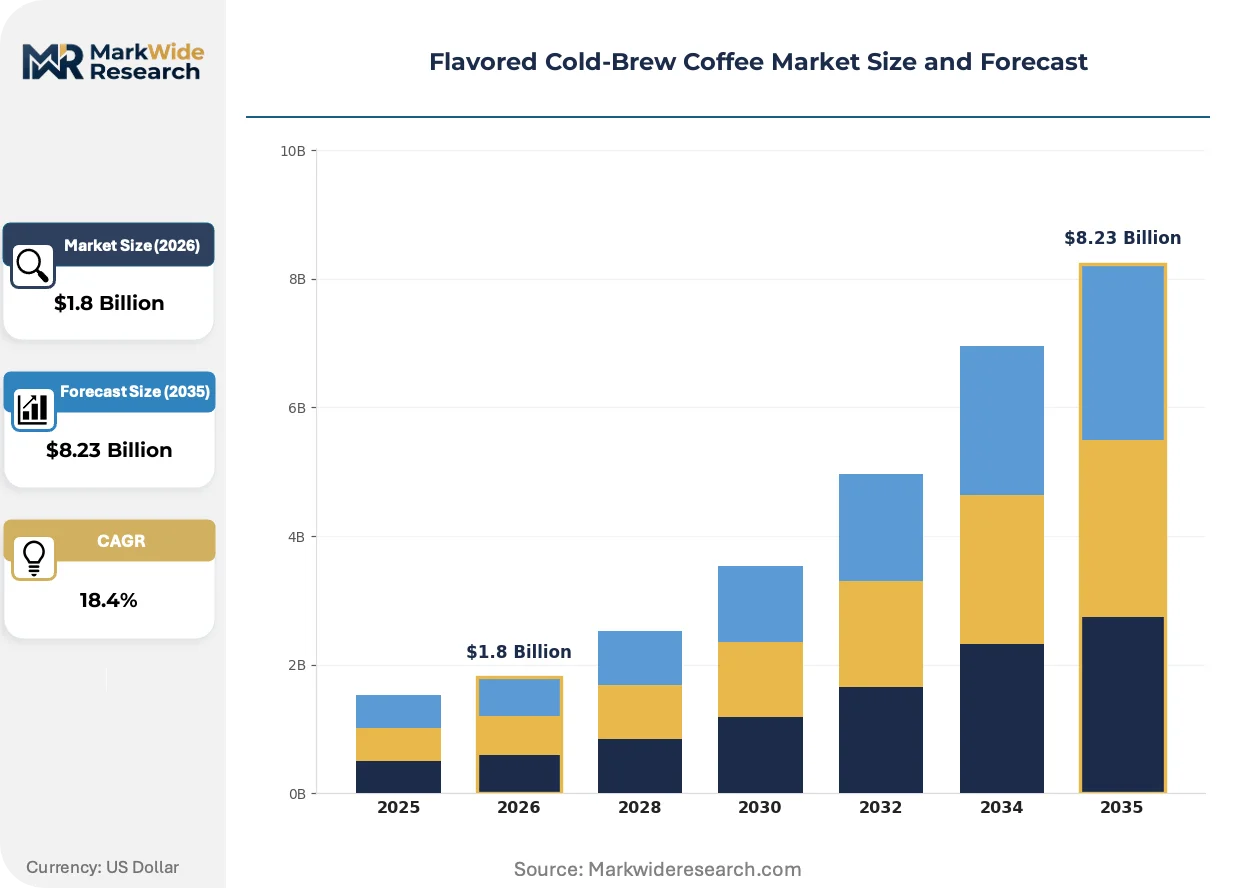
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanilla, Hazelnut, Caramel, Mocha Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Cafés Packaging Type: Bottled, Canned, Tetra Pack, K-Cup End User: Millennials, Health-Conscious Consumers, Office Workers, Students |
| Companies Covered | Starbucks Corporation, Nestlé S.A., Califia Farms, JAB Holding Company, The J.M. Smucker Company, La Colombe Coffee Roasters, Blue Bottle Coffee, Grady's Cold Brew, HighBrew Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored Cold-Brew Coffee Market Trends and Innovations
High-pressure processing equipment is entering cold-brew facilities, extending shelf life without thermal degradation while preserving volatile aromatic compounds that heat pasteurization destroys.
Flash-chilled extraction systems is rewriting production economics for mid-scale bottlers. Equipment from Italian manufacturers reduces steeping cycles from eighteen hours to ninety minutes while maintaining comparable total dissolved solids. Regional roasters in Chicago and Seattle adopt these systems to fulfill foodservice contracts with twenty-four-hour turnaround requirements. The compression is eroding the batch-size advantage that industrial-scale competitors previously held over craft entrants.
FDA nutrition labeling modernization mandates force reconciliation between cold-brew concentrate and ready-to-drink serving declarations. Bottlers must disaggregate caffeine content from total coffee solids, complicating multi-SKU portfolio management. Premium positioned brands with single-origin supply chains face disproportionate compliance burden relative to commodity blenders with centralized formulation labs.
Subscription replenishment algorithms now trigger automatic cold-brew shipments based on individual consumption velocity rather than fixed calendar intervals. Direct-to-consumer platforms in Brooklyn and Los Angeles deploy machine learning models trained on pantry-scanning mobile applications. The shift concentrates customer lifetime value among digitally native entrants while supermarket loyalty programs struggle to replicate predictive replenishment capabilities.
Flavored Cold-Brew Coffee Market Segmentation
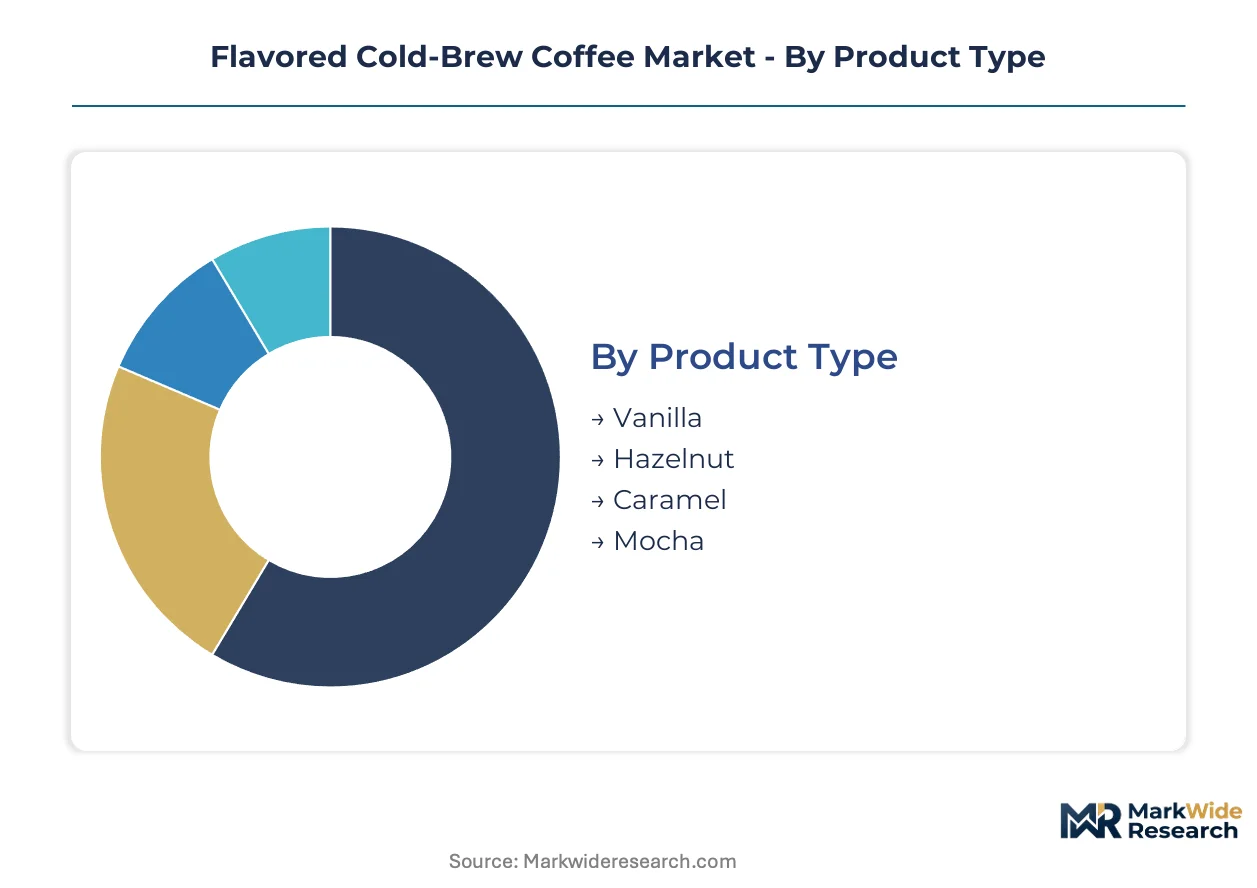
Segmentation in flavored cold-brew coffee reveals how formulation choices, channel access, and consumption occasions fragment addressable demand. Manufacturers must align production scale and shelf-life engineering to the specific velocity and margin profile of each slice.
Product Type:
Standardization dominates vanilla and caramel formulations, while hazelnut and mocha variants demand more complex stabilization protocols and carry shorter production runs.
- Vanilla:The most chemically stable flavor base in cold-brew matrices, compatible with both dairy and oat milk systems without separation. Demand concentrates in U.S. supermarkets where family-pack formats drive volume, though vanilla's ubiquity now compresses differentiation premiums.
- Caramel:Requires precise pH buffering to prevent Maillard browning during extended refrigerated storage. Caramel anchors the convenience store channel in Texas and Florida, where commuter grab-and-go occasions favor sweetness intensity over subtlety.
- Hazelnut:Nut-allergen labeling requirements from FDA complicate co-packing arrangements, limiting supplier flexibility.
- Mocha:Cocoa powder suspension demands homogenization equipment that smaller roasters often lack.
Most installed capacity flows through vanilla. Expansion is steepest in caramel.
Distribution Channel:
Channel selection determines refrigeration requirements, promotional spend ratios, and data capture depth for each brand.
- Supermarkets:Slotting fees and promotional calendars absorb 15-20% of gross revenue for national distribution, but scanner data enables precise velocity tracking by SKU. The channel rewards scale and shelf-stable formats that minimize shrink.
- Online Retailers:Subscription algorithms and pantry-scanning apps concentrate customer lifetime value among digitally native entrants. Brooklyn and Los Angeles platforms deploy predictive replenishment that supermarket loyalty programs cannot replicate.
- Convenience Stores:Refrigerated cooler doors in U.S. c-stores are reallocating from fountain soda to ready-to-drink coffee, capturing commuter traffic.
- Cafés:Draft-system dispensing without keg infrastructure is emerging through nitrogen-infusion hardware from Irish equipment suppliers.
Supermarkets still concentrate the bulk of margin pools. Online retailers are gaining share fastest.
Packaging Type:
Material choice reflects trade-offs between shelf-life extension, deposit legislation compliance, and consumer occasion portability.
- Bottled:Glass commands the widest retail footprint despite weight and breakage costs. Domestic container manufacturing clusters in Ohio and Pennsylvania create geographic vulnerability to logistics shocks.
- Canned:Aluminum enables shelf-stable distribution and benefits from California bottle-deposit expansion incentives. The format is climbing the fastest as younger consumers prioritize portability over premium perception.
- Tetra Pack:Aseptic filling lines require capital investment that mid-scale bottlers struggle to justify.
- K-Cup:Single-serve pods face sustainability scrutiny and brewing temperature limitations that underextract cold-brew concentrate.
Bottled formats retain the highest price realization. Cans are expanding most quickly.
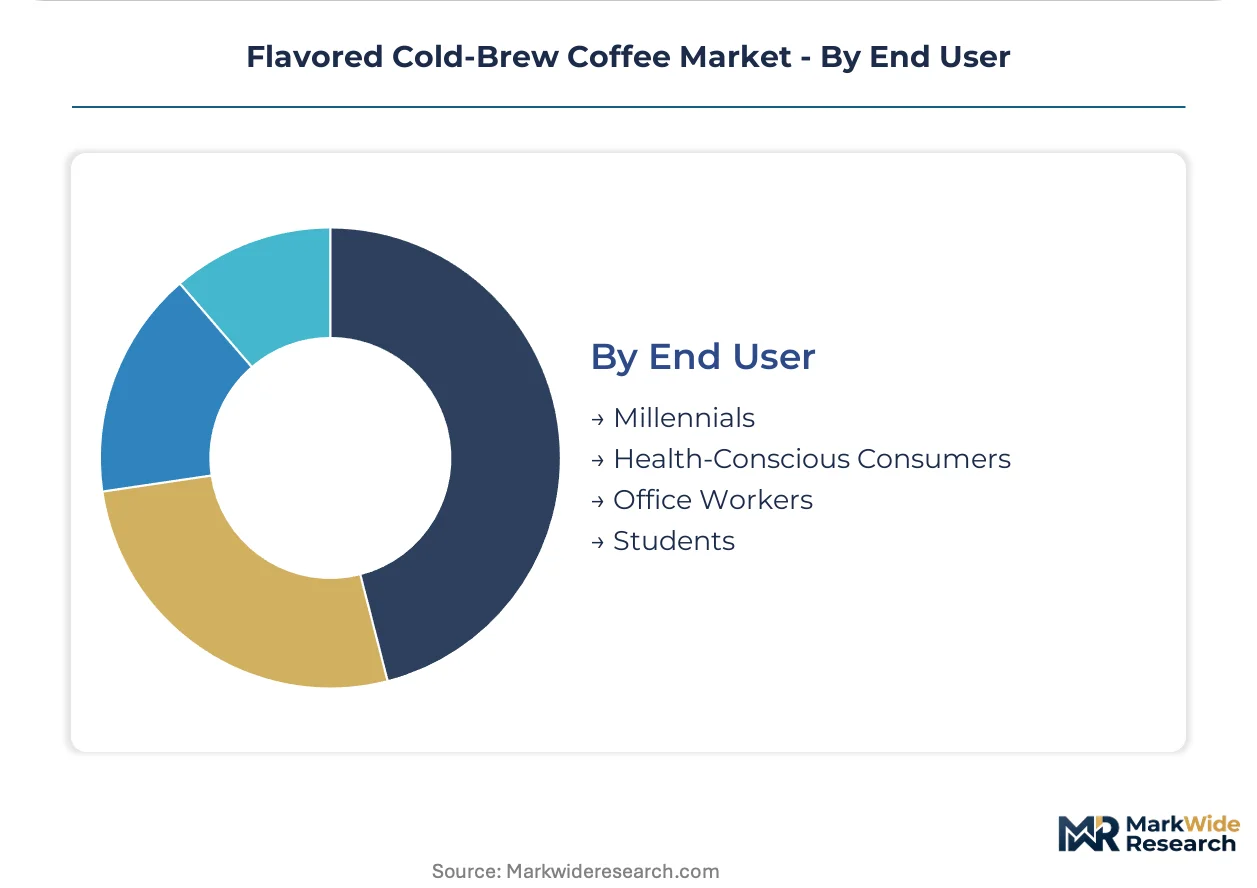
End User:
User archetypes differ in purchase frequency, price elasticity, and sensitivity to ingredient transparency claims.
- Millennials:The core volume driver, purchasing across all channels with high trial rates for novel flavors. This cohort responds to Instagram-native branding and limited-edition collaborations.
- Health-Conscious Consumers:USDA organic certification and non-GMO verification standards filter their consideration sets, accepting price premiums for clean-label positioning.
- Office Workers:Corporate beverage programs in Austin and Denver bypass retail slotting fees while securing predictable volume through direct-to-office subscriptions.
- Students:Price sensitivity concentrates demand in private-label and promotional SKUs, with channel preference shifting toward convenience stores near campus clusters.
Millennials represent the largest installed base. Health-conscious consumers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemists and beverage formulation specialists cluster in Portland and San Francisco, anchoring innovation pipelines that feed production facilities across three continents. This talent concentration shapes regional competitive dynamics as much as raw material access or consumer demand density.
United States
Convenience store cooler reallocation toward ready-to-drink coffee captures commuter traffic previously flowing to fountain soda. FDA added-sugar disclosure mandates force reformulation trade-offs between taste intensity and clean-label positioning. Extraction facilities co-locate near metropolitan demand clusters in Chicago and Seattle rather than centralized roasting hubs.
Germany
Barista-grade oat milk compatibility drives adoption among consumers with dairy restrictions, expanding addressable segments beyond traditional coffee drinkers. EFSA caffeine labeling requirements create compliance complexity for concentrate and ready-to-drink serving declarations. Industrial equipment manufacturers in Milan supply flash-chilled extraction systems that compress steeping cycles for mid-scale bottlers.
Japan
Corporate beverage programs and direct-to-office subscription channels secure predictable volume outside retail slotting fee structures. METI standards for refrigerated supply chain certification extend facility qualification timelines for new market entrants. Tokyo-based platforms deploy predictive replenishment algorithms trained on consumption velocity rather than fixed calendar intervals.
Brazil
Arabica price volatility from frost cycles and labor disruptions transmits directly to cold-brew input costs, compressing margins at the commodity tier. National agricultural policy stabilizes supply through crop insurance programs and research station breeding initiatives. São Paulo roasting clusters integrate backward into green coffee sourcing to defend margin positions against spot market swings.
United Kingdom
Supermarket promotional calendars and slotting fees absorb substantial gross revenue shares for national distribution, rewarding scale and shelf-stable formats. Health-conscious consumer segments filter consideration sets through organic certification and non-GMO verification standards. London direct-to-consumer platforms concentrate customer lifetime value through subscription algorithms that incumbent retail loyalty programs cannot replicate.
Flavored Cold-Brew Coffee Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across extraction technology and flavor formulation. The market structures around three tiers: multinational beverage conglomerates with captive roasting infrastructure, plant-based dairy specialists leveraging oat milk compatibility, and ultra-premium craft roasters emphasizing small-batch positioning. Consolidation pressure intensifies as refrigerated supply chain requirements raise minimum efficient scale. Competitive moves center on nitrogen-infusion hardware partnerships and direct-to-office subscription channel development.
Among beverage conglomerates, Starbucks Corporation exemplifies scale-driven positioning through global roasting infrastructure sustaining volume leadership across premium and mass-market tiers. Califia Farms occupies a specialist position within the plant-based flavored formulation segment, anchoring competitive dynamics in dairy-alternative cold-brew. Blue Bottle Coffee represents the ultra-premium archetype through direct-to-café distribution and small-batch market positioning.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Nestlé S.A. |
| Califia Farms |
| JAB Holding Company |
| The J.M. Smucker Company |
| La Colombe Coffee Roasters |
| Blue Bottle Coffee |
| Grady's Cold Brew |
| HighBrew Coffee |
| Others |
Pricing and Supply Chain Analysis
Arabica green coffee futures transmit Brazilian frost risk directly through commodity-tier cold-brew pricing, while refrigerated trucking scarcity forces premium brands toward metropolitan co-location that compresses margin recovery at the high end.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription replenishment algorithms from single-unit retail transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient transparency and extraction batch size. Cost compression in the commodity tier intensifies because Brazilian spot market volatility transmits without hedging buffers. Students and price-sensitive convenience store purchasers exhibit highest elasticity, while health-conscious consumers accept organic certification premiums.
Supply Chain Analysis
Green coffee sourcing rests on Brazilian arabica cooperatives, Colombian high-altitude estates, and Ethiopian heirloom variety exporters. Oat milk barista formulations draw from Swedish specialty processors, while glass bottle manufacturing clusters in Ohio and Pennsylvania. Single-source vulnerability concentrates in domestic container supply during logistics shocks. Distribution runs through refrigerated trucking networks to metropolitan cold-storage hubs, with ambient can formats bypassing temperature-controlled requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: FDA added-sugar disclosure mandates impose reformulation costs on U.S. bottlers that European competitors under EFSA guidelines avoid, creating margin differential for export-oriented production.
For Market Incumbents: To counter flash-chilled extraction technology erosion from Italian equipment suppliers, anchor volume through captive roasting infrastructure in Chicago and Seattle while deepening backward integration into green coffee sourcing. Secure nitrogen-infusion hardware partnerships with Irish draft-system manufacturers to defend café channel positioning against craft entrants.
For New Entrants and Emerging Players: Launch via direct-to-office subscription channels in Austin and Denver corporate clusters, bypassing supermarket slotting fee structures that absorb fifteen to twenty percent of gross revenue. Target health-conscious consumer segments with pre-existing USDA organic certification and oat milk compatibility formulations.
For Investors and Strategic Acquirers: Consolidation pressure builds where refrigerated supply chain requirements raise minimum efficient scale beyond mid-scale roaster capacity. Long-term viability favors asset-light designers with predictive replenishment algorithms over capital-heavy extraction facility operators. Watch California bottle-deposit expansion legislation as signal for aluminum can migration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Office Subscription Launch | Bypasses retail slotting fees while securing predictable volume from Austin and Denver corporate programs. |
| Nitrogen-Infusion Hardware Partnership | Enables draft-system dispensing without keg infrastructure through Irish equipment supplier integration. |
| Flash-Chilled Extraction Adoption | Compresses steeping cycles from eighteen hours to ninety minutes using Italian manufacturer systems. |
| Aluminum Can Format Migration | Opens shelf-stable distribution pathways incentivized by California bottle-deposit redemption value increases. |
| Predictive Replenishment Algorithm Deployment | Concentrates customer lifetime value through machine learning models trained on pantry-scanning mobile applications. |
Research Methodology
Multiple input streams — primary interviews with cold-brew extraction facility operators, flavor formulation chemists, and convenience store category buyers, alongside secondary validation from FDA labeling guidance documents, USDA organic certification databases, and refrigerated freight capacity reports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume projections to product type, distribution channel, packaging format, and end-user archetype segmentation across the analysis window. CAGRs derived from historical velocity patterns in scanner data and forward-looking capacity announcements from extraction equipment manufacturers. Forecast inputs incorporated oat milk compatibility adoption curves and nitrogen-infusion technology penetration rates.
Several conditions sit outside the modeled scope, including Arabica futures price spike scenarios beyond historical volatility bands and unscheduled FDA caffeine disclosure requirement changes. Forecasts reflect documented assumptions about refrigerated trucking capacity normalization and metropolitan co-location feasibility. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Global Coffee Machine Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Singapore Coffee Roaster Market
Coffee
Coffee Grinder Market
Coffee
Instant Coffee Market
Coffee
Coffee Pods Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Coffee Extracts Market
Coffee
Coffee Capsules Market
Coffee
Cold Brew Coffee Market
Coffee
Espresso Coffee Market
Coffee
North America Instant Coffee Market