
 Coffee Crystal Market | 2026-2036
Coffee Crystal Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Crystal Market Analysis
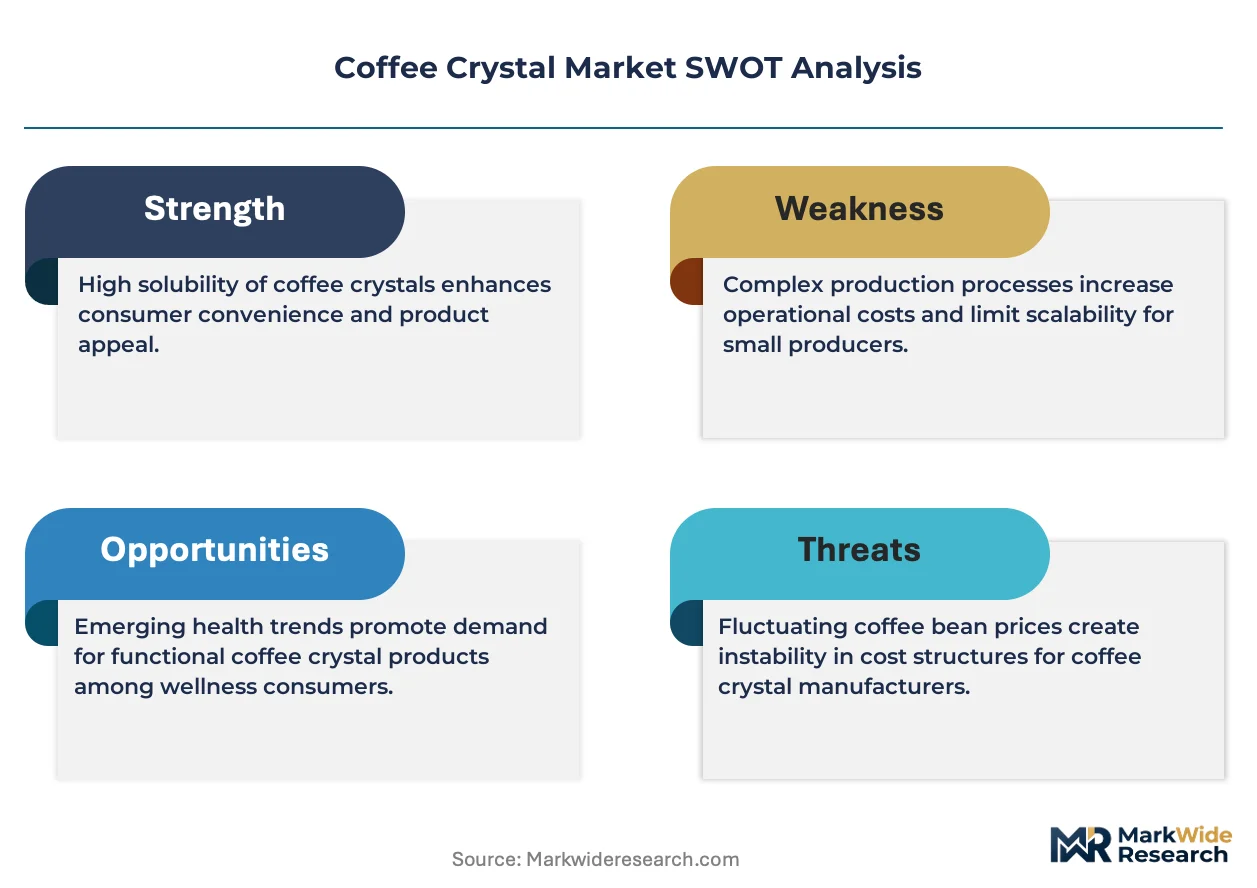
Single-serve pouch configurations are rebalancing buyer choice across retail and food service channels, shifting volume away from traditional glass jar formats. Nestle leverages its freeze-dried production infrastructure to anchor premium positioning in North American and European supermarkets. Jacobs Douwe Egberts sustains broad portfolio coverage across spray-dried and granulated formats, competing on price-accessibility in emerging markets. Tata Consumer Products specializes in bulk-bag supply to industrial beverage manufacturers, extending its presence in Middle Eastern and African distribution networks.
Coffee crystals denote soluble coffee products manufactured through either freeze-drying or spray-drying processes, yielding particles with moisture content below 5% and rapid reconstitution in water at temperatures ranging from 85°C to boiling. Freeze-dried coffee retains volatile aromatic compounds through sublimation, commanding premium placement, while spray-dried variants dominate volume through lower energy intensity and faster throughput. Spray-dried coffee occupies the largest share of production volume owing to established manufacturing scale and input cost efficiency. Freeze-dried coffee represents the fastest-growing product type as specialty coffee positioning migrates into instant formats. Pouch packaging captures expanding margin pools through reduced material cost and e-commerce logistics optimization.
The FDA enforces Good Manufacturing Practice standards and FSMA traceability requirements that elevate compliance costs for coffee crystal importers into the United States. EFSA and EU Green Deal sustainability frameworks shape demand for deforestation-free supply chain certification across European procurement. BIS quality standards in India and CDSCO food additive regulations constrain market entry for non-compliant foreign suppliers. Stakeholders must monitor evolving packaging waste directives and carbon border adjustments that will redefine cost structures and sourcing geographies.
Market Dynamics
The FDA's updated Food Safety Modernization Act traceability rules are compressing supplier qualification timelines and forcing ready-to-drink beverage manufacturers to revalidate sourcing relationships across their coffee crystal procurement networks.
Growth Catalysts
- Single-serve pouch adoption:Food service operators and e-commerce retailers are accelerating procurement of flexible-format coffee crystals to reduce material cost and optimize last-mile logistics.
- Brazilian processing capacity expansion:Export-oriented soluble coffee infrastructure in São Paulo and Minas Gerais is capturing inbound demand from Middle Eastern and African distribution networks.
- Freeze-drying technology maturation:Specialty coffee positioning migrating into instant formats is pulling capital toward sublimation-based production lines that preserve volatile aromatic compounds.
Market Restraints
- Robusta arabica price volatility:Green coffee bean cost swings directly compress spray-dried margin structures given energy-intensive throughput requirements.
- EU deforestation-free certification:EFSA and EU Green Deal sustainability frameworks are extending compliance timelines for non-certified suppliers seeking European market access.
- Ready-to-drink liquid coffee substitution:Cold brew concentrate and nitro can formats are displacing at-home reconstitution occasions in North American convenience channels.
Strategic Opportunities
- Middle East food service penetration:Bulk-bag supply relationships with hospitality chains in Dubai and Riyadh remain underdeveloped relative to South Asian sourcing concentration.
- Carbon border adjustment preparation:EU importers are pre-qualifying low-carbon-intensity spray-dried suppliers ahead of phased carbon border tax implementation.
- Hybrid freeze-spray drying convergence:Process technology blending aroma retention with throughput efficiency is opening mid-premium positioning between commodity and specialty tiers.
Industry Challenges
- FSMA traceability system integration:Legacy batch-recording infrastructure at older spray-drying facilities requires capital-intensive retrofit to meet lot-level tracking mandates.
- Aroma chemist talent scarcity:Formulation expertise for volatile compound stabilization in freeze-dried products concentrates among a narrow pool of European and Japanese specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Crystal Market |
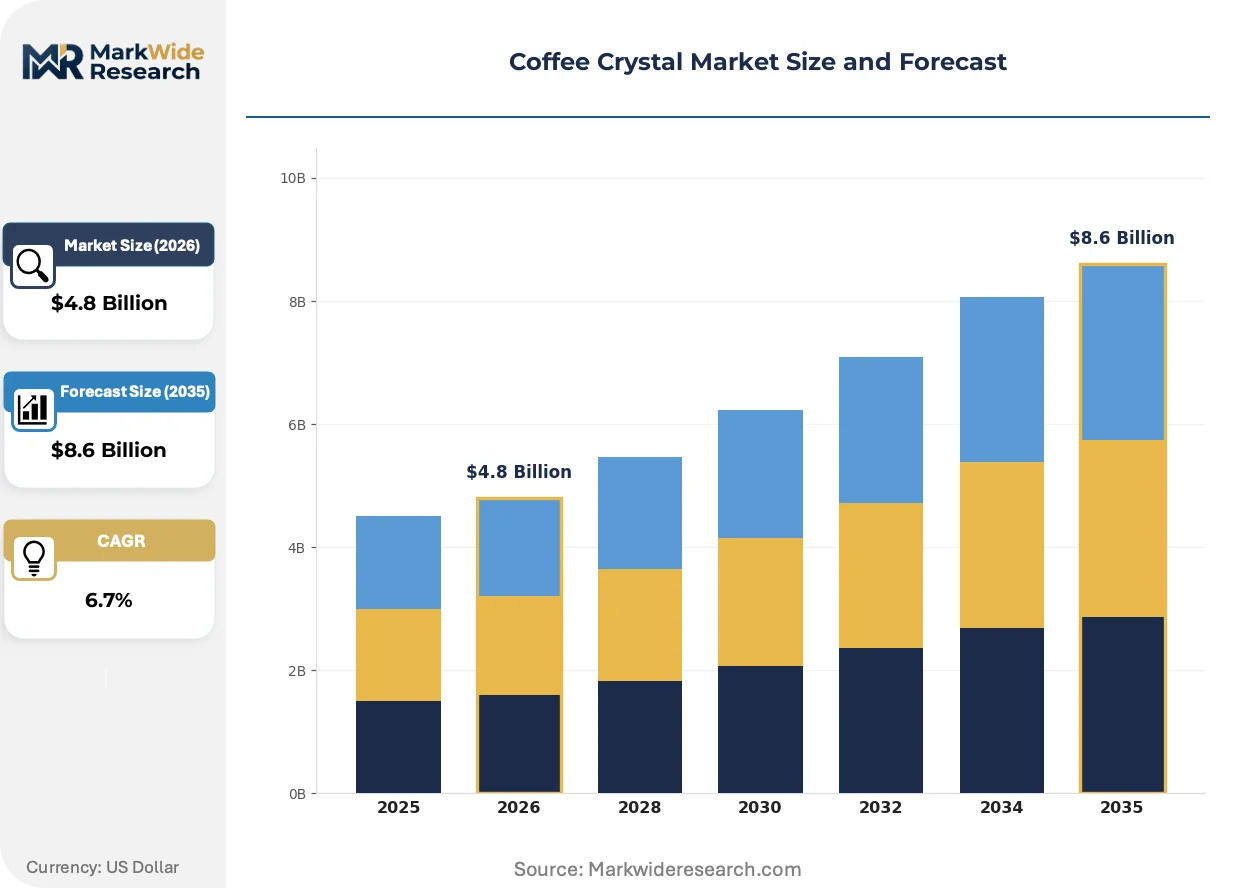
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Coffee Crystals, Freeze-Dried Coffee, Spray-Dried Coffee, Granulated Coffee End User: Food Service, Retail, E-commerce, HoReCa Packaging Type: Bottles, Pouches, Bulk Bags, Capsules Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Nestle, Starbucks, Jacobs Douwe Egberts, Kraft Heinz, Tata Consumer Products, Tchibo, Bustelo, Mount Hagen, Folgers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Crystal Market Emerging Trajectories
Technology convergence and regulatory compression are redrawing competitive boundaries between freeze-dried premium positioning and spray-dried volume dominance across procurement and distribution channels.
Micro-batch freeze-drying equipment is decentralizing production geography by enabling specialty roasters to retain aromatic integrity without capital-scale infrastructure. Mid-sized Brazilian and Colombian processors are adopting these systems to bypass traditional toll-manufacturing relationships with multinational freeze-drying networks. The technology is decentralizing supply concentration that historically anchored premium instant coffee production in Swiss and German facilities.
EFSA's tightening maximum residue limits for acrylamide in roasted coffee products are forcing spray-dried manufacturers to revalidate thermal process parameters. Facilities operating older rotary atomization systems face retrofit costs or volume displacement to compliant competitors. European private-label suppliers are responding by consolidating procurement toward integrated processors with in-house laboratory verification capacity.
Direct-to-procurement relationships between ready-to-drink bottlers and soluble coffee processors are shortening traditional ingredient distribution hierarchies. Large beverage manufacturers are establishing dedicated supply agreements that bypass regional distributor markups for coffee crystal inputs. This channel compression is most visible in North American and Western European markets where bottler consolidation has concentrated buying power among three dominant ready-to-drink coffee brands.
Coffee Crystal Market Segmentation
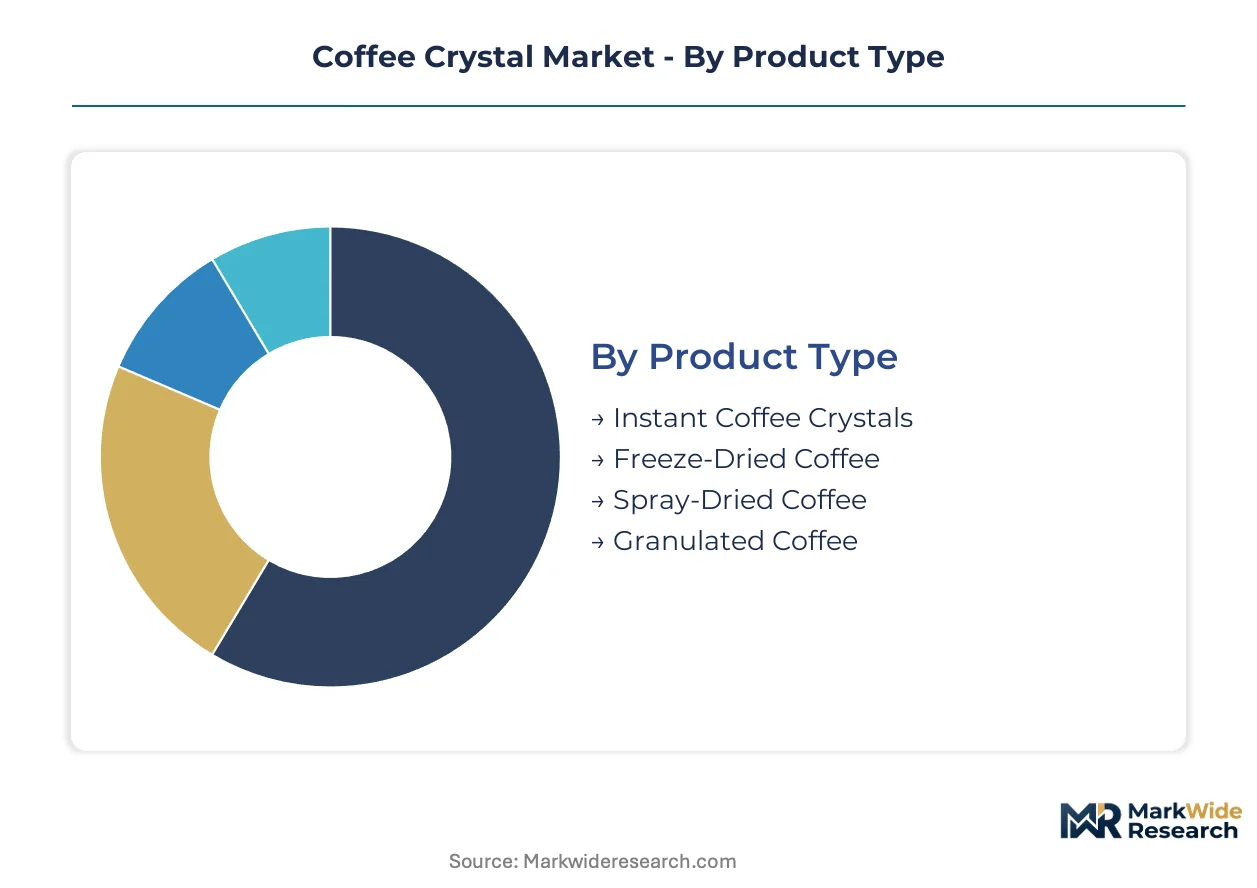
Coffee crystal segmentation reveals divergent margin structures between commodity spray-dried volume and premium freeze-dried positioning. Procurement patterns across food service, retail, and industrial channels demand distinct packaging configurations and distribution economics.
Product Type:
Volume concentration dominates spray-dried production, while freeze-dried variants capture expanding premium shelf space in specialty retail.
- Instant Coffee Crystals:Broad category encompassing all soluble formats with moisture content below 5% and rapid reconstitution properties. Demand concentrates in Brazilian export processing for Middle Eastern and African distribution networks driven by food service procurement scale.
- Freeze-Dried Coffee:Sublimation-based production preserves volatile aromatic compounds through low-temperature dehydration. Specialty coffee positioning migrating into instant formats pulls capital toward this technology in Swiss and German processing facilities constrained by aroma chemist talent scarcity.
- Spray-Dried Coffee:Rotary atomization delivers lower energy intensity and faster throughput for commodity-grade production.
- Granulated Coffee:Agglomerated particles from re-wet spray-dried base offer intermediate solubility characteristics.
Mature deployment sits with Spray-Dried Coffee. Newer deployment is concentrated in Freeze-Dried Coffee.
End User:
Procurement scale separates institutional buyers from fragmented household demand, with channel-specific packaging and logistics requirements.
- Food Service:High-volume procurement from restaurant chains and catering operators demands bulk-bag configurations with consistent batch quality. Brazilian processors in São Paulo and Minas Gerais anchor supply relationships with Middle Eastern hospitality networks expanding procurement of soluble coffee inputs.
- Retail:Supermarket and hypermarket channels balance shelf-stable glass jars against flexible pouch formats. North American and European retailers are rebalancing assortment toward single-serve configurations that optimize e-commerce logistics and reduce material cost.
- E-commerce:Direct-to-consumer fulfillment favors lightweight pouch packaging with extended shelf-life specifications.
- HoReCa:Hotel, restaurant, and café procurement requires reliable supply cadence and private-label formulation flexibility.
Established volume concentrates in Food Service. Expanding deployment is concentrated in E-commerce.
Packaging Type:
Material cost and logistics optimization drive format selection across temperature-controlled and ambient supply chains.
- Bottles:Traditional glass jar formats retain visibility in European and North American supermarket shelves despite higher material cost and breakage rates. Nestle maintains premium positioning through proprietary jar designs that signal freeze-dried quality differentiation.
- Pouches:Flexible film configurations reduce shipping weight and enable single-serve portioning for food service and e-commerce channels. Retailers and bottlers are accelerating procurement of pouch-format coffee crystals to optimize last-mile delivery economics.
- Bulk Bags:Industrial-scale flexible intermediate bulk containers serve ready-to-drink manufacturers and large food service operators.
- Capsules:Portion-controlled pods compete with soluble formats in convenience-oriented consumption occasions.
Dominant deployment sits with Bottles. Fastest-gaining deployment is concentrated in Pouches.
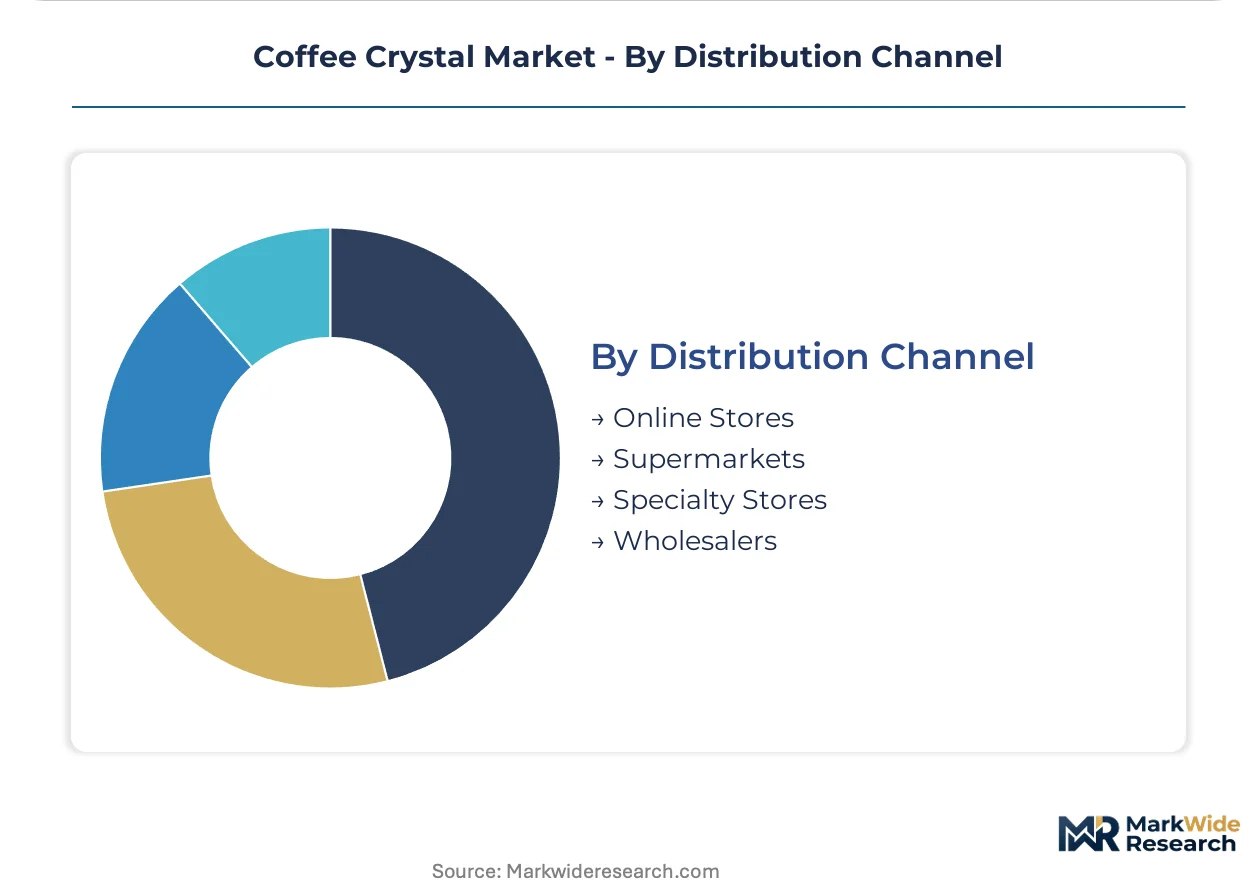
Distribution Channel:
Channel compression is shortening traditional ingredient hierarchies as large buyers establish direct processor relationships.
- Online Stores:Direct-to-consumer platforms and B2B procurement portals enable bypass of regional distributor markups. Ready-to-drink bottlers in North America are establishing dedicated supply agreements that disintermediate traditional ingredient distribution layers.
- Supermarkets:Mass retail chains anchor volume for household reconstitution occasions with extensive private-label assortment. European private-label suppliers are consolidating procurement toward integrated processors with in-house laboratory verification capacity for EFSA acrylamide compliance.
- Specialty Stores:Premium coffee retailers and gourmet food shops curate freeze-dried selections for specialty positioning.
- Wholesalers:Traditional distribution networks persist in emerging markets with fragmented retail infrastructure.
Conventional volume sits with Supermarkets. Channel expansion is concentrated in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Brazil and Vietnam supply raw material to processing facilities concentrated in Switzerland and Germany, while consumption demand fragments across divergent regulatory environments and channel preferences.
Brazil
Domestic soluble coffee consumption climbs alongside export-oriented processing capacity expansion in São Paulo and Minas Gerais. ANVISA enforces food additive and labeling standards that constrain non-compliant foreign supplier entry. Brazilian processors capture inbound demand from Middle Eastern hospitality networks through bulk-bag supply relationships.
United States
Ready-to-drink beverage manufacturers revalidate sourcing relationships under compressed supplier qualification timelines. FDA traceability rules under FSMA elevate compliance costs for coffee crystal importers and force lot-level tracking infrastructure upgrades. Nestle leverages freeze-dried production infrastructure to anchor premium positioning in North American supermarket channels.
Germany
Specialty coffee positioning migrates into instant formats, pulling capital toward sublimation-based production lines. EFSA maximum residue limits for acrylamide force spray-dried manufacturers to revalidate thermal process parameters. Swiss and German processing facilities face aroma chemist talent scarcity for volatile compound stabilization.
India
Tata Consumer Products extends bulk-bag supply presence across Middle Eastern and African distribution networks. BIS quality standards and CDSCO food additive regulations constrain market entry for non-compliant foreign suppliers. Karnataka and Tamil Nadu processing clusters serve industrial beverage manufacturers with consistent batch quality requirements.
United Arab Emirates
Hospitality chains in Dubai and Riyadh accelerate procurement of flexible-format coffee crystals for food service operations. MOHAP food safety frameworks align with Gulf standardization council requirements for import clearance. Dubai-based distribution hubs consolidate South Asian sourcing concentration for re-export across regional networks.
Coffee Crystal Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across spray-dried commodity volume and freeze-dried premium positioning. The vendor base separates into three strategic archetypes: multinational food conglomerates with integrated soluble coffee divisions, regional processors serving industrial bulk buyers, and specialty roasters adopting micro-batch freeze-drying equipment. Competitive moves concentrate on direct-to-procurement relationship establishment with ready-to-drink bottlers and carbon border adjustment pre-qualification for EU market access.
Within the multinational conglomerate tier, Nestle and Jacobs Douwe Egberts exemplify divergent strategic positioning—Nestle anchoring premium freeze-dried placement through proprietary production infrastructure, Jacobs Douwe Egberts sustaining broad portfolio coverage across spray-dried and granulated formats. Tata Consumer Products occupies a position among industrial bulk suppliers with specialized hospitality network penetration. These three entities represent distinct competitive vectors: premium technology leadership, price-accessible emerging market coverage, and industrial channel specialization.
| Leading Market Players |
|---|
| Nestle |
| Starbucks |
| Jacobs Douwe Egberts |
| Kraft Heinz |
| Tata Consumer Products |
| Tchibo |
| Bustelo |
| Mount Hagen |
| Folgers |
| Others |
Supply Flow & Price Mechanics
Freeze-dried and spray-dried tier divergence manifests in divergent margin structures and sourcing configurations across the coffee crystal market. Premium sublimation-based production commands contract-based long-term offtake agreements with ready-to-drink bottlers, while commodity rotary atomization operates on commodity spot pricing tethered to green coffee bean futures volatility.
Pricing Analysis
Margin tightening in spray-dried commodity tiers reflects Robusta arabica price volatility and energy-intensive throughput requirements. Three-tier pricing structure across premium, standard, and economy levels differentiates by quality grade and certification level, with FSMA-compliant suppliers capturing brand premium in North American procurement. Cost-down pressure on standard-tier processors accelerates because Brazilian capacity expansion floods Middle Eastern spot markets. Food service operators demonstrate highest price sensitivity, while ready-to-drink manufacturers with dedicated supply agreements exhibit lowest.
Supply Chain Analysis
Regional distribution centers in Dubai and São Paulo anchor hub-and-spoke patterns for Middle Eastern and African networks. Supply concentrates in Brazil, Vietnam, and Switzerland, with raw material dependencies on green coffee beans, natural gas for thermal processing, and aroma stabilization chemistries. Single-source vulnerability in Swiss and German freeze-drying facilities amplifies risk given aroma chemist talent scarcity. Distribution runs through direct-to-procurement relationships that disintermediate traditional ingredient hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying technology maturation is displacing legacy spray-dried infrastructure as specialty coffee positioning migrates into instant formats. Capital allocation should anticipate this transition phase rather than reinforce incumbent commodity scale.
For Market Incumbents: Anticipate cold brew concentrate substitution in North American convenience channels by deepening backward integration into Brazilian green coffee sourcing. Secure FSMA traceability system integration ahead of lot-level tracking mandates to defend contract renewals with ready-to-drink bottlers. Prioritize aroma chemist recruitment or specialist firm acquisition to address formulation expertise scarcity in volatile compound stabilization. For New Entrants and Emerging Players: Begin with micro-batch freeze-drying equipment deployment to serve specialty roasters seeking aromatic integrity without multinational toll-manufacturing relationships. Target underdeveloped bulk-bag supply relationships with hospitality chains in Riyadh and Dubai, where South Asian sourcing concentration leaves procurement gaps. Pursue direct-to-procurement positioning with mid-sized ready-to-drink brands seeking to bypass regional distributor markups. For Investors and Strategic Acquirers: Re-rating potential sits with integrated processors owning in-house laboratory verification capacity given EFSA acrylamide compliance requirements. Long-term viability favors facilities with hybrid freeze-spray drying convergence technology bridging premium and commodity tiers. Monitor EU carbon border adjustment pre-qualification activity as inflection indicator for low-carbon-intensity supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Green Coffee Sourcing | Brazilian processors secure input cost stability against Robusta arabica futures volatility. |
| FSMA Traceability System Deployment | Lot-level tracking infrastructure satisfies FDA mandates for ready-to-drink bottler procurement. |
| Micro-Batch Freeze-Drying Equipment Adoption | Specialty roasters bypass Swiss and German toll-manufacturing concentration for aromatic retention. |
| Carbon Border Adjustment Pre-Qualification | Low-carbon-intensity spray-dried suppliers secure preferred EU importer status ahead of tax implementation. |
| Direct-to-Procurement Relationship Establishment | Ready-to-drink bottlers disintermediate regional distributor markups for coffee crystal inputs. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with soluble coffee plant managers, procurement leads at ready-to-drink manufacturers, distribution channel partners, and aroma formulation specialists combined with secondary validation from FDA FSMA guidance documents, ANVISA food additive standards, and EFSA maximum residue limit determinations. Bottom-up volume modeling and top-down value reconciliation triangulated across these sources.
Data-stream reconciliation integrated production capacity surveys, import-export trade flows, and channel shipment patterns across the projection horizon. Segmentation dimensions modeled encompass product type, end user, packaging configuration, and distribution channel alongside processing technology tier. CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections, with specific inputs including green coffee bean price indices and energy cost curves for thermal processing.
Underlying measurement precision varies by segment; freeze-dried premium tiers carry tighter precision than spray-dried commodity volumes given concentrated producer base. Forecasts reflect assumptions regarding regulatory implementation timelines, technology adoption curves, and trade flow stability that stress-testing should periodically validate. Commodity price volatility and carbon border adjustment phase-in schedules represent specific risk factors that could materially revise projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Europe Coffee Pods and Capsules Market
Coffee
GCC Instant Coffee Market
Coffee
North America Specialty Coffee Market
Coffee
UK Coffee Roaster Market
Coffee
Take Out Coffee Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Coffee Concentrate Market
Coffee
Asia Pacific Coffee Market
Coffee
Mushroom Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
US Coffee Machine Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Coffee and Tea Capsule Market
Coffee
Global Coffee Market
Coffee
Thailand Coffee and Tea Capsules Market