
 Cake Cutting Machines Market | 2026-2036
Cake Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cake Cutting Machines Market Insights
EU F-Gas Regulation compliance pressure on refrigeration-integrated production lines is expanding demand for energy-efficient cake cutting equipment across European industrial bakeries. GORRERI leverages its Italian engineering heritage to dominate premium automated slicing systems for high-volume pastry operations. FoodTools sustains North American market presence through specialized ultrasonic cutting technology for delicate layered cakes. Mecasonic anchors its competitive position with advanced blade vibration systems that reduce product deformation in frozen dessert applications.
Cake cutting machines are electromechanical or hydraulically actuated devices engineered to portion baked goods with blade tolerances typically ranging from 0.5 to 2 millimeters, employing ultrasonic, wire, or rotary blade technologies to achieve clean cuts without structural compromise in layered or delicate products. The electric product type category leads installed base volumes due to operational consistency and lower total cost of ownership in continuous production environments. Smart technology integration represents the fastest-expanding segment as bakeries deploy IoT-enabled cutting stations with real-time portion monitoring and predictive maintenance algorithms. Traditional manual and semi-automated systems retain substantial share in small-scale retail bakeries where capital constraints limit automation deployment.
FDA food contact surface regulations and USDA facility sanitation standards shape equipment material specifications and clean-in-place design requirements for machines serving the North American market, while CE marking and EU Machinery Directive compliance govern European market access with specific provisions for operator safety interlocks and electromagnetic compatibility. BIS certification requirements in India and GB standards enforcement through SAMR in China create divergent compliance pathways that regionally focused manufacturers must navigate. Stakeholders should monitor evolving national energy efficiency labeling programs and carbon border adjustment mechanisms that will increasingly determine equipment qualification for public procurement and export eligibility.
Market Dynamics
EU F-Gas Regulation compliance deadlines are compressing replacement cycles for refrigeration-integrated production lines, forcing industrial bakeries to prioritize energy-efficient cake cutting equipment with lower refrigerant dependency.
Growth Catalysts
- EU Green Deal energy mandates:National sustainability frameworks in Germany, France, and Italy are mandating carbon footprint reductions that favor electric cutting systems over hydraulic alternatives in high-volume facilities.
- Commercial bakery automation:Labor cost pressures and portion consistency requirements are accelerating deployment of automated portioning systems across industrial baking clusters.
- Smart technology integration:IoT-enabled cutting stations with predictive maintenance algorithms are reducing unplanned downtime in continuous production environments.
Market Restraints
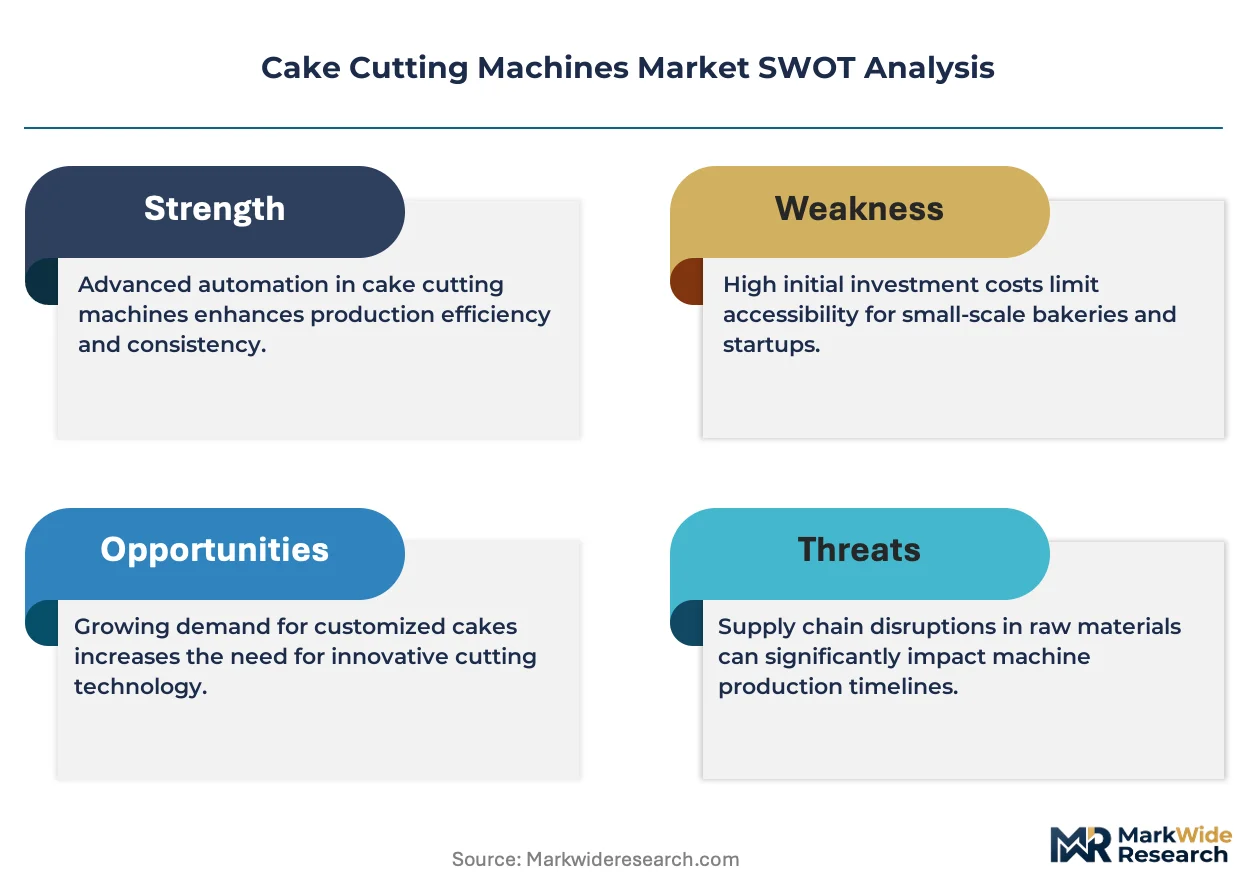
- Stainless steel input volatility:Food-grade 304 and 316 stainless steel price swings compress equipment margins and complicate long-term contract pricing for manufacturers.
- Technical blade wear limitations:Ultrasonic transducer degradation in high-duty cycles creates maintenance cost uncertainty that delays automation decisions at mid-scale bakeries.
- Regulatory fragmentation:Divergent BIS certification requirements in India versus GB standards enforcement through SAMR in China force redundant engineering and testing expenditures.
Strategic Opportunities
- Underpenetrated frozen dessert segment:Blade vibration systems for ice cream cakes and frozen pastries represent white space with limited specialized equipment suppliers.
- Energy efficiency labeling tailwinds:Emerging national carbon border adjustment mechanisms will qualify premium efficient designs for public procurement preferences.
- Convergence of ultrasonic and vision systems:Real-time product dimension scanning paired with adaptive blade positioning enables zero-waste portioning for irregular artisan products.
Industry Challenges
- Electromechanical technician scarcity:Specialized skills for servo motor calibration and ultrasonic generator maintenance are concentrated among aging workforces in mature manufacturing regions.
- Legacy system integration friction:Retrofitting IoT-enabled cutting stations into existing bakery management software requires custom middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cake Cutting Machines Market |
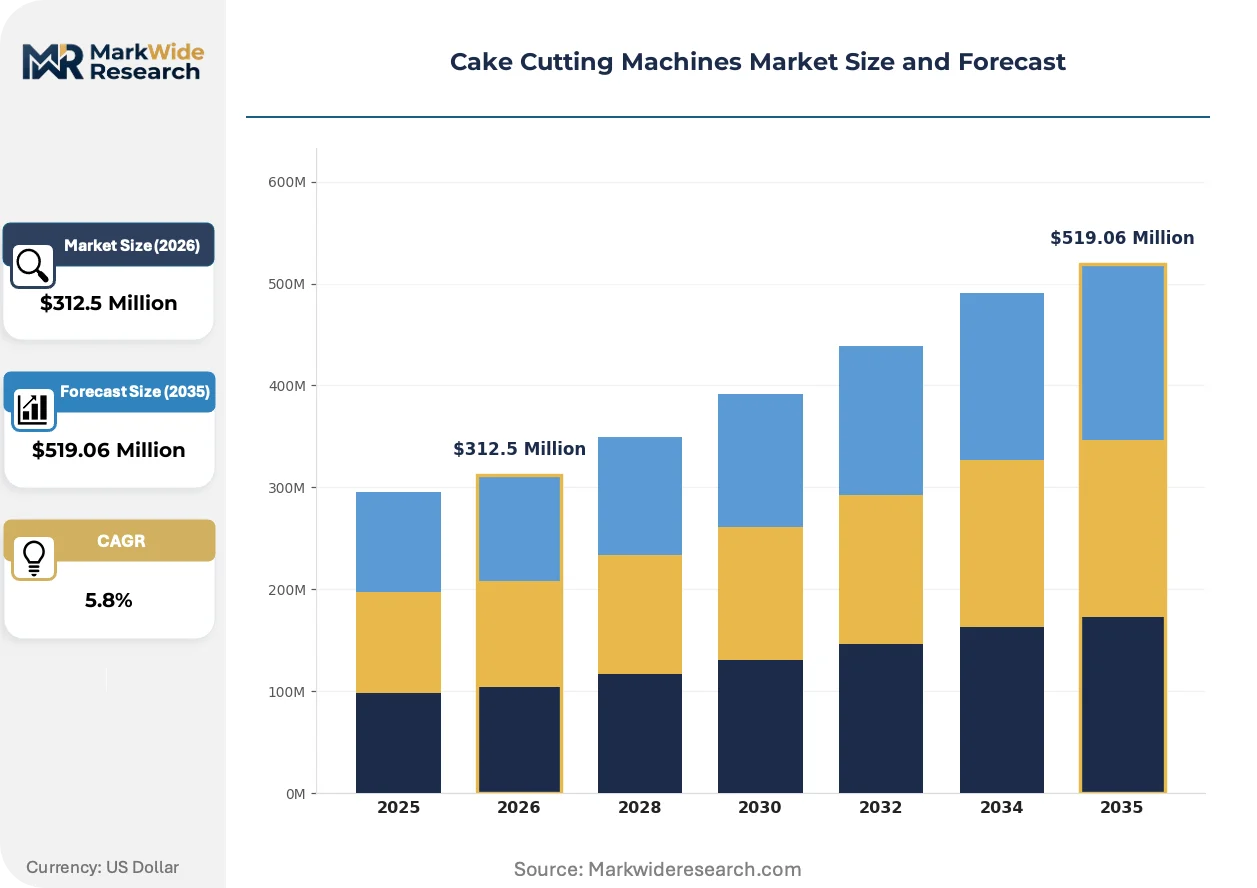
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Hydraulic, Pneumatic Application: Bakery, Restaurants, Catering, Events End User: Retail Bakeries, Food Service, Industrial Kitchens, Home Users Technology: Automated, Semi-Automated, Traditional, Smart |
| Companies Covered | GORRERI, FoodTools, Mecasonic, BFR Systems, NIKKO, Metronics Technologies, Bakon Food Equipment, Dardi International, Kleenline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cake Cutting Machines Market Trends and Innovations
Equipment architecture is fragmenting from monolithic systems toward configurable sub-assemblies that bakeries can resequence for product mix changes without full line replacement.
Ultrasonic cutting technology is modularizing across blade generator, transducer, and horn assemblies that facilities can swap independently based on product density and throughput requirements. Mid-scale commercial bakeries in Germany and Italy are adopting this architecture fastest, driven by SKU proliferation in private-label contract manufacturing. The shift is compressing capital deployment from full-line replacement toward targeted subsystem upgrades.
REACH chemical substance restrictions and EU Machinery Directive safety interlock mandates are reshaping material specifications for blade coatings and operator access panels. Manufacturers serving European industrial bakeries must now document full material substance inventories and electromagnetic compatibility certifications before CE marking approval. Frozen dessert applications face the tightest compliance timelines due to extended refrigerant system integration testing.
Bakeries are unbundling equipment purchase from aftermarket service contracts, preferring third-party maintenance providers or in-house technician certification programs. This procurement pattern is displacing traditional OEM service捆绑 agreements most visibly in North American multi-site bakery chains with centralized engineering capabilities. Equipment vendors are responding with modular spare parts pricing and remote diagnostic subscriptions rather than comprehensive service packages.
Cake Cutting Machines Market Segmentation
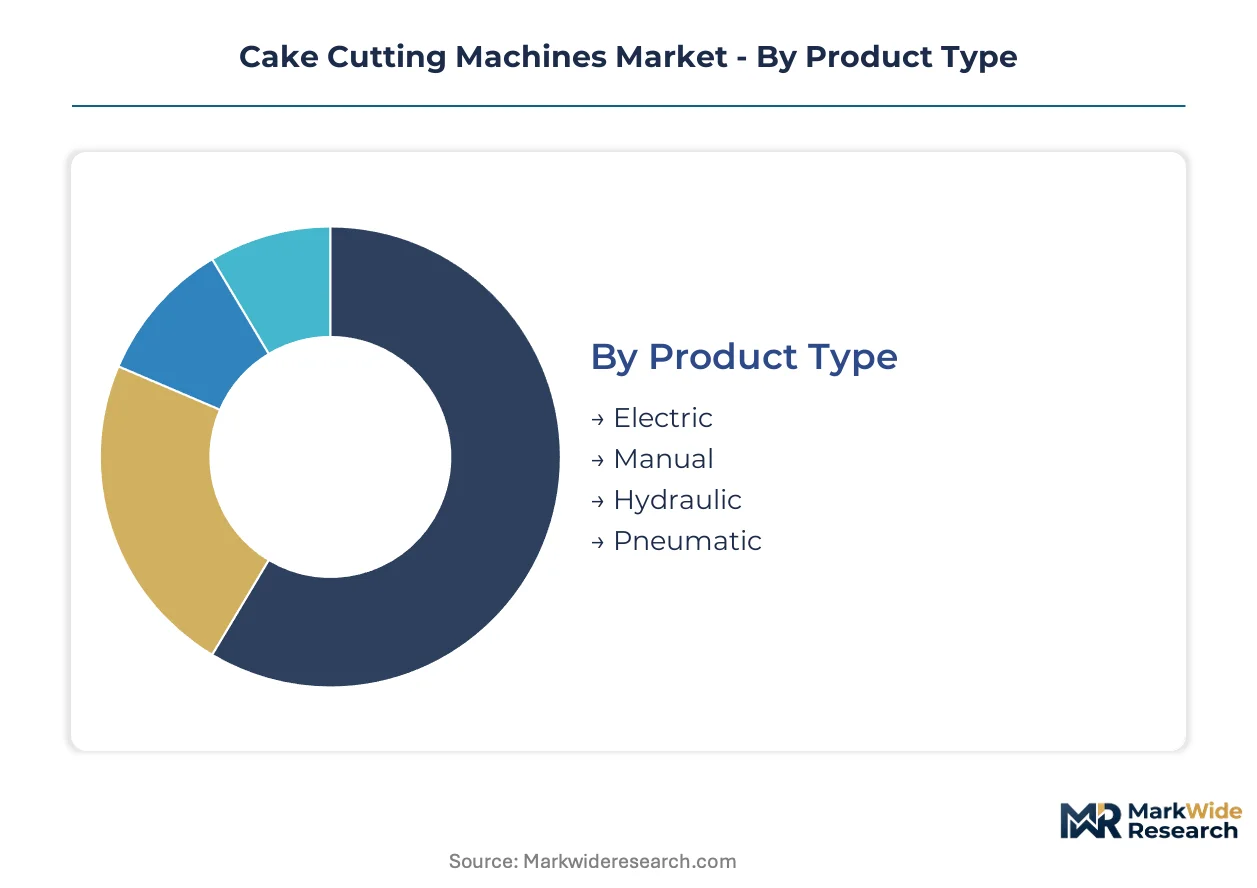
Cake cutting machine procurement diverges sharply across operational scales and technical sophistication requirements. Equipment specification matrices must reconcile throughput demands, labor availability, and compliance obligations that vary by facility type and geographic jurisdiction.
Product Type:
Actuation technology determines energy consumption profiles, maintenance cadences, and regulatory alignment trajectories across installation bases.
- Electric:Servo-driven blade systems deliver cutting force with positional repeatability within 0.5 millimeters. German industrial bakeries in Munich and Stuttgart prioritize electric configurations to satisfy EU Green Deal carbon reduction mandates and minimize refrigerant-dependent hydraulic infrastructure.
- Hydraulic:Fluid-power actuation generates higher cutting force for dense frozen products but carries refrigerant compliance burdens under EU F-Gas Regulation deadlines. French and Italian facilities are accelerating replacement cycles away from hydraulic systems toward electric alternatives.
- Manual:Hand-cranked or gravity-fed portioning devices dominate small-scale retail bakeries with capital constraints and lower throughput requirements.
- Pneumatic:Compressed-air systems occupy niche applications requiring rapid blade cycling in high-altitude production environments where electric motor efficiency degrades.
Electric configurations lead on scale across industrial installations; smart-integrated electric variants lead on momentum as IoT-enabled predictive maintenance expands.
Application:
End-use environment dictates sanitation protocols, portion size ranges, and equipment mobility requirements.
- Bakery:Fixed-installation cutting stations with clean-in-place designs serve high-volume production lines. German commercial bakery clusters drive precision equipment procurement for private-label contract manufacturing with strict portion consistency specifications.
- Restaurants:Compact countertop units with rapid blade changeover accommodate dessert menu rotation. Italian full-service restaurant chains are deploying semi-automated systems to reduce pastry chef labor hours.
- Catering:Mobile cutting equipment with battery power options supports off-site event production with limited utility access.
- Events:Rental-oriented machines with simplified operator interfaces address temporary demand spikes for wedding and corporate function dessert service.
Bakery applications command the largest installed base; catering applications are climbing the fastest as event-service automation lags manufacturing penetration.
End User:
Capital deployment capacity and technical staffing depth create distinct procurement patterns across buyer categories.
- Industrial Kitchens:Centralized food production facilities with dedicated maintenance technicians deploy fully automated cutting lines with SCADA integration. REACH chemical substance restrictions and EU Machinery Directive safety interlock mandates reshape material specifications for blade coatings in European installations.
- Retail Bakeries:Owner-operated shops with limited technical staff favor semi-automated wire-cutting systems that balance labor reduction against capital outlay. FDA food contact surface regulations and USDA facility sanitation standards govern equipment specifications for machines serving the North American market.
- Food Service:Contract catering and institutional feeding operations prioritize equipment durability and standardized portion weights for nutritional compliance reporting.
- Home Users:Consumer-grade electric slicers with safety interlocks and compact footprints address domestic baking enthusiasts and small-scale cottage food producers.
Industrial kitchens lead on scale; retail bakeries represent the steepest expansion trajectory as automation costs decline and labor availability tightens.
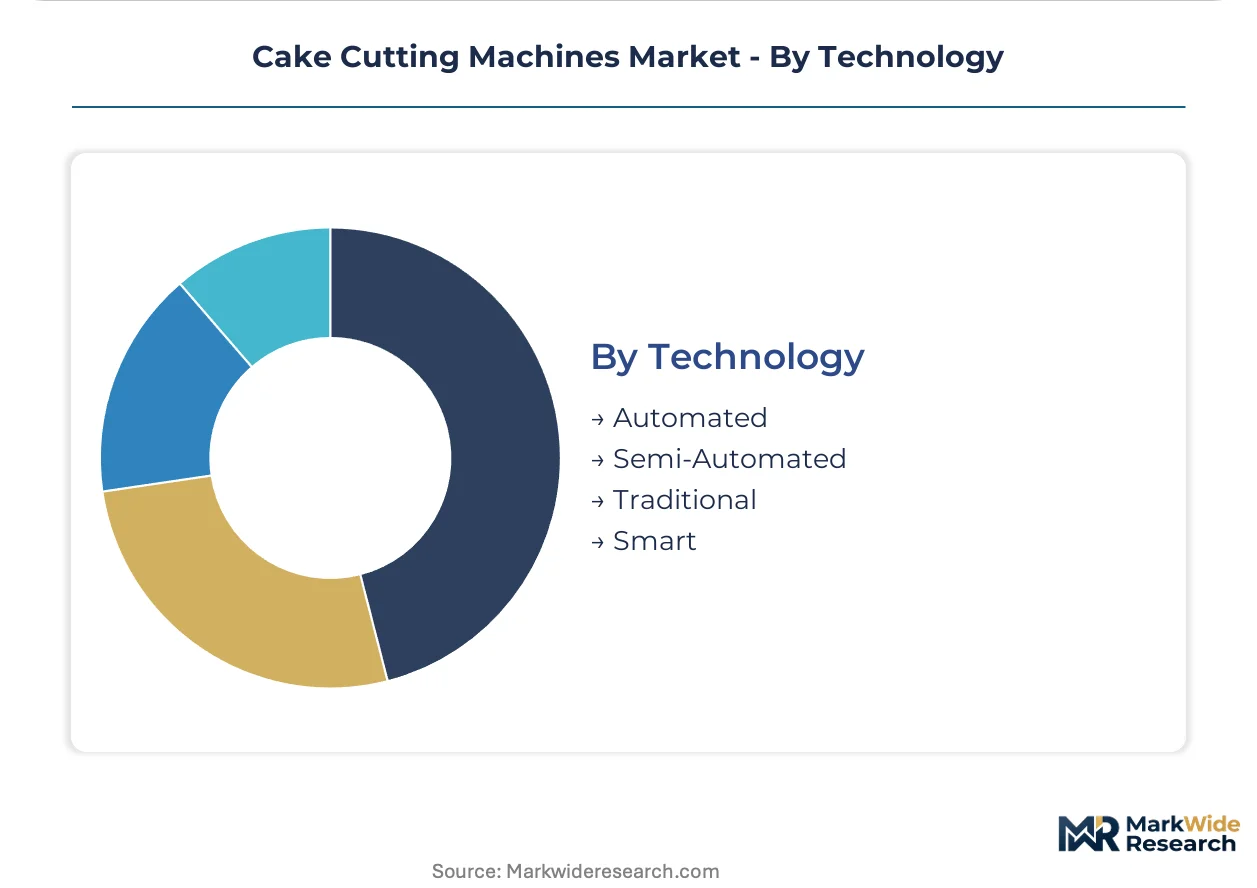
Technology:
Automation sophistication tiers correspond to data integration capabilities and operational decision-support functionality.
- Smart:IoT-enabled cutting stations incorporate real-time portion monitoring, predictive maintenance algorithms, and cloud-based performance analytics. CE marking and EU Machinery Directive compliance with electromagnetic compatibility certifications are mandatory for European market access.
- Automated:Programmable logic controller-driven systems execute cutting sequences without operator intervention but lack connectivity for remote diagnostics or production optimization.
- Semi-Automated:Operator-assisted machines with automated blade actuation but manual product positioning and removal occupy the mid-market price tier.
- Traditional:Fully manual cutting tools without powered components persist in artisan bakeries where product irregularity defies automated portioning and capital constraints limit equipment investment.
Automated systems lead on scale; smart technology configurations are gaining share fastest as bakeries unbundle equipment purchase from aftermarket service contracts in favor of remote diagnostic subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial baking heritage traces to nineteenth-century mechanical engineering clusters that standardized food processing equipment. Italian precision manufacturing traditions and Japanese automation expertise subsequently shaped cutting technology evolution. Contemporary demand concentrates in manufacturing regions with strong downstream bakery infrastructure and regulatory pressure for energy-efficient production.
Germany
Industrial bakery clusters in Munich and Stuttgart drive precision equipment procurement for private-label contract manufacturing. EU Green Deal carbon reduction mandates and F-Gas Regulation compliance deadlines accelerate replacement of hydraulic systems with electric alternatives. Baden-Württemberg engineering networks supply servo motor calibration expertise that underpins smart cutting station deployment.
Italy
Full-service restaurant chains deploy semi-automated systems to reduce pastry chef labor hours amid tightening hospitality staffing. REACH chemical substance restrictions reshape blade coating material specifications for CE marking approval. Emilia-Romagna's packaging machinery corridor generates technology spillover into modular cutting sub-assemblies for SKU-flexible production.
United States
Multi-site bakery chains with centralized engineering capabilities unbundle equipment purchase from traditional OEM service agreements. FDA food contact surface regulations and USDA facility sanitation standards govern stainless steel specifications and clean-in-place design requirements. Midwest industrial baking concentrations in Illinois and Ohio retrofit IoT-enabled stations into legacy production management software.
China
Domestic frozen dessert manufacturers import blade vibration systems for ice cream cake applications with limited local specialized suppliers. GB standards enforcement through SAMR and dual carbon goals create divergent compliance pathways from Western certification regimes. Yangtze River Delta baking equipment distributors build regional service networks for mid-scale commercial bakery automation.
India
Retail bakeries in Maharashtra and Gujarat balance labor reduction against capital constraints through semi-automated wire-cutting systems. BIS certification requirements for electrical safety and food contact materials extend equipment qualification timelines versus CE-marked alternatives. Karnataka's food technology institutes develop in-house technician certification programs that displace OEM service捆绑 agreements.
Cake Cutting Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a moderately consolidated vendor base where European engineering heritage confers durability premiums. Italian and German fabricators dominate premium automated slicing systems through precision manufacturing ecosystems. Three archetypes populate the competitive map: heritage engineering houses with multi-decade baking industry relationships, ultrasonic technology specialists leveraging vibration physics expertise, and Asian-scale manufacturers competing on subsystem cost. Consolidation proceeds through regional distributor acquisition and technology licensing partnerships rather than horizontal merger waves.
Within the heritage engineering tier, GORRERI S.r.l. represents Italian electromechanical integration capabilities, while FoodTools Inc. anchors North American presence through specialized cutting technology positioning. Mecasonic S.A.S. exemplifies French vibration systems expertise for frozen dessert applications. These three occupy positions that downstream buyers associate with specific product density and throughput requirements, though actual procurement decisions increasingly hinge on modular spare parts availability and remote diagnostic subscription quality rather than brand heritage alone.
| Leading Market Players |
|---|
| GORRERI |
| FoodTools |
| Mecasonic |
| BFR Systems |
| NIKKO |
| Metronics Technologies |
| Bakon Food Equipment |
| Dardi International |
| Kleenline |
| Others |
Pricing and Supply Chain Analysis
Backward integration into servo motor and ultrasonic transducer production anchors pricing power for heritage European manufacturers while compressing margins for subsystem-dependent competitors. German and Italian fabricators with captive supply of precision electromechanical components command premium positioning against Asian-scale manufacturers sourcing from distributed component markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked smart-integrated systems from basic automated configurations and manual equipment. Price differentiation rests on certification grade and after-sales service bundling, with EU Machinery Directive compliance and remote diagnostic subscriptions commanding substantial premiums. Cost compression in the standard tier is intensifying because stainless steel input volatility compresses equipment margins. Retail bakeries exhibit highest price sensitivity due to capital constraints, while industrial kitchens with centralized engineering capabilities prioritize total cost of ownership over upfront expenditure.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian precision engineering clusters for high-tolerance servo drives and ultrasonic generator assemblies. Component sourcing draws from China for food-grade stainless steel raw stock, Germany for precision electromechanical systems, and Japan for industrial automation controllers. Supply chain risk centers on tariff exposure for steel inputs and regulatory restriction divergence between CE marking and BIS certification pathways. Distribution runs through specialized bakery equipment distributors with regional service capabilities, though multi-site chains increasingly procure direct from manufacturers with in-house technician certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in smart-technology tier migration and aftermarket service unbundling, with predictive maintenance subscriptions offering recurring revenue streams that offset equipment margin compression.
For Market Incumbents: Anticipate ultrasonic-wire convergence technologies by deepening R&D investment in adaptive blade positioning systems that pair vibration physics with real-time vision scanning. Defend against modular subsystem competitors by expanding captive spare parts distribution networks and remote diagnostic subscription penetration across installed bases. CE marking and EU F-Gas Regulation compliance investment represents the critical certification lever for European market retention. For New Entrants and Emerging Players: Vision-guided adaptive cutting systems for irregular artisan products offer technology-first wedge opportunity with limited incumbent specialization. Frozen dessert blade vibration applications in China and India represent the most penetrable white space, with domestic manufacturers lacking specialized equipment for ice cream cake portioning. Go-to-market execution should prioritize regional distributor partnerships with established bakery equipment service networks over direct sales investment. For Investors and Strategic Acquirers: Roll-up economics work for regional precision engineering specialists because customer relationships in industrial baking clusters exhibit high switching costs and multi-decade equipment replacement cycles. Target acquisition archetypes include Italian electromechanical integrators with established CE marking documentation and German servo motor calibration expertise. The signal to watch is carbon border adjustment mechanism implementation timing, which will accelerate premium-efficient equipment qualification for public procurement preferences.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Technology Integration | IoT-enabled predictive maintenance subscriptions displace traditional OEM service捆绑 agreements in North American multi-site chains. |
| Modular Subsystem Architecture | Independent blade generator and transducer swap capability compresses capital deployment from full-line replacement toward targeted upgrades. |
| Energy Efficiency Certification | EU Green Deal compliance positioning qualifies premium electric configurations for carbon-conscious procurement in German industrial clusters. |
| Regional Distributor Acquisition | Control over service networks in Yangtze River Delta and Maharashtra-Gujarat corridors secures aftermarket revenue streams. |
| Ultrasonic-Wire Convergence R&D | Adaptive blade technology for irregular artisan products opens zero-waste portioning applications beyond standardized industrial production. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at commercial bakeries, procurement leads at multi-site bakery chains, aftermarket service heads at equipment distributors, and technical R&D directors at ultrasonic component suppliers with secondary validation against SEC filings, EU Machinery Directive certification databases, customs trade records for stainless steel equipment imports, and industrial automation capex disclosures. Bottom-up installed base enumeration and top-down production capacity estimation were cross-referenced for triangulation.
Historical reference periods anchored the forecast window through backward projection of equipment replacement cycles and forward modeling of automation penetration rates across facility scale tiers. Segmentation dimensions modeled include actuation technology, automation sophistication tier, end-use environment, and geographic regulatory cluster. CAGRs were derived from curve-fitting across disclosed equipment shipments and facility expansion announcements. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance deadline acceleration and labor availability indices for electromechanical technician specialization.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment mechanism implementation schedules and stainless steel commodity price trajectories. Forecasts reflect documented assumptions regarding replacement cycle compression and smart technology adoption elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Double Stack Oven Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Dispensing Systems and Equipment Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Fish Deboning Machine Market