
 APAC Ready-To-Drink Coffee Market | 2026-2036
APAC Ready-To-Drink Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Ready-To-Drink Coffee Market Insights
Convenience store cold-chain infrastructure is reshaping how RTD coffee reaches consumers across Southeast Asian corridors. Nestle S.A. leverages its Nescafé manufacturing footprint to dominate shelf-stable formats in Indonesian and Thai convenience networks. The Coca-Cola Company anchors its position through Costa Coffee ready-to-drink lines distributed via Coca-Cola's chilled direct-store-delivery system. Suntory Holdings Limited specializes in premium black coffee variants that occupy refrigerated sections in Japanese and Taiwanese convenience outlets.
APAC ready-to-drink coffee comprises brewed, extracted, or reconstituted coffee beverages packaged in shelf-stable or refrigerated formats with typical caffeine concentrations ranging from 80 to 200 milligrams per serving, designed for immediate consumption without additional preparation. Canned formats lead volume across price-sensitive Southeast Asian markets where ambient distribution dominates logistics economics. Bottled variants capture margin pools in premium urban channels across Japan and South Korea where glass and PET aesthetics signal quality differentiation. E-commerce channels represent the fastest-growing distribution vector as chilled last-mile delivery networks expand across Chinese tier-one cities and Indian metropolitan zones.
Japan's Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards that govern caffeine labeling and additive permissions for imported RTD coffee products. Australia's container deposit legislation and China's GB standards for pre-packaged beverages shape packaging material choices and cross-border compliance costs for regional suppliers. India's FSSAI registration requirements and China's SAMR labeling rules add friction for new entrants seeking multi-country distribution. Stakeholders must monitor evolving extended producer responsibility frameworks and sugar taxation proposals across multiple Asia-Pacific jurisdictions to anticipate reformulation mandates and channel cost shifts.
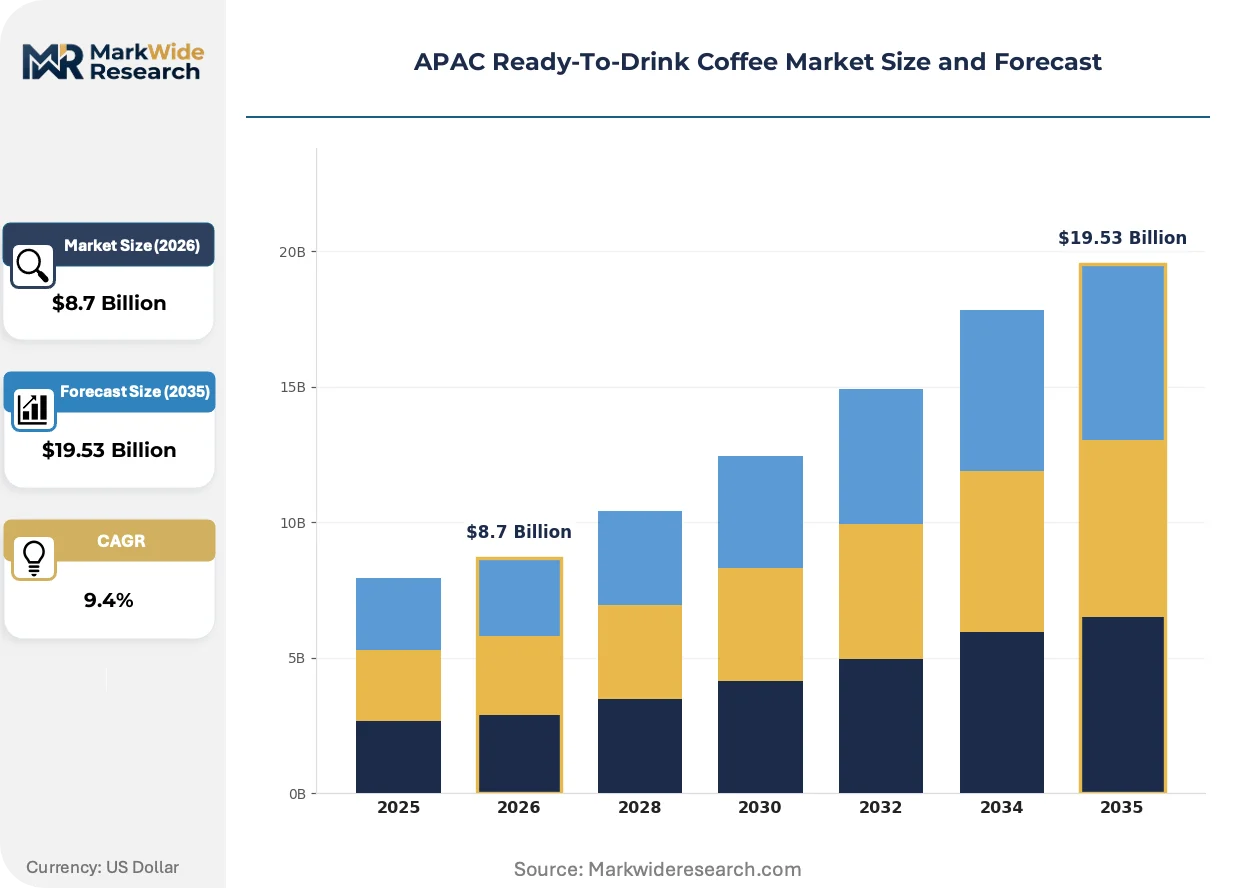
Market Dynamics
Cold-chain infrastructure expansion across Chinese tier-one cities and Southeast Asian urban corridors is compressing distribution timelines and enabling refrigerated SKU proliferation that shelf-stable formats cannot match.
Growth Catalysts
- Container deposit schemes:Australia's state-level container deposit legislation incentivizes PET and aluminum packaging investments by domestic bottlers seeking compliance credits.
- White-collar consumption clusters:Shanghai and Shenzhen office districts generate concentrated demand for premium black coffee variants during morning commute windows.
- GB standards alignment:China's national pre-packaged beverage standards streamline cross-provincial distribution by reducing label variation requirements for registered products.
Market Restraints
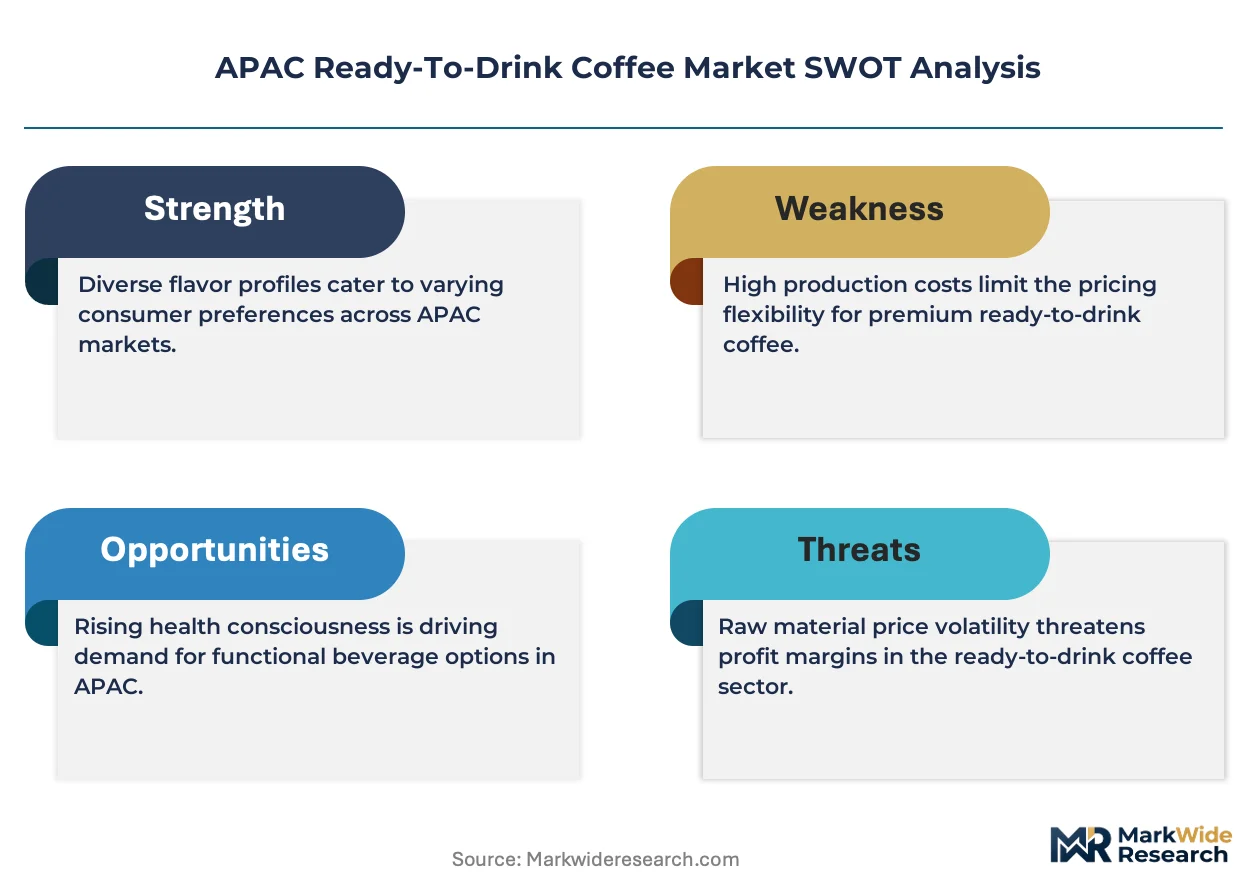
- Robusta arabica price volatility:Green coffee input costs swing with Brazilian and Vietnamese harvest cycles, compressing margin predictability for mid-tier producers.
- Refrigerated logistics concentration:Cold-chain capacity clusters in Japan, South Korea, and eastern China, leaving Southeast Asian markets dependent on costly ambient-stable formulations.
- FSSAI registration friction:India's food safety authority mandates multi-month approval timelines for imported RTD coffee SKUs, delaying market entry for new suppliers.
Strategic Opportunities
- Indian metropolitan zones:Mumbai, Bangalore, and Delhi display underpenetrated chilled coffee availability relative to tea-dominated beverage consumption.
- E-commerce chilled last-mile:Dedicated cold-box delivery networks in Chinese tier-two cities enable direct-to-consumer subscription models bypassing traditional retail.
- Extended producer responsibility frameworks:Japan's evolving packaging waste policies create first-mover advantages for aluminum can recyclers and refillable bottle systems.
Industry Challenges
- Reformulation chemistry expertise:Sugar taxation proposals across Thailand, Philippines, and Australia demand accelerated low-glycemic sweetener integration that outpaces available food technologist supply.
- SAMR label compliance timelines:China's State Administration for Market Regulation requires nutritional panel updates that delay seasonal SKU launches by 8-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Ready-To-Drink Coffee Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Bottled, Bag-in-Box, Powder Flavor Profile: Sweetened, Unsweetened, Mocha, Vanilla Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Specialty Stores End User: Office Workers, Students, Athletes, Casual Consumers |
| Companies Covered | Nestle S.A., The Coca-Cola Company, Suntory Holdings Limited, Kirin Holdings Company, Limited, UCC Holdings Co., Ltd., Lotte Chilsung Beverage Co., Ltd., Asahi Group Holdings, Ltd., Starbucks Coffee Company, Tan Do Beverage, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Ready-To-Drink Coffee Market Trends and Innovations
Aseptic cold-brew extraction methods and nitrogen-infusion technologies are displacing traditional hot-brew processes in premium positioning. Regulatory pressure on sugar content and packaging circularity is forcing simultaneous reformulation and material transitions across the region.
High-pressure cold-brew extraction systems operate at ambient temperature, preserving volatile aromatic compounds that degrade under thermal processing. Japanese and Taiwanese convenience retailers are adopting these systems for private-label offerings. Hot-brew concentration followed by thermal stabilization is rendering obsolete for single-origin premium lines where flavor differentiation commands price premiums.
Japan's Food Sanitation Act amendments tightened caffeine disclosure thresholds and additive approval lists for imported RTD coffee products. Domestic manufacturers face reformulation costs for existing SKUs while import volumes shift toward compliant suppliers with pre-cleared formulations. Australian container deposit schemes and China's dual carbon goals are accelerating aluminum can and rPET adoption, compressing glass bottle share in premium channels.
Subscription-based replenishment models are displacing impulse convenience store purchases among urban professionals in Seoul, Tokyo, and Singapore. Chilled direct-to-office delivery services capture recurring revenue streams that traditional retail cannot replicate. This behavioral pivot concentrates most visibly in South Korean corporate districts where employer-subsidized beverage programs aggregate individual demand into bulk procurement contracts.
APAC Ready-To-Drink Coffee Market Segmentation
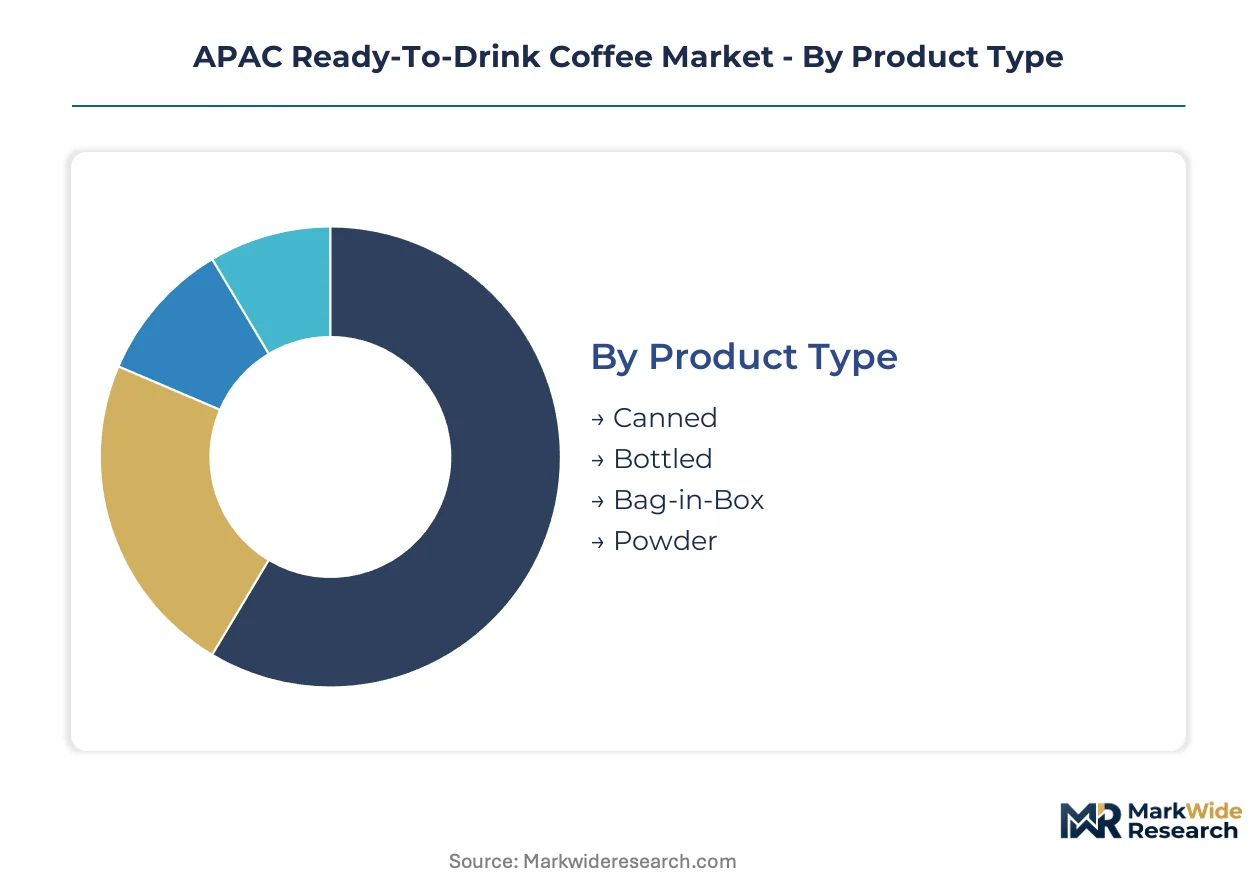
APAC ready-to-drink coffee segmentation reflects divergent consumption rituals across convenience retail, premium channels, and digital replenishment. Product format and distribution channel combinations determine margin architecture, while flavor profile and end-user targeting shape brand positioning in Japan's vending machine corridors versus China's subscription-driven tier-one cities.
Product Type:
Metal and glass packaging formats span ambient-stable logistics and chilled premium positioning across Japanese convenience networks and Indonesian supermarket aisles.
- Canned:Aluminum cylindrical containers dominate ambient distribution economics across Southeast Asian markets where refrigeration infrastructure remains sparse. Vietnamese and Thai consumers favor 180-240ml formats for immediate consumption during tropical commutes, with local bottlers optimizing line speeds for high-volume output.
- Bottled:PET and glass configurations capture margin pools in South Korean and Japanese refrigerated sections where visual aesthetics signal quality differentiation. Shanghai office workers select 400-500ml bottles for desk-side consumption, driving premium pricing tiers unavailable to canned equivalents.
- Bag-in-Box:Multi-liter flexible packaging serves institutional catering and workplace coffee stations across Australian corporate campuses. The format reduces per-serving packaging costs but requires dedicated dispensing equipment limiting household penetration.
- Powder:Soluble coffee concentrates enable consumer-controlled dilution in Indian and Philippine markets where price sensitivity intersects with inconsistent cold-chain access. Sachet packaging dominates rural distribution through traditional trade channels.
Established volume favors canned formats across ambient-distributed Southeast Asian corridors; emerging adoption favors bottled variants in Chinese and South Korean chilled retail expansion.
Flavor Profile:
Palate preferences stratify between sugar-forward formulations for mass-market penetration and clean-label positioning for health-conscious urban professionals.
- Sweetened:Sucrose and high-fructose corn syrup formulations dominate Indonesian and Philippine convenience store velocity, with local taste panels calibrating sweetness intensity above Western equivalents. Sugar taxation proposals across Thailand and Australia are forcing accelerated reformulation timelines.
- Unsweetened:Zero-additive black coffee concentrates attract Seoul and Tokyo white-collar segments seeking caffeine without glycemic load. Japanese Ministry of Health, Labour and Welfare labeling requirements mandate precise caffeine disclosure for these variants.
- Mocha:Chocolate-coffee hybrid formulations target younger demographics in Singapore and Malaysian campuses, with cocoa powder sourcing costs adding formulation complexity.
- Vanilla:Flavoring extracts occupy mid-tier positioning in Taiwanese and Hong Kong convenience channels, competing with local bubble tea alternatives for discretionary beverage spend.
Sweetened variants retain volume leadership in Southeast Asian price-sensitive markets; unsweetened alternatives gain share fastest in Japanese and South Korean health-positioned retail.
Distribution Channel:
Route-to-consumer architecture determines temperature requirements, promotional mechanics, and margin capture across ambient and chilled supply chains.
- Supermarkets:Multi-format shelf sets in Australian Woolworths and Coles, Japanese AEON, and Chinese Hema stores combine ambient center-store displays with refrigerated perimeter positioning. Category managers negotiate slotting fees that favor established suppliers with SKU breadth.
- Convenience Stores:7-Eleven, Lawson, and FamilyMart networks across Japan, Taiwan, and Thailand operate as primary impulse purchase venues. Chilled single-serve placement near checkout counters drives unplanned consumption during morning commute windows.
- E-commerce:Tmall, JD.com, and Coupang platforms enable subscription replenishment and chilled last-mile delivery in Chinese and South Korean metropolitan zones. Direct-to-consumer models bypass traditional retail margin stacking but require cold-box logistics investment.
- Specialty Stores:Coffee-focused retail in Melbourne, Sydney, and Tokyo offers curated RTD selections alongside equipment and bean sales, targeting enthusiasts seeking single-origin or small-batch formulations unavailable in mass channels.
Convenience stores anchor volume in established Japanese and Southeast Asian markets; e-commerce channels climb the fastest in Chinese tier-one and tier-two city expansion.
End User:
Occupational and lifestyle segmentation shapes consumption occasion, format preference, and price elasticity across APAC metropolitan corridors.
- Office Workers:White-collar professionals in Shanghai, Shenzhen, and Bangalore corporate districts drive premium black coffee demand during pre-work and mid-afternoon consumption windows. Employer-subsidized beverage programs in South Korea aggregate individual demand into bulk procurement contracts.
- Students:University campuses across Manila, Jakarta, and Ho Chi Minh City generate price-sensitive volume for sweetened canned formats, with vending machine placement near library and dormitory facilities capturing between-class consumption.
- Athletes:Protein-fortified and electrolyte-enhanced RTD coffee targets gym-goers and amateur sports participants in Australian and Japanese fitness culture markets, competing with dedicated sports nutrition brands.
- Casual Consumers:Occasional drinkers without fixed consumption rituals respond to promotional pricing and seasonal limited editions, displaying low brand loyalty and high channel-switching behavior.
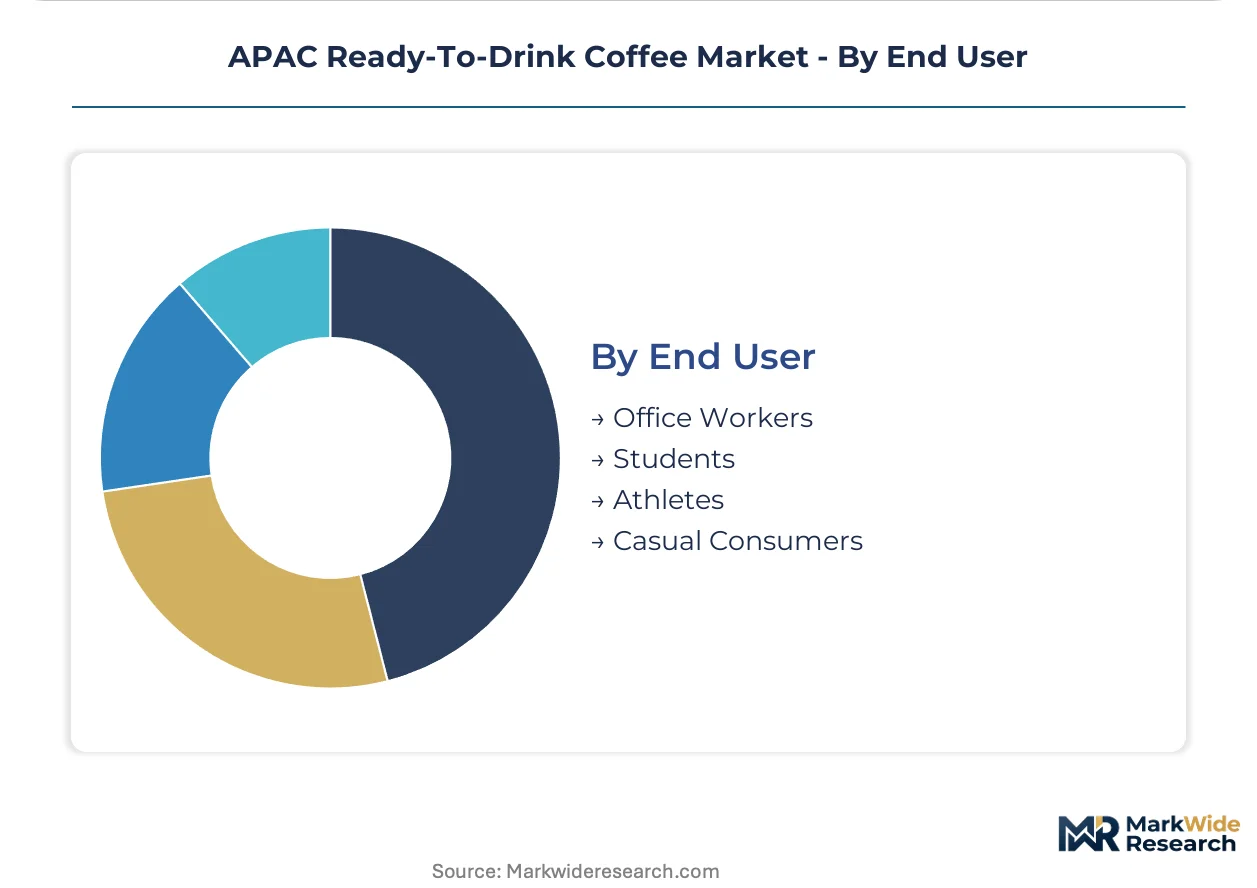
Office workers concentrate revenue in premium chilled segments; students sustain volume in ambient-distributed economy tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium bottled variants in Japanese convenience networks command price multiples that canned ambient formats in Indonesian corridors cannot approach. This pricing-power asymmetry reflects cold-chain density disparities and white-collar consumption clustering rather than input cost differentials.
China
Shanghai and Shenzhen office districts concentrate chilled black coffee demand during compressed morning commute windows. SAMR labeling rules for pre-packaged beverages enforce nutritional panel standards that delay seasonal SKU launches by 8-12 weeks. Yangtze River Delta logistics hubs enable same-day chilled delivery to tier-one metropolitan zones.
Japan
Tokyo's vending machine corridors and convenience store networks sustain the world's highest per-capita RTD coffee consumption. The Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards governing caffeine disclosure thresholds and additive permissions for domestic and imported products. Kanto region manufacturing clusters specialize in nitrogen-infusion and cold-brew extraction systems.
South Korea
Seoul Capital Area corporate districts drive employer-subsidized beverage program adoption that aggregates individual demand into bulk procurement contracts. MFDS registration requirements shape import compliance timelines for new market entrants. Busan-Ulsan logistics corridors support refrigerated distribution to secondary metropolitan zones.
Australia
Melbourne and Sydney specialty coffee cultures sustain premium RTD segments alongside traditional café consumption. State-level container deposit legislation incentivizes aluminum and rPET packaging investments by domestic bottlers seeking compliance credits. New South Wales and Victoria retail networks combine supermarket shelf sets with chilled convenience store placement.
India
Mumbai, Bangalore, and Delhi metropolitan zones display underpenetrated chilled coffee availability relative to tea-dominated beverage consumption patterns. FSSAI registration mandates multi-month approval timelines for imported RTD coffee SKUs, delaying market entry for new suppliers. Maharashtra and Karnataka industrial corridors host emerging contract manufacturing capacity for ambient-stable formulations.
APAC Ready-To-Drink Coffee Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where extraction technology and flavor formulation determine margin capture. The market structure concentrates around diversified beverage conglomerates with chilled distribution infrastructure and multinational food manufacturers leveraging existing coffee brand equity. Two strategic archetypes dominate: vertically integrated conglomerates with captive cold-chain networks, and specialist coffee houses licensing brand equity to manufacturing partners. Competitive moves center on refrigerated logistics expansion and aseptic cold-brew capacity addition.
Within the conglomerate tier, Nestle S.A. and The Coca-Cola Company exemplify divergent approaches to RTD coffee penetration. Nestle S.A. leverages its Nescafé manufacturing footprint across Indonesian and Thai convenience networks, anchoring shelf-stable format dominance. The Coca-Cola Company occupies a parallel position through Costa Coffee ready-to-drink lines distributed via its chilled direct-store-delivery system. Suntory Holdings Limited represents the premium specialist archetype, with black coffee variants positioned in refrigerated sections of Japanese and Taiwanese convenience outlets.
| Leading Market Players |
|---|
| Nestle S.A. |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Kirin Holdings Company, Limited |
| UCC Holdings Co., Ltd. |
| Lotte Chilsung Beverage Co., Ltd. |
| Asahi Group Holdings, Ltd. |
| Starbucks Coffee Company |
| Tan Do Beverage |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta manufacturing clusters anchor ambient-stable production capacity that shapes margin architecture across Southeast Asian price-sensitive corridors. Cold-chain density in Shanghai and Shenzhen enables premium bottled positioning that Vietnamese and Thai ambient markets cannot replicate, compressing pricing power into logistics-enabled geographies.
Pricing Analysis
Configured-to-order pricing for private-label extraction systems spreads 40-60% above standard off-the-shelf formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold-chain access: nitrogen-infused cold-brew commands shelf-space premiums in Japanese convenience networks, while commodity canned variants compete on unit economics in Indonesian traditional trade. Pricing pressure stems from Robusta arabica input volatility and sugar taxation proposals across Thailand and Australia. Students in Manila and Jakarta display highest price sensitivity; Seoul office workers in employer-subsidized programs show lowest.
Supply Chain Analysis
Export-control regimes on aseptic processing equipment limit technology transfer to Vietnamese and Indonesian bottlers seeking cold-brew capability. Green coffee sourcing concentrates in Brazil and Vietnam; aluminum can sheet draws from Chinese and South Korean smelters; nitrogen-infusion systems rest on Japanese and Taiwanese engineering. Single-source vulnerability sits with Brazilian harvest cycles and Vietnamese Robusta concentration. Distribution runs through Coca-Cola's chilled direct-store-delivery in developed markets and Nestlé's ambient distributor networks in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC ready-to-drink coffee sits in cyclical recovery as post-pandemic office attendance rebounds in Shanghai, Seoul, and Tokyo corporate districts, reconstituting pre-work consumption rituals that subscription and impulse channels depend upon.
For Market Incumbents: Entrench cold-chain infrastructure in Chinese tier-two cities before regional competitors replicate Yangtze River Delta logistics density. Expand aseptic cold-brew capacity in Kanto manufacturing clusters to capture flavor-premium positioning that hot-brew concentration cannot match. Defend against Suntory-style premium specialists by locking exclusive refrigerated placement in Lawson and FamilyMart networks. For New Entrants and Emerging Players: Mumbai, Bangalore, and Delhi chilled coffee availability gaps represent the most penetrable entry point, with FSSAI registration friction deterring multinational speed-to-market. Target employer-subsidized beverage programs in South Korean corporate districts where bulk procurement contracts aggregate fragmented individual demand. Pursue direct-to-office delivery partnerships bypassing traditional retail slotting fee barriers. For Investors and Strategic Acquirers: Long-term, this sits as a logistics-arbitrage play because cold-chain infrastructure ownership determines margin capture more than brand equity in emerging metropolitan zones. Acquisition targets with captive chilled distribution in Chinese tier-two cities or nitrogen-infusion IP in Japanese manufacturing clusters command structural premiums. Watch Indian FSSAI approval timeline compression as signal that regulatory friction is easing for import-heavy entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Chilled Last-Mile Network Expansion | Enables subscription models in Chinese tier-two cities bypassing traditional retail margin stacking. |
| Aseptic Cold-Brew Capacity Addition | Preserves volatile aromatics that Japanese Ministry of Health labeling requirements now favor for premium positioning. |
| Aluminum Can Recyclability Investment | Captures Australia's container deposit scheme compliance credits while aligning with China's dual carbon goals. |
| Private-Label Extraction Technology Licensing | Monetizes Japanese nitrogen-infusion IP in Taiwanese and South Korean convenience retail expansion. |
| Sugar Reformulation R&D Partnership | Accelerates low-glycemic sweetener integration ahead of Thailand and Philippines taxation implementation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, Nielsen retail audit data, and GB standards documentation. Interviews with category buyers at 7-Eleven and Lawson networks, supply planners at Nestlé and Coca-Cola chilled distribution operations, and regulatory affairs leads navigating SAMR and FSSAI registration informed demand and compliance dynamics. Bottom-up SKU-level volume builds triangulate against top-down category expenditure estimates from national beverage associations.
Forecast inputs incorporate product format segmentation across canned, bottled, and powder configurations; flavor profile stratification between sweetened and unsweetened variants; distribution channel splits across convenience, supermarket, and e-commerce; and end-user targeting of office workers versus students. CAGRs derive from logistic curve adoption modeling applied to cold-chain infrastructure penetration rates and white-collar employment clustering in tier-one metropolitan zones. Coffee commodity price cycles and sugar taxation proposal timelines feed as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in Chinese urban disposable income growth or Brazilian Real exchange rates would shift the trajectory. Forecasts reflect stated assumptions about cold-chain capex continuation and regulatory approval timeline stability. Material shifts in India's FSSAI enforcement posture or Australia's container deposit scheme expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Coffee Roaster Machine Market
Coffee
RTD Coffee Market
Coffee
Raw Coffee Beans Market
Coffee
Coffee Bags Market
Coffee
Coffee and Tea Capsule Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Caffeine Market
Coffee
Middle East Coffee Market
Coffee
Coffee Grinder Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Freeze Dried Coffee Market
Coffee
High Protein Coffee Market
Coffee
Coffee Fruit Extract Market
Coffee
Espresso Coffee Market