
 United States Ready-To-Drink (RTD) Coffee Market | 2026-2036
United States Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ready-To-Drink (RTD) Coffee Market Analytics
California's SB 54 extended producer responsibility mandate is consolidating packaging accountability across beverage supply chains. Starbucks Corp. leverages its captive roasting infrastructure to control ingredient quality from bean to shelf. PepsiCo Inc. anchors distribution through convenience store partnerships that dominate impulse purchase locations. Nestlé S.A. competes via Nescafé's manufacturing scale in Solon, Ohio, where it operates one of North America's largest RTD coffee production facilities.
Ready-to-drink coffee comprises brewed coffee extract, water, and optional dairy or plant-based milk formulations, packaged in shelf-stable formats with thermal processing or aseptic filling to ensure microbiological safety. Its primary commercial purpose is delivering caffeinated refreshment without equipment dependency for time-constrained consumers. Bottled formats lead volume due to premium positioning and resealability, while canned variants sustain growth through lower unit economics and sports-adjacent marketing. Online retail channels represent the fastest-expanding distribution pathway as subscription models and direct-to-consumer platforms capture repeat purchase loyalty.
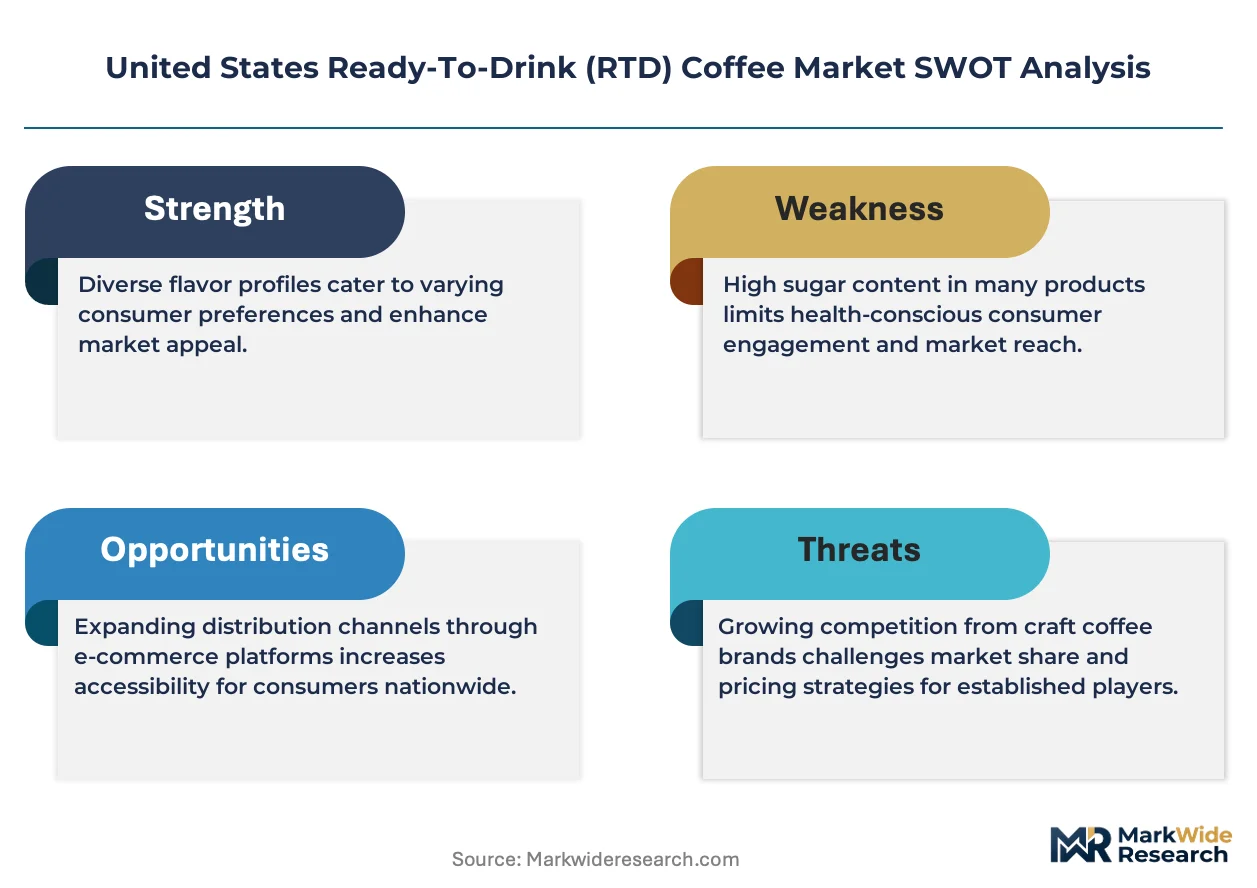
The FDA governs caffeine content disclosure and GRAS status for novel ingredients, while USDA organic certification shapes premium tier access and pricing power. State-level bottle deposit laws in California, Oregon, and New York impose compliance costs that favor larger producers with dedicated sustainability departments. Stakeholders must monitor evolving sugar taxation proposals in municipal jurisdictions and assess whether clean-label reformulation investments align with shifting consumer ingredient scrutiny.
Market Dynamics
California's SB 54 extended producer responsibility mandate is forcing beverage manufacturers to internalize end-of-life packaging costs, consolidating supply chain accountability from raw material sourcing through retail distribution across the United States RTD coffee sector.
Growth Catalysts
- Urban Commuter Patterns:On-the-go consumption among time-constrained professionals in dense metropolitan corridors is expanding addressable demand for shelf-stable caffeinated beverages.
- USDA Organic Certification:Premium tier access and pricing power for certified products is pulling investment toward clean-label ingredient sourcing and processing transparency.
- Cold Brew Penetration:Smoother taste profiles and higher caffeine concentration in California and the Northeast corridor are accelerating format adoption beyond traditional hot-brew extracts.
Market Restraints
- Arabica Price Volatility:Input cost instability for high-quality coffee beans compresses margin predictability for mid-tier producers without captive roasting infrastructure.
- State Bottle Deposit Laws:Compliance cost fragmentation across California, Oregon, and New York creates operational friction that favors larger producers with dedicated sustainability departments.
- Dairy Alternative Supply Concentration:Oat and almond milk ingredient sourcing clusters in limited processing regions, exposing formulation pipelines to regional climate and logistics disruptions.
Strategic Opportunities
- Direct-to-Consumer Platforms:Subscription models and brand-owned e-commerce channels are capturing repeat purchase loyalty outside traditional retail margin structures.
- Functional Ingredient Convergence:Collagen, adaptogens, and nootropic additives are creating new occasion-based consumption moments in fitness and wellness verticals.
- Clean-Label Reformulation:FDA's updated nutrition labeling requirements for added sugars are creating first-mover advantage for brands with reduced-sugar portfolios ahead of enforcement timelines.
Industry Challenges
- Aseptic Filling Technical Talent:Specialized microbiological safety engineering expertise remains scarce, constraining capacity expansion timelines for emerging brands.
- GRAS Determination Delays:Novel ingredient approval pathways through FDA extend product development cycles and increase regulatory compliance capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ready-To-Drink (RTD) Coffee Market |
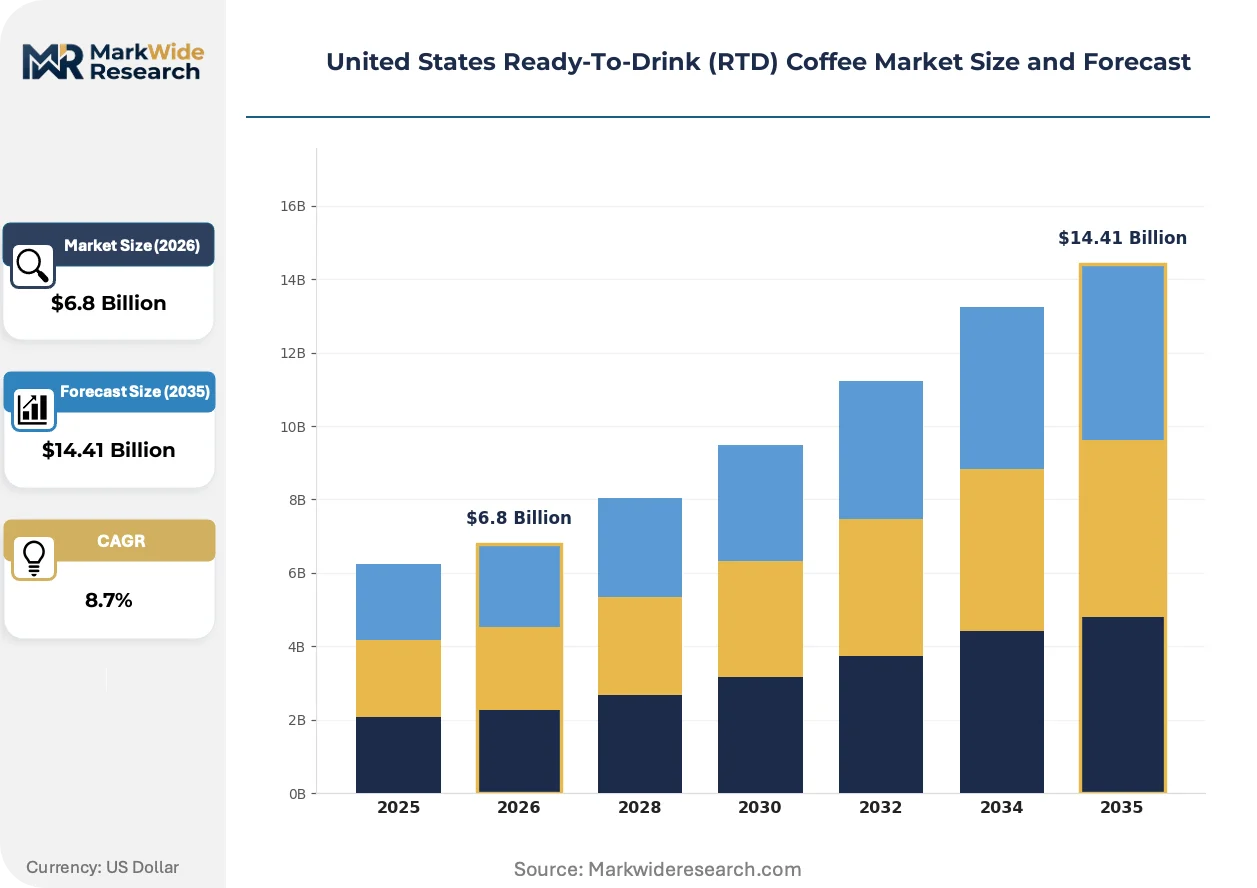
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Bottled, Coffee Pouches, Cartons Flavor Profile: Vanilla, Mocha, Caramel, Hazelnut Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Coffee Shops Consumer Age Group: Millennials, Gen Z, Baby Boomers, Generation X |
| Companies Covered | Starbucks Corp., PepsiCo Inc., The Coca-Cola Company, Nestlé S.A., Danone S.A., Keurig Dr Pepper, Inc., Califia Farms, LLC, La Colombe Holdings, Inc., Dunkin' Brands Group, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ready-To-Drink (RTD) Coffee Market Evolving Landscape
Reformulation pressure and channel diversification are rewriting how RTD coffee reaches consumers and what ingredients qualify for shelf placement.
Cold brew extraction technology is rewriting quality benchmarks across the category. Smaller-batch, extended steeping methods are capturing premium positioning from traditional thermal processing. Northeast corridor retailers and specialty grocers are prioritizing these SKUs, compressing distribution access for conventional hot-brew brands.
FDA's updated nutrition labeling requirements for added sugars are forcing portfolio-wide reformulation investments. Brands must now disclose added versus naturally occurring sugars, creating compliance cost stratification between established players and new entrants. Premium and standard tiers are responding fastest, while economy labels face margin pressure from dual-labeling requirements.
Subscription-based replenishment models are displacing impulse-heavy convenience store purchasing among core urban demographics. Direct-to-consumer platforms capture predictable revenue streams and first-party consumption data. California and New York metropolitan areas show the deepest channel shift, with repeat purchase rates climbing through personalized flavor profiling and delivery scheduling.
United States Ready-To-Drink (RTD) Coffee Market Segmentation
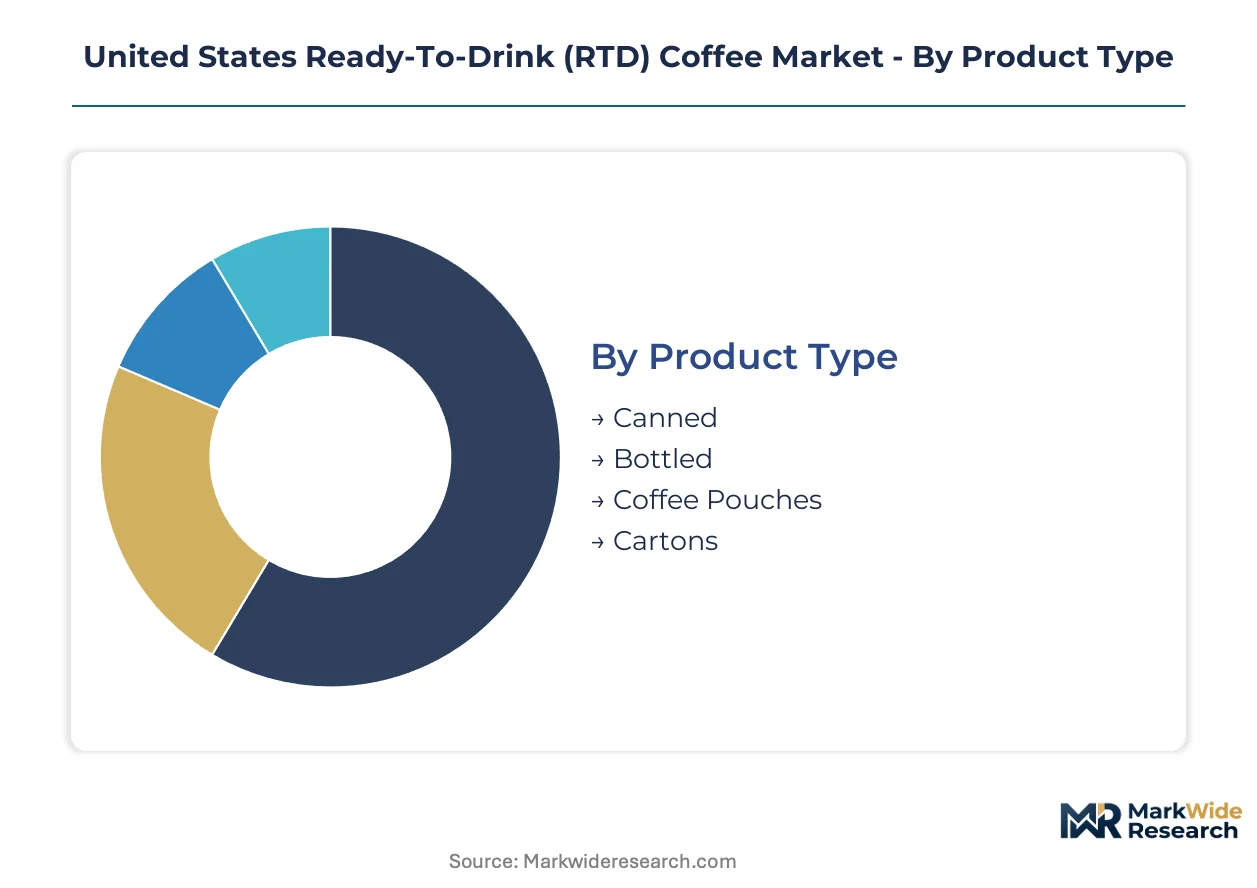
RTD coffee manufacturers calibrate portfolio allocation across four distinct segmentation axes. Product format dictates margin structure and shelf-life engineering requirements. Flavor, channel, and demographic variables determine promotional spend efficiency and repeat purchase velocity in a market where impulse and subscription models coexist.
Product Type:
Purchase decisions here pivot on portability requirements versus resealability needs, with unit economics and thermal processing constraints shaping manufacturer prioritization.
- Bottled:PET and glass formats dominate premium positioning through resealable convenience and label real estate for clean-label claims. California and Northeast corridor retailers allocate disproportionate cold-case facings to these SKUs, driven by commuter consumption patterns and higher per-unit willingness-to-pay.
- Canned:Aluminum formats sustain volume leadership through lower material costs and sports-adjacent marketing alignment. Convenience store channels in Texas and Florida metropolitan areas favor 12-ounce slim cans for single-serve impulse capture, though resealability limitations constrain multipack adoption.
- Coffee Pouches:Flexible single-serve sachets address portability extremes for hiking and military end-uses, with limited retail penetration concentrated in outdoor specialty channels.
- Cartons:Aseptic brick formats serve institutional foodservice and warehouse club bulk purchasing, where per-ounce cost minimization overrides brand loyalty considerations.
Bottled leads on scale; canned leads on momentum.
Flavor Profile:
Flavor selection correlates with daypart targeting and permissible indulgence framing, with formulation complexity driving SKU proliferation strategies.
- Vanilla:The category's baseline sweetener-masking vehicle, vanilla formulations balance broad demographic acceptability against commodity flavor positioning. Midwest and Southern markets show persistent preference for this profile in standard-tier pricing.
- Mocha:Chocolate-coffee fusion captures dessert-replacement occasions and higher caffeine tolerance among younger demographics. Northeast urban centers and Pacific Northwest metropolitan areas sustain disproportionate velocity for mocha SKUs, linked to afternoon energy-seeking behavior.
- Caramel:Butterscotch-adjacent sweetness targets female-skewing demographics in suburban supermarket channels, with seasonal limited editions driving trial.
- Hazelnut:European-origin flavor profile retains niche positioning in specialty coffee shop distribution and premium-tier bottled formats, constrained by polarizing taste intensity.
Vanilla dominates volume throughput; mocha gains share fastest in direct-to-consumer subscription channels.
Distribution Channel:
Channel strategy determines margin capture versus data ownership tradeoffs, with traditional retail yielding scale and digital platforms yielding lifetime value metrics.
- Supermarkets:Mass merchandisers and grocery chains control case volume through promotional calendar coordination and end-cap placement fees. California's SB 54 compliance costs concentrate here due to packaging volume thresholds and deposit law administration.
- Convenience Stores:Impulse-heavy petroleum-retail locations dominate single-serve cold-case velocity, with PepsiCo and Coca-Cola system bottlers controlling cooler door access through beverage category management contracts.
- Online Retail:Amazon and direct-to-consumer platforms represent the steepest expansion trajectory, with subscription models capturing predictable replenishment cycles and first-party consumption data in New York and Los Angeles metropolitan statistical areas.
- Specialty Coffee Shops:Starbucks Reserve and independent third-wave operators serve as brand elevation venues and new product testbeds, with limited volume contribution but disproportionate influence on trend origination.
Supermarkets anchor current revenue; online retail climbs the fastest.
Consumer Age Group:
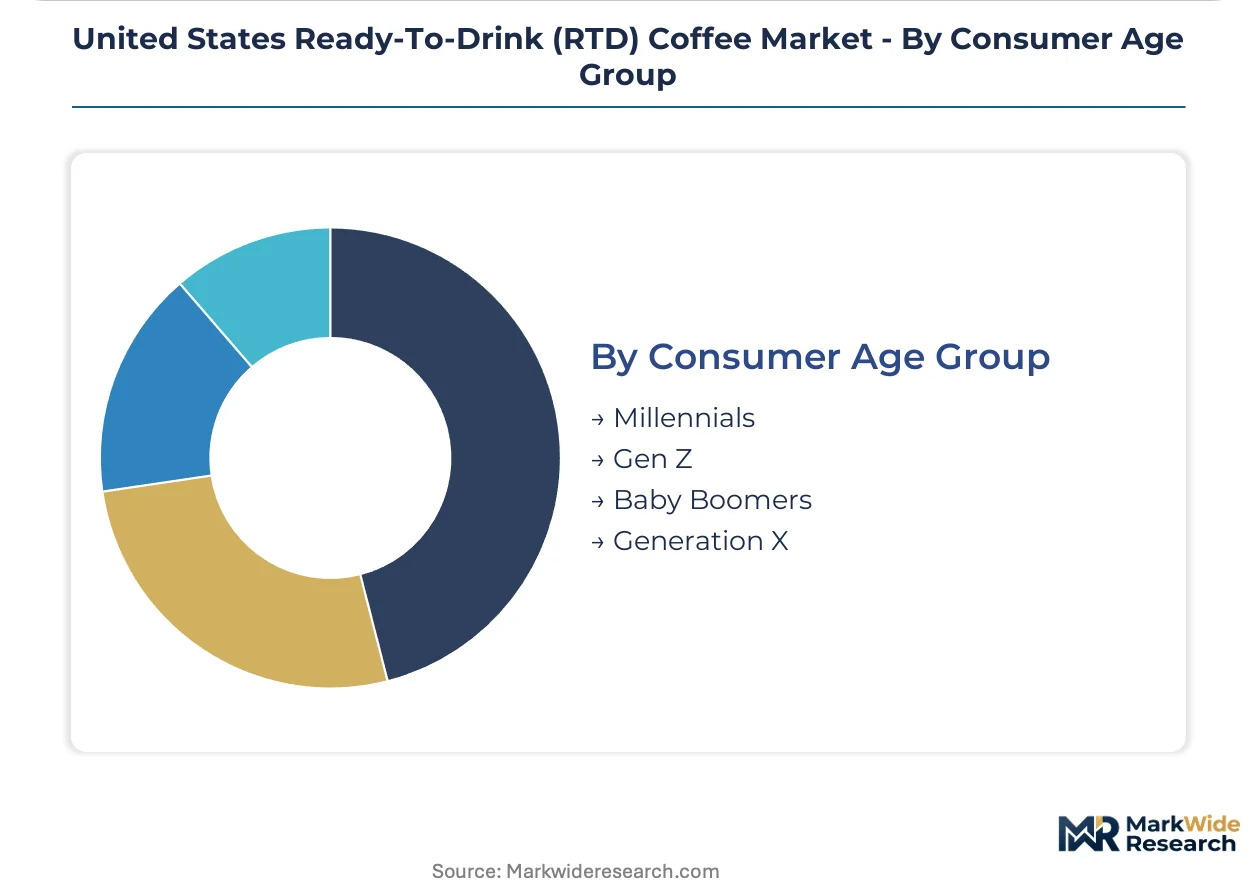
Cohort targeting aligns product attributes with life-stage consumption constraints, from entry-level pricing for debt-burdened younger consumers to health-positioning for aging demographics.
- Millennials:The core volume driver, this cohort balances premium willingness-to-pay with subscription convenience adoption. Cold brew penetration rates peak among urban professional millennials in Seattle, San Francisco, and Austin.
- Gen Z:TikTok-native discovery patterns and functional ingredient openness define this emerging segment. Sugar-conscious reformulation and adaptogen fortification resonate here, with purchase initiation concentrated in campus-adjacent convenience retail.
- Baby Boomers:Loyalty to established brands and hot-brew heritage flavors characterizes this shrinking but high-frequency segment, with supermarket channel dependence and price sensitivity increasing.
- Generation X:Sandwich-generation time constraints drive multipack bulk purchasing in warehouse clubs, with moderate premium acceptance for organic certification claims.
Millennials lead on current spending; Gen Z leads on projected lifetime value acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The RTD coffee industry took root in the United States during the late 1980s when Japanese-style canned coffee imports established shelf-stable coffee as a viable convenience category, with domestic production scaling through the 1990s as Starbucks and PepsiCo pioneered the bottled Frappuccino format.
California
Cold brew penetration rates peak here among urban professionals seeking smoother caffeine delivery. The state's SB 54 extended producer responsibility mandate forces manufacturers to internalize packaging end-of-life costs. Los Angeles and San Francisco metropolitan areas concentrate the deepest direct-to-consumer subscription adoption and specialty coffee shop distribution networks.
Northeast Corridor
Urban commuter density drives the highest per-capita consumption of bottled formats in New York, Boston, and Philadelphia metropolitan statistical areas. State bottle deposit laws in New York impose compliance cost fragmentation that favors larger producers with dedicated sustainability departments. Brooklyn and Queens anchor independent cold brew innovation and third-wave coffee shop testbed activity.
Texas
Convenience store channel dominance supports canned format volume leadership through petroleum-retail impulse purchasing in Dallas-Fort Worth and Houston. The absence of state bottle deposit laws reduces operational friction for emerging brands testing price-sensitive formulations. Austin's millennial population sustains above-average cold brew penetration relative to other Sun Belt metros.
Pacific Northwest
Seattle's heritage as Starbucks' headquarters city creates disproportionate brand loyalty and premium willingness-to-pay for certified organic SKUs. Washington State's clean energy mandates intersect with manufacturing facility location decisions for brands emphasizing carbon-neutral processing claims. Portland's independent roaster culture feeds specialty RTD experimentation through co-packing relationships.
Florida
Tourism-dependent consumption patterns create seasonal demand spikes for single-serve canned formats in Orlando and Miami metropolitan areas. The state's lack of bottle deposit infrastructure reduces compliance overhead relative to California or New York operations. Jacksonville and Tampa convenience store channels favor sports-adjacent marketing alignment for energy-positioned RTD coffee variants.
United States Ready-To-Drink (RTD) Coffee Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and channel access dimensions. The United States RTD coffee sector exhibits consolidated structure at the top tier with captive roasting infrastructure, while mid-tier and emerging brands fragment across co-packing dependencies and regional distribution partnerships. Three strategic archetypes dominate: beverage conglomerates with diversified refreshment portfolios, coffee-specialist companies with upstream bean-to-shelf control, and plant-based dairy hybrid innovators. Competitive intensity centers on M&A activity targeting cold brew capabilities and strategic partnerships locking convenience store cooler door access.
Within the beverage conglomerate tier, Starbucks Corp., PepsiCo Inc., and Nestlé S.A. anchor competitive positioning through divergent control strategies. Starbucks exemplifies the coffee-specialist archetype with captive roasting infrastructure. PepsiCo represents diversified refreshment portfolio breadth. Nestlé S.A. occupies the manufacturing scale position through its Solon, Ohio production facility. Each sits within distinct margin and channel access tiers without overlapping core strategic vectors.
| Leading Market Players |
|---|
| Starbucks Corp. |
| PepsiCo Inc. |
| The Coca-Cola Company |
| Nestlé S.A. |
| Danone S.A. |
| Keurig Dr Pepper, Inc. |
| Califia Farms, LLC |
| La Colombe Holdings, Inc. |
| Dunkin' Brands Group, Inc. |
| Others |
Value Network & Pricing Analysis
Aseptic filling engineers concentrated in Ohio and Wisconsin command wage premiums that widen spreads between premium-tier bottled formats and economy canned variants. Labor scarcity at thermal processing facilities forces mid-tier brands toward co-packing arrangements, compressing margin autonomy and amplifying price stratification across USDA organic, conventional, and private-label tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs shelf placement negotiations, with organic certification and cold brew processing method as primary price differentiation drivers. Cost compression in the standard tier intensifies because Arabica bean price volatility and dual-labeling compliance for added sugars erode producer margins. Convenience store impulse buyers exhibit highest price sensitivity, while direct-to-consumer subscribers demonstrate lowest elasticity due to replenishment habit formation.
Supply Chain Analysis
California's SB 54 domestic-content mandate for packaging end-of-life accountability is reshaping sourcing decisions toward in-state recycling infrastructure partners. Raw material flows draw from Colombian and Brazilian Arabica origins, Wisconsin dairy and oat milk processing clusters, and Chinese aluminum can manufacturing. Single-source vulnerability concentrates in aseptic carton barrier film supply. Distribution runs through PepsiCo and Coca-Cola system bottler networks controlling convenience store cooler door access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas and Florida offer geographic arbitrage against California and New York compliance costs, with absence of bottle deposit laws reducing operational friction for price-sensitive formulation testing.
For Market Incumbents: Extend captive roasting infrastructure into cold brew extraction capabilities to defend against specialty co-packer encroachment. Anchor convenience store cooler door contracts through beverage category management partnerships that lock out emerging brands. Prioritize Solon-scale manufacturing investments that amortize SB 54 compliance across volume tiers. For New Entrants and Emerging Players: Enter via Texas metropolitan convenience store channels where deposit law absence and lower slotting fees reduce capital barriers. Target functional ingredient convergence in fitness verticals, where collagen and adaptogen fortification commands premium pricing with less entrenched incumbent presence. Launch through direct-to-consumer subscription to capture first-party data before retail expansion. For Investors and Strategic Acquirers: Beverage conglomerates with diversified refreshment portfolios are the most active acquirer in this space, seeking cold brew capabilities and brand elevation assets. Long-term viability hinges on clean-label reformulation completion ahead of enforcement timelines. Monitor GRAS determination velocity for novel functional ingredients as inflection indicator for product pipeline expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Brew Capability Acquisition | Starbucks and La Colombe cold brew assets command premium valuations from PepsiCo system bottlers seeking format expansion. |
| Direct-to-Consumer Platform Launch | Subscription models in Los Angeles and New York metropolitan areas capture repeat purchase loyalty outside retail margin structures. |
| Clean-Label Reformulation Investment | FDA added sugar disclosure requirements favor early movers with reduced-sugar portfolios ahead of compliance deadlines. |
| Convenience Store Cooler Door Expansion | PepsiCo and Coca-Cola bottler category management contracts dominate impulse purchase locations in Texas and Florida. |
| Sustainability Repositioning | California SB 54 packaging accountability mandates favor producers with dedicated sustainability departments and in-state recycling partnerships. |
Research Methodology
Coverage spans California, Texas, Florida, and the Northeast corridor, with primary inputs from each region triangulated against national trends. The research combines interviews with RTD coffee brand managers, convenience store category buyers, aseptic filling facility engineers, and USDA organic certification auditors with secondary validation from FDA GRAS notices, Nielsen retail audit data, and state-level bottle deposit compliance filings. Bottom-up volume modeling and top-down value estimation cross-check against trade customs records and SEC beverage segment disclosures.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models segmentation across product format, flavor profile, distribution channel, and consumer age cohort, with additional dimensioning for organic certification tier and cold brew versus hot-brew extraction method. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and channel shift velocity. Forecast inputs incorporate Arabica futures price volatility assumptions and SB 54 compliance cost pass-through rates.
The model holds under stable FDA enforcement timelines and continued urban commuter consumption patterns; deviation in GRAS determination delays or sugar taxation municipal adoption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding cold brew penetration rates and subscription channel expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
High Protein Coffee Market
Coffee
Coffee Pods Market
Coffee
Coffee Beans Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Tea and Coffee Bags Market
Coffee
Italy Coffee Market
Coffee
Canned Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
United States Coffee Market
Coffee
Coffee Grinder Market
Coffee
Coffee Syrup Market
Coffee
Global Automatic Coffee Machines Market
Coffee
UK Coffee Roaster Market
Coffee
Singapore Coffee Roaster Market
Coffee
North America Instant Coffee Market