
 Espresso Powder Market | 2026-2036
Espresso Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Espresso Powder Market Analytics
Barista-level roasting expertise is rotating from artisan cafés into industrial R&D labs, tightening the talent pool available to mid-sized processors. Nestle leverages its vertically integrated coffee supply chain to secure premium arabica lots for soluble extraction. JDE anchors its European manufacturing footprint with dedicated espresso powder lines in the Netherlands and France. Starbucks competes through direct-to-consumer channel control, converting café brand equity into retail instant formats.
Espresso powder consists of finely ground, dark-roasted coffee beans processed through spray-drying or freeze-drying to produce a concentrated, water-soluble extract with 1.5–3% residual moisture and intense aromatic oil retention. The product serves commercial bakeries, beverage manufacturers, and home consumers requiring consistent coffee flavor without brewing equipment. Instant espresso dominates volume throughput due to its compatibility with single-serve stick packs and vending machine channels, while organic espresso commands premium shelf positioning in specialty retail. Food manufacturers represent the fastest-growing end-user category as clean-label dessert and confectionery formulations replace artificial coffee flavorants with natural powdered extracts.
The FDA enforces strict labeling standards for instant coffee products under the Federal Food, Drug, and Cosmetic Act, including caffeine content disclosure and allergen cross-contamination protocols. The EU's REACH regulation governs chemical residues in processing solvents, while EFSA sets maximum acrylamide thresholds for roasted coffee derivatives sold in member states. Stakeholders must monitor evolving pesticide residue limits under the EU Green Deal's Farm to Fork strategy, as these standards propagate through contract farming agreements into origin-country enforcement.
Market Dynamics
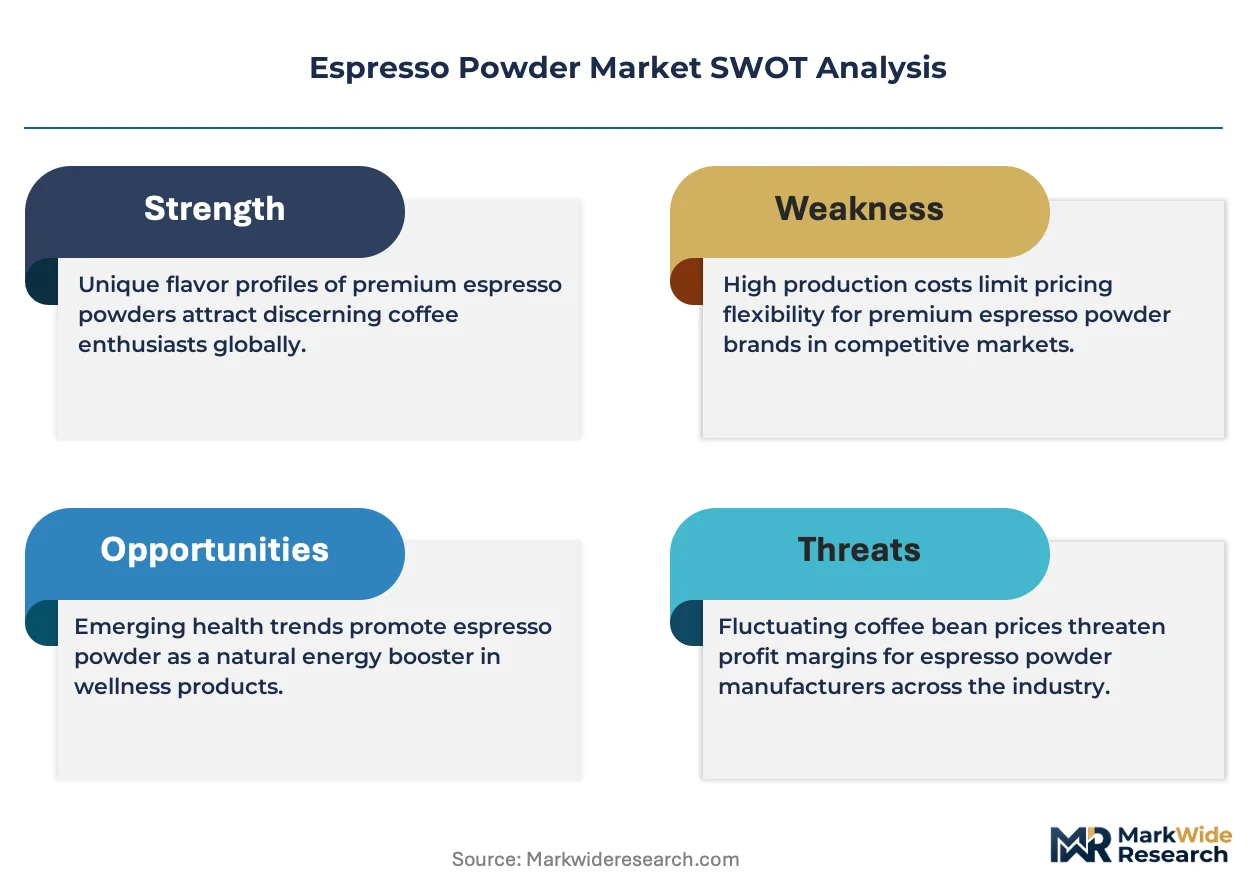
The EU Green Deal's Farm to Fork strategy is restructuring how espresso powder processors contract arabica supplies, forcing origin-country compliance upgrades and reshaping competitive access to certified bean lots.
Growth Catalysts
- Clean-label confectionery demand:Food manufacturers are replacing artificial coffee flavorants with natural powdered extracts in dessert formulations, pulling volume through industrial procurement channels.
- Single-serve stick pack compatibility:Instant espresso's moisture stability and flow properties align with automated packaging lines serving vending machine and hospitality channels.
- Home-barista segment expansion:Specialty coffee shop chains in Italy and the United States are extending branded powdered espresso into retail, converting café loyalty into pantry stock.
Market Restraints
- Arabica price volatility:Concentrated sourcing from Brazil and Vietnam exposes processors to frost and drought shocks that compress margin buffers.
- Acrylamide threshold enforcement:EFSA's maximum limits for roasted coffee derivatives require capital-intensive process controls that disadvantage smaller European processors.
- Fresh espresso substitution:Capsule system penetration in German and French households threatens instant espresso's convenience positioning among premium buyers.
Strategic Opportunities
- Organic certification premium:EU Green Deal agricultural sustainability criteria create shelf-space advantages for processors with origin-country organic supply contracts.
- Bakery ingredient channel development:Industrial bakeries in France and the Netherlands are qualifying powdered espresso for croissant and tiramisu fillings, opening bulk volume contracts.
- Freeze-drying technology convergence:Combining spray-drying efficiency with freeze-dried aromatic retention is enabling mid-tier processors to challenge premium positioning.
Industry Challenges
- Roasting expertise migration:Artisan café talent is relocating to industrial R&D labs, narrowing the specialist pool available to mid-sized soluble coffee processors.
- REACH solvent residue compliance:Chemical processing verification timelines for extraction solvents are extending product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Espresso Powder Market |
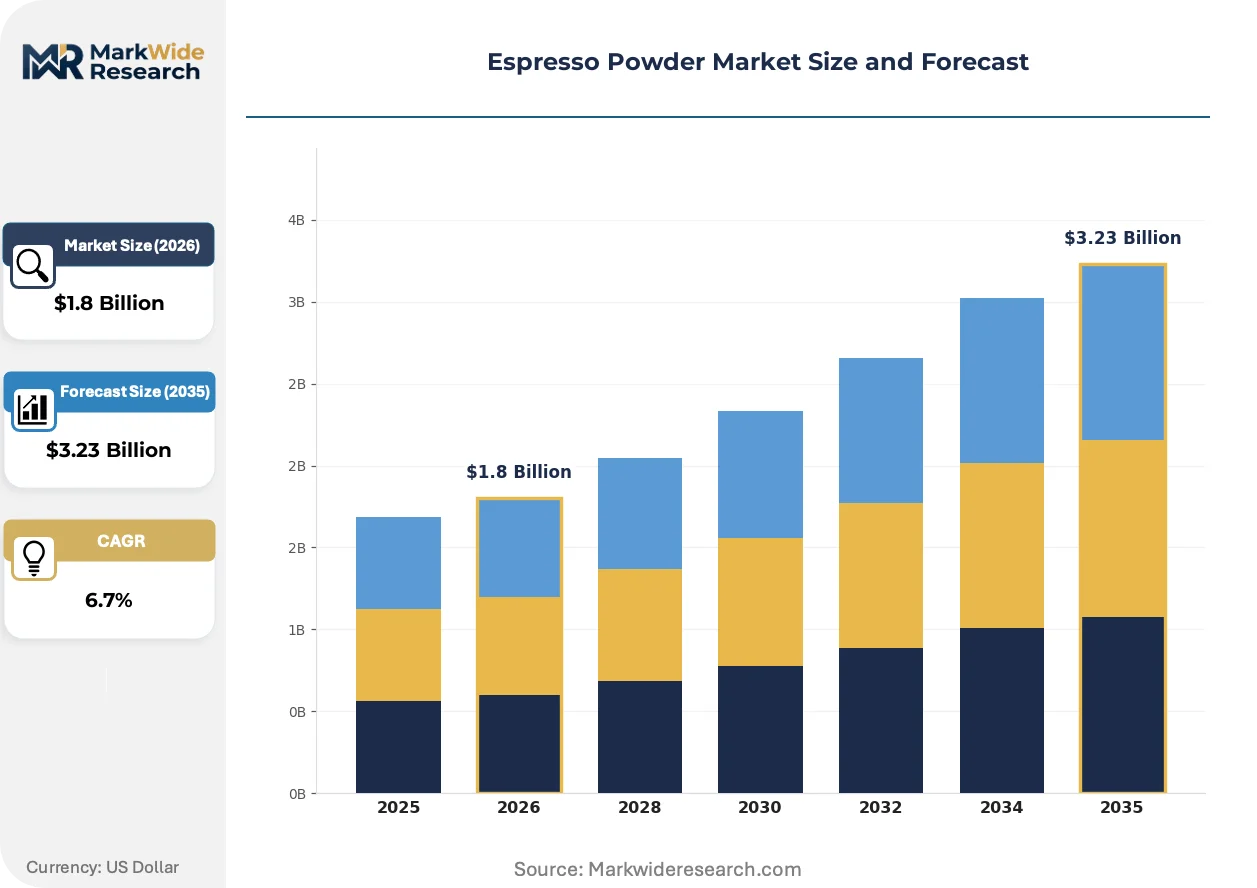
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Espresso, Instant Espresso, Decaf Espresso, Espresso Blends Form: Powder, Granules, Liquid Concentrate, Extract End User: Household, Cafes, Restaurants, Food Manufacturers Packaging Type: Bags, Jars, Pouches, Containers |
| Companies Covered | Nestle, JDE, The Kraft Heinz, Luigi Lavazza S.p.A., Tchibo, Starbucks, illycaffè S.p.A., Segafredo Zanetti, Tata Global Beverages, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Espresso Powder Market Evolving Landscape
Processing technology and sourcing certification are converging to redefine quality differentiation in espresso powder, with sustainability credentials now functioning as technical specifications rather than marketing overlays.
Cold-brew soluble extraction is fragmenting traditional hot-extraction process hierarchies. This low-temperature method preserves volatile aromatic compounds that degrade under thermal processing. Premium confectionery manufacturers in Belgium and Switzerland are adopting cold-brew powders for chocolate and patisserie applications. The technology is fragmenting equipment vendor relationships as processors dual-source hot and cold extraction lines.
REACH chemical residue protocols are tightening solvent monitoring across European manufacturing. ECHA enforcement actions against non-compliant extraction facilities have triggered industry-wide migration to food-grade ethanol and supercritical CO2 systems. Italian and Spanish processors face the steepest compliance curves due to legacy chlorinated solvent dependencies.
Direct-to-consumer subscription models are compressing traditional wholesale distribution layers. Specialty roasters in Portland and Melbourne are bypassing retail intermediaries to ship micro-lot espresso powders on monthly cycles. This channel shift is most visible among millennial home-barista segments seeking traceability narratives unavailable through supermarket instant coffee aisles.
Espresso Powder Market Segmentation
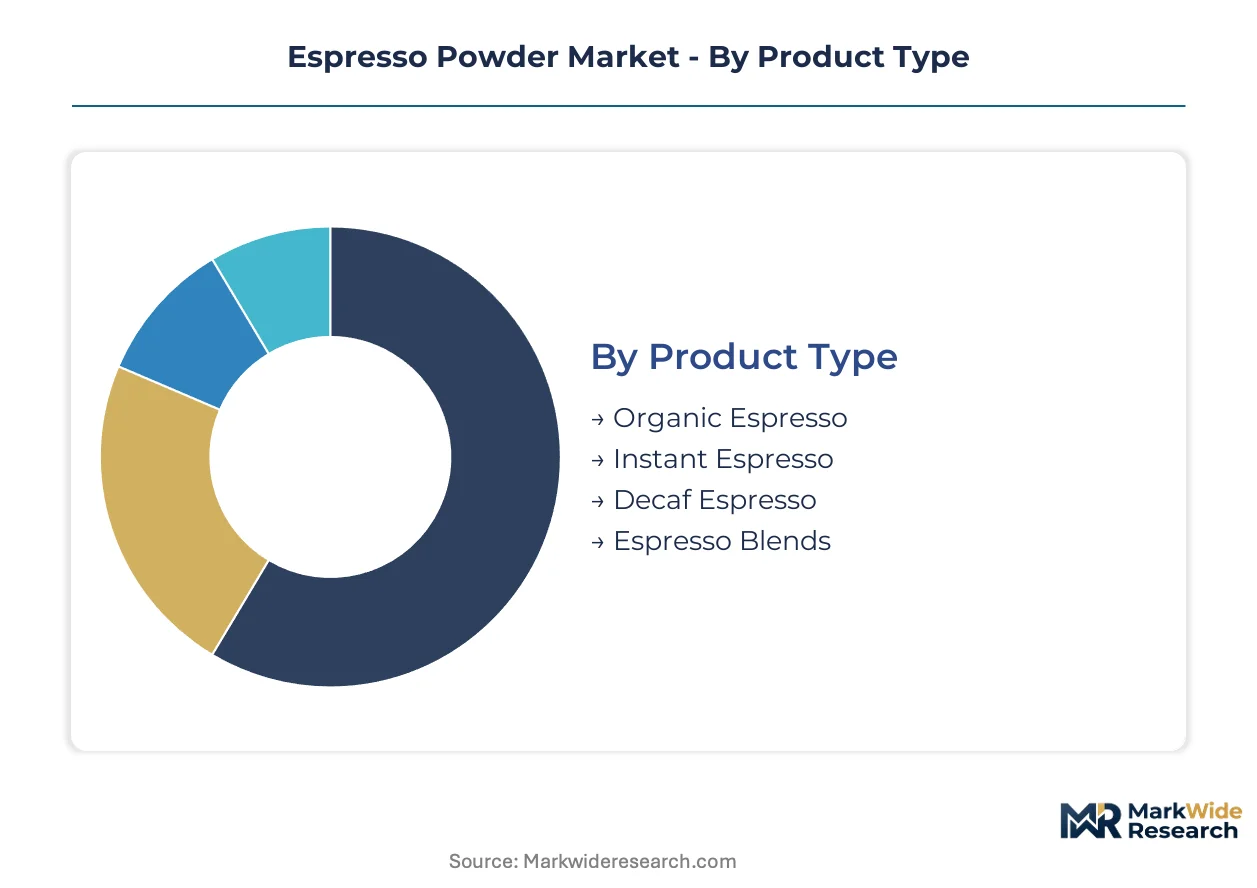
Espresso powder segmentation reveals distinct channel economics across product tiers, with instant formats dominating mass retail velocity while organic variants command specialty placement premiums. Form factors and packaging configurations further stratify procurement patterns between industrial foodservice buyers and home-consumption channels.
Product Type:
Channel-mix dynamics concentrate instant espresso through supermarket and vending machine networks, while organic and decaf variants flow predominantly through specialty retail and direct-to-consumer platforms.
- Instant Espresso:Spray-dried or freeze-dried soluble extract with 1.5–3% residual moisture, engineered for rapid dissolution in hot water. Demand concentrates in Italian and United States vending machine channels and single-serve hospitality portions, driven by automated packaging compatibility and moisture stability requirements. By volume, Instant Espresso leads. By growth pace, Organic Espresso is ahead.
- Organic Espresso:Certified arabica beans processed through EU Green Deal-compliant supply chains with full origin traceability. Premium shelf positioning in Netherlands and France specialty retail accelerates as clean-label confectionery manufacturers qualify certified inputs for chocolate and patisserie applications.
- Decaf Espresso:CO2 or water-processed decaffeinated extract retaining aromatic oil profiles. Health-conscious household segments in Germany and Switzerland drive qualification for home-barista pantries.
- Espresso Blends:Multi-origin arabica-robusta formulations balancing intensity with solubility. Italian industrial bakeries specify blend ratios for tiramisu and croissant filling applications.
Organic certification creates the steepest price-tier separation, with certified products commanding shelf-space advantages under EU agricultural sustainability criteria.
Form:
Cost-tier differentiation separates commodity spray-dried powders from premium freeze-dried granules, with liquid concentrates occupying an intermediate position in food manufacturing procurement.
- Powder:Finely milled soluble extract with controlled particle size distribution for beverage and bakery dispersion. Food manufacturers in Belgium and Switzerland prioritize powder flow properties for automated dessert production lines.
- Granules:Agglomerated particles with enhanced aromatic oil retention through freeze-drying. Premium positioning in French and Spanish specialty retail reflects superior flavor intensity for home-barista reconstitution.
- Liquid Concentrate:High-strength aqueous extract requiring refrigerated distribution. Cold-brew processing variants gain traction among Portland and Melbourne direct-to-consumer roasters seeking volatile compound preservation.
- Extract:Ultra-concentrated soluble base for industrial flavoring applications. Netherlands-based confectionery manufacturers leverage extract potency for clean-label coffee flavorant replacement.
Granules capture premium pricing tiers, while powders dominate procurement tonnage across industrial channels.
End User:
Application-specific requirements fragment procurement specifications, with food manufacturers imposing the most stringent solubility and residue compliance standards.
- Food Manufacturers:Industrial bakeries and confectionery producers in France and the Netherlands drive volume through bulk contracts for croissant, tiramisu, and chocolate applications. REACH solvent residue compliance and EFSA acrylamide thresholds constrain supplier qualification. This segment is expanding most quickly as clean-label formulations displace artificial flavorants.
- Household:Home-barista consumers in Italy and the United States convert café brand loyalty into pantry stock through specialty retail and subscription channels. Single-serve stick pack compatibility shapes packaging preferences.
- Cafes:Back-of-house soluble espresso for baking and sauce applications supplements fresh espresso service. Portland and Melbourne specialty roasters bypass wholesale intermediaries through direct-to-consumer models.
- Restaurants:Dessert and beverage program inputs requiring consistent flavor without brewing equipment. Hospitality procurement in Germany and France prioritizes portion-control packaging formats.
Food manufacturers impose the tightest technical specifications, while household channels generate the most volatile demand fluctuations.
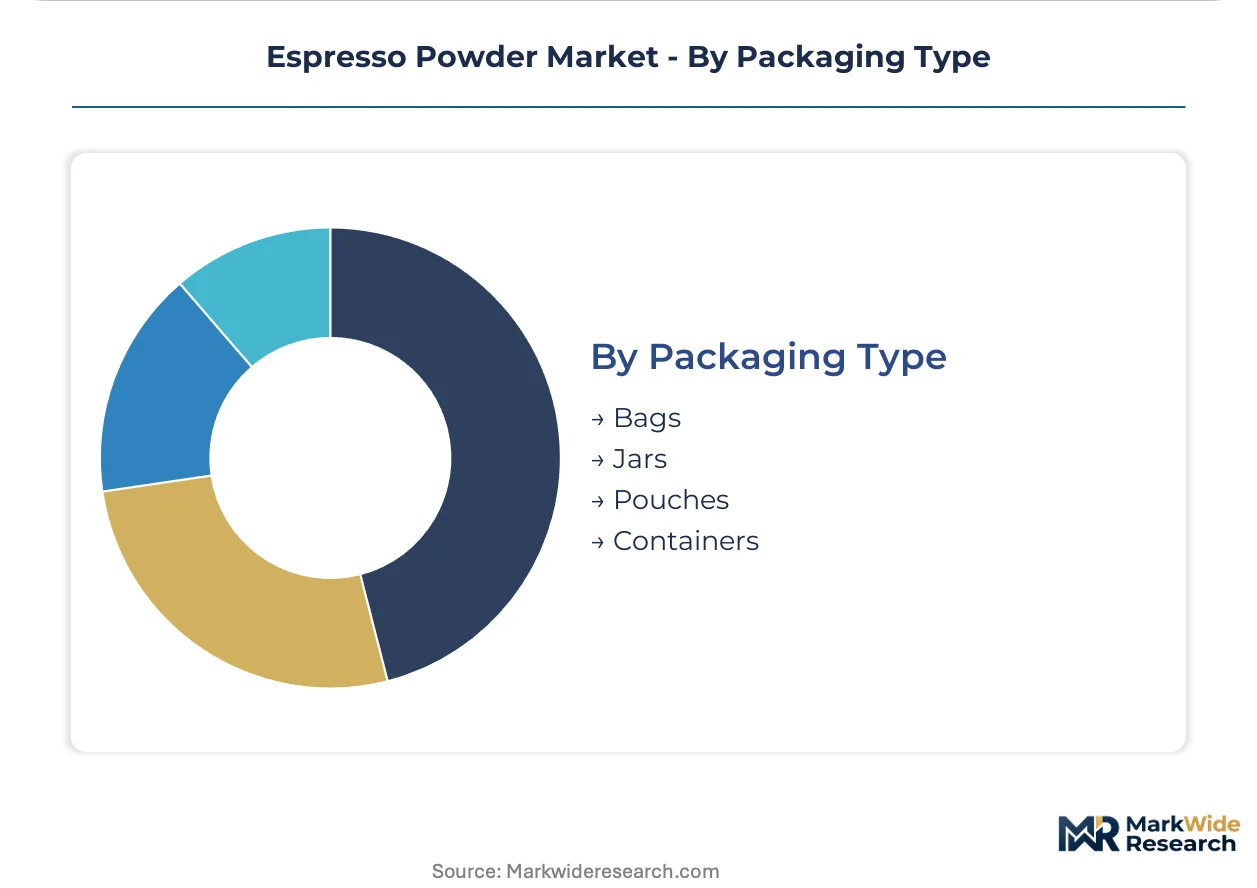
Packaging Type:
Volume scale and margin structure diverge sharply between bulk industrial containers and single-serve retail formats.
- Pouches:Flexible laminate structures with moisture barrier properties for single-serve and small-format retail. Automated stick pack lines in Italian vending machine channels favor pouch flow characteristics.
- Jars:Rigid glass or plastic containers for pantry-stock household segments. Premium positioning in French specialty retail emphasizes resealability and shelf visibility.
- Bags:Multi-wall paper or foil laminate for foodservice and light industrial quantities. Netherlands bakery ingredient distributors specify bag formats for croissant filling procurement.
- Containers:Bulk rigid packaging for industrial food manufacturing inputs. Confectionery producers in Belgium optimize container specifications for automated dispensing systems.
Containers and bags dominate procurement tonnage, while pouches deliver the highest unit margins through single-serve positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's acrylamide thresholds and EU Green Deal sourcing criteria are restructuring competitive access to certified arabica supplies across the five dominant national markets.
Italy
Traditional espresso culture intersects with industrial-scale soluble production in Lombardy and Veneto. REACH chemical residue protocols force migration from legacy chlorinated solvents to food-grade ethanol systems. Turin hosts concentrated R&D activity where artisan roasting expertise relocates to industrial labs.
United States
Specialty coffee shop chains extend branded powdered espresso into retail channels targeting home-barista segments. FDA labeling standards under the Federal Food, Drug, and Cosmetic Act mandate caffeine content disclosure and allergen cross-contamination protocols. Portland and Melbourne-style direct-to-consumer subscription models compress traditional wholesale distribution layers.
Germany
Capsule system penetration in households threatens instant espresso's convenience positioning among premium buyers. EFSA maximum acrylamide limits for roasted coffee derivatives require capital-intensive process controls. Industrial bakeries in Bavaria and North Rhine-Westphalia qualify powdered espresso for clean-label dessert formulations.
France
Premium granule positioning in specialty retail reflects superior flavor intensity for home-barista reconstitution. EU Green Deal Farm to Fork strategy propagates pesticide residue limits through contract farming agreements. Paris and Lyon-based confectionery manufacturers leverage extract potency for natural coffee flavorant replacement.
Netherlands
Industrial bakery ingredient distributors specify bag formats for croissant and tiramisu filling procurement. ECHA enforcement actions against non-compliant extraction facilities trigger industry-wide solvent system migrations. Amsterdam-Rotterdam corridor anchors European manufacturing footprint with dedicated espresso powder lines.
Espresso Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the espresso powder market. Vertically integrated multinational food conglomerates control premium arabica sourcing and captive soluble extraction capacity. Mid-tier processors compete through hybrid freeze-spray drying technology convergence. Strategic moves concentrate on backward integration into origin-country certified supply contracts and geographic expansion of direct-to-consumer subscription platforms.
Among European-based processors, Luigi Lavazza S.p.A. and Segafredo Zanetti exemplify the heritage-roaster archetype migrating artisan expertise into industrial R&D functions. Nestle occupies a position representing the vertically integrated multinational archetype with captive supply chain control over premium arabica lots. These three companies anchor the competitive structure through divergent channel strategies spanning retail instant formats, foodservice hospitality portions, and industrial bakery ingredient supply.
| Leading Market Players |
|---|
| Nestle |
| JDE |
| The Kraft Heinz |
| Luigi Lavazza S.p.A. |
| Tchibo |
| Starbucks |
| illycaffè S.p.A. |
| Segafredo Zanetti |
| Tata Global Beverages |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Brazilian and Vietnamese arabica processing facilities shapes margin compression dynamics across spray-dried and freeze-dried extraction tiers. Scale concentration in origin-country roasting infrastructure establishes price floors that mid-tier European processors struggle to match without backward integration into certified supply contracts.
Pricing Analysis
Price spreads between Italian specialty retail and German mass-market channels exceed threefold for equivalent solubility grades. Three-tier pricing structure across organic-certified, conventional instant, and private-label economy levels reflects EU Green Deal compliance costs and aromatic oil retention technology. Pricing pressure stems from capsule system substitution in French and German premium households. Food manufacturers exhibit lowest price sensitivity due to clean-label formulation lock-in, while vending machine operators face acute margin compression.
Supply Chain Analysis
Strategic arabica stockpiling dominates processor inventory strategy ahead of Brazil's frost season, contrasting with just-in-time green bean flows for European decaffeination facilities. Raw material sourcing draws from Brazil, Vietnam, and Colombia for arabica-robusta blending ratios. Extraction solvent compliance under REACH regulation creates single-source vulnerability for Italian and Spanish processors with legacy chlorinated dependencies. Distribution runs through Amsterdam-Rotterdam corridor manufacturing hubs into industrial bakery and confectionery channels across France, Belgium, and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Espresso powder demand cycles correlate with arabica futures volatility and specialty coffee shop expansion waves, positioning the market for recovery as origin-country climate shocks moderate and home-barista subscription penetration deepens.
For Market Incumbents: Fortify captive arabica sourcing through EU Green Deal-compliant contract farming agreements in Brazil and Colombia. Nestle and JDE should accelerate freeze-drying capacity additions in the Netherlands to defend premium positioning against hybrid technology challengers. EFSA acrylamide enforcement threatens smaller European processors with compliance cost disadvantages.
For New Entrants and Emerging Players: Anchor in Portland and Melbourne direct-to-consumer subscription white space where traceability narratives bypass retail intermediaries. Cold-brew soluble extraction technology offers the most penetrable differentiation angle for premium confectionery supply contracts. Target Belgian and Swiss chocolate manufacturers with volatile compound retention specifications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid freeze-spray drying specialists with EU organic certification and industrial bakery channel penetration. Long-term viability hinges on backward integration into origin-country supply contracts rather than equipment-only plays. Watch ECHA enforcement action intensity as inflection signal for solvent system migration capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Supply Contracting | Secures certified arabica lots for EFSA-compliant extraction and premium shelf positioning. |
| Freeze-Spray Hybrid Technology Deployment | Enables mid-tier processors to challenge premium granule positioning with aromatic retention parity. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale compression in Portland and Melbourne home-barista segments. |
| Industrial Bakery Channel Qualification | Locks bulk volume contracts with French and Netherlands croissant and tiramisu manufacturers. |
| REACH Solvent System Migration | Avoids ECHA enforcement exposure for Italian and Spanish legacy chlorinated dependencies. |
Research Methodology
A spread of perspectives from coffee processing plant managers, specialty roaster R&D directors, industrial bakery procurement leads, and EU regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from EFSA acrylamide threshold documentation, REACH solvent residue protocols, EU Green Deal Farm to Fork strategy filings, and customs trade data for green coffee imports. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled span product type hierarchy, form factor economics, end-user application requirements, and packaging configuration across the projection horizon. CAGRs derived from historical arabica price volatility patterns and specialty coffee shop channel expansion trajectories. Forecast inputs incorporated EU pesticide residue limit propagation timelines and freeze-drying technology adoption curves.
Material uncertainties — origin-country climate shocks, EFSA threshold revisions, and capsule system substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU Green Deal compliance cost trajectories and industrial bakery clean-label conversion rates. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and Brazilian frost frequency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Ground Coffee Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
United States Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
Coffee Premixes Market
Coffee
Italy Coffee Market
Coffee
Caffeine Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Organic Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
US Coffee Machine Market
Coffee
Adaptogen Coffee Market
Coffee
Green Coffee Bean Extract Market
Coffee
US Coffee Roaster Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Specialty Coffee Market