
 Coffee Extracts Market | 2026-2036
Coffee Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Extracts Market Outlook
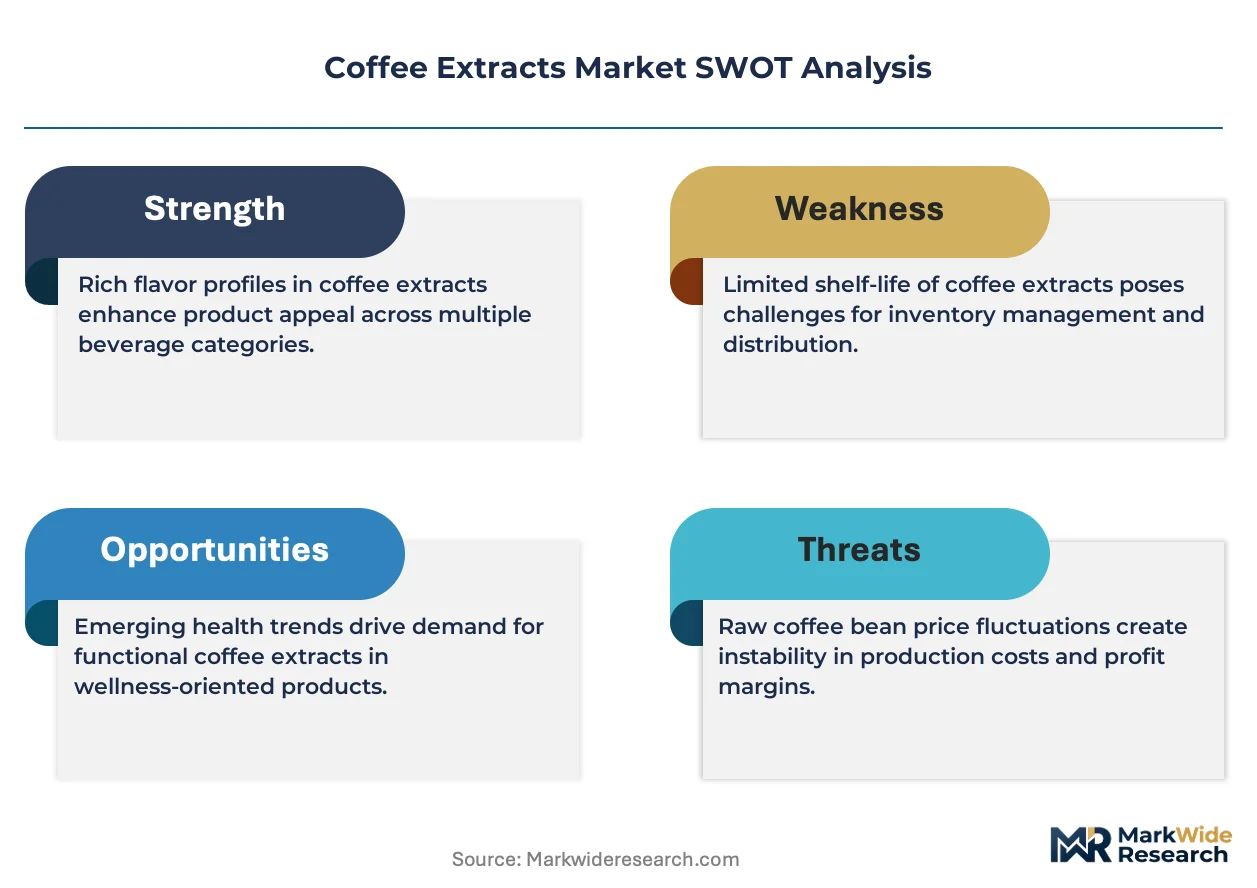
The EU Green Deal is expanding compliance obligations for coffee extract suppliers shipping into European markets. Nestlé leverages backward integration into bean sourcing and roasting infrastructure across Latin America and Africa. Jacobs Douwe Egberts anchors its competitive position through proprietary freeze-dried extract technologies. Givaudan specializes in flavor-house partnerships that embed coffee extracts into beverage and confectionery formulations.
Coffee extracts are concentrated preparations derived from roasted or unroasted Coffea arabica and Coffea canephora beans through aqueous extraction, spray-drying, or freeze-drying processes, yielding standardized solids ranging from 15% to 100% concentration for industrial flavoring, beverage bases, and cosmetic active applications. Liquid extracts hold established share in beverage manufacturing due to ease of batch formulation and dissolution control, while powdered variants gain traction in nutraceutical capsules and functional food powders where shelf stability and precise dosing matter. The organic formulation segment commands premium positioning as clean-label procurement policies at North American and European food manufacturers tighten ingredient specifications.
FDA food additive regulations, EFSA novel food assessments, and USDA organic certification standards collectively govern extract purity, labeling claims, and import eligibility across major destination markets. REACH compliance in Europe adds chemical safety documentation burdens for solvent-extracted variants entering cosmetic and nutraceutical channels. Stakeholders must monitor evolving deforestation traceability mandates and decaffeination process disclosures as these criteria increasingly determine supplier qualification at multinational buyers.
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are restructuring procurement relationships between European buyers and Latin American coffee extract suppliers, forcing traceability investments that reshape competitive positioning across the value chain.
Growth Catalysts
- Ready-to-drink beverage manufacturing:Liquid extract procurement is accelerating as beverage formulators seek batch consistency and rapid dissolution control for functional coffee drinks.
- EU Green Deal compliance infrastructure:Deforestation traceability requirements are creating qualification barriers that favor established suppliers with integrated sourcing networks.
- Clean-label procurement policies:North American and European food manufacturers are tightening organic certification standards, elevating premium positioning for certified extract variants.
Market Restraints
- Raw bean price volatility:Arabica futures fluctuations in Brazilian and Colombian commodity markets transmit directly into extract production cost structures.
- Spray-drying energy intensity:Natural gas and electricity input costs for thermal drying processes constrain margin expansion during energy price spikes.
- REACH documentation burdens:ECHA chemical safety filing requirements for solvent-extracted cosmetic-grade variants create regulatory friction for smaller suppliers entering European channels.
Strategic Opportunities
- Freeze-dried nutraceutical applications:Precise dosing requirements in functional food powders and capsules are opening premium segments beyond conventional beverage bases.
- Cosmetic active ingredient channels:Caffeine and antioxidant extract applications in skincare formulations represent underpenetrated demand outside traditional food and beverage verticals.
- Backward integration into roasting infrastructure:Captive control over bean sourcing and roast profiles enables flavor standardization that commodity traders cannot match.
Industry Challenges
- Decaffeination process disclosure requirements:Multinational buyers are demanding solvent residue documentation that many mid-tier extractors lack laboratory infrastructure to generate.
- Organic certification timeline compression:USDA and EU organic audit backlogs are extending supplier qualification cycles beyond typical procurement planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Extracts Market |
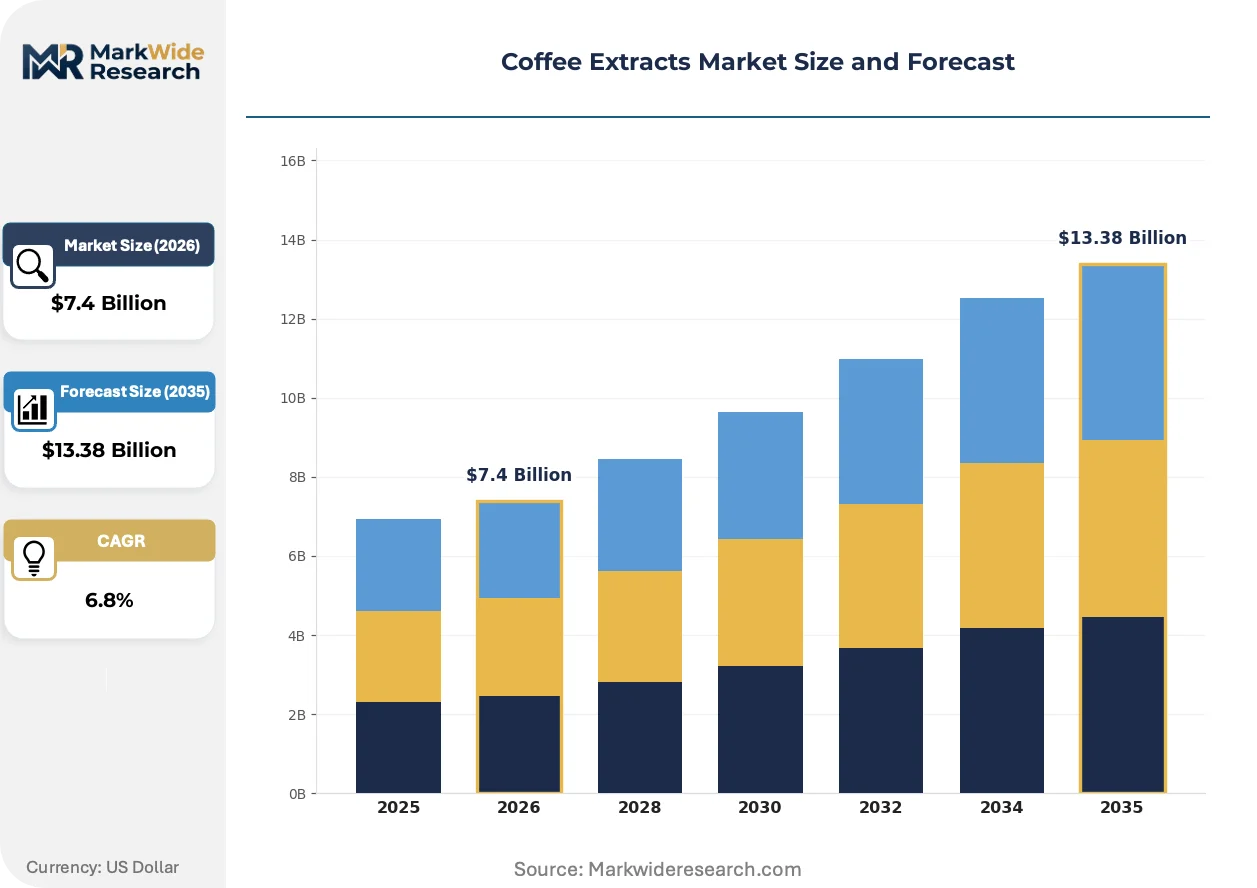
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Powdered Extracts, Instant Coffee, Coffee Beans Application: Beverages, Cosmetics, Nutraceuticals, Bakery Products Formulation: Organic, Conventional, Decaffeinated, Specialty Distribution Channel: Online Stores, Supermarkets, Specialty Retailers, Food Service |
| Companies Covered | Nestlé, Starbucks Corporation, Jacobs Douwe Egberts, Givaudan, Kerry Group, Kraft Heinz, Firmenich, Keurig Dr Pepper, Lavazza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Extracts Market Strategic Shifts
Extraction technology and regulatory traceability are converging to redefine supplier qualification criteria, while demand patterns shift toward concentrated formats that prioritize dissolution performance over commodity bean trading.
Supercritical CO2 decaffeination is absorbing market share from traditional solvent-based processes in premium extract segments. Specialty coffee roasters and organic-certified suppliers are adopting this technology to eliminate methylene chloride residue concerns. The capital intensity of pressurized CO2 systems is compressing supplier tiers, favoring processors with captive infrastructure over toll manufacturers.
REACH chemical safety documentation requirements are expanding scope for solvent-extracted variants entering European cosmetic and nutraceutical channels. ECHA filing obligations now cover residual caffeine and chlorogenic acid concentrations previously exempt from disclosure. Small and mid-tier Brazilian and Colombian processors are responding by partnering with EU-based regulatory consultants or exiting cosmetic-grade supply entirely.
Clean-label procurement mandates are rotating demand toward certified organic and deforestation-free extract grades. North American beverage manufacturers are unbundling commodity coffee purchasing from extract supply agreements to enforce traceability standards. This pattern is most visible in contract negotiations between ready-to-drink brands and their flavor-house partners, where EUDR compliance documentation now sits alongside price and volume terms.
Coffee Extracts Market Segmentation
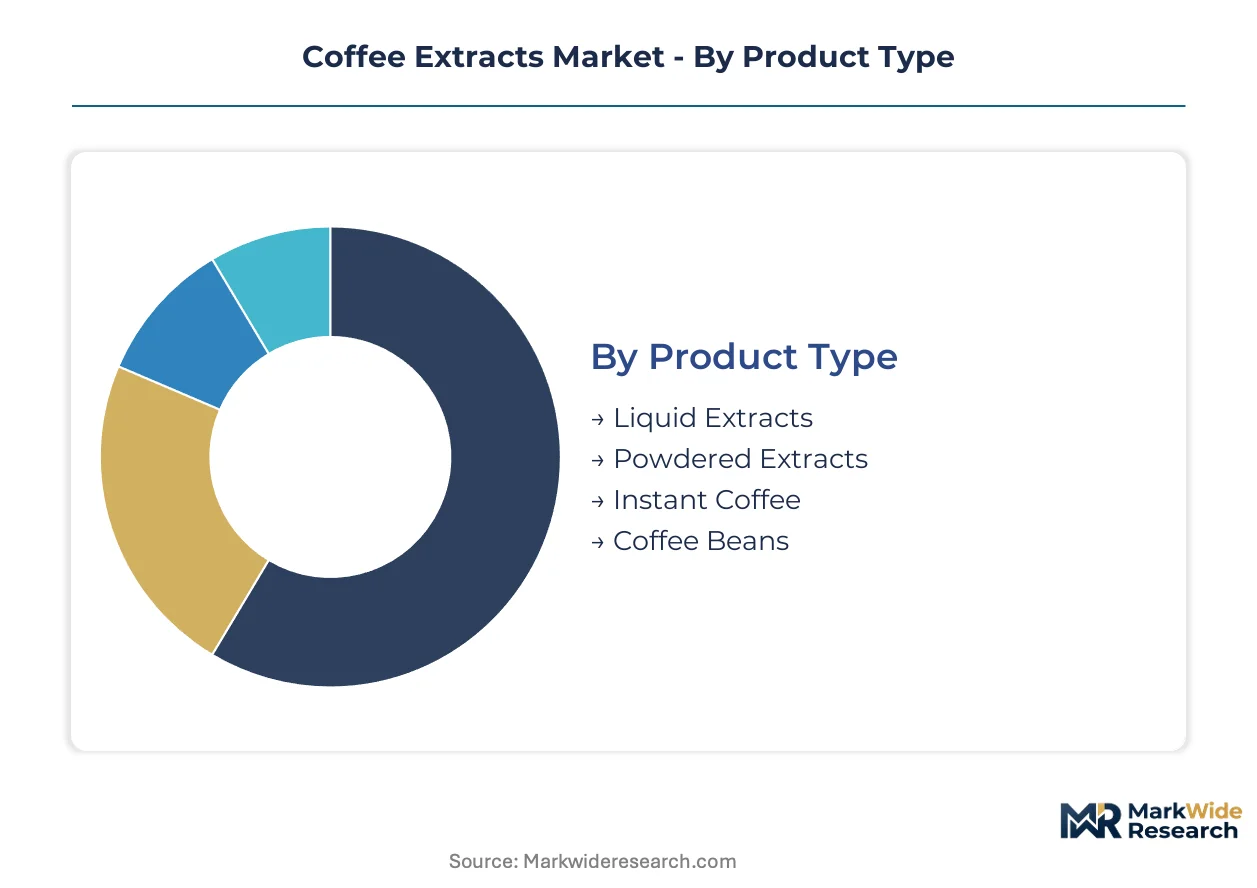
Coffee extract procurement decisions hinge on dissolution performance, certification grade, and channel-specific formulation requirements. Buyers unbundle commodity bean purchasing from extract supply agreements to enforce traceability standards that commodity traders cannot match.
Product Type:
Manufacturers select extract formats based on batch processing speed, shelf stability requirements, and equipment compatibility with existing production lines.
- Liquid Extracts:Aqueous concentrates standardized to 15-40% soluble solids enable precise batch formulation control in ready-to-drink beverage manufacturing. Nestlé and Jacobs Douwe Egberts accelerate procurement for functional coffee drinks where rapid dissolution determines production throughput.
- Powdered Extracts:Spray-dried or freeze-dried preparations ranging from 50-100% concentration prioritize shelf stability and precise dosing. Demand concentrates in nutraceutical capsules and functional food powders where moisture sensitivity constrains liquid alternatives.
- Instant Coffee:Agglomerated or freeze-dried soluble coffee granules reconstitute rapidly in hot water for direct consumer preparation.
- Coffee Beans:Whole or ground roasted beans serve as feedstock for captive extraction operations and specialty retail channels.
Volume sits with Liquid Extracts; growth tilts toward Powdered Extracts.
Application:
End-use specifications diverge sharply across cosmetic, nutraceutical, and beverage channels, with each vertical imposing distinct purity and documentation requirements.
- Beverages:Standardized extracts for ready-to-drink formulations, coffee concentrates, and flavor bases dominate procurement volumes. Brazil anchors demand as both sourcing origin and processing hub for soluble derivatives.
- Cosmetics:Caffeine and chlorogenic acid isolates for skincare formulations require REACH-compliant documentation for European cosmetic channels. ECHA filing obligations for residual compound concentrations compress supplier tiers.
- Nutraceuticals:Precise-dose extracts for functional supplements and wellness products command premium positioning through organic certification.
- Bakery Products:Flavor extracts and coffee powders for confectionery and baked goods applications emphasize cost efficiency at scale.
Revenue concentrates in Beverages; margin expansion tilts toward Cosmetics.
Formulation:
Certification grade determines supplier qualification at multinational buyers, with organic and deforestation-free documentation now standard in contract negotiations.
- Organic:USDA and EU organic-certified extracts command premium positioning as clean-label procurement policies tighten ingredient specifications. Audit backlogs are extending supplier qualification cycles beyond typical procurement planning horizons.
- Conventional:Standard extracts without organic certification serve cost-sensitive beverage and food manufacturing applications.
- Decaffeinated:Supercritical CO2 processed variants eliminate methylene chloride residue concerns for premium segments. Capital intensity of pressurized systems favors processors with captive infrastructure.
- Specialty:Single-origin, micro-lot, or proprietary roast profile extracts target specialty coffee roasters and premium beverage brands.
Procurement volume sits with Conventional; qualification priority tilts toward Organic.
Distribution Channel:
Channel selection reflects buyer scale, documentation requirements, and the need for technical support in formulation integration.
- Online Stores:Direct-to-manufacturer and small-batch procurement platforms enable rapid sample access for product development teams. Digital channels expand fastest for specialty and organic-certified variants.
- Supermarkets:Mass-market retail distribution serves consumer-packaged instant coffee and extract products.
- Specialty Retailers:Premium and single-origin extracts for artisan roasters and boutique food manufacturers.
- Food Service:Bulk liquid and powdered extracts for hospitality, restaurant, and institutional catering operations.
Transaction volume sits with Food Service; channel expansion tilts toward Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors coffee extract processing capacity through integrated roasting and soluble manufacturing corridors serving both domestic formulation and export markets.
Brazil
Ready-to-drink beverage manufacturers in Campinas and Ribeirão Preto accelerate liquid extract procurement for functional coffee formulations. ANVISA cosmetic-grade registration requirements compress supplier tiers for caffeine isolate exports. Minas Gerais coffee belt cooperatives invest in traceability infrastructure to satisfy EU Green Deal deforestation-free mandates.
United States
Clean-label procurement policies at North American food manufacturers tighten organic certification standards for extract suppliers. FDA food additive regulations govern decaffeination process disclosures in contract negotiations. Pacific Northwest specialty coffee roasters drive demand for single-origin micro-lot extracts with proprietary roast profiles.
Germany
REACH chemical safety documentation requirements reshape procurement relationships for solvent-extracted cosmetic-grade variants. ECHA filing obligations for residual caffeine concentrations favor established suppliers with integrated regulatory infrastructure. Hamburg and Bremen port clusters concentrate import logistics for Latin American extract shipments.
Japan
Precise-dose freeze-dried extract demand concentrates in nutraceutical capsules and functional food powders. METI standards for food additive purity intersect with industry self-regulation on solvent residue thresholds. Kansai region beverage formulators source liquid concentrates for ready-to-drink coffee manufacturing.
India
FSSAI food safety compliance and DGFT export documentation requirements structure extract trade flows for cosmetic and nutraceutical channels. Karnataka coffee belt processors in Chikmagalur and Coorg develop spray-drying capacity for instant coffee derivatives. Domestic demand for chicory-blended extracts sustains cost-competitive manufacturing.
Coffee Extracts Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and traceability documentation capabilities. The supplier base stratifies into integrated multinationals with captive sourcing networks, mid-tier toll processors dependent on third-party bean supply, and specialty organic-certified operators serving clean-label procurement policies. Three archetypes dominate: backward-integrated beverage conglomerates controlling roast profiles and extraction infrastructure; flavor-house partners embedding extracts into beverage and confectionery formulations; and toll manufacturers serving commodity instant coffee production. Competitive moves concentrate on traceability infrastructure investments and freeze-drying capacity expansion for nutraceutical applications.
Within the integrated multinational tier, Nestlé and Jacobs Douwe Egberts exemplify backward integration into Latin American and African bean sourcing networks. Givaudan occupies a position among flavor-house specialists that embed coffee extracts into beverage and confectionery formulations through technical partnership structures. These three anchors represent distinct competitive vectors: captive supply chain control, proprietary extraction technology, and formulation integration expertise.
| Leading Market Players |
|---|
| Nestlé |
| Starbucks Corporation |
| Jacobs Douwe Egberts |
| Givaudan |
| Kerry Group |
| Kraft Heinz |
| Firmenich |
| Keurig Dr Pepper |
| Lavazza |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's deforestation-free supply chain mandates operate as a dual gatekeeper mechanism, restricting qualified supply access while simultaneously filtering which suppliers can command premium-tier pricing in European procurement channels. Buyers now unbundle commodity bean purchasing from extract supply agreements to enforce traceability standards that commodity traders cannot match, compressing supplier tiers and rotating price power toward integrated operators with captive sourcing networks.
Pricing Analysis
Batch consistency and rapid dissolution performance anchor value-based pricing in ready-to-drink beverage manufacturing, where Nestlé and Jacobs Douwe Egberts pay premiums for standardized liquid extracts that minimize formulation rework. Certification grade and volume scale drive price differentiation, with USDA and EU organic-certified variants commanding substantial premiums over conventional alternatives. Cost compression in spray-dried commodity tiers is intensifying because natural gas and electricity input spikes constrain margin expansion. Mid-tier toll processors exhibit highest price sensitivity, while backward-integrated multinationals with captive roasting infrastructure demonstrate lowest sensitivity due to in-house production of key inputs.
Supply Chain Analysis
Domestic-content mandates in Brazil's ANVISA cosmetic-grade registration requirements are reshaping sourcing patterns, forcing foreign suppliers to establish local processing presence or exit caffeine isolate channels entirely. Supply concentrates in Brazil, Colombia, and Vietnam as primary sourcing origins, with São Paulo anchoring integrated roasting and soluble manufacturing corridors. The chain draws from green coffee beans, natural gas for thermal drying, and methylene chloride or supercritical CO2 for decaffeination processes. Single-source vulnerability runs through Brazilian arabica futures volatility, which transmits directly into extract production cost structures. Distribution runs through Hamburg and Bremen port clusters for European entry, with flavor-house technical partnerships embedding extracts into downstream beverage formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coffee extracts market sits in a technology-transition phase as supercritical CO2 decaffeination displaces traditional solvent-based processes, eliminating residue concerns while compressing supplier tiers through capital intensity barriers.
For Market Incumbents: To counter margin erosion from energy price volatility and raw bean futures fluctuations, deepen backward integration into Latin American and African roasting infrastructure to capture flavor standardization premiums commodity traders cannot replicate. Prioritize freeze-drying capacity expansion for nutraceutical applications where precise dosing requirements command sustained premium positioning.
For New Entrants and Emerging Players: Begin with cosmetic active ingredient channels in European markets, where REACH documentation requirements have compressed incumbent supply and created qualification gaps for caffeine and chlorogenic acid isolates. Target white-space demand in skincare formulations by partnering with EU-based regulatory consultants to navigate ECHA filing obligations, using technical partnership structures that mirror Givaudan's flavor-house embedding model.
For Investors and Strategic Acquirers: Accelerating procurement volumes from ready-to-drink beverage manufacturers is the leading indicator that liquid extract demand will outpace commodity instant coffee growth. Long-term viability favors processors with integrated traceability infrastructure and captive organic certification pipelines. Watch for EU Green Deal audit backlogs extending supplier qualification cycles beyond procurement planning horizons as the inflection signal for acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Roasting Infrastructure | Captive control over Minas Gerais and Colombian bean sourcing enables flavor standardization unmatched by commodity traders. |
| Freeze-Drying Capacity Expansion | Precise-dose capabilities for nutraceutical capsules address functional food powder demand concentrated in Japan and North America. |
| Supercritical CO2 Decaffeination Adoption | Elimination of methylene chloride residue concerns opens premium segments as clean-label procurement policies tighten. |
| EU Regulatory Consultant Partnerships | ECHA filing infrastructure enables Brazilian and Colombian processors to maintain cosmetic-grade channel access. |
| Traceability Infrastructure Investment | Deforestation-free documentation satisfies EU Green Deal mandates that now sit alongside price terms in contract negotiations. |
Study Parameters
Independent corroboration across ANVISA registration databases, ECHA chemical safety filings, and USDA organic certification records underwrites the qualitative findings presented in this study. Primary interviews with coffee processing plant managers, procurement leads at ready-to-drink beverage manufacturers, flavor-house technical directors, and cosmetic formulation scientists combined with secondary validation from customs trade data, SEC 10-K disclosures, and EU Green Deal implementation guidance. Bottom-up volume modeling across extract format segments triangulated against top-down value estimates from industry association reports.
Rate-of-change decomposition across product type, application vertical, certification grade, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs were derived through segment-level growth rate blending weighted by baseline revenue contribution, with inputs including arabica futures price trajectories, spray-drying energy cost indices, and organic certification audit timeline data.
Underlying measurement precision varies by segment; liquid and powdered extract volumes carry tighter precision than instant coffee derivatives due to more concentrated supplier reporting. Forecasts reflect documented assumptions regarding EU Green Deal implementation timelines and supercritical CO2 equipment deployment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Oceania Coffee Market
Coffee
Coffee and Tea Capsule Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Robusta Coffee Beans Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Coffee Roaster Market
Coffee
Single Origin Coffee Market
Coffee
Ethiopia Coffee Market
Coffee
United States Coffee Pods and Capsules Market
Coffee
Global Professional Coffee Machine Market
Coffee
United States Coffee Market
Coffee
Coffee Fruit Extract Market
Coffee
Tea and Coffee Bags Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market