
 Coconut Syrup Market | 2026-2036
Coconut Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Syrup Market Analysis
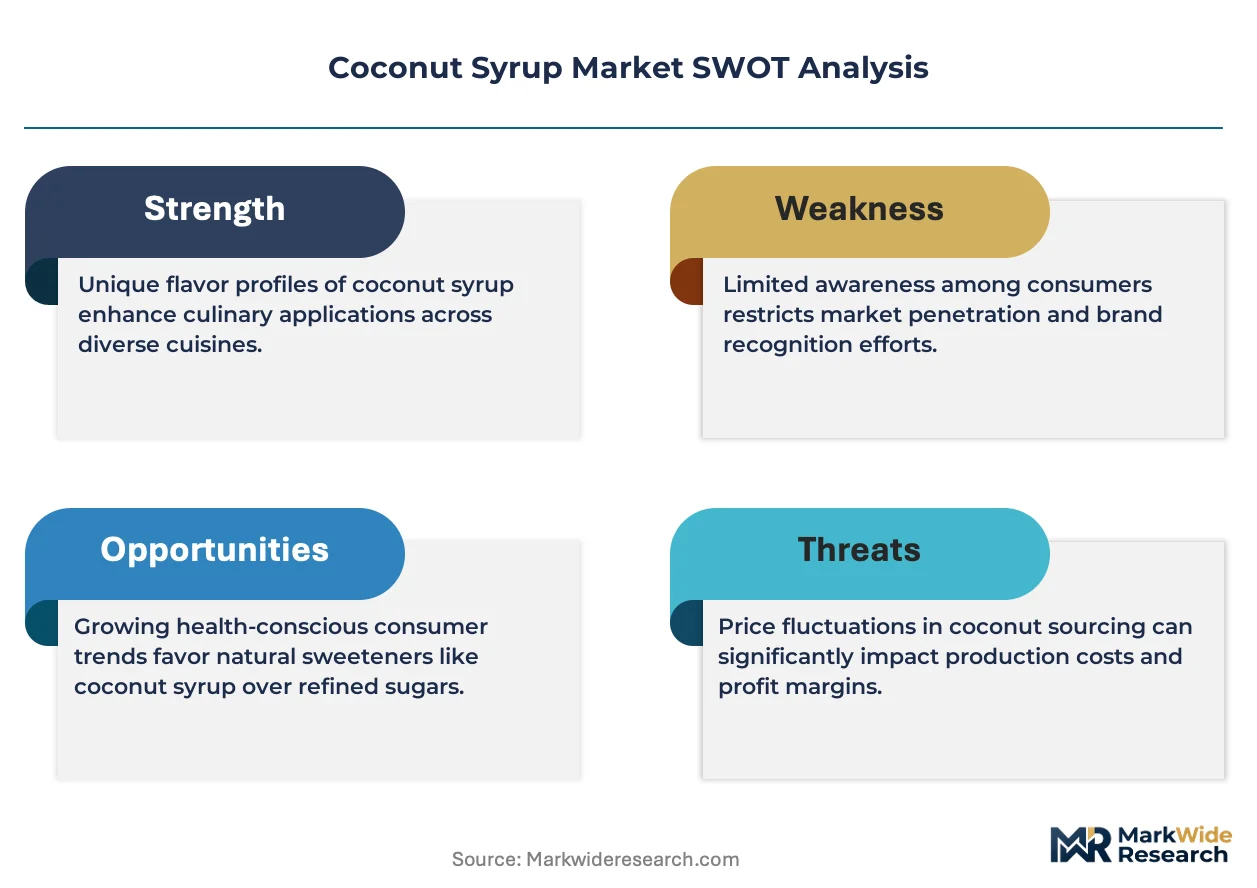
EU organic certification standards is recalibrating the cost-of-entry calculus for coconut syrup exporters seeking access to European retail channels. Bali Nutra Ltd. leverages its Indonesian supply base to control raw sap sourcing from farm to processing facility. Tradin Organic Agriculture B.V. dominates European distribution through its Rotterdam logistics hub and longstanding organic trader relationships. Wholesome Sweeteners Inc. anchors North American shelf presence through premium placement in Whole Foods and independent natural grocers.
Coconut syrup is a viscous liquid sweetener derived from the reduced sap of coconut palm inflorescences, typically containing sucrose as its dominant sugar fraction alongside glucose and fructose, with a glycemic index lower than refined cane sugar. Manufacturers reduce fresh sap through controlled evaporation to achieve soluble solids concentrations suitable for industrial food formulation or direct consumer use. Organic product type commands premium shelf positioning as retailers restrict conventional alternatives in dedicated natural food aisles. Beverage manufacturers represent the fastest-growing end user segment as craft soda and functional drink brands replace high-fructose corn syrup with plant-based alternatives. Online retail distribution channels are capturing incremental volume from direct-to-consumer subscription models that bypass traditional wholesale markups.
FDA food labeling requirements in the United States mandate accurate sugar disclosure on nutrition facts panels, pushing manufacturers toward single-ingredient sweeteners that simplify compliance. BIS quality standards in India govern domestic coconut product purity benchmarks that shape export eligibility for regional processors. Stakeholders must monitor evolving organic equivalence agreements between ASEAN producer nations and destination markets to preempt certification gaps that could interrupt supply continuity.
Market Dynamics
Clean-label mandates from EFSA and FDA are compressing formulation timelines for food manufacturers, forcing rapid substitution of refined cane sugar with single-ingredient natural sweeteners that simplify compliance documentation.
Growth Catalysts
- EU organic certification standards:Retailers across Germany and France now restrict conventional sweeteners in dedicated natural food aisles, creating shelf-access premiums for certified coconut syrup suppliers.
- Beverage reformulation:Craft soda and functional drink manufacturers in the United States are replacing high-fructose corn syrup with plant-based alternatives to meet FDA sugar disclosure requirements.
- Southeast Asian tapping infrastructure:Indonesia, the Philippines, and Sri Lanka maintain industrial-scale coconut palm sap collection networks that lower raw material aggregation costs for processors.
Market Restraints
- Raw sap perishability:Fresh coconut sap ferments within hours of collection, requiring immediate evaporation or chilling infrastructure that elevates capital requirements for new entrants.
- Input cost volatility:Weather disruptions in the Bay of Bengal and South China Sea regions create unpredictable coconut palm yields, compressing processor margins during poor harvest cycles.
- Substitution threat:Date syrup and agave nectar from established supply chains compete for the same clean-label positioning in European and North American retail channels.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channels bypass traditional wholesale markups by delivering coconut syrup directly to home bakers and specialty food enthusiasts.
- ASEAN organic equivalence agreements:Evolving mutual recognition protocols between Indonesia, the Philippines, and destination markets reduce duplicate certification costs for exporters.
- Functional beverage convergence:Kombucha and adaptogenic drink brands combine coconut syrup with probiotic or botanical ingredients, opening premium positioning above commodity sweeteners.
Industry Challenges
- Organic certification timeline:Three-year conversion periods for conventional coconut palm groves delay supply expansion for processors responding to sudden demand spikes.
- Skilled tapper scarcity:Traditional coconut palm climbing and sap collection expertise concentrates among aging rural workforces in Kerala and Java, constraining scalable labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Syrup Market |
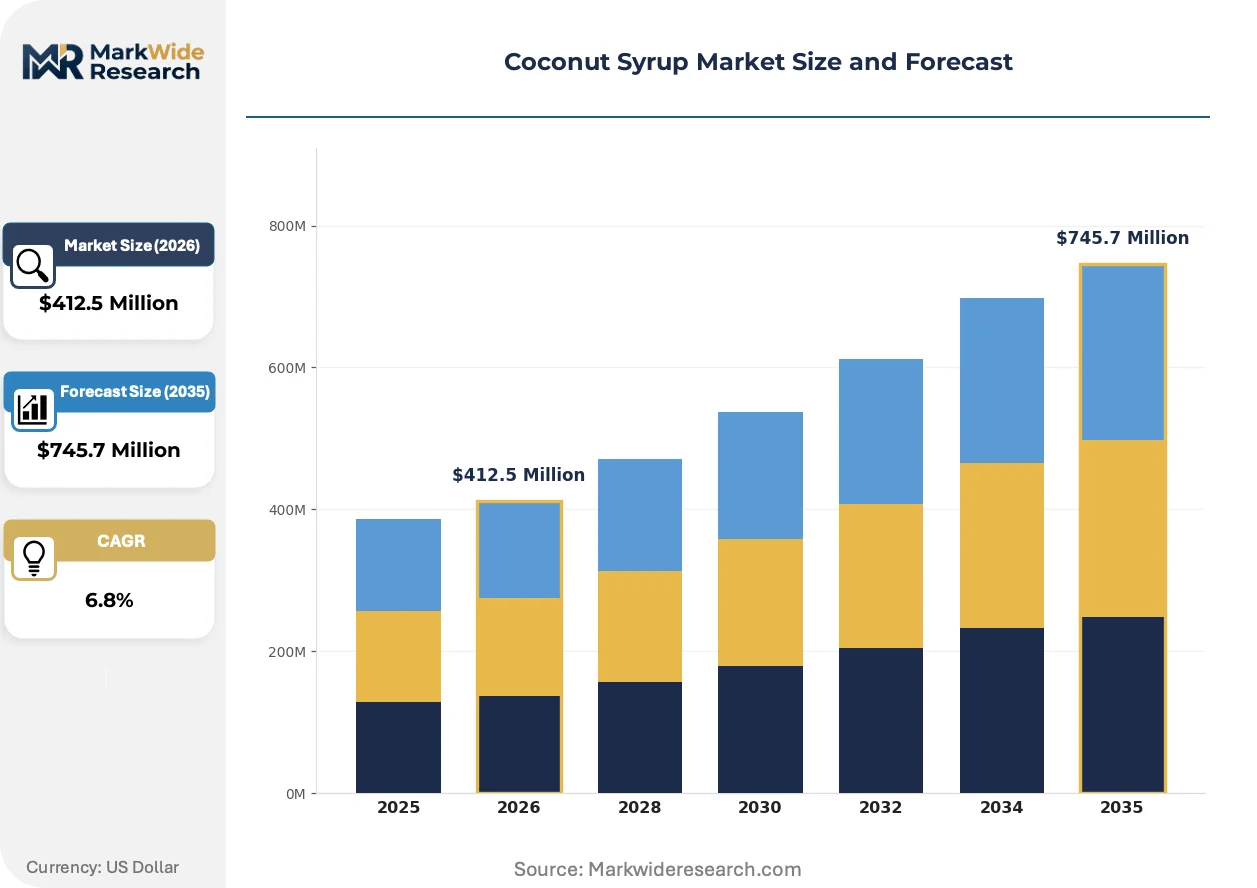
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Raw, Flavored End User: Food Industry, Beverage Manufacturers, Retail Stores, Foodservice Packaging Type: Bottles, Tetra Packs, Jars, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Bali Nutra Ltd., Tradin Organic Agriculture B.V., Wholesome Sweeteners Inc., Coconut Secret, Coconut Merchant Ltd., Big Tree Farms, Benevelle Corporation, Treelife, Madhava Natural Sweeteners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Syrup Market Emerging Trajectories
Membrane filtration and low-temperature evaporation systems are compressing processing energy requirements while preserving coconut syrup's enzymatic and mineral content for premium positioning.
Low-temperature vacuum evaporation is overtaking conventional open-pan reduction methods in Indonesian and Philippine processing facilities. Beverage manufacturers and organic food brands are adopting these syrups at accelerating rates to preserve heat-sensitive compounds for functional product claims. This technology is overtaking traditional methods by enabling processors to command organic and raw-food certifications that conventional heat treatment destroys.
REACH registration requirements for imported food contact substances are tightening documentation burdens on coconut syrup entering European Union markets. Manufacturers must now demonstrate full supply chain substance compliance from farm to final packaging. Organic and clean-label product lines face the steepest compliance costs, prompting some exporters to establish EU-based blending and repackaging operations.
Subscription-based procurement is displacing spot-market purchasing among North American specialty food retailers and direct-to-consumer brands. These buyers now commit to twelve-month supply contracts with Indonesian and Sri Lankan processors, replacing quarterly auction-based sourcing. This shift concentrates most visibly in the United States, where direct-to-consumer brands prioritize supply continuity over price arbitrage.
Coconut Syrup Market Segmentation
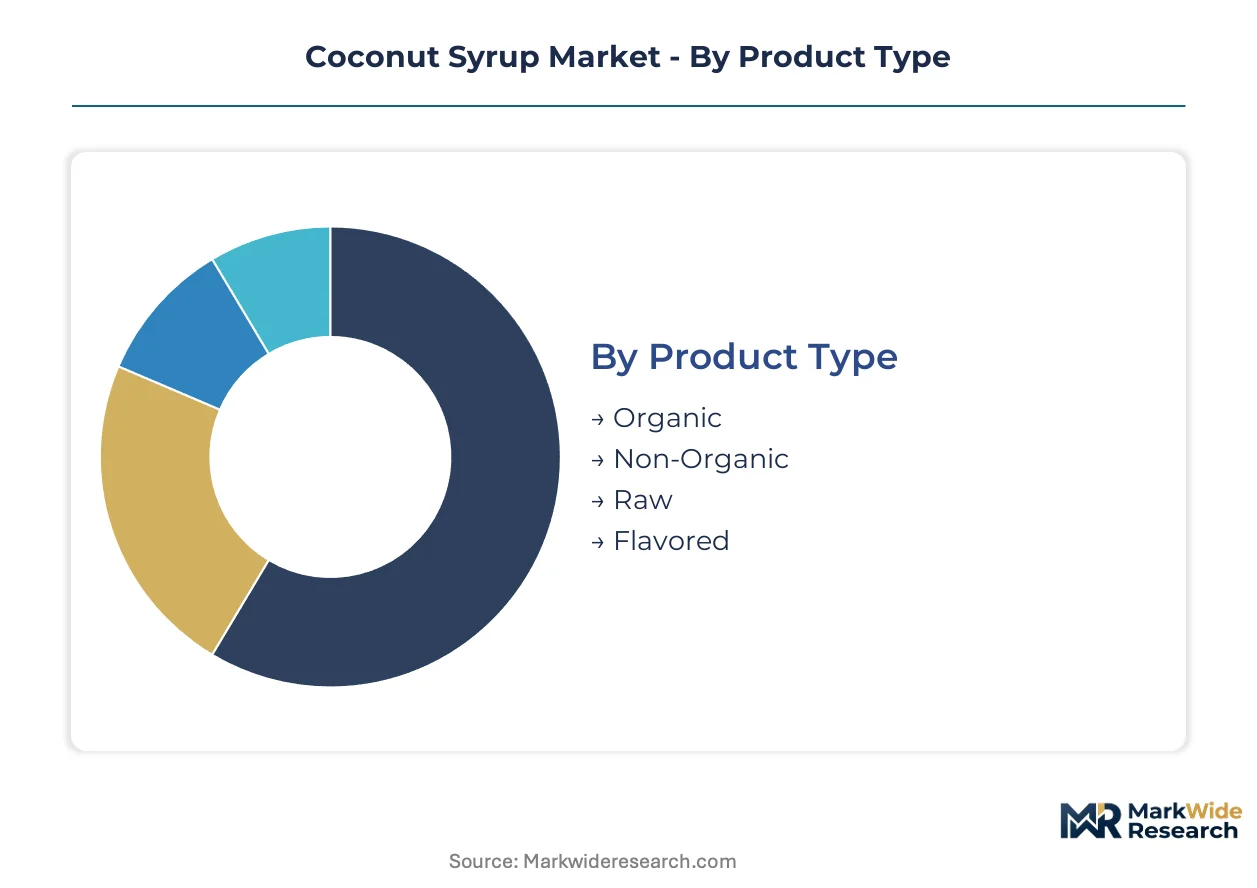
Coconut syrup segmentation reflects divergent buyer priorities across certification tiers, formulation requirements, and channel economics. Processors calibrate production lines to serve distinct demand profiles ranging from industrial-scale beverage reformulation to premium direct-to-consumer subscription models.
Product Type:
Buyers in this category separate cleanly by certification tolerance and thermal processing preferences, with price premiums scaling directly to compliance burden and enzymatic preservation claims.
- Organic:Derived from coconut palms cultivated without synthetic pesticides or fertilizers for three consecutive years under certifying body supervision. German and French retailers now mandate organic certification for shelf placement in dedicated natural food aisles, compressing conventional alternatives to perimeter displays. Organic commands the steepest price tier and tightest supply allocation among Indonesian and Philippine processors.
- Non-Organic:Conventional cultivation permits controlled agrochemical application, yielding lower farmgate costs and broader volume availability. Food manufacturers in Southeast Asia favor this tier for bakery and confectionery applications where certification adds no formulation value. Non-Organic leads volumes today; Organic is gaining share fastest.
- Raw:Processed exclusively through low-temperature vacuum evaporation below 45°C to preserve heat-sensitive enzymes and mineral complexes for functional food positioning.
- Flavored:Infused with vanilla, ginger, or botanical extracts targeting specialty beverage and home baking segments in North American direct-to-consumer channels.
Raw and Flavored variants capture incremental margin through processing differentiation rather than agricultural certification.
End User:
Volume concentration and margin capture diverge sharply between formulation-scale buyers and retail-channel intermediaries.
- Beverage Manufacturers:Craft soda and functional drink brands in the United States are replacing high-fructose corn syrup with coconut syrup to satisfy FDA sugar disclosure mandates while maintaining clean-label positioning. This segment demands consistent brix specifications and quarterly volume commitments that favor processors with captive Indonesian supply bases.
- Food Industry:Bakery and confectionery formulators across Southeast Asia substitute coconut syrup for refined cane sugar in regional product lines, prioritizing cost parity and supply continuity over certification premiums. Food Industry leads volumes today; Beverage Manufacturers is gaining share fastest.
- Retail Stores:Natural grocers and conventional supermarkets stock coconut syrup in baking aisles and natural sweetener sections, with placement determined by distributor relationships and slotting fee negotiations.
- Foodservice:Restaurants, cafes, and institutional kitchens incorporate coconut syrup into beverage programs and dessert formulations, purchasing through broadline distributors with irregular order patterns.
Foodservice procurement remains fragmented compared to the concentrated contract structures governing Beverage Manufacturer relationships.
Packaging Type:
Shelf-life requirements and handling economics shape format selection across ambient, chilled, and foodservice distribution pathways.
- Bottles:Glass and PET containers dominate retail shelf presence, with amber glass preferred for premium organic lines to prevent photochemical degradation of residual enzymes. Bottles leads volumes today; Pouches is gaining share fastest.
- Tetra Packs:Aseptic carton formats extend ambient shelf stability for foodservice and industrial bulk users with limited refrigeration infrastructure.
- Jars:Wide-mouth glass containers target home baking and spoonable applications where viscosity and pour control matter less than scoop accessibility.
- Pouches:Flexible stand-up bags with spout closures reduce shipping cube and material cost for direct-to-consumer subscription fulfillment.
Format innovation concentrates in Pouch development for e-commerce channels rather than retail-facing Bottle redesign.
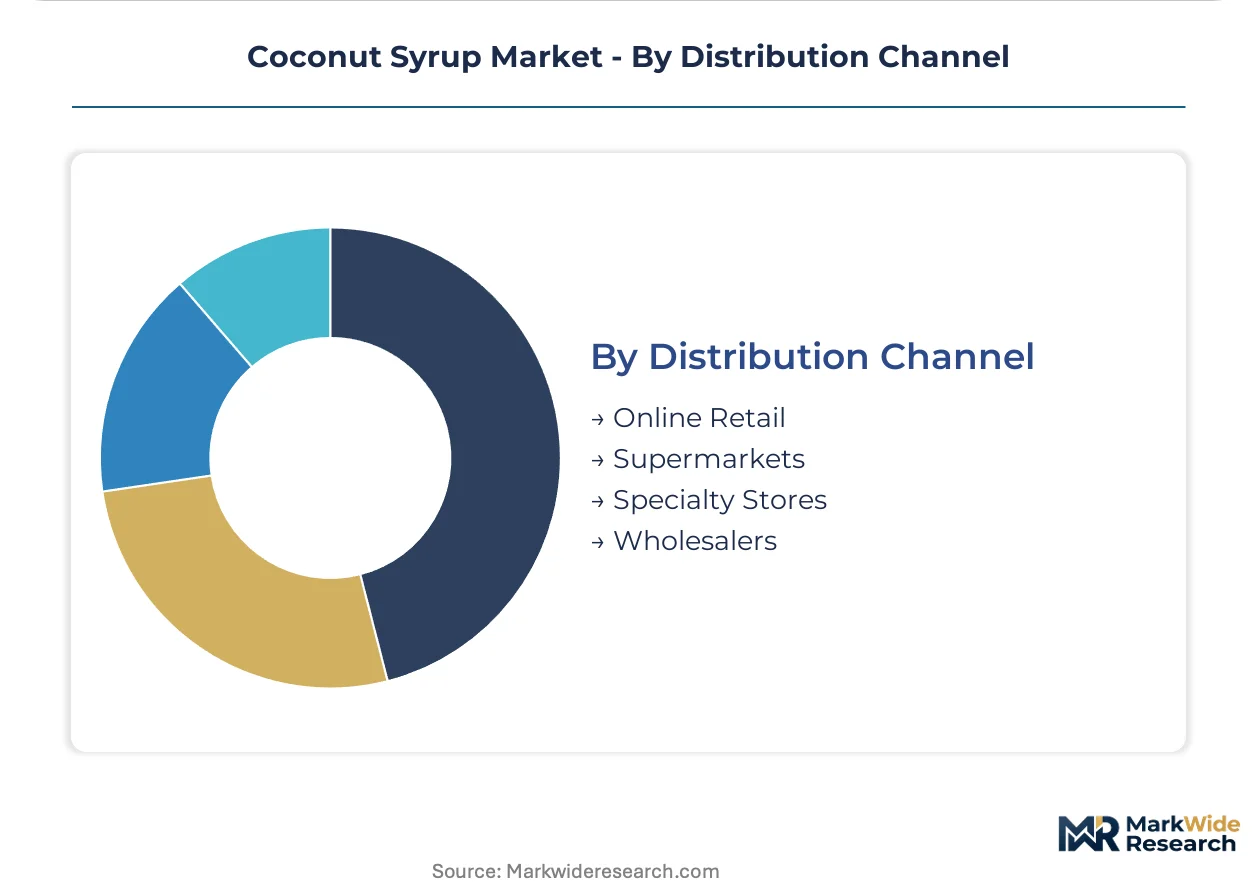
Distribution Channel:
Margin retention and customer data access separate channel strategies, with intermediation levels compressing proportionally to buyer scale.
- Online Retail:Direct-to-consumer subscription models bypass wholesale markups, capturing full retail margin and recurring revenue visibility for Indonesian and Sri Lankan processors. United States-based specialty brands prioritize twelve-month supply contracts through this channel over quarterly spot purchasing.
- Supermarkets:Conventional grocery chains demand promotional funding and category management support, concentrating volume among processors with established distributor relationships and working capital depth. Supermarkets leads volumes today; Online Retail is gaining share fastest.
- Specialty Stores:Independent natural grocers and regional chains curate premium organic assortments with higher per-unit margins and lower velocity requirements than mass retail.
- Wholesalers:Foodservice and industrial distributors aggregate fragmented demand from restaurants, bakeries, and small manufacturers, capturing margin through volume consolidation and logistics efficiency.
Wholesaler relationships remain essential for foodservice penetration despite their margin compression relative to direct Online Retail engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut syrup production originated in Southeast Asian archipelagos where coconut palm tapping traditions date back centuries. Industrial scaling began in Indonesia and the Philippines during the early organic certification waves of the 1990s. Today the industry spans producer nations with established tapping infrastructure and importer markets with stringent clean-label regulations.
Indonesia
Bali Nutra Ltd. controls integrated supply chains from Javanese coconut groves to processing facilities. The country's national food and drug regulator, BPOM, enforces halal certification requirements that shape export eligibility for Middle Eastern markets. Industrial clusters concentrate in Central Java and Bali provinces where cooperative tapping networks supply organic-certified sap to exporters.
Philippines
Quezon Province and Davao Region host the densest coconut palm concentrations for commercial syrup extraction. The Philippine Coconut Authority administers quality standards that govern both domestic trade and export documentation. Davao-based processors supply North American beverage manufacturers through long-term procurement contracts.
Sri Lanka
The Coconut Development Authority certifies organic groves in the Southern and North Western provinces for EU-bound shipments. Galle and Kurunegala districts maintain traditional tapping workforces that supply European organic traders. Processors here specialize in low-temperature vacuum evaporation for raw-food certification.
United States
FDA sugar disclosure mandates drive beverage reformulation toward single-ingredient natural sweeteners. Wholesome Sweeteners Inc. anchors retail presence through premium placement in Whole Foods Market locations. California and Pacific Northwest distribution hubs consolidate imports from Southeast Asian processors for national redistribution.
Netherlands
Rotterdam serves as the primary European entry point for organic coconut syrup shipments from ASEAN producers. EFSA clean-label guidance shapes importer documentation requirements for Dutch organic traders. Tradin Organic Agriculture B.V. leverages its Rotterdam logistics hub to distribute certified syrups across German and French retail channels.
Coconut Syrup Market Vendor Landscape
The competitive structure tilts toward integrated supply chain operators with captive Indonesian or Philippine sourcing. Market concentration remains moderate, with distinct tiers separating multinational organic traders from regional processors and direct-to-consumer specialists. Three archetypes dominate: plantation-integrated processors controlling raw sap access, certification-focused traders managing European distribution complexity, and subscription-oriented brands capturing North American retail premiums. Competitive moves center on backward integration into coconut palm groves and twelve-month supply contract negotiations with beverage manufacturers.
Among plantation-integrated processors, Bali Nutra Ltd. exemplifies the archetype of supply chain control from farm to facility. Tradin Organic Agriculture B.V. and Wholesome Sweeteners Inc. represent divergent distribution strategies—European wholesale channel dominance versus North American retail shelf positioning. These three companies anchor the competitive landscape without exhausting its structural variety.
| Leading Market Players |
|---|
| Bali Nutra Ltd. |
| Tradin Organic Agriculture B.V. |
| Wholesome Sweeteners Inc. |
| Coconut Secret |
| Coconut Merchant Ltd. |
| Big Tree Farms |
| Benevelle Corporation |
| Treelife |
| Madhava Natural Sweeteners |
| Others |
Supply Flow & Price Mechanics
Raw sap collection labor costs in Indonesian and Philippine tapping networks cascade through three distinct pricing tiers before reaching end buyers. Farmgate wages for skilled climbers in Central Java and Quezon Province set floor pricing for organic certification tiers, while vacuum evaporation energy inputs separate raw-food premiums from conventional heat-processed alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs coconut syrup transactions. Certification grade and volume scale drive price differentiation, with organic raw variants commanding shelf-positioning premiums over conventional non-organic bulk. Pricing pressure stems from date syrup and agave nectar substitution in European clean-label channels. Beverage manufacturers exhibit highest price sensitivity due to reformulation cost targets, while direct-to-consumer subscription buyers accept premium positioning for supply continuity.
Supply Chain Analysis
Regional distribution centers in Rotterdam and California consolidate hub-and-spoke patterns for European and North American delivery. Indonesia, the Philippines, and Sri Lanka anchor upstream supply concentration. Fresh coconut sap, amber glass packaging, and organic certification documentation feed downstream dependencies. Single-source vulnerability concentrates in aging tapper workforces across Kerala and Java. Distribution runs through organic trader networks for retail placement and direct-to-consumer fulfillment for subscription retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in coconut syrup hinges on low-temperature processing premiums displacing conventional heat-treated volumes. Energy-efficient vacuum evaporation investments compress unit costs while preserving enzymatic positioning for functional beverage claims.
For Market Incumbents: Deploy backward integration into Javanese and Quezon coconut groves to secure captive sap access against skilled tapper scarcity. Lock twelve-month procurement contracts with U.S. beverage manufacturers before date syrup substitution accelerates. Prioritize organic certification maintenance for EU shelf-access retention. For New Entrants and Emerging Players: Begin with direct-to-consumer subscription models in North American specialty food channels where incumbent distributor relationships remain underdeveloped. Target flavored variant white space for home baking segments. Pursue raw-food certification positioning to bypass commodity pricing in conventional sweetener tiers. For Investors and Strategic Acquirers: Consolidation pressure builds where plantation-integrated processors lack European distribution infrastructure. Five-to-ten-year viability favors operators with captive Indonesian supply bases and Rotterdam logistics access. Monitor ASEAN organic equivalence agreement progress as inflection signal for certification cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Groves | Captive sap sourcing in Central Java mitigates perishability risk and tapper scarcity. |
| Low-Temperature Vacuum Evaporation Scale-Up | Energy-efficient processing preserves enzymatic content for raw-food certification premiums. |
| Direct-to-Consumer Subscription Launch | Twelve-month contracts bypass wholesale markups and capture recurring revenue visibility. |
| EU Organic Certification Investment | BPOM and Coconut Authority alignment with EFSA standards secures Rotterdam distribution access. |
| Functional Beverage Partnership | Kombucha and adaptogenic brand collaborations open premium positioning above commodity sweeteners. |
Methodological Framework
Coverage spans Southeast Asian producer nations and North American and European importer markets, with primary inputs from each. The analysis combines interviews with coconut syrup processors, organic certification auditors, beverage manufacturer procurement leads, and natural grocer category buyers with secondary validation from BPOM quality standards, Philippine Coconut Authority documentation, FDA labeling requirements, and EFSA clean-label guidance. Bottom-up volume modeling and top-down value triangulation anchor market sizing.
Granularity-level modeling disaggregates volume and value across certification tier, thermal processing method, end-user segment, packaging format, and distribution channel throughout the forecast period. CAGRs derive from segment-level growth trajectory analysis calibrated against historical organic sweetener adoption patterns and beverage reformulation pipeline visibility. Raw sap yield volatility and organic conversion timeline constraints inform scenario-weighted projections.
Several conditions sit outside the modeled scope, including extreme weather disruption scenarios in the Bay of Bengal and South China Sea regions, abrupt shifts in EU organic equivalence recognition, and breakthrough processing technologies that eliminate enzymatic degradation. Forecasts reflect documented assumptions around tapping workforce stability and certification body capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Australia Vanilla Flavor Market