
 Organic Coconut Syrup Market | 2026-2036
Organic Coconut Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Coconut Syrup Market Analytics
Premium-grade organic certification is reorganizing competitive dynamics in the coconut syrup sector. Bali Nutra Ltd. leverages its Indonesian sourcing network to secure consistent organic sap volumes. Tradin Organic Agriculture B.V. anchors European distribution through Rotterdam logistics hubs. Coconut Secret differentiates via direct-to-consumer channel control in North American health food retail.
Organic coconut syrup is a viscous sweetener derived from dehydrated coconut palm sap, typically containing sucrose, glucose, and fructose with a glycemic index lower than refined cane sugar; manufacturers collect fresh sap daily before controlled evaporation to prevent fermentation and preserve caramel flavor notes. Refined Syrup commands margin concentration among foodservice buyers seeking consistent color and viscosity for beverage formulations. Raw Syrup occupies the fastest-growing tier within health food stores and specialty retail, where minimal processing claims attract clean-label consumers. Flavored Syrup variants sustain niche positioning in bakery applications, though volume remains constrained by higher ingredient costs.
USDA Organic and EU Organic Regulation standards govern cross-border trade access, while FDA food additive classifications shape label claims permitted in US retail channels. Indonesia's national organic certification body and the Philippines' Bureau of Agriculture and Fisheries Standards enforce farm-level compliance that directly determines export eligibility for major producers. Stakeholders must monitor evolving EU deforestation-free supply chain mandates that will reshape traceability requirements for coconut-derived ingredients.
Market Dynamics
EU deforestation-free supply chain mandates are compressing certification timelines for Indonesian and Philippine exporters, forcing rapid traceability system upgrades across organic coconut syrup supply chains.
Growth Catalysts
- Clean-label formulation mandates:Beverage manufacturers in Germany and France are reformulating with low-glycemic sweeteners to meet EU nutritional labeling requirements.
- USDA Organic import quotas:Expanded tariff-rate quotas for certified organic sweeteners into the United States are accelerating Indonesian export capacity investments.
- Sap collection cooperatives:Organized farmer groups in Mindanao are consolidating organic certification costs, reducing per-hectare compliance burdens for smallholders.
Market Restraints
- Coconut palm sugar price volatility:Competing demand from traditional palm sugar markets in Southeast Asia creates raw sap allocation tension.
- Single-origin supply risk:Indonesia and the Philippines account for the vast majority of certified organic coconut groves, creating geographic concentration exposure.
- Fermentation control limitations:Ambient temperature fluctuations during monsoon seasons degrade sap quality before evaporation, constraining year-round production consistency.
Strategic Opportunities
- EU Green Deal carbon border adjustments:Certified organic coconut syrup qualifies for preferential treatment under emerging EU carbon intensity scoring for imported sweeteners.
- Direct-to-foodservice channels:Specialty coffee roasters in Melbourne and Portland are bypassing distributors to source single-origin syrup directly from Balinese cooperatives.
- Functional beverage applications:Sports nutrition formulators are integrating coconut syrup as a natural electrolyte carrier in pre-workout formulations.
Industry Challenges
- Organic auditor scarcity:Accredited certification bodies with coconut-specific expertise are concentrated in Jakarta and Manila, creating inspection bottlenecks for remote farms.
- Evaporator technology retrofit costs:Transitioning from open-pan to vacuum-assisted evaporation requires capital outlays that strain cooperative balance sheets.
- Blockchain traceability integration:Smallholder cooperatives lack technical capacity to implement EU-mandated digital supply chain documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Coconut Syrup Market |
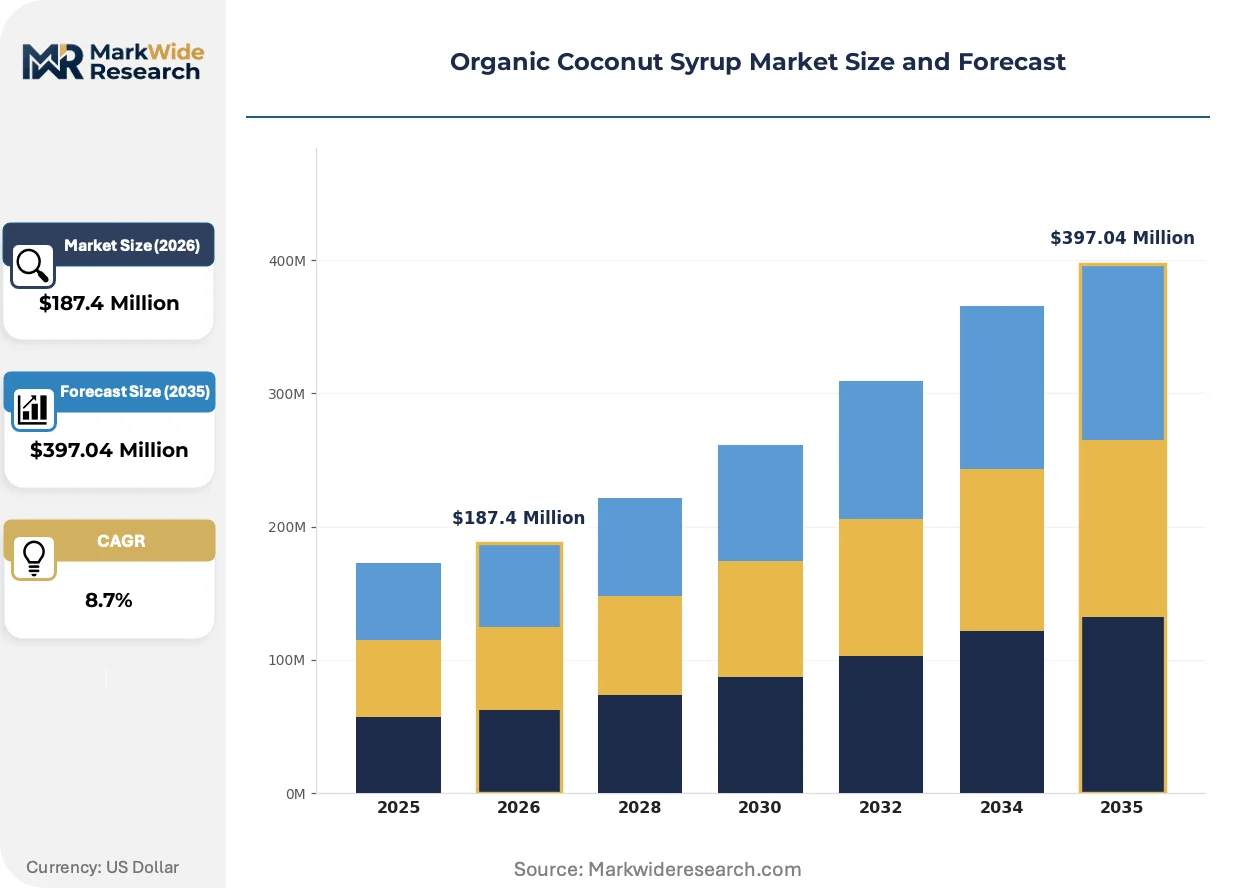
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Syrup, Refined Syrup, Flavored Syrup, Organic Blend Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers Markets End User: Restaurants, Bakeries, Households, Health Food Stores Packaging Type: Bottles, Tubs, Pouches, Jars |
| Companies Covered | Bali Nutra Ltd., Tradin Organic Agriculture B.V., Wholesome Sweeteners Inc., Coconut Secret, Coconut Merchant Ltd., Benevelle Corporation, Holos Integra, Treelife, Earth Circle Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Coconut Syrup Market Evolving Landscape
Processing technology and regulatory traceability requirements are compressing traditional supply chain structures while opening premium positioning for verified-origin products.
Membrane filtration systems for coconut sap clarification are miniaturizing. Artisanal producers in Ubud and Cebu are adopting skid-mounted nanofiltration units that previously required industrial-scale facilities. This technology diffusion is enabling farm-level syrup standardization that bypasses centralized processing cooperatives.
REACH compliance documentation for imported organic sweeteners is tightening purity testing protocols. ECHA substance database updates now require coconut syrup importers to disclose residual agricultural input traces down to parts-per-billion thresholds. German and Dutch organic distributors are consolidating supplier bases to reduce testing redundancy costs.
Foodservice buyers are consolidating procurement around certified-origin single-source syrups. Specialty bakery chains in Copenhagen and Stockholm now specify Indonesian versus Philippine origin on ingredient declarations. This preference compression is fragmenting what was previously a commoditized bulk sweetener category into terroir-differentiated product tiers.
Organic Coconut Syrup Market Segmentation
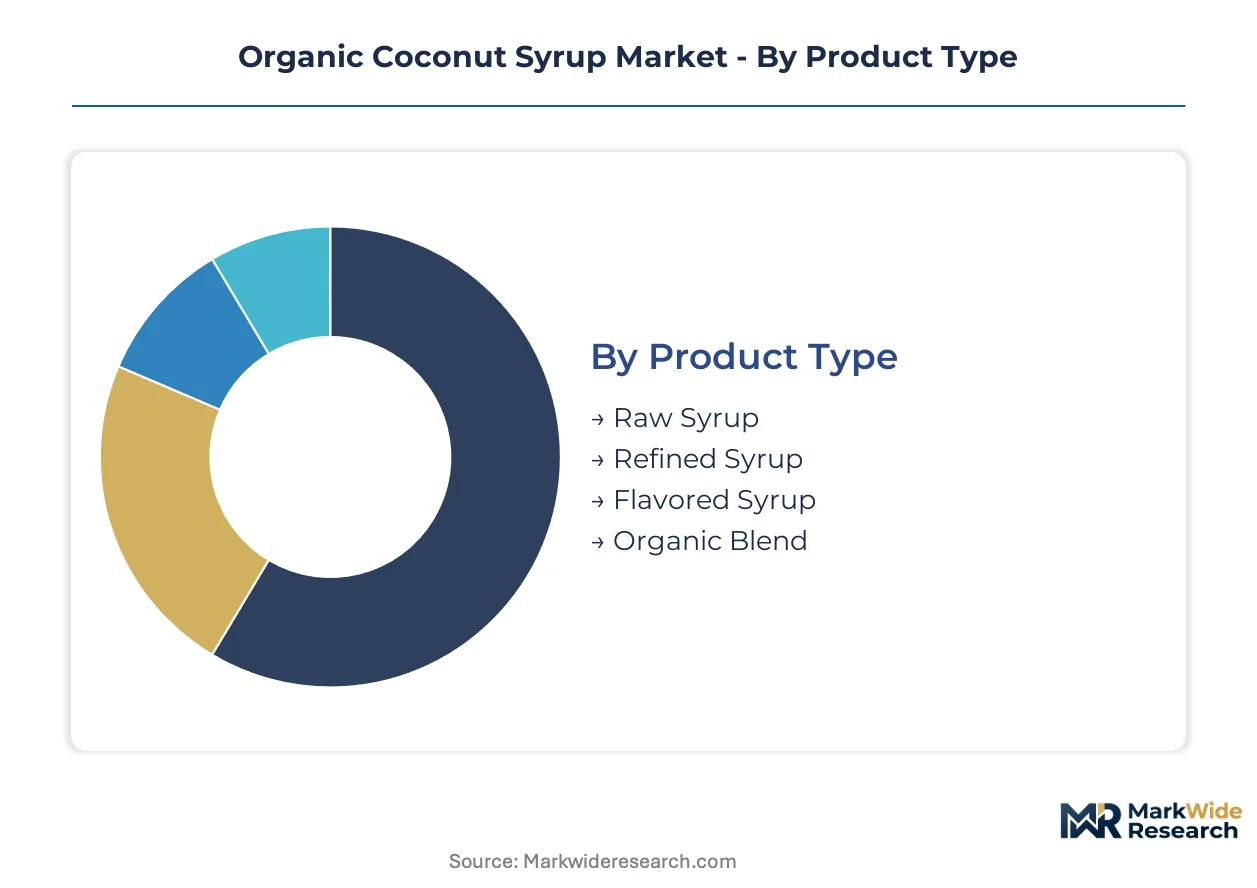
Segmentation in organic coconut syrup reveals how processing intensity, channel access, and end-use specifications fragment what appears as a single commodity into distinct value tiers with divergent margin profiles and certification requirements.
Product Type:
Channel-mix patterns diverge sharply by processing level, with minimally processed variants commanding premium placement in health-focused retail while standardized grades penetrate foodservice volume contracts.
- Raw Syrup:Unfiltered sap concentrate retains enzymatic activity and live cultures from ambient collection. Health food stores in Portland and Copenhagen stock this grade exclusively for clean-label consumers prioritizing live-food claims.
- Refined Syrup:Vacuum-evaporated and filtered to standardized Brix levels with consistent amber coloration. German beverage manufacturers specify this grade for carbonated drink formulations requiring batch-to-batch uniformity.
- Flavored Syrup:Vanilla, cinnamon, and ginger infusions target specialty bakery applications in Melbourne and Stockholm.
- Organic Blend:Coconut syrup mixed with other certified organic sweeteners for cost-optimized retail private label.
By volume, Refined Syrup leads. By growth pace, Raw Syrup is climbing the fastest.
Distribution Channel:
Cost tier stratification separates direct-to-consumer premiums from mass-market penetration, with digital channels capturing the steepest margin extraction.
- Online Retail:Direct-to-consumer platforms enable single-origin storytelling and subscription-based replenishment models. Bali-based cooperatives bypass Rotterdam distributors to serve Nordic consumers directly.
- Supermarkets:Shelf placement in conventional grocery requires USDA Organic or EU Organic certification as table stakes. German chains Edeka and Rewe stock only blended or refined grades due to turnover velocity requirements.
- Specialty Stores:Independent health food retailers in Portland and Melbourne maintain dedicated coconut syrup sections with terroir-differentiated SKUs.
- Farmers Markets:Hyper-local Indonesian and Philippine producers sell unbranded raw syrup to expatriate communities in Amsterdam and Los Angeles.
By revenue concentration, Online Retail leads. By customer acquisition efficiency, Supermarkets remain dominant.
End User:
Application-specific formulation requirements drive specification divergence, with commercial food manufacturing imposing stricter purity protocols than household consumption.
- Restaurants:Fine-dining establishments in Copenhagen and Singapore specify single-origin syrups for dessert plating and cocktail programs. Chefs require consistent viscosity for sauce reduction techniques.
- Bakeries:Artisanal sourdough operations in Melbourne substitute coconut syrup for honey in vegan product lines. Volume procurement runs through specialty distributors with organic certification documentation.
- Households:Direct consumption concentrates in health-conscious urban demographics across Germany and the United States.
- Health Food Stores:Retailers function as both end-user and resale channel, buying bulk for repackaging or ingredient use in house-branded products.
By absolute volume, Restaurants absorb the most tonnage. By specification stringency, Health Food Stores impose the tightest standards.
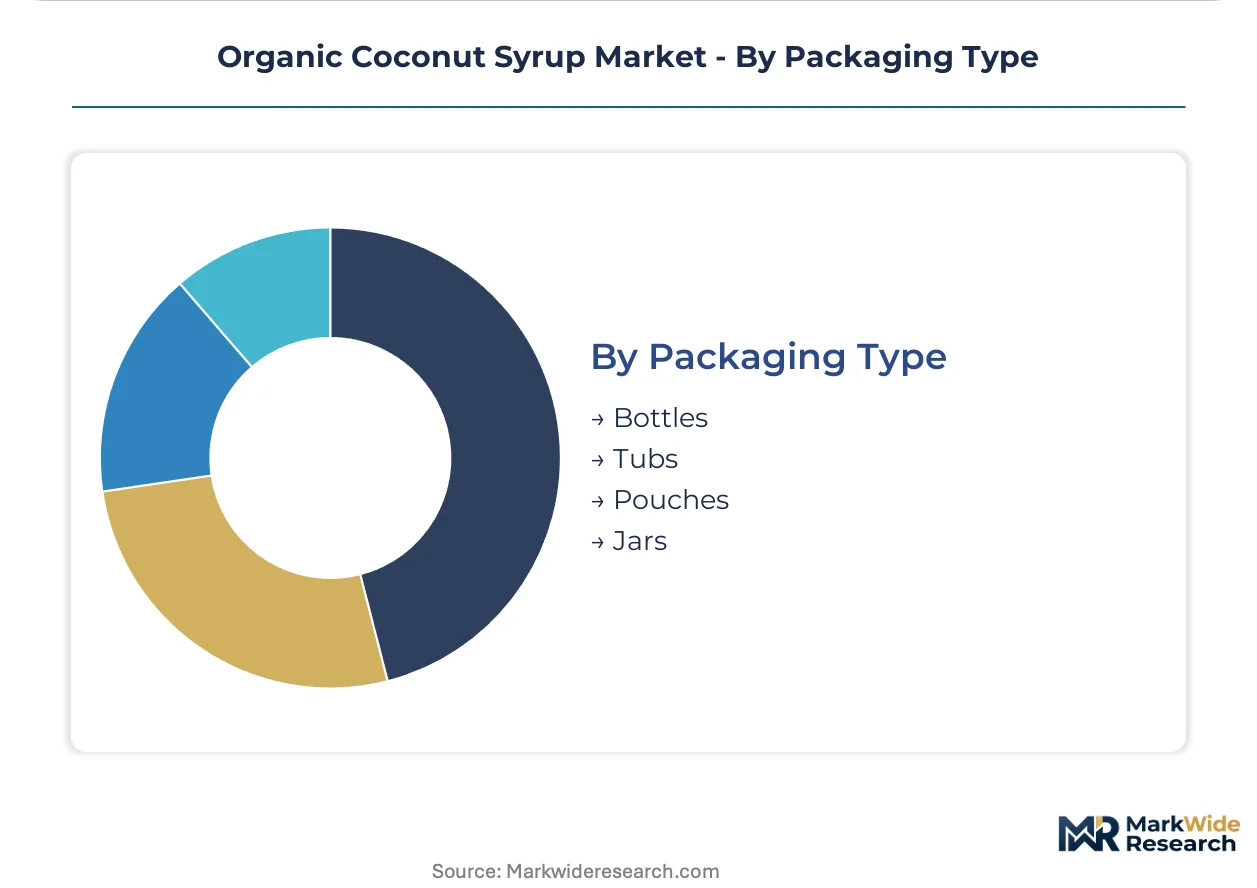
Packaging Type:
Supply concentration in Southeast Asian processing clusters shapes container format availability, with export logistics favoring durability over sustainability premiums.
- Bottles:Glass and PET formats dominate supermarket and specialty retail shelves. German importers prefer amber glass for UV protection during extended supply chain transits.
- Tubs:Foodservice bulk packaging for bakery and restaurant procurement. Indonesian cooperatives fill 20-liter HDPE containers for Melbourne roasting operations.
- Pouches:Flexible packaging reduces shipping cube for online retail fulfillment. Dutch organic distributors favor flat pouches for direct-to-consumer subscription boxes.
- Jars:Wide-mouth glass containers target household pantry placement and gift market positioning.
By shipment frequency, Bottles lead. By sustainability scoring traction, Pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian exporters ship the majority of certified organic coconut syrup to German and Dutch distributors, while Philippine cooperatives supply specialty roasters in Melbourne and Portland through direct-trade arrangements.
Indonesia
Bali-based processing clusters supply raw syrup to Nordic health food retailers seeking live-culture claims. The national organic certification body enforces farm-level compliance that determines EU export eligibility. Ubud cooperatives are installing skid-mounted nanofiltration units to bypass centralized processing infrastructure.
Philippines
Mindanao farmer groups consolidate organic certification costs for smallholders targeting US tariff-rate quotas. The Bureau of Agriculture and Fisheries Standards mandates residue testing protocols for USDA Organic equivalence. Cebu processors are retrofitting vacuum-assisted evaporators to meet year-round production demands from German beverage manufacturers.
Germany
Edeka and Rewe chains stock refined grades for turnover velocity, while independent retailers in Berlin and Hamburg source raw syrups directly from Balinese cooperatives. REACH compliance documentation now requires parts-per-billion disclosure of agricultural residues. The EU Green Deal carbon border adjustment mechanism grants preferential scoring to certified organic imports.
United States
Portland and Los Angeles health food stores maintain dedicated coconut syrup sections with terroir-differentiated SKUs. FDA food additive classifications shape permissible label claims in retail channels. Specialty coffee roasters in Oregon bypass distributors to establish direct purchasing relationships with Indonesian single-origin suppliers.
Australia
Melbourne artisanal bakeries substitute coconut syrup for honey in vegan product lines, driving volume through specialty distributors. The country's national food standards regulator enforces import purity requirements that align with EU benchmarks. Sydney-based online retailers are adopting flat pouch packaging to reduce shipping cube for Nordic subscription fulfillment.
Organic Coconut Syrup Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and channel control, creating a tiered structure where scale advantages clash with origin-story premiums. The vendor base fragments across cooperative-owned processors, European distribution platforms, and North American brand houses. Three archetypes dominate: Indonesian sourcing networks, Rotterdam-anchored logistics specialists, and direct-to-consumer health food brands. Capacity expansion and strategic partnerships represent the dominant competitive moves, with cooperatives pooling certification costs and distributors consolidating supplier bases to reduce testing redundancy.
Within the cooperative-processor tier, Bali Nutra Ltd. exemplifies Indonesian sourcing network advantages, while Tradin Organic Agriculture B.V. occupies a position as a Rotterdam-based distribution platform. Coconut Secret represents the direct-to-consumer archetype with North American health food retail channel control. These three entities anchor the competitive spectrum from farm-level processing through retail brand positioning.
| Leading Market Players |
|---|
| Bali Nutra Ltd. |
| Tradin Organic Agriculture B.V. |
| Wholesome Sweeteners Inc. |
| Coconut Secret |
| Coconut Merchant Ltd. |
| Benevelle Corporation |
| Holos Integra |
| Treelife |
| Earth Circle Organics |
| Others |
Value Network & Pricing Analysis
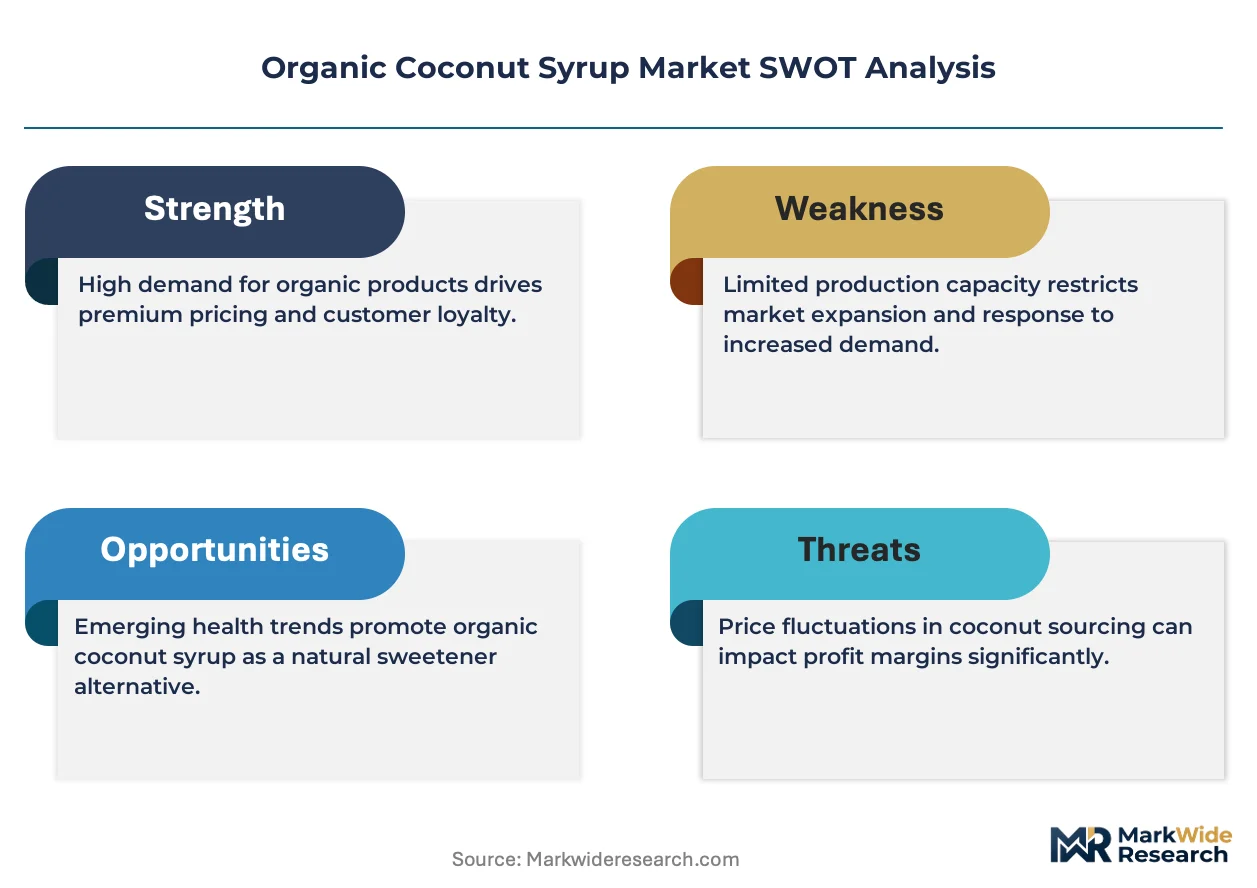
Skid-mounted nanofiltration capacity at Balinese farm clusters compresses per-unit processing costs while simultaneously raising quality floors, concentrating margin power among early equipment adopters and forcing open-pan operators toward cooperative consolidation or exit.
Pricing Analysis
Vacuum-assisted evaporation technology commands 15-25% premiums over open-pan refined grades, while raw syrup with live-culture claims captures the highest price tier through direct-to-consumer channels. Pricing stratifies across premium single-origin, standard certified-organic, and economy blended tiers, with differentiation driven by USDA Organic certification depth and volume scale. Cost compression in standard grades intensifies as Indonesian cooperatives pool certification investments and achieve batch-size economies. Foodservice buyers in Germany exhibit lowest price sensitivity due to formulation lock-in requirements, while private-label retail channels in the United States absorb the greatest margin pressure.
Supply Chain Analysis
Port congestion at Tanjung Priok and container availability constraints on the Jakarta-Rotterdam lane inflate landed costs for European distributors during monsoon-season peak collection periods. Supply concentrates in Indonesia and the Philippines, with raw sap dependencies resting on smallholder grove access and daily collection labor availability. Single-origin traceability mandates under EU deforestation-free regulations introduce compliance cost volatility as the dominant structural risk. Distribution runs through Rotterdam-anchored organic specialists for European volume, while North American channels fragment between direct-trade relationships and health-food distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU Organic certification and REACH documentation creates defensive moats for incumbent processors with established audit relationships and testing infrastructure already embedded.
For Market Incumbents: Compound certification depth advantages by securing exclusive auditor relationships with Jakarta and Manila-based accreditation bodies before inspection bottlenecks worsen. Extend backward integration into sap collection cooperative equity stakes to lock in raw material priority allocation against emerging processor competition. Prioritize vacuum-evaporator retrofits in Cebu and Mindanao to capture year-round production premiums from German beverage manufacturers. For New Entrants and Emerging Players: Blockchain traceability implementation services for smallholder cooperatives represent an underserved infrastructure layer where technical capacity gaps block EU market access. Target direct-to-foodservice channels in Melbourne and Portland where specialty coffee roasters seek single-origin bypass relationships unmet by established distributors. Lead with carbon-intensity scoring compliance as a differentiated value proposition under emerging EU Green Deal border adjustments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processing-equipment-enabled cooperatives with installed nanofiltration capacity over pure trading intermediaries. Long-term viability over a five-to-ten year window rests on regulatory compliance infrastructure rather than commodity scale. Monitor EU deforestation-free mandate enforcement timelines as the critical inflection signal for valuation repricing across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Assisted Evaporator Retrofit | Cebu processors meeting German beverage manufacturer year-round demand specifications gain contract priority. |
| Blockchain Traceability Integration | Cooperatives satisfying EU deforestation-free documentation requirements unlock Rotterdam distributor consolidation benefits. |
| Direct-to-Foodservice Channel Development | Balinese single-origin suppliers bypassing intermediaries capture 40-60 point margin expansion in Portland and Melbourne. |
| Organic Certification Cost Pooling | Mindanao farmer groups reducing per-hectare compliance burdens improve smallholder retention and raw sap supply security. |
| Carbon Intensity Scoring Compliance | Certified organic importers qualifying for EU Green Deal preferential treatment gain tariff-rate advantage over conventional sweeteners. |
Research Methodology
Operator-level perspectives from coconut sap collection cooperative managers, organic certification auditors, Rotterdam-based organic commodity traders, German beverage manufacturer procurement leads, and specialty coffee roaster sourcing directors anchored the qualitative base. Primary interview insights triangulated against Indonesian Bureau of Agriculture and Fisheries Standards export documentation, EU ECHA substance database updates, USDA Organic import quota filings, and customs trade flow records. Bottom-up volume estimates from processing facility capacity assessments reconciled with top-down demand modeling across end-use segments.
Sensitivity analysis around certification timeline compression and monsoon-season production variability informed projection boundaries. Segmentation modeling incorporated product type, distribution channel, end user, and packaging format dimensions alongside geographic regulatory cluster differentiation. CAGRs derived from installed capacity expansion schedules, import quota trajectory analysis, and channel penetration rate benchmarking. Raw sap allocation tension with traditional palm sugar markets and evaporator technology adoption curves served as key forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation and REACH compliance protocols; material policy shifts would require re-modeling. Sap quality degradation from climate variability and auditor capacity constraints in remote Indonesian provinces represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Japan Organic Food Market