
 Australia Vanilla Flavor Market | 2026-2036
Australia Vanilla Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Vanilla Flavor Market Insights
The capability gap between integrated extract processors and commodity blenders is collapsing as extraction technology standardizes. Givaudan SA leverages its captive Madagascar bean sourcing to sustain premium positioning across Australian dairy accounts. Kerry Group competes through liquid flavor system specialization, anchoring its Melbourne technical center to local beverage formulation demand.
Australia vanilla flavor encompasses aromatic compounds derived from cured Vanilla planifolia or Vanilla tahitensis pods, typically standardized at 1-4% vanillin content by weight for commercial food-grade applications. These formulations serve primarily as taste-masking and flavor-consistent agents across heat-processed and cold-filled food matrices. Natural extract formulations command margin premiums in bakery applications where clean-label positioning drives procurement decisions, while liquid concentrates dominate beverages due to dosing precision and dissolution kinetics. Powder formats retain share in confectionery where moisture control governs shelf stability.
FSANZ administers maximum residue limits and labeling thresholds that determine natural versus artificial classification claims on Australian retail packaging. The country's national pharmaceutical regulator, TGA, intersects with this market through therapeutic goods containing vanilla-derived excipients. Food manufacturers must navigate parallel compliance with ISO 22000 certification requirements and state-level dairy processing codes enforced by Dairy Food Safety Victoria. Stakeholders should monitor extraction technology cost curves and bean origin diversification strategies as determinants of sustainable supply security.
Market Dynamics
FSANZ reformulation mandates and Madagascar bean supply concentration are compressing formulation flexibility for Australian food manufacturers while extraction technology standardization erodes processor capability premiums.
Growth Catalysts
- Artisan dairy expansion:Premium ice cream manufacturers in Victoria and New South Wales are scaling natural extract procurement for clean-label positioning in gelato and cultured dairy segments.
- ISO 22000 certification pathways:Third-party food safety validation is unlocking export-ready production capacity for Australian flavor houses targeting Asian confectionery accounts.
- Cold-fill beverage precision dosing:Liquid concentrate formats are capturing share in functional drink applications where dissolution kinetics and batch consistency govern supplier selection.
Market Restraints
- Madagascar bean dependency:Over 80% of global vanilla bean supply concentrates in a single origin, exposing Australian processors to cyclone-induced harvest volatility and price spikes.
- Natural-artificial classification friction:FSANZ labeling thresholds create procurement rigidity, forcing reformulation costs when vanillin content thresholds shift between extract and flavoring categories.
- Synthetic biology substitution pressure:Fermentation-derived vanillin from engineered yeast strains is achieving cost parity with natural extracts in bakery applications.
Strategic Opportunities
- Papua New Guinea origin diversification:Near-shore bean sourcing from Pacific island cooperatives offers freight cost advantages and shorter supply chains for Melbourne-based processors.
- Therapeutic goods crossover:TGA-registered excipient applications in pharmaceutical coatings represent an adjacent revenue stream with higher margin retention than commodity food-grade sales.
- Blockchain traceability integration:Immutable origin documentation is commanding procurement preference from export-oriented confectionery brands requiring deforestation-free supply chain verification.
Industry Challenges
- Flavor chemist talent scarcity:Specialized extraction process engineering expertise is concentrating at multinational technical centers, constraining domestic mid-tier processor R&D capacity.
- Dairy Food Safety Victoria audit compression:State-level dairy processing code recertification timelines are extending 40% due to inspector capacity constraints, delaying new product launches.
- Legacy powder-to-liquid line conversion:Capital equipment retrofit requirements for concentrate manufacturing are straining mid-cap processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Vanilla Flavor Market |
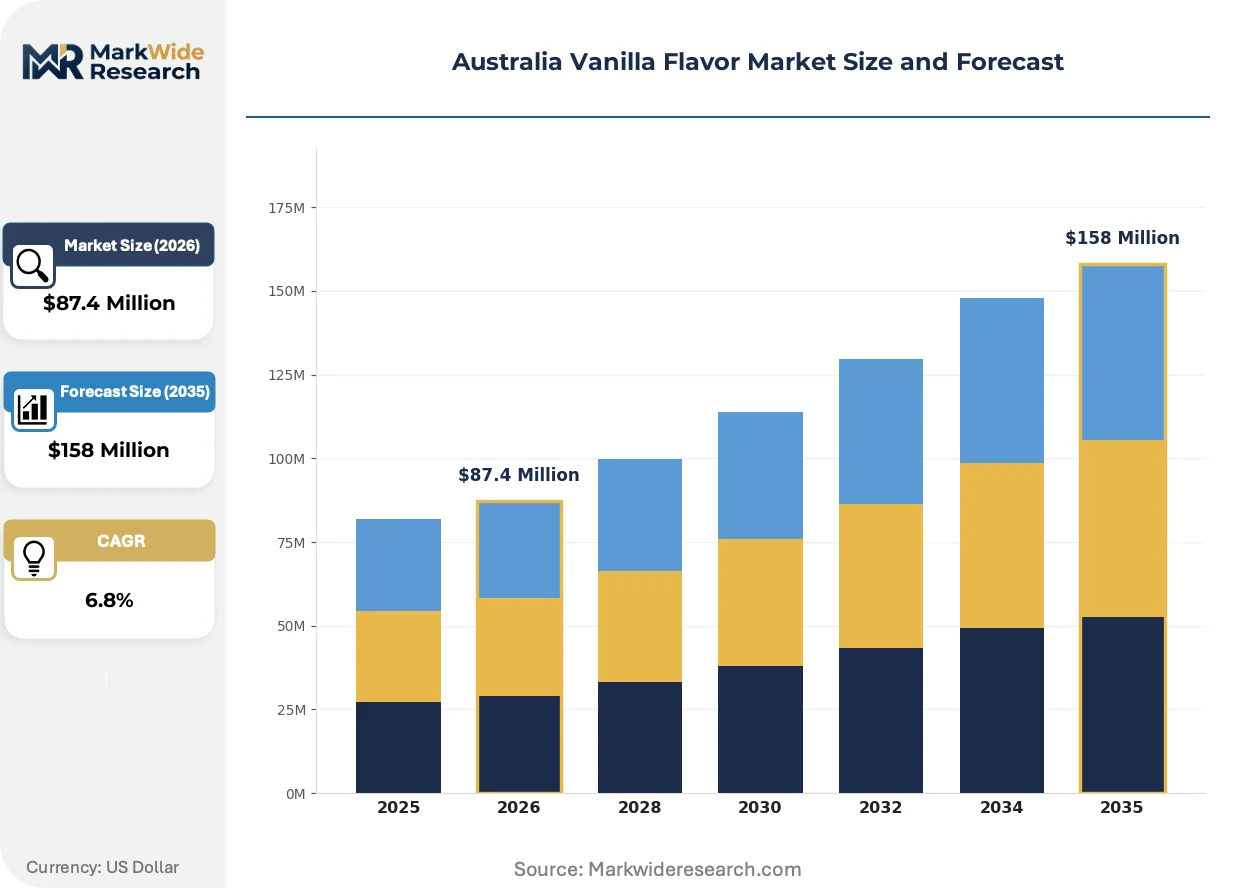
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Artificial, Organic, Extract Application: Beverages, Bakery, Confectionery, Dairy Form: Liquid, Powder, Paste, Granule End User: Food Manufacturers, Retailers, Restaurants, Households |
| Companies Covered | Givaudan SA, Symrise AG, Nielsen-Massey Vanillas, Inc., Scentral Flavours and Fragrances, Dr. Oetker Group, Solvay SA, International Flavors & Fragrances, Kerry Group, Firmenich SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Vanilla Flavor Market Trends and Innovations
Extraction technology maturation and regulatory precision are fragmenting competitive positioning across natural, nature-identical, and synthetic vanillin supply tiers.
Supercritical CO2 extraction is bifurcating the premium segment from conventional solvent-based processing. Artisan chocolate manufacturers in Tasmania and South Australia are adopting CO2-derived extracts for terpene preservation and clean-label claims. This technology is compressing the margin premium previously commanded by traditional Bourbon-Madagascar cured bean extracts.
FSANZ is tightening maximum residue limits for solvent residues in natural flavor declarations, effective across all Australian retail packaging from 2025. This regulatory compression is forcing solvent-based processors to invest in purification infrastructure or pivot to CO2 extraction partnerships. Bakery and confectionery segments with high clean-label exposure are accelerating supplier qualification audits to preempt compliance gaps.
Direct procurement contracts between Victorian dairy processors and Pacific island cooperatives are displacing traditional broker-mediated bean sourcing. These bilateral arrangements reduce price volatility exposure while enabling customized curing protocols for specific flavor profiles. The shift is most visible in Melbourne's food manufacturing corridor, where technical centers are embedding origin-specific quality specifications into master service agreements.
Australia Vanilla Flavor Market Segmentation
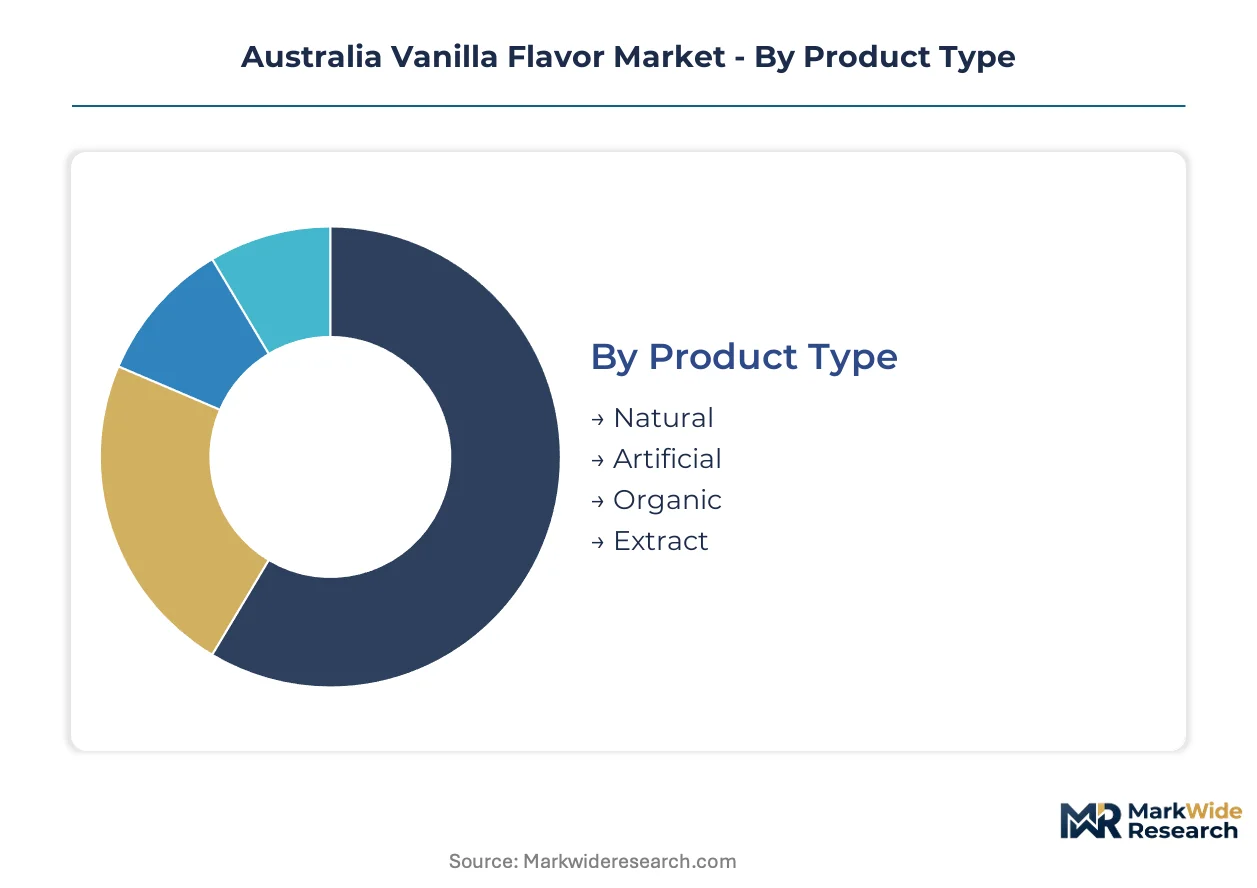
Vanilla flavor procurement in Australia fragments across regulatory thresholds that determine natural versus artificial classification claims. FSANZ labeling mandates reshape sourcing strategies differently across product tiers, application matrices, and end-user compliance requirements.
Product Type:
FSANZ maximum residue limits and vanillin content thresholds create distinct procurement categories with divergent compliance burdens and margin structures.
- Natural:Derived from cured Vanilla planifolia or Vanilla tahitensis pods with standardized vanillin content. Artisan dairy manufacturers in Victoria's food processing corridor prioritize this tier for clean-label positioning in premium gelato and cultured dairy segments.
- Extract:Concentrated alcoholic solutions standardized at 1-4% vanillin by weight. Bakery applications concentrate demand here as FSANZ labeling rules permit direct "natural flavor" claims without artificial classification triggers.
- Artificial:Synthetically produced vanillin or ethyl vanillin compounds. Cost-sensitive confectionery manufacturers leverage this tier where heat processing masks origin differentiation and label claims carry less consumer weight.
- Organic:Certified organic bean sourcing with full traceability documentation. Export-oriented brands targeting Asian markets command procurement preference here for deforestation-free supply chain verification.
Established volume favors Extract; emerging adoption favors Organic.
Application:
Heat-processed versus cold-filled matrices impose divergent stability requirements that determine format selection and supplier qualification criteria.
- Dairy:Premium ice cream and cultured product manufacturers anchor demand in Melbourne's manufacturing base. Cold-fill processing precision requirements favor liquid concentrate formats with controlled dissolution kinetics.
- Bakery:Heat-processed applications tolerate broader format flexibility. Moisture control and Maillard reaction compatibility govern procurement decisions across industrial and artisan production scales.
- Beverages:Functional drink formulations require precise dosing and rapid dissolution. Liquid concentrates capture share here as batch consistency requirements exceed tolerance for powder reconstitution variance.
- Confectionery:Shelf stability imperatives favor powder and granule formats with low water activity. Melbourne-based processors supply this segment through ISO 22000-certified production lines targeting export markets.
Current procurement scale favors Dairy; steepest expansion trajectory favors Beverages.
Form:
Capital equipment retrofit requirements and moisture control specifications fragment competitive positioning across manufacturing infrastructure profiles.
- Liquid:Concentrate solutions optimized for cold-fill dosing precision. Beverage and dairy applications concentrate demand here, with technical centers embedding dissolution kinetics specifications into supplier agreements.
- Powder:Spray-dried or encapsulated formats with extended shelf stability. Confectionery manufacturers prioritize this form for moisture-sensitive production environments and distribution durability.
- Paste:High-viscosity suspensions retaining aromatic compound integrity. Artisan chocolate manufacturers in Tasmania adopt this format for terpene preservation in small-batch processing.
- Granule:Free-flowing particulates for automated dosing systems. Industrial-scale bakery operations favor this form for metering accuracy in continuous production lines.
Legacy infrastructure favors Powder; line conversion investment favors Liquid.
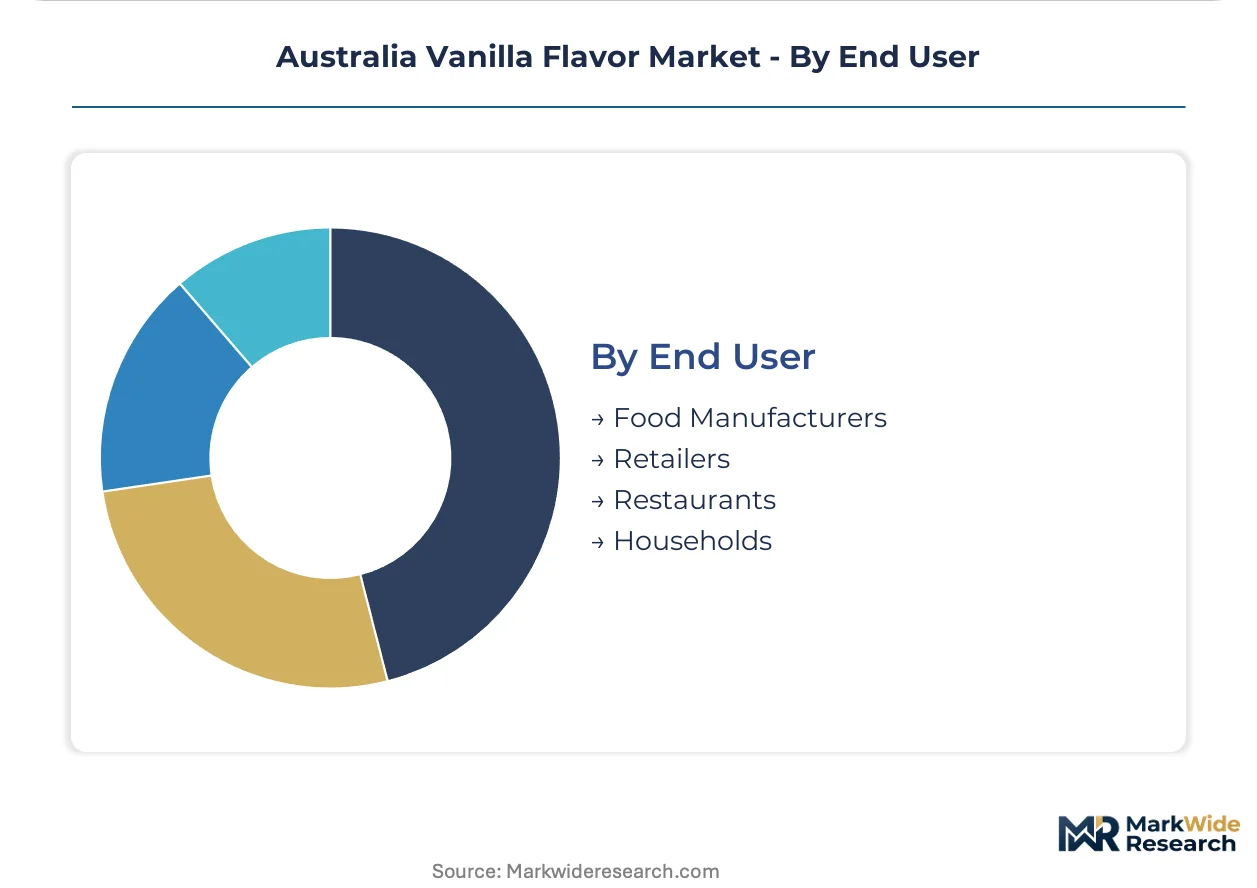
End User:
Compliance sophistication and volume scale determine supplier relationship structures across the procurement spectrum from industrial accounts to dispersed consumer channels.
- Food Manufacturers:Industrial-scale processors with ISO 22000 certification and FSANZ compliance infrastructure. These accounts drive technical service requirements and origin-specific master service agreements.
- Restaurants:Commercial foodservice operations with variable batch sizes and format flexibility needs. Melbourne's hospitality sector concentrates demand for liquid concentrates with portion-control packaging.
- Retailers:Private-label and branded product distributors with packaging claim verification requirements. Clean-label positioning pressures concentrate procurement toward natural and organic tiers.
- Households:Dispersed consumer purchases through retail channels. This segment shows highest price sensitivity and lowest format specification complexity across the end-user spectrum.
Contract value concentration favors Food Manufacturers; channel expansion favors Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Melbourne-based processors relative to Sydney distribution channels, reflecting Victoria's concentration of extraction infrastructure and New South Wales' reliance on interstate supply chains for natural flavor formulations.
New South Wales
Artisan bakery manufacturers in Sydney's Inner West and North Shore drive natural extract procurement for clean-label positioning. FSANZ labeling compliance costs burden smaller processors without dedicated regulatory affairs teams. The Parramatta food manufacturing corridor hosts blending operations that source concentrated inputs from Victorian suppliers.
Victoria
Premium dairy processors in Melbourne's northern suburbs anchor national demand for liquid concentrate formats with precise dissolution specifications. Dairy Food Safety Victoria enforces state-level processing codes that extend audit timelines for flavor house certification. Geelong's emerging food tech cluster attracts supercritical CO2 extraction investment from specialty ingredient startups.
Queensland
Functional beverage manufacturers in Brisbane's industrial precincts favor liquid concentrate dosing systems for batch consistency. The state's agricultural department supports Pacific island bean sourcing initiatives through trade development programs. Gold Coast confectionery exporters maintain ISO 22000-certified production lines targeting Asian retail accounts.
South Australia
Artisan chocolate producers in Adelaide Hills and Barossa Valley adopt paste-format vanilla for terpene preservation in small-batch processing. The state's primary industries regulator administers parallel organic certification pathways that reduce documentation burden for export-oriented manufacturers. Port Adelaide handles bulk extract imports for redistribution to interstate blenders.
Tasmania
Specialty dairy and confectionery manufacturers in Hobart and Launceston leverage the island's clean-food reputation for premium positioning in Asian export markets. The Tasmanian government offers grant programs for traceability technology integration that satisfies deforestation-free supply chain verification requirements. Burnie's port infrastructure supports direct procurement from Papua New Guinea cooperatives.
Australia Vanilla Flavor Market Competitive Landscape
Concentration sits with integrated multinational flavor houses that control captive bean sourcing and maintain Melbourne-based technical service centers. The vendor base fragments across mid-tier domestic blenders lacking extraction infrastructure and specialty importers focused on organic certification tiers. Two strategic archetypes dominate: Madagascar-anchored integrated processors with backward supply chain control, and liquid-format specialists competing through dosing precision and dissolution kinetics. Competitive moves center on Pacific origin diversification partnerships and CO2 extraction technology licensing to preempt FSANZ solvent residue limits.
Within the integrated multinational tier, Givaudan SA and Kerry Group occupy positions that exemplify divergent specialization strategies. Givaudan SA represents the origin-anchored archetype with captive Madagascar bean sourcing sustaining premium positioning across Australian dairy accounts. Kerry Group exemplifies the application-technical archetype, anchoring its Melbourne technical center to local beverage formulation demand and liquid flavor system specialization. Symrise AG sits within the same tier, though its regional positioning emphasizes fragrance crossover capabilities rather than food-grade extraction dominance.
| Leading Market Players |
|---|
| Givaudan SA |
| Symrise AG |
| Nielsen-Massey Vanillas, Inc. |
| Scentral Flavours and Fragrances |
| Dr. Oetker Group |
| Solvay SA |
| International Flavors & Fragrances |
| Kerry Group |
| Firmenich SA |
| Others |
Pricing and Supply Chain Analysis
Direct procurement contracts between Victorian dairy processors and Pacific island cooperatives lock in multi-year supply access and price visibility for natural extract tiers. These bilateral arrangements displace spot-market bean sourcing while insulating Australian manufacturers from Madagascar cyclone-induced volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order curing protocols from standard Bourbon-Madagascar extracts. Three-tier pricing structure across premium, standard, and economy levels reflects vanillin content thresholds and FSANZ natural classification compliance. Cost compression in standard extract tiers is intensifying because fermentation-derived vanillin achieves parity in bakery applications. Industrial confectionery manufacturers show highest price sensitivity, while artisan dairy processors absorb premiums for clean-label positioning.
Supply Chain Analysis
Madagascar Strait transit and Indian Ocean shipping lanes underwrite delivery reliability for over 80% of global vanilla bean supply. Australian processors draw from Madagascar, Papua New Guinea, and Indonesia for raw pod inputs. Single-source vulnerability concentrates in Madagascar harvest cycles exposed to tropical storm disruption. Distribution runs through Melbourne-based extraction facilities for downstream blending to interstate food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against fermentation-derived vanillin achieving cost parity and flavor profile equivalence in heat-processed applications.
For Market Incumbents: Secure backward integration into Pacific island curing infrastructure to preempt supply disruption and sustain natural extract premiums. Anchor Melbourne technical centers to beverage formulation partnerships that liquid concentrate specialization protects from synthetic substitution. FSANZ solvent residue limits favor processors with CO2 extraction capabilities already deployed. For New Entrants and Emerging Players: Technical service gaps in mid-tier processor R&D capacity present white-space entry points. Target South Australian artisan chocolate manufacturers with paste-format terpene preservation solutions. Pursue TGA excipient registration as a higher-margin adjacent channel with lower competitive density than commodity food-grade sales. For Investors and Strategic Acquirers: Capital is best deployed toward integrated processors with captive Pacific island sourcing and Melbourne-based extraction assets. The five-to-ten year viability window favors operators controlling origin diversification rather than commodity blenders. Watch fermentation-derived vanillin cost curves as the inflection signal for natural extract margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Pacific Origin Diversification | Papua New Guinea cooperatives reduce Madagascar dependency and freight costs for Melbourne processors. |
| Supercritical CO2 Extraction Licensing | FSANZ solvent residue limits from 2025 force purification infrastructure investment or technology pivot. |
| TGA Excipient Registration | Therapeutic goods coatings command higher margin retention than commodity food-grade vanilla sales. |
| Blockchain Traceability Integration | Immutable origin documentation satisfies Asian export market deforestation-free verification requirements. |
| Liquid Concentrate Line Conversion | Cold-fill beverage precision dosing captures share in functional drink applications across Brisbane manufacturers. |
Research Methodology
A standing panel of flavor chemists, extraction process engineers, FSANZ regulatory affairs specialists, and Dairy Food Safety Victoria auditors provided ongoing calibration. Primary interviews with procurement leads at Victorian dairy processors and Pacific island cooperative managers combined with secondary validation from FSANZ labeling guidance documents, TGA excipient registration databases, and ISO 22000 certification records. Bottom-up volume modeling across product tiers triangulated against top-down industry aggregation.
Output consistency was validated against customs import data for vanilla bean origins and extraction equipment capital expenditure disclosures. The analytical framework segments by natural versus artificial classification tiers, application matrices spanning heat-processed and cold-filled products, and end-user compliance sophistication across the projection horizon. CAGRs were derived from trend extrapolation of procurement patterns and substitution elasticity estimates for fermentation-derived alternatives.
Forecasts assume regulatory continuity in FSANZ maximum residue limits and TGA excipient pathways; material policy shifts would require re-modeling. Cyclone frequency in Madagascar and synthetic biology cost curves represent specific risk factors that could revise trajectory. Practitioners should keep alternative scenarios live as fermentation-derived vanillin production scales and Pacific island curing capacity expands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Lemon Extract Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Poria Cocos Extract Market