
 Flavor Compounds Market | 2026-2036
Flavor Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Compounds Market Intelligence
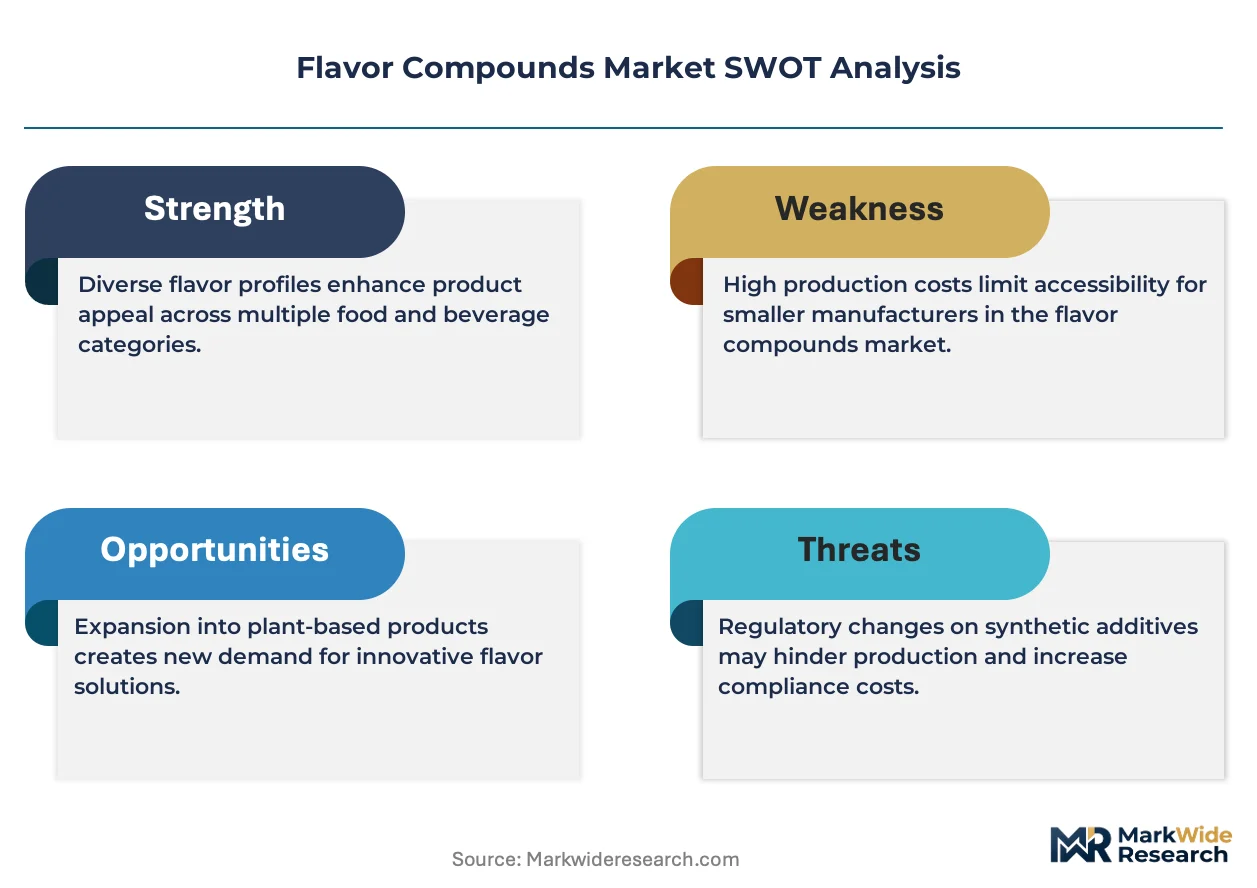
EU Green Deal provisions on sustainable food systems is consolidating procurement standards across European food processing units. Givaudan leverages its botanical extraction network to secure raw material traceability for natural flavor lines. Takasago International Corporation anchors its competitive position through biotechnology-driven fermentation processes that yield nature-identical molecules. Kerry Group sustains volume leadership by controlling dairy and beverage flavor formulations across multiple continents.
Flavor compounds constitute volatile and non-volatile organic molecules—esters, aldehydes, terpenoids, and pyrazines—engineered to impart, enhance, or mask taste and aroma in finished consumer goods, typically dosed at parts-per-million to parts-per-thousand concentrations depending on application heat stability and shelf-life requirements. Natural flavors and nature-identical flavors now command premium positioning as clean-label mandates from retail buyers displace legacy synthetic formulations in beverage and bakery applications. Synthetic flavors retain cost advantages in confectionery and nutritional products where thermal processing demands exceed natural molecule stability thresholds.
FDA food additive regulations, EFSA flavoring substance evaluations under Regulation (EC) No 1334/2008, and FSSAI standards for proprietary food categories collectively determine which molecules gain market access and which face reformulation deadlines. These frameworks are shifting R&D budgets toward GRAS-self-affirmed natural extracts and encapsulated delivery systems that mask off-notes in plant-based proteins. Stakeholders must monitor evolving positive lists in Europe and Asia-Pacific as regulatory divergence threatens to fragment formulation strategies across export markets.
Market Dynamics
The EU Green Deal's sustainable food systems mandate is compressing synthetic flavor tolerance thresholds while elevating natural extraction and fermentation-derived alternatives across European formulation pipelines.
Growth Catalysts
- Clean-label procurement mandates:Retail chains in Germany, France, and the Netherlands now require natural flavor certification for shelf placement, pulling beverage and dairy manufacturers toward botanical-derived systems.
- Biotechnology maturation:Precision fermentation yields nature-identical molecules at cost parity with petrochemical routes, unlocking scale for vanilla, citrus, and dairy flavor replication.
- EFSA positive list expansion:New approvals for encapsulated terpenoid and pyrazine formulations under Regulation (EC) No 1334/2008 accelerate reformulation timelines for heat-stable bakery applications.
Market Restraints
- Raw material supply volatility:Weather-dependent harvests of Madagascar vanilla, Indonesian cloves, and Indian cardamom create input cost spikes that synthetic alternatives avoid.
- Extraction capacity concentration:Supercritical CO2 and molecular distillation infrastructure clusters in Switzerland and southern Germany, creating geographic bottlenecks for natural flavor supply security.
- Thermal stability ceilings:Natural esters and aldehydes degrade above 180°C, excluding them from extruded snack and UHT sterilization processes where synthetic pyrazines dominate.
Strategic Opportunities
- Plant-based protein masking:Off-note suppression in pea and oat protein formulations creates demand for specialized encapsulated flavor systems in meat alternatives and functional beverages.
- India FSSAI proprietary food category expansion:New flavoring substance approvals for traditional dairy and confectionery applications open formulation latitude for multinational suppliers establishing local production.
- Direct-to-manufacturer digital platforms:B2B marketplaces bypass traditional distribution layers, enabling mid-size flavor houses to serve craft beverage and regional bakery segments with customized small-batch formulations.
Industry Challenges
- Cross-jurisdictional compliance staffing:Divergent positive lists between EFSA, FDA, and FSSAI require dedicated regulatory affairs teams for export-oriented formulation houses.
- Legacy equipment retrofit costs:Natural flavor handling demands stainless steel processing lines and nitrogen blanketing systems incompatible with existing synthetic flavor infrastructure at contract manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Compounds Market |
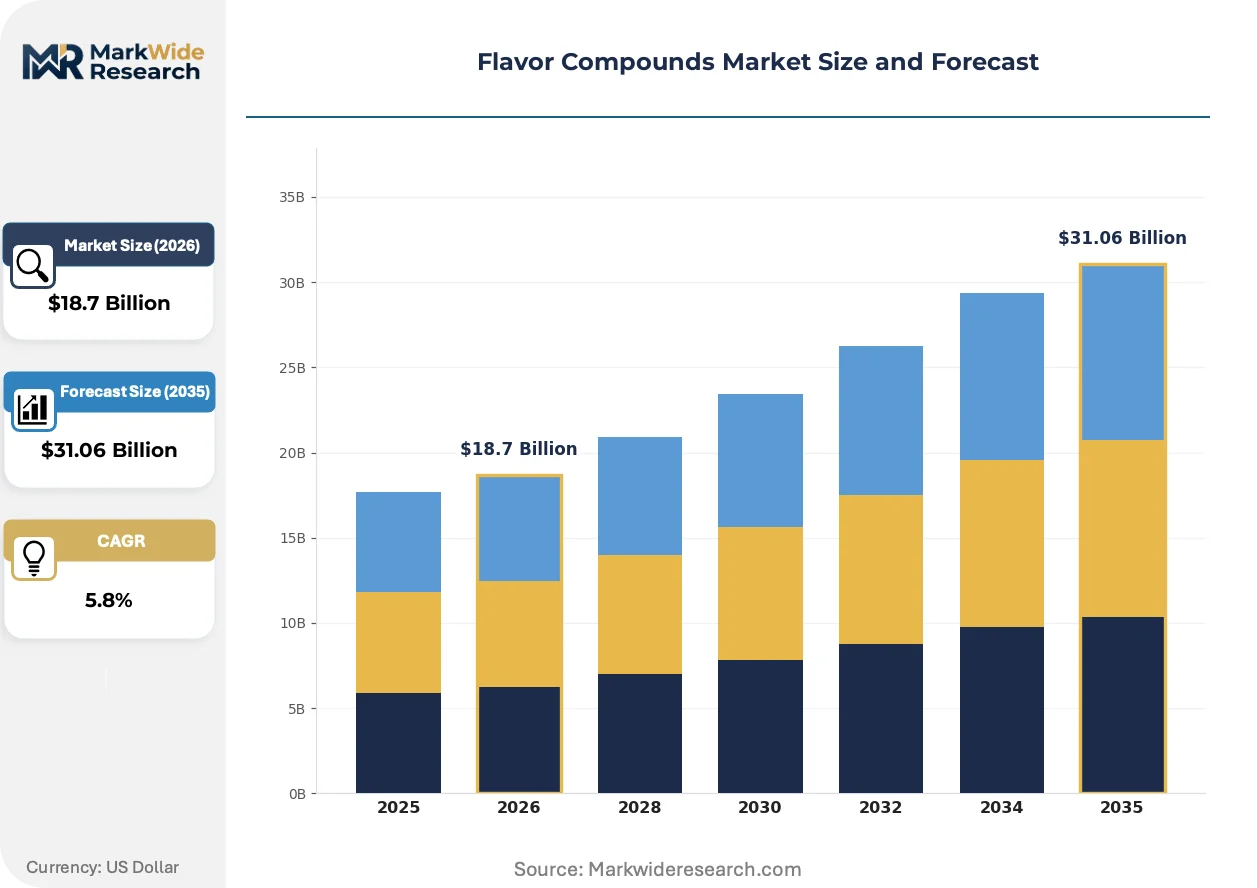
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Nature-Identical Flavors, Extracts, Oleoresins Application: Beverages, Confectionery, Bakery, Dairy Alternatives, Nutritional Products End User Industry: Food Processing Units, Beverage Manufacturers, Nutraceutical Firms, Cosmetic Producers, Pharmaceutical Brands Form: Liquid, Powder, Emulsions, Encapsulated Powders, Spray-Dried Powders |
| Companies Covered | International Flavors & Fragrances Inc., Takasago International Corporation, Givaudan, MANE, Kerry Group, Firmenich SA, Sensient Technologies Corporation, Robertet SA, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Compounds Market Strategic Shifts & Innovations
Biotechnology-enabled production methods and regulatory-driven formulation transparency are reconfiguring competitive advantage away from petrochemical synthesis toward traceable, fermentation-derived molecular platforms.
Cell-culture fermentation of flavor-active molecules is absorbing capital allocation from traditional extraction operations. Dairy and beverage manufacturers in Germany and the Netherlands are integrating these inputs at pilot scale. The technology is absorbing market share from solvent-based botanical extraction by delivering batch-to-batch consistency impossible with agricultural harvests.
REACH registration requirements for synthetic flavor intermediates are tightening substance documentation obligations for importers into the European Economic Area. Industrial consequence includes accelerated substitution of petroleum-derived aldehydes with bio-based equivalents. Bakery and confectionery segments are responding by pre-qualifying suppliers with complete SVHC disclosure portfolios ahead of 2027 reauthorization deadlines.
Ingredient provenance verification has become a non-negotiable purchasing criterion for branded food manufacturers. Third-party blockchain traceability platforms are displacing paper-based chain-of-custody documentation in procurement workflows. This shift is most visible in German retail private-label programs, where clean-label claims now require geolocation data for vanilla, citrus, and spice raw materials back to cooperative-level harvest records.
Flavor Compounds Market Segmentation
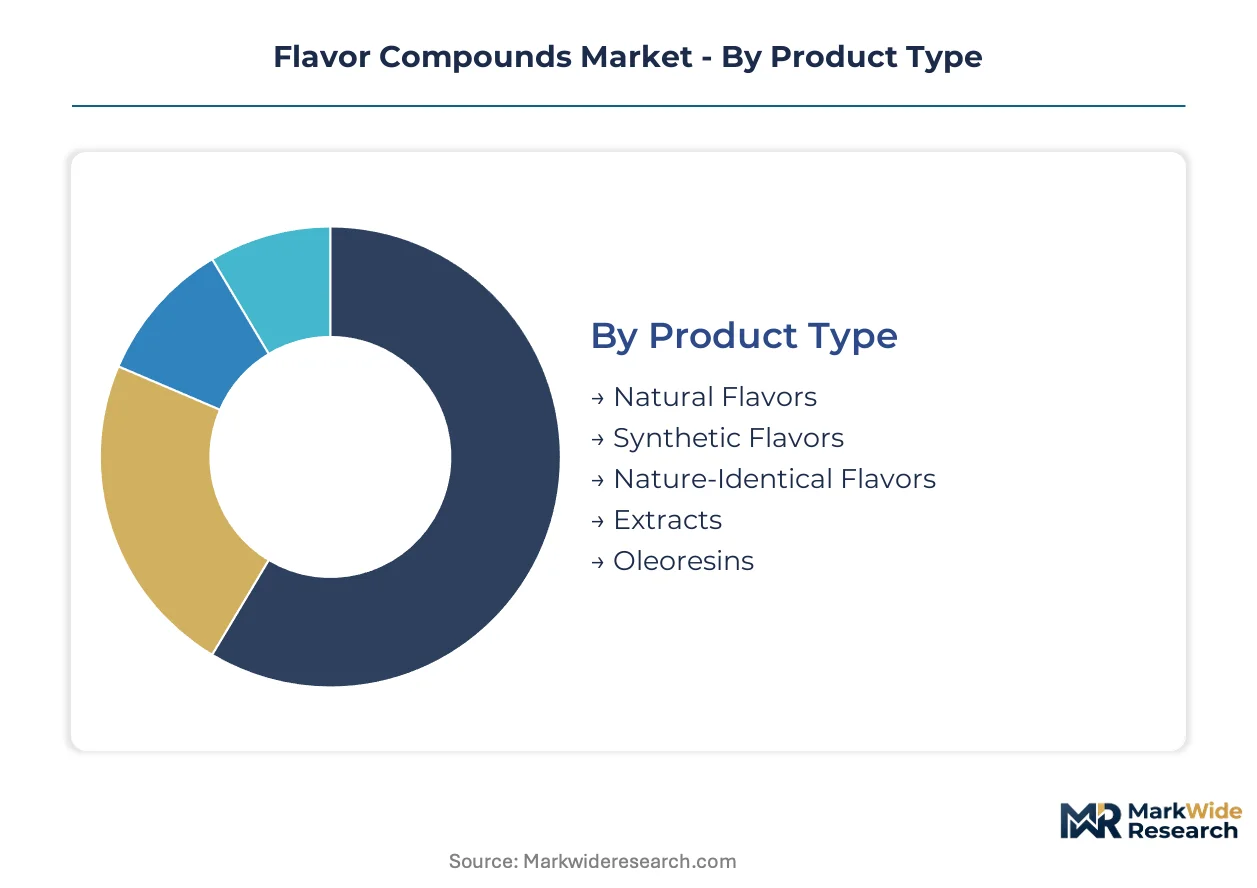
Segmentation in flavor compounds determines capital allocation priorities, with extraction infrastructure, fermentation bioreactors, and encapsulation equipment requiring vastly different upfront commitments. Procurement patterns diverge sharply across product types and applications, forcing suppliers to maintain parallel production architectures.
Product Type:
Natural flavors demand the heaviest capital burden through supercritical CO2 extraction systems and geographic diversification of raw material sourcing networks.
- Natural Flavors:Botanical and animal-derived volatile compounds extracted via solvent, distillation, or mechanical pressing. Beverage manufacturers in Germany and France now mandate these for clean-label placement, though Madagascar vanilla and Indonesian clove harvest volatility creates margin pressure.
- Synthetic Flavors:Petrochemical-derived aromatic molecules engineered for thermal stability above 200°C. Confectionery and extruded snack applications in Asia-Pacific rely on these where natural esters degrade, though EU Green Deal provisions are compressing tolerance thresholds.
- Nature-Identical Flavors:Molecules chemically identical to natural counterparts but synthesized via fermentation or chemical pathways. Precision fermentation yields cost parity with petrochemical routes for vanilla and citrus replication.
- Extracts:Concentrated flavor preparations obtained directly from source materials without synthetic modification. Steam-distilled citrus oils from Spain and Italy anchor European supply.
- Oleoresins:Solvent-extracted resinous concentrates combining volatile oils and non-volatile resins. Spice applications in processed meats and savory seasonings favor these for standardized potency.
Natural flavors absorb the bulk of installed capacity; nature-identical flavors are expanding most quickly.
Application:
Volume concentration varies by thermal processing requirements, with ambient-stable applications commanding different formulation architectures than heat-exposed categories.
- Beverages:Water-soluble flavor systems dosed at low parts-per-million, requiring stability across acidic pH ranges and pasteurization cycles. Germany's retail chains now enforce natural certification for shelf placement.
- Confectionery:Lipid-compatible flavors surviving high-shear mixing and controlled crystallization. Synthetic pyrazines dominate chocolate and hard candy where thermal profiles exceed natural molecule ceilings.
- Bakery:Heat-stable encapsulated systems releasing aroma during baking while surviving dough mixing shear. EFSA positive list expansions for terpenoid formulations are accelerating reformulation timelines.
- Dairy Alternatives:Masking systems suppressing off-notes in pea, oat, and soy protein bases. Plant-based meat alternatives drive specialized encapsulated demand.
- Nutritional Products:Flavor systems compatible with vitamin fortification and protein enrichment. Synthetic formulations retain cost advantages where thermal processing demands exceed natural stability thresholds.
Beverages command the largest formulation volumes; dairy alternatives are climbing the fastest.
End User Industry:
Customer scale determines service model, with multinational food processors demanding integrated technical support that mid-size flavor houses cannot replicate.
- Food Processing Units:Integrated meat, savory, and sauce manufacturers requiring batch-to-batch consistency. Swiss and German extraction infrastructure clusters create geographic supply security dependencies.
- Beverage Manufacturers:Carbonated, juice, and functional drink producers with stringent clean-label procurement mandates. Direct-to-manufacturer digital platforms are bypassing traditional distribution layers for craft segments.
- Nutraceutical Firms:Vitamin, mineral, and supplement producers masking active ingredient bitterness. Encapsulated delivery systems predominate for off-note suppression.
- Cosmetic Producers:Fragrance-flavor crossovers in oral care and lip products. Regulatory divergence between food and cosmetic safety standards fragments formulation strategies.
- Pharmaceutical Brands:Pediatric and geriatric drug formulations requiring palatability enhancement. GRAS-self-affirmed natural extracts dominate to avoid complex drug-master-file submissions.
Food processing units anchor volume demand; nutraceutical firms are gaining share fastest.
Form:
Physical state dictates packaging, handling infrastructure, and shelf-life engineering, with liquid systems requiring stainless steel tankage that powder operations avoid.
- Liquid:Solvent-based or oil-dispersed concentrates for immediate incorporation into liquid food matrices. Beverage and sauce applications favor these for uniform distribution.
- Powder:Spray-dried or plated flavors on carbohydrate carriers for dry mix applications. Bakery and confectionery dry blends require these for storage stability.
- Emulsions:Oil-in-water dispersions stabilizing lipophilic flavors in aqueous systems. Clouding agents in citrus beverages rely on emulsion technology.
- Encapsulated Powders:Core-shell structures protecting volatile molecules from oxidation and heat. Plant-based protein masking creates demand for specialized systems in meat alternatives.
- Spray-Dried Powders:Atomized liquid feedstock dried into free-flowing particulates. Cost-efficient production for high-volume, non-heat-sensitive applications.
Liquid formulations retain the largest installed base; encapsulated powders are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of flavor compounds clusters in Switzerland and Germany, while consumption concentrates in Western European retail markets and North American beverage processing. Extraction infrastructure and fermentation capacity remain geographically concentrated, creating supply security dependencies for natural flavor sourcing.
Germany
Beverage manufacturers in Hamburg and Bavaria now mandate natural flavor certification for retail shelf placement under clean-label procurement rules. The EU Green Deal's sustainable food systems mandate compresses synthetic additive tolerance thresholds nationwide. Supercritical CO2 extraction facilities cluster around Basel-Zurich-Frankfurt corridor, anchoring continental supply security for botanical-derived flavor lines.
United States
Carbonated and functional beverage producers drive formulation volumes, with FDA GRAS self-affirmation pathways accelerating natural extract market access. The FDA maintains distinct food additive approval frameworks separate from EFSA positive list structures, creating compliance complexity for export-oriented suppliers. Chicago and New Jersey processing corridors concentrate dairy and savory flavor demand from multinational food processors.
Switzerland
Precision fermentation infrastructure for nature-identical molecules absorbs capital allocation from traditional solvent extraction. REACH registration requirements for synthetic intermediates tighten substance documentation obligations for importers. Geneva and Basel host concentrated flavor innovation hubs serving German and French formulation pipelines with batch-to-batch consistency technologies.
India
FSSAI expansion of proprietary food categories for traditional dairy and confectionery applications opens formulation latitude for multinational suppliers establishing local production. Cardamom and spice harvest volatility from Kerala and Karnataka creates raw material cost pressure for natural extraction operations. Mumbai and Ahmedabad processing clusters attract investment in encapsulated delivery systems for heat-stable bakery applications.
France
Retail chains in Paris and Lyon enforce stricter labeling disclosures than EU baseline requirements, pulling manufacturers toward botanical-derived systems. EFSA evaluations under Regulation (EC) No 1334/2008 determine market access for new terpenoid and pyrazine formulations. Grasse fragrance-flavor crossover infrastructure supports oral care and cosmetic flavor applications with shared extraction expertise.
Flavor Compounds Market Key Industry Players
The competitive structure tilts toward integrated botanical extraction networks and biotechnology-enabled fermentation platforms. Multinational suppliers with captive raw material sourcing and regulatory affairs capabilities occupy premium positions, while mid-size houses compete through specialized encapsulation technologies. Three archetypes dominate: integrated extraction-fermentation hybrids, precision biotechnology specialists, and regional formulation service providers. Capacity expansion in fermentation bioreactors and strategic partnerships for blockchain traceability represent the dominant competitive moves.
Among integrated Swiss-Dutch suppliers, Givaudan, Firmenich SA, and Kerry Group exemplify the extraction-fermentation hybrid archetype. Givaudan leverages botanical networks for raw material traceability. Firmenich SA occupies a position at the biotechnology-driven end of nature-identical production. Kerry Group anchors volume leadership through dairy and beverage formulation control across multiple continents. Takasago International Corporation represents the precision fermentation specialist tier, while International Flavors & Fragrances Inc. sits within the scale-driven multinational segment.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Takasago International Corporation |
| Givaudan |
| MANE |
| Kerry Group |
| Firmenich SA |
| Sensient Technologies Corporation |
| Robertet SA |
| Symrise AG |
| Others |
Cost & Logistics Intelligence
Precision fermentation scale-up is compressing production cost curves while simultaneously concentrating bioreactor capacity in Swiss and German industrial clusters, tightening supply security for nature-identical molecules and amplifying pricing power for integrated extraction-fermentation hybrids over standalone botanical processors.
Pricing Analysis
Margin tightening in natural flavor tiers reflects Madagascar vanilla and Indonesian clove harvest volatility that synthetic alternatives bypass. Three-tier pricing structure across premium clean-label certification, standard nature-identical, and economy synthetic grades separates formulation tiers by thermal stability and traceability depth. Cost-down pressure on mid-tier fermentation-derived products accelerates because biotechnology maturation yields cost parity with petrochemical routes. Beverage manufacturers in Germany and France show least price sensitivity due to retail procurement mandates, while Asian confectionery processors remain most price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with supercritical CO2 extraction infrastructure concentrated in Switzerland and southern Germany. Geographic supply concentration centers on Madagascar for vanilla, Indonesia for cloves and nutmeg, and India for cardamom and spice oleoresins. Raw material dependencies rest on weather-dependent agricultural harvests, petroleum-derived aldehyde intermediates, and fermentation feedstocks. Supply chain risk hinges on regulatory restriction as EU Green Deal provisions compress synthetic additive tolerance thresholds. Distribution runs through integrated multinational suppliers with captive botanical networks, bypassing traditional distribution layers via direct-to-manufacturer digital platforms for craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extraction infrastructure scarcity props pricing for integrated suppliers, constraining volume expansion for mid-size houses lacking captive raw material sourcing or fermentation bioreactor networks.
For Market Incumbents: Cement supply security through backward integration into Madagascar vanilla and Indonesian spice cooperative networks, insulating margin structures from harvest volatility. Expand precision fermentation bioreactor capacity in Swiss-German industrial corridors to capture biotechnology-driven cost compression. Defend against emerging precision fermentation specialists by locking long-term offtake agreements with beverage manufacturers facing clean-label procurement mandates. For New Entrants and Emerging Players: Begin with encapsulated delivery systems for plant-based protein masking in dairy alternatives, the fastest-climbing application segment with specialized technical barriers mid-size entrants can exploit. Target Indian FSSAI proprietary food category expansion for traditional dairy and confectionery applications, where multinational supplier presence remains underdeveloped. Pursue direct-to-manufacturer digital platform routes to bypass incumbent distribution layers serving craft beverage and regional bakery segments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated extraction-fermentation hybrids seeking biotechnology capabilities and geographic footprint expansion. Long-term viability favors suppliers with demonstrated batch-to-consistency in fermentation-derived molecules and complete SVHC disclosure portfolios ahead of REACH reauthorization deadlines. Watch EFSA positive list expansion velocity as the signal indicating reformulation timeline acceleration and corresponding input demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biotechnology maturation yields cost parity with petrochemical routes for vanilla and citrus replication. |
| Blockchain Traceability Integration | Third-party platforms displace paper-based chain-of-custody documentation in German retail procurement workflows. |
| Encapsulation Technology Acquisition | Core-shell delivery systems protect volatile molecules from oxidation in plant-based protein masking applications. |
| Backward Integration into Spice Cooperatives | Captive sourcing networks insulate margin structures from Madagascar vanilla and Indonesian clove harvest volatility. |
| EFSA Regulatory Affairs Expansion | Dedicated compliance teams navigate divergent positive lists between European and Asia-Pacific export markets. |
Research Approach
Document review covered EFSA flavoring substance evaluations under Regulation (EC) No 1334/2008, FDA GRAS self-affirmation pathways, FSSAI proprietary food category notifications, and REACH registration databases, complemented by interviews with flavor application technologists at beverage manufacturers, procurement leads at German retail chains, extraction facility managers in Switzerland, regulatory affairs directors at multinational suppliers, and fermentation process engineers. Secondary validation drew from customs trade data, SEC filings of listed flavor houses, and botanical harvest reports. Bottom-up formulation volume estimates triangulated against top-down market sizing from production capacity assessments.
Cross-referencing historical pricing volatility in Madagascar vanilla and Indonesian clove markets against panel input from procurement executives anchored demand elasticity assumptions across the projection horizon. Segmentation modeling incorporated product type, application thermal stability requirements, end-user industry scale, and physical form factors. CAGRs derived from capacity expansion pipelines in fermentation bioreactors and supercritical CO2 extraction facilities, weighted by regulatory approval timelines for new molecular entities and clean-label procurement mandate adoption curves in German and French retail.
Underlying measurement precision varies by segment; nature-identical flavors and synthetic formulations carry tighter precision than natural extraction categories subject to agricultural harvest variability. Forecasts embed assumptions regarding biotechnology cost curve trajectories, EU Green Deal implementation pacing, and FSSAI category expansion velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
1-Decanol Market