
 Keto Friendly Flavors Market | 2026-2036
Keto Friendly Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Keto Friendly Flavors Market Outlook
Functional beverage manufacturers are reorganizing their supplier portfolios toward flavor houses that certify zero-net-carb profiles. Perfect Keto leverages direct-to-consumer channel control to sustain repeat purchase rates in powdered creamer applications. Givaudan anchors its position through in-house production of natural vanilla and cocoa extracts tailored to ketogenic macro constraints. Quest Nutrition differentiates via savory-sweet hybrid formats that occupy shelf space traditionally held by conventional snack flavorings.
Keto friendly flavors comprise taste-active compounds formulated without fermentable carbohydrates, typically achieving sweetness through high-intensity non-glycemic agents at concentrations between 0.01% and 2.0% by weight, with primary commercial purpose of enabling palatability in products maintaining sub-5g net carbohydrate per serving. Chocolate and vanilla flavor types dominate current volume due to their compatibility across beverage and dessert applications, while caramel is gaining fastest as brands target indulgence positioning without sucrose. Liquid formulations lead in manufacturing efficiency for ready-to-drink lines, though powdered concentrates capture margin pools in at-home mixing segments where stevia and allulose sweetener types are displacing erythritol for cleaner aftertaste profiles.
The FDA's GRAS determinations for allulose and monk fruit extract shape which sweetener-flavor combinations achieve national retail distribution, while EFSA novel food opinions govern European market access timelines for emerging botanical extracts. BIS quality mandates in India and China's SAMR labeling requirements for low-carb claims create divergent compliance pathways that flavor houses must navigate simultaneously. Stakeholders need to monitor how regulatory divergence between jurisdictions affects formulation standardization costs and whether centralized R&D hubs or regional adaptation labs prove more capital-efficient for multi-territory launches.
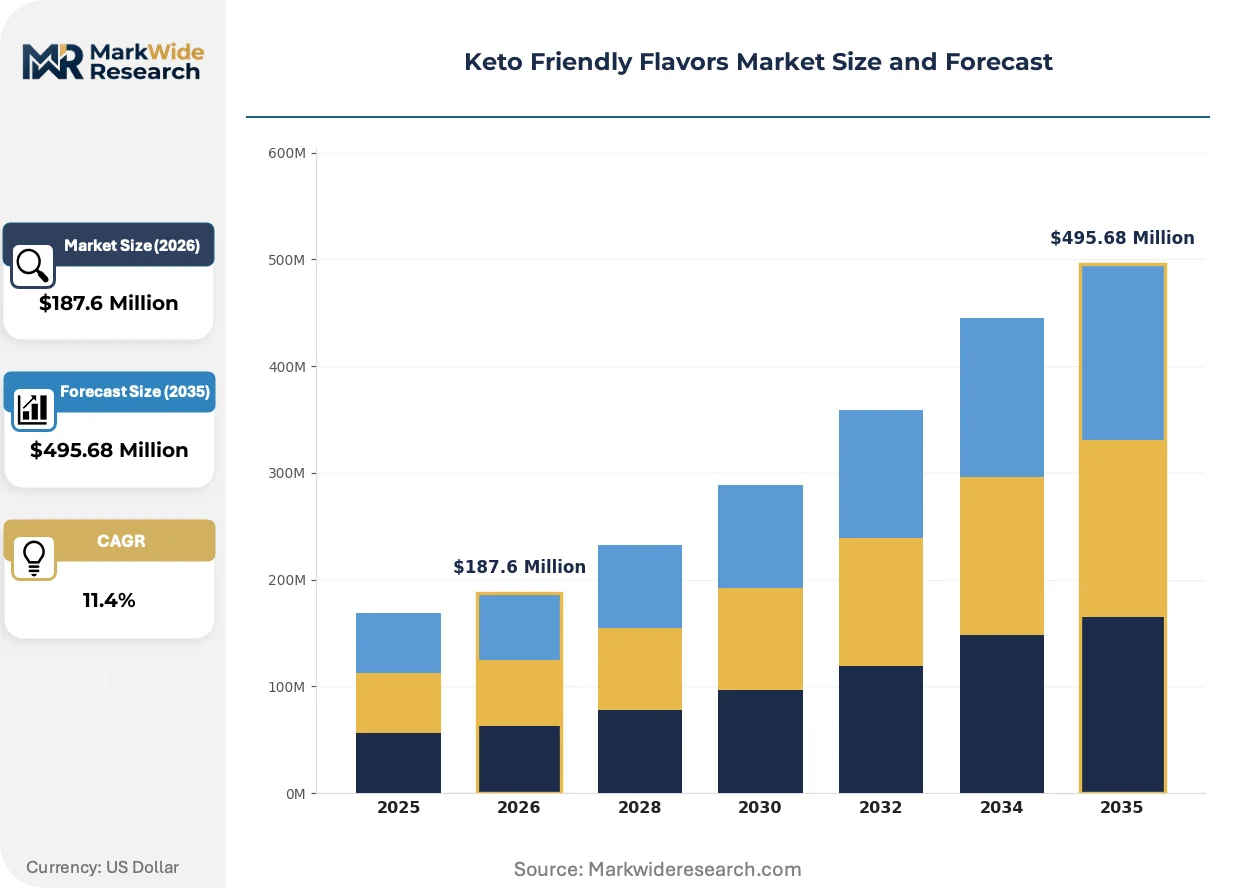
Market Dynamics
Clean-label sweetener approvals by the FDA and EFSA are compressing formulation timelines and forcing flavor houses to revalidate entire product portfolios around non-glycemic carrier systems.
Growth Catalysts
- Functional Beverage Procurement:Sports nutrition manufacturers are expanding orders for keto-compliant flavor systems to serve ready-to-drink protein lines. This pulls volume through certified supply chains.
- GRAS Determinations:The FDA's allulose and monk fruit approvals enable national retail distribution for previously constrained formulations. Brands now scale without state-by-state compliance fragmentation.
- Low-Carb Lifestyle Adoption:Germany, the United States, and Australia show deepening consumer adherence to ketogenic macro targets. This concentrates demand in markets with established specialty retail infrastructure.
Market Restraints
- Natural Extract Volatility:Vanilla and cocoa supply from Madagascar and Côte d'Ivoire faces climate-driven harvest inconsistency. This squeezes margin pools for natural-positioned flavor houses.
- Sweetener Aftertaste Limitations:Erythritol cooling effects persist in powdered creamer applications despite reformulation efforts. Some consumers reject products with detectable off-notes.
- Regional Labeling Divergence:China's SAMR low-carb claim requirements differ from BIS quality mandates in India. Multi-territory launches require parallel compliance documentation.
Strategic Opportunities
- Savory-Sweet Hybrid Formats:Snack flavorings combining umami and sweetness occupy shelf space traditionally held by conventional seasonings. This opens incremental placement in savory aisles.
- Direct-to-Consumer Channels:Powdered concentrate brands bypass retail slotting fees through subscription models. At-home mixing segments capture margin pools lost to ready-to-drink lines.
- Botanical Extract Novel Foods:EFSA opinions on emerging plant-derived sweeteners create first-mover windows for European market access. Early filers secure 18-24 month competitive isolation.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise spanning high-intensity sweetener synergy and ketogenic macro constraints remains concentrated at senior levels. Junior pipeline development lags demand.
- Cross-Functional Capex Requirements:In-house natural extract production demands simultaneous investment in agricultural sourcing, processing equipment, and analytical validation labs.
- Carrier System Reconfiguration:Legacy maltodextrin-based flavor delivery vehicles require complete replacement with non-glycemic alternatives. This forces reformulation of established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keto Friendly Flavors Market |
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $495.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Chocolate, Vanilla, Strawberry, Caramel Application: Beverages, Snacks, Desserts, Sauces Formulation: Concentrates, Powdered, Liquid, Granulated Sweetener Type: Stevia, Erythritol, Monk Fruit, Allulose |
| Companies Covered | Natures Flavors.com, Ancient Nutrition, Keto Creamer, BPI Health, Perfect Keto, Quest Nutrition, Simply Good Foods USA, HighKey, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keto Friendly Flavors Market Strategic Shifts
Flavor delivery technology is splitting between manufacturing-optimized liquid systems and margin-rich powdered concentrates, while regulatory divergence between jurisdictions forces parallel R&D track development.
Allulose-stevia blends are bifurcating the high-intensity sweetener landscape by enabling clean aftertaste profiles previously unattainable with single-ingredient solutions. Ready-to-drink beverage manufacturers are adopting these combinations at accelerated pace for Q3-Q4 formulation cycles. The technology is compressing erythritol's market position while expanding addressable applications into temperature-sensitive dessert categories.
EFSA novel food opinions are reshaping European market access timelines for botanical extracts derived from non-traditional sources. Flavor houses must now submit comprehensive safety dossiers 24-36 months ahead of commercial launch targets. Ketogenic positioned brands targeting Germany and France are responding by front-loading regulatory investment or shelving European expansion in favor of faster FDA-tracked US introductions.
Subscription-based replenishment models are displacing traditional retail stocking for at-home powdered creamer segments. Direct-to-consumer brands capture recurring revenue streams while specialty retailers lose foot traffic in beverage aisles. This pattern is most visible in the United States, where warehouse club shelf resets increasingly exclude niche flavor formats in favor of mass-market alternatives.
Keto Friendly Flavors Market Segmentation
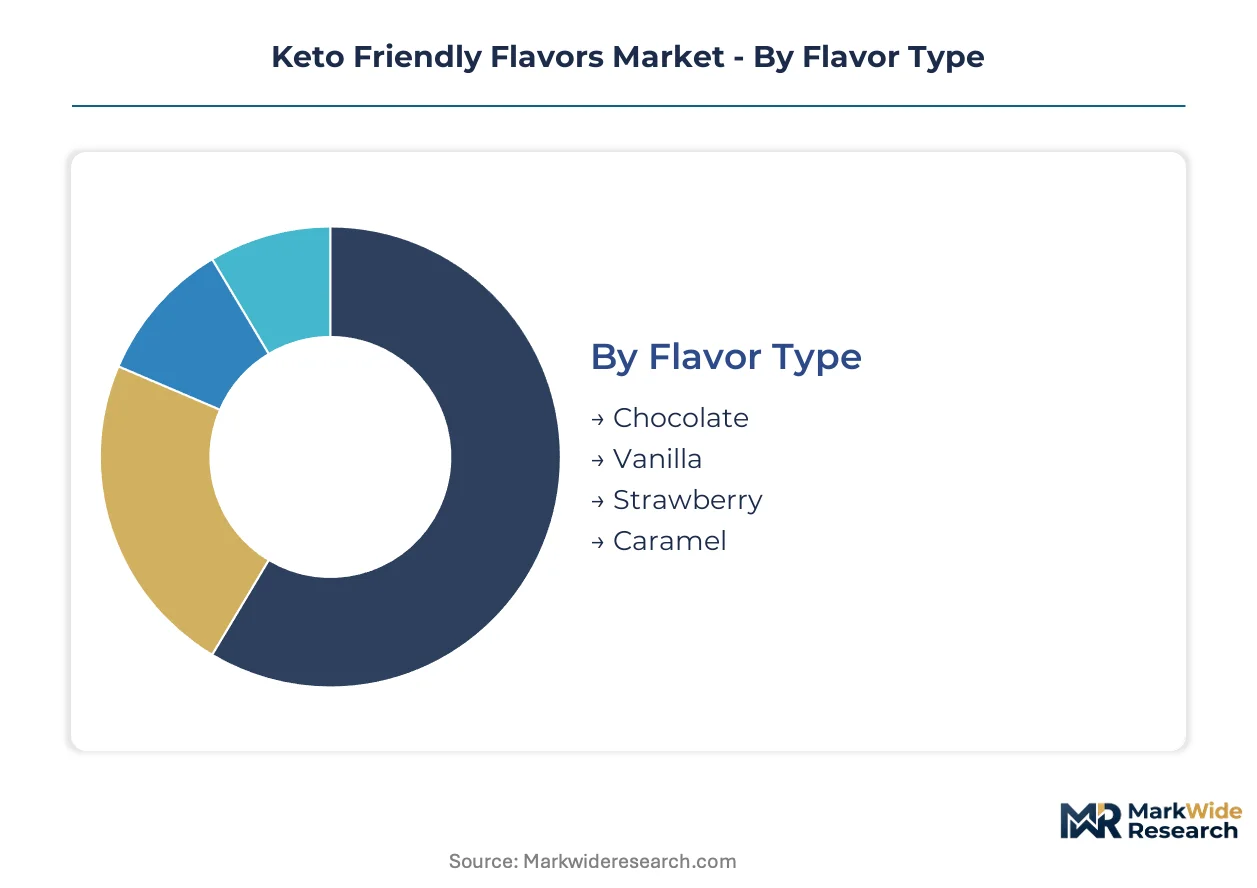
Keto friendly flavors segment along four functional dimensions that determine formulation complexity and channel access. Each category carries distinct technical constraints affecting procurement patterns and margin structures across beverage, snack, and dessert applications.
Flavor Type:
Flavor type distribution tracks closely to retail channel placement and repeat purchase velocity in powdered creamer and ready-to-drink formats.
- Chocolate:Cocoa-derived taste-active compounds formulated at 0.5-2.0% concentration by weight. Demand concentrates in United States beverage applications where clean-label positioning drives premium shelf placement. Supply volatility from Côte d'Ivoire harvests constrains natural-positioned variants.
- Vanilla:Natural extract and synthetic vanillin systems tailored to ketogenic macro constraints. Germany and Australia show deepening procurement for dessert applications as low-carb lifestyle adherence expands. Madagascar supply inconsistency squeezes margin pools for premium-positioned lines.
- Strawberry:Botanical-derived ester compounds achieving palatability without fermentable carbohydrates.
- Caramel:Maillard-reaction flavor systems enabling indulgence positioning without sucrose contribution.
By volume, chocolate leads. By growth pace, caramel is expanding most quickly.
Application:
Application mix reflects divergent manufacturing efficiency requirements between at-home preparation and industrial-scale production.
- Beverages:Ready-to-drink and powdered creamer formats demanding liquid flavor systems with thermal stability across pasteurization protocols. United States sports nutrition manufacturers pull volume through certified supply chains for protein line extensions.
- Snacks:Savory-sweet hybrid formats occupying shelf space traditionally held by conventional seasonings. Quest Nutrition and similar brands target Germany and Australia retail placement with umami-sweet crossover products.
- Desserts:Temperature-sensitive applications requiring flavor systems stable across freeze-thaw cycles.
- Sauces:Viscosity-compatible concentrates for condiment and dressing formulations.
Beverages dominate current procurement volume. Snacks are gaining share fastest through savory aisle expansion.
Formulation:
Formulation choice separates manufacturing-optimized industrial supply from margin-rich direct-to-consumer channels.
- Liquid:Manufacturing-efficient systems for ready-to-drink lines with streamlined dosing and homogenization. Givaudan and flavor houses with in-house natural extract production anchor supply to large beverage manufacturers.
- Powdered:Concentrates capturing margin pools in at-home mixing segments where subscription models bypass retail slotting fees. Perfect Keto leverages direct-to-consumer channel control for repeat purchase retention.
- Concentrates:High-potency systems requiring precise dilution protocols.
- Granulated:Free-flowing formats for dry-blend applications with extended shelf stability.
Liquid formulations lead in manufacturing throughput. Powdered concentrates command the steepest expansion trajectory in revenue-per-unit terms.
Sweetener Type:
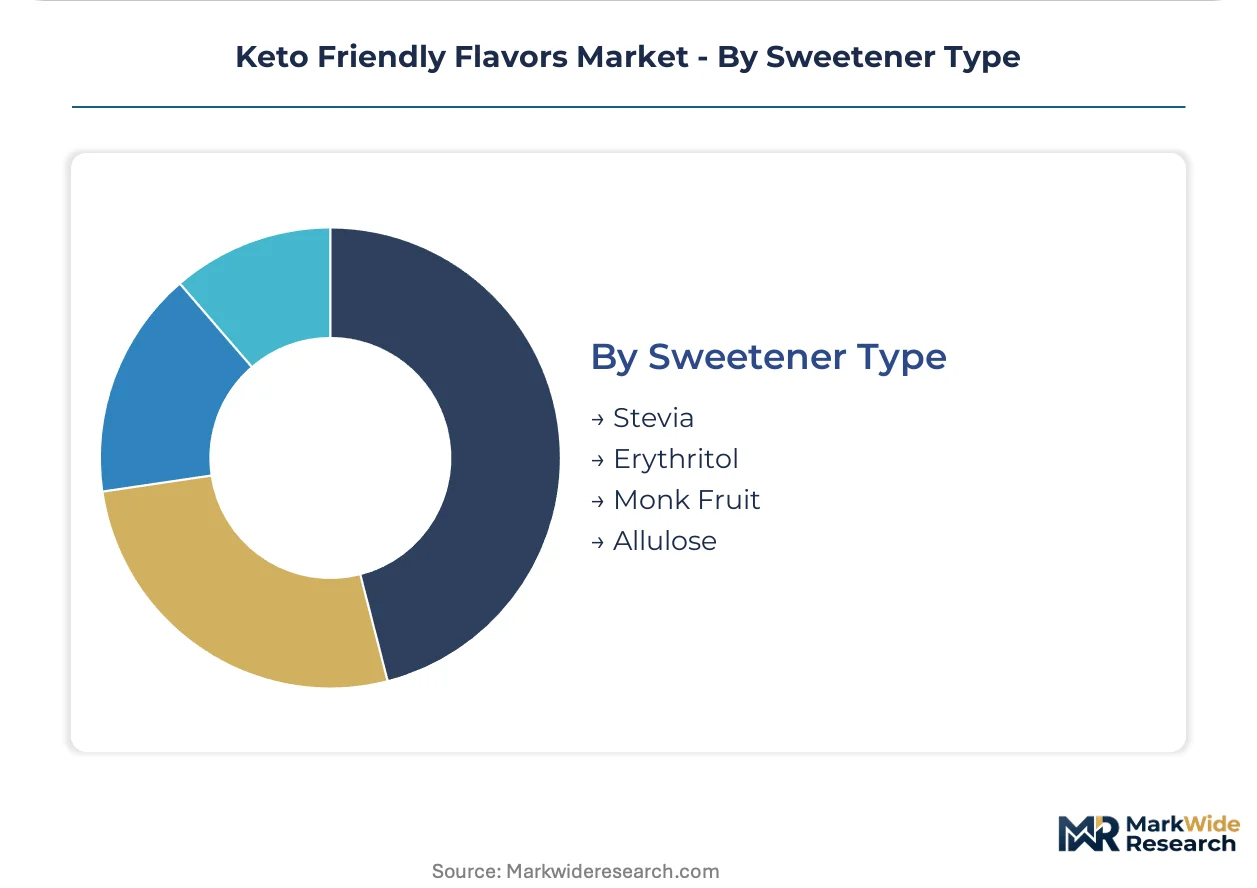
Sweetener selection determines regulatory access and aftertaste profile, with FDA GRAS determinations shaping viable combinations.
- Allulose:Rare sugar achieving clean sweetness without glycemic impact, approved under FDA GRAS for national retail distribution. Brands reformulate Q3-Q4 cycles to displace erythritol in temperature-sensitive dessert categories.
- Stevia:High-intensity glycoside extracts blended with allulose for synergistic aftertaste improvement. EFSA novel food opinions govern European market access timelines, creating 18-24 month competitive isolation for early filers.
- Monk Fruit:Mogroside extracts with FDA GRAS status enabling scaled distribution without state-by-state compliance fragmentation.
- Erythritol:Polyol sweetener facing compression from allulose-stevia blends due to persistent cooling aftertaste in powdered creamer applications.
Allulose-stevia blends are climbing the fastest as manufacturers prioritize clean aftertaste profiles. Erythritol retains volume leadership in legacy formulations pending reformulation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor houses in the United States export keto-compliant formulations to Germany and Australia, creating a transatlantic trade corridor for low-carb taste systems. This flow concentrates procurement power in North American supply chains while European and Asia-Pacific markets adapt local regulatory frameworks.
United States
Sports nutrition manufacturers in California and Texas drive procurement for ready-to-drink protein lines with zero-net-carb specifications. FDA GRAS determinations for allulose and monk fruit extract enable national retail distribution without state-by-state compliance fragmentation. Chicago and Austin clusters host formulation labs that revalidate portfolios around non-glycemic carrier systems.
Germany
Low-carb lifestyle adherence in Bavaria and North Rhine-Westphalia deepens demand for dessert applications using vanilla and cocoa extracts. EFSA novel food opinions govern market access timelines for emerging botanical sweeteners, creating 18-24 month competitive isolation for early filers. Frankfurt-area flavor houses front-load regulatory investment to secure European positioning.
Australia
Functional beverage adoption in New South Wales and Victoria concentrates orders for stevia-allulose blend systems. TGA labeling requirements for low-carb claims shape local formulation standards distinct from FDA or EFSA pathways. Sydney-based manufacturers expand savory-sweet hybrid snack formats into retail channels.
China
SAMR labeling requirements for low-carb claims create compliance divergence from Western regulatory frameworks. Yangtze River Delta flavor producers adapt formulations for domestic ketogenic positioned brands while exporting raw extract materials. Shanghai clusters specialize in high-intensity sweetener processing for regional beverage manufacturers.
India
BIS quality mandates for food-grade flavor compounds govern import and domestic production standards. Maharashtra and Gujarat industrial zones develop localized stevia extraction capacity to serve emerging low-carb consumer segments. Mumbai-based distributors navigate parallel documentation requirements for multi-territory launches.
Keto Friendly Flavors Market Competitive Environment
Player mix skews toward integrated flavor houses with captive extract production and direct-to-consumer nutrition brands controlling subscription channels. The market structure splits between manufacturing-optimized liquid system suppliers and margin-rich powdered concentrate specialists. Two strategic archetypes dominate: vertically integrated natural extract producers and digitally native brands bypassing retail slotting fees. Competitive moves center on regulatory first-filing for novel food approvals and backward integration into agricultural sourcing.
Among integrated flavor houses, Givaudan anchors the natural extract tier through in-house vanilla and cocoa production. Perfect Keto and Quest Nutrition occupy positions within the direct-to-consumer archetype, leveraging channel control to sustain repeat purchase rates. These three exemplify the bifurcation between manufacturing-scale supply and digitally distributed brand economics.
| Leading Market Players |
|---|
| Natures Flavors.com |
| Ancient Nutrition |
| Keto Creamer |
| BPI Health |
| Perfect Keto |
| Quest Nutrition |
| Simply Good Foods USA |
| HighKey |
| Givaudan |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day vanilla extract lead times from Madagascar and Côte d'Ivoire compress margin pools for natural-positioned flavor houses while amplifying pricing power for integrated producers with captive agricultural sourcing.
Pricing Analysis
Prior-generation erythritol-based formulations trade at commodity-grade price points while next-generation allulose-stevia blends command 15-25% premiums for clean aftertaste profiles. Three-tier pricing structure across premium natural-extract, standard synthetic-vanillin, and economy-grade compounded systems separates Givaudan's in-house cocoa production from contract manufacturers dependent on spot-market botanicals. Price differentiation rests on FDA GRAS certification tier and volume scale commitments from sports nutrition manufacturers. Cost compression in powdered concentrate segments is intensifying because Perfect Keto and similar direct-to-consumer brands bypass retail slotting fees through subscription models, forcing legacy suppliers to absorb distributor margins. Beverage manufacturers show highest price sensitivity due to manufacturing-optimized liquid system commoditization, while at-home mixing segments accept premium positioning for personalized flavor control.
Supply Chain Analysis
Madagascar and Côte d'Ivoire anchor natural vanilla and cocoa extract production, while the United States concentrates formulation and flavor house R&D capacity. Raw material dependencies draw from high-intensity sweetener processing in China, botanical cultivation in Southeast Asia, and dairy-derived carrier systems from European suppliers. Single-source vulnerability in Madagascar vanilla harvests creates supply chain risk amplified by climate-driven yield inconsistency. Distribution runs through certified supply chains serving sports nutrition manufacturers, with direct-to-consumer subscription channels displacing traditional retail stocking for powdered concentrate segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor chemists capable of balancing high-intensity sweetener synergy with ketogenic macro constraints remain concentrated at senior levels, creating a bottleneck that determines which formulation portfolios achieve regulatory clearance and commercial scale.
For Market Incumbents: Fortify regulatory first-filing positions for EFSA novel food opinions to secure 18-24 month competitive isolation in Germany and France, while deepening backward integration into Madagascar and Côte d'Ivoire agricultural sourcing to defend margin pools against climate-driven extract volatility. Channel control through direct-to-consumer subscription infrastructure represents the priority lever against retail slotting fee compression. For New Entrants and Emerging Players: Subscription-based replenishment gaps in European markets where EFSA timelines delay incumbent launches offer the most penetrable white-space target. Botanical extract novel foods awaiting safety dossier approval create entry windows for early filers willing to front-load regulatory investment. A go-to-market angle anchored in stevia-allulose blend systems for temperature-sensitive dessert categories bypasses erythritol's entrenched position in legacy formulations. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA GRAS determinations compress US market access timelines relative to EFSA novel food pathways, rewarding portfolios weighted toward American formulation assets. Acquisition targets should display integrated natural extract production or captive direct-to-consumer channels. The signal to watch is EFSA opinion publication velocity for emerging botanical sweeteners, which will reshape competitive isolation windows across European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory First-Filing for Novel Foods | EFSA opinion windows create 18-24 month competitive isolation for early botanical extract filers in Germany. |
| Backward Integration into Agricultural Sourcing | In-house vanilla and cocoa production in Madagascar insulates Givaudan against climate-driven harvest volatility. |
| Direct-to-Consumer Channel Development | Subscription models bypass retail slotting fees and capture recurring revenue streams in at-home mixing segments. |
| Allulose-Stevia Blend Formulation | Clean aftertaste profiles displace erythritol in temperature-sensitive dessert categories across Q3-Q4 reformulation cycles. |
| Carrier System Reconfiguration | Non-glycemic alternatives replace maltodextrin-based delivery vehicles to meet FDA and EFSA clean-label mandates. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with flavor chemists, sports nutrition procurement directors, regulatory affairs specialists at FDA and EFSA, and direct-to-consumer brand supply chain managers; and secondary validation through FDA GRAS filings, EFSA novel food opinions, customs records for vanilla and cocoa extract trade flows, and SEC 10-K disclosures from integrated flavor houses. Bottom-up triangulation across formulation complexity tiers and top-down validation against certified supply chain volumes anchored market sizing.
Across the analysis window, the forecasting framework modeled flavor type, application, formulation, and sweetener type segmentation dimensions with geographic regulatory cluster overlays. CAGRs were derived from procurement pattern trajectories in sports nutrition and functional beverage verticals, cross-referenced against clean-label sweetener approval timelines and low-carb lifestyle adoption curves in the United States, Germany, and Australia.
Material uncertainties — EFSA opinion delays, Madagascar harvest failures, and SAMR labeling requirement shifts in China — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway standardization and botanical extract supply stability. Recalibration cycles align with material shifts in FDA GRAS determination velocity and climate-driven agricultural yield patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Dairy Flavors Market