
 Sour Cream Powder Market | 2026-2036
Sour Cream Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Sour Cream Powder Market Analysis
The EU Green Deal is broadening sourcing requirements for dairy-derived ingredients entering European food manufacturing. Bluegrass Ingredients, Inc. leverages its Kentucky production base to supply spray-dried dairy powders to North American seasoning houses. Commercial Creamery Company anchors its position through specialized cultured dairy powder formulations for industrial sauce applications. Dairy Farmers of America, Inc. sustains volume leadership via cooperative-backed milk supply security and integrated drying operations.
Sour cream powder consists of cultured cream that undergoes drying—typically spray-drying or freeze-drying—to yield a shelf-stable powder with approximately 35-45% milk fat content and enhanced tangy flavor profiles from lactic acid fermentation; manufacturers deploy it as a functional ingredient where liquid sour cream would compromise moisture stability or shorten finished-product shelf life. Spray-dried variants dominate procurement volumes due to lower unit production costs and favorable dispersibility in high-temperature processing environments, while freeze-dried grades command premium positioning in gourmet seasoning and specialty snack segments where flavor intensity retention justifies elevated pricing. The food processing end-user channel absorbs the largest share of bulk shipments, though snack manufacturers represent the fastest-growing demand pocket as seasoned chip and extruded snack portfolios expand.
FDA dairy identity standards, USDA organic certification requirements, and EU REACH chemical safety protocols collectively shape ingredient compliance burdens, formulation transparency expectations, and cross-border market access conditions for sour cream powder suppliers. FSMA preventive controls mandates require domestic and import facilities to maintain hazard analysis documentation across spray-drying and packaging operations. Stakeholders must monitor evolving clean-label thresholds and regional allergen declaration rules to sustain formulation relevance and distribution eligibility across multi-jurisdictional supply chains.
Market Dynamics
Spray-drying technology maturation and FDA dairy identity standard revisions are compressing formulation timelines while forcing ingredient declaration transparency across North American food manufacturing. These dual pressures reward suppliers with integrated fermentation and drying capabilities.
Growth Catalysts
- Clean-label mandates:FDA modernization of dairy ingredient labeling standards compels manufacturers to reformulate with recognizable cultured dairy powders rather than synthetic acidifiers.
- Extruded snack expansion:Seasoned chip and puffed snack producers in the United States are scaling bulk procurement of dispersible dairy powders for high-temperature coating operations.
- Shelf-stable sauce demand:Ready-meal manufacturers require lactic acid-fermented powders that withstand retort processing without moisture compromise.
Market Restraints
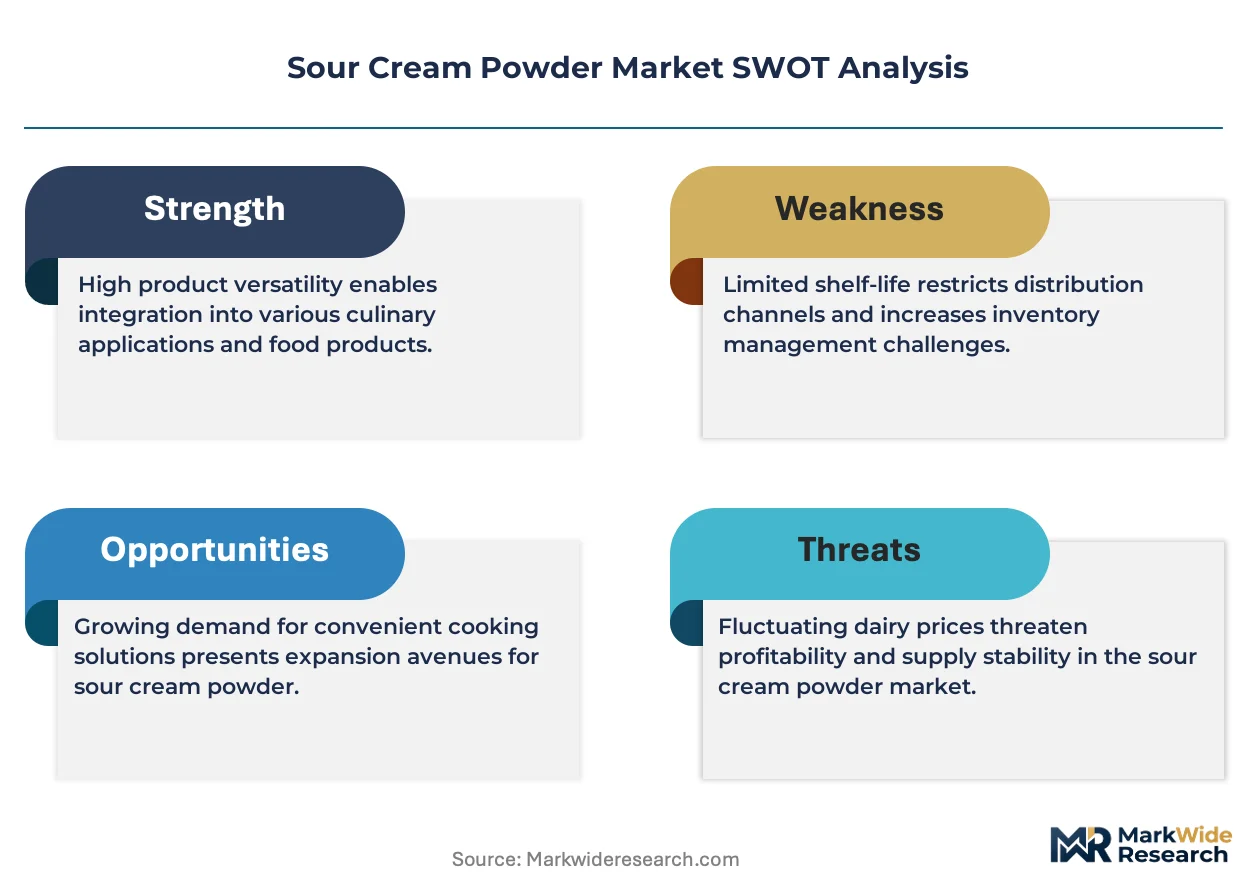
- Butterfat cost volatility:Cream input prices track CME Group dairy commodity swings, compressing margins for standard-grade powder specifications.
- Midwest supply concentration:Spray-drying capacity clusters in Wisconsin and Kentucky, creating geographic vulnerability to regional weather and logistics disruptions.
- Fresh sour cream substitution:Refrigerated dairy distributors promote liquid cultured cream for high-volume foodservice accounts with reliable cold-chain infrastructure.
Strategic Opportunities
- EU Green Deal alignment:European sourcing requirements for low-carbon dairy ingredients create entry paths for North American suppliers with verified methane-reduction credentials.
- Gourmet seasoning premiumization:Freeze-dried variants with enhanced flavor intensity retention command price multiples in specialty retail and craft snack channels.
- Organic certification arbitrage:USDA organic sour cream powder remains undersupplied relative to conventional grades, rewarding early certifiers with procurement preference from natural product brands.
Industry Challenges
- FSMA documentation burden:Preventive controls mandates require hazard analysis records across spray-drying and packaging operations, stretching quality assurance staffing.
- Clean-label threshold evolution:Shifting consumer definitions of "natural" force continuous reformulation cycles without standardized regulatory benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sour Cream Powder Market |
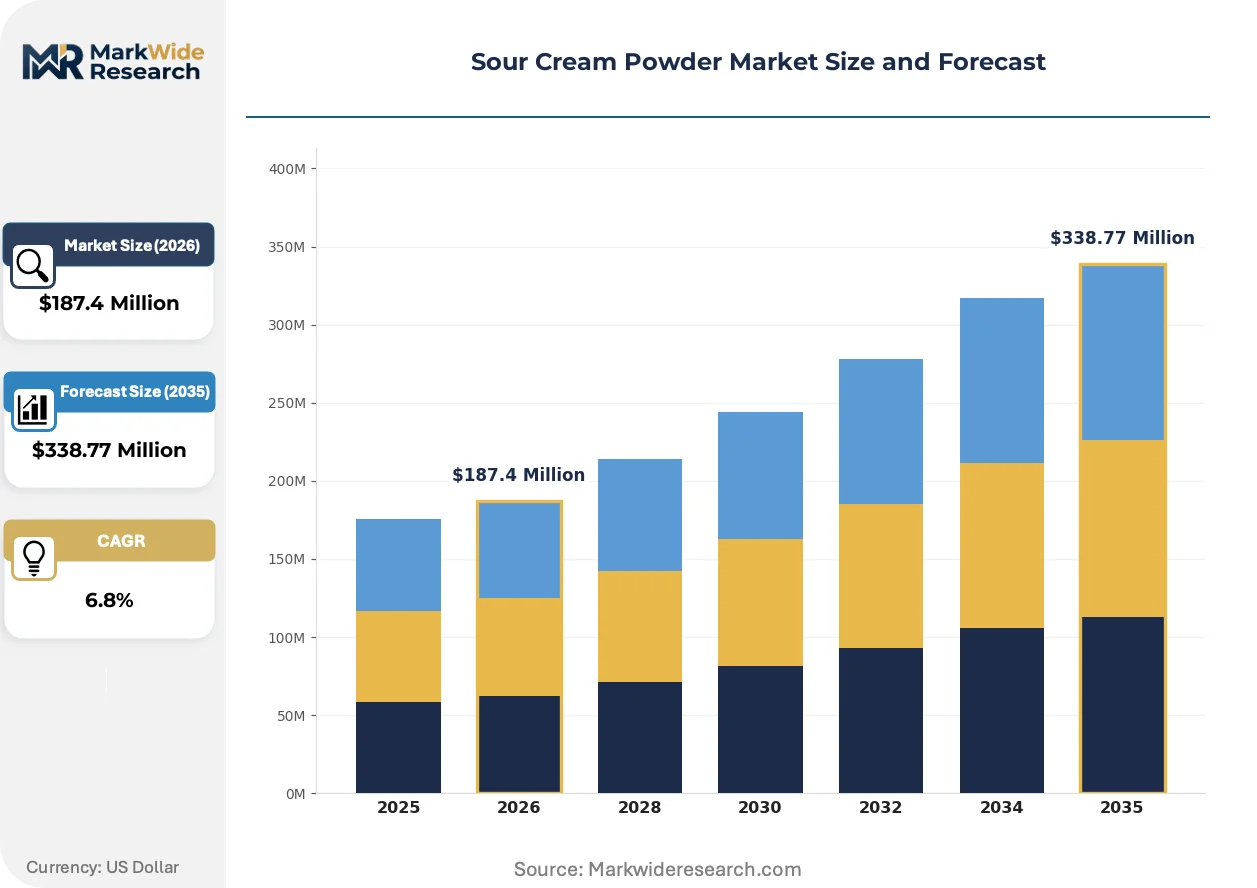
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant, Spray-Dried, Freeze-Dried, Granulated End User: Food Processing, Bakery, Snacks, Dairies Application: Seasonings, Sauces, Soups, Rigid Foods Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Bluegrass Ingredients, Inc., Commercial Creamery Company, Dairy Farmers of America, Inc., Hoosier Hill Farm LLC, Rogers & Company Foods Pty Ltd, The Food Source International Inc., Thrive Life LLC, Tsukuba Dairy Products Co., Ltd., Varesco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sour Cream Powder Market Emerging Trajectories
Processing technology convergence and regulatory transparency mandates are reshaping competitive differentiation around fermentation control, drying efficiency, and supply-chain traceability rather than commodity scale alone.
Encapsulated lipid technologies are expanding into sour cream powder formulations to protect volatile flavor compounds through high-heat snack seasoning applications. Major seasoning houses in the United States are piloting these materials for extended shelf-life targets. This protection capability is expanding into premium positioning for export markets with lengthy distribution cycles.
REACH chemical safety protocols in Europe are tightening residual solvent limits for dairy-derived ingredients entering food manufacturing. Suppliers must validate extraction and drying processes against ECHA substance restrictions. Powder exporters to Germany and France face extended certification timelines and third-party testing costs.
Direct-procurement relationships between snack manufacturers and dairy powder cooperatives are displacing traditional ingredient distributor intermediaries. Large-scale chip producers negotiate volume contracts with drying facilities for customized fat content and fermentation profiles. This disintermediation concentrates most visibly in the Midwest, where production proximity enables just-in-time delivery to seasoning operations.
Sour Cream Powder Market Segmentation
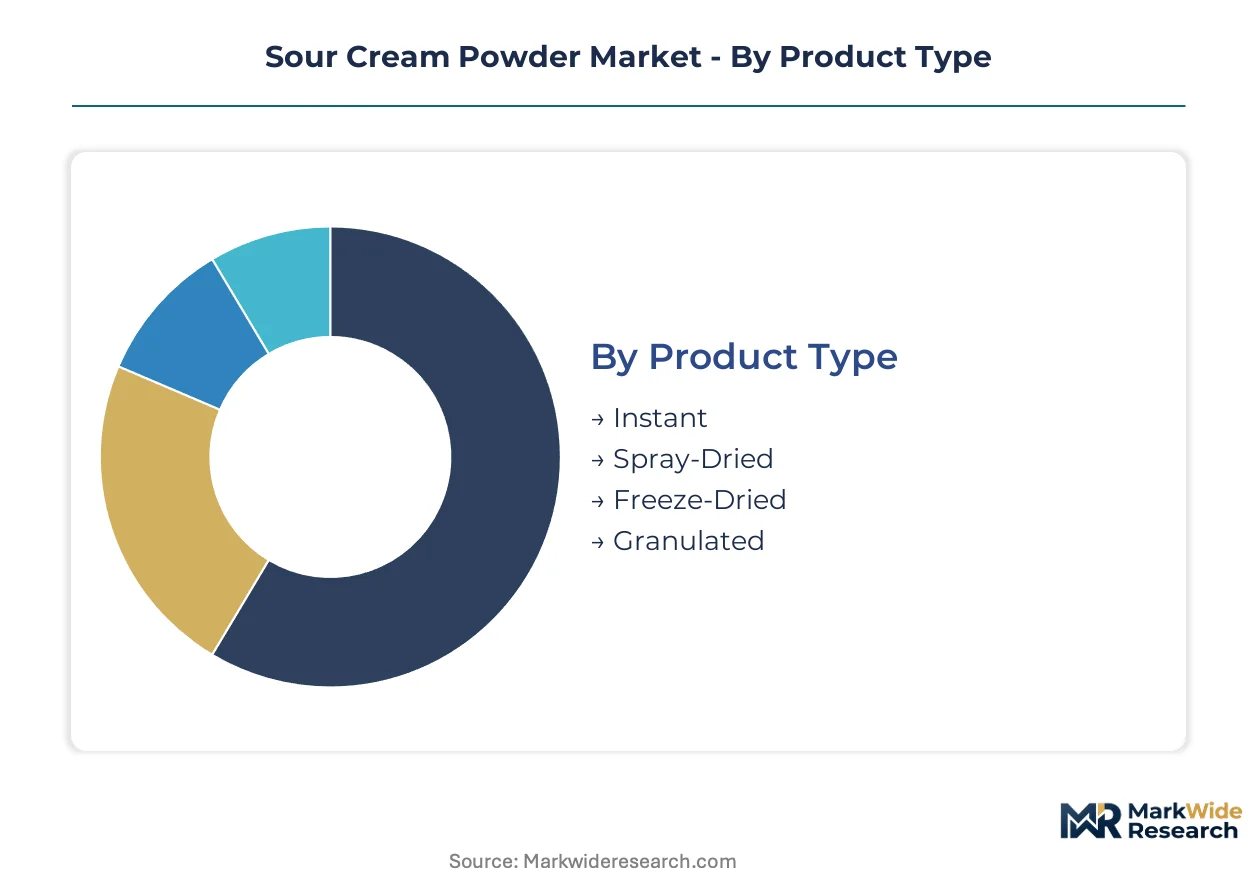
Sour cream powder manufacturers configure production lines around distinct functional specifications demanded by downstream processing environments. Each segmentation axis reveals divergent margin structures and technical compliance requirements that shape supplier positioning.
Product Type:
Standardization dominates the commodity end of this spectrum, while premium tiers reward proprietary drying protocols and flavor retention engineering.
- Spray-Dried:Dominant production method employs high-temperature atomization to reduce moisture below 4%, yielding dispersible powders for high-volume seasoning operations. Food processing facilities in the United States absorb the bulk of procurement, driven by retort-stable sauce formulations that tolerate heat exposure without flavor degradation.
- Freeze-Dried:Sublimation drying preserves volatile lactic acid compounds and aromatic esters, producing intense flavor profiles for gourmet seasoning blends. Specialty snack producers and craft food manufacturers pay price multiples for enhanced organoleptic retention in low-moisture applications.
- Instant:Agglomerated particles with modified surface properties enable rapid rehydration in ambient-temperature water, serving foodservice operators with limited heating infrastructure.
- Granulated:Coarse particle sizing reduces dusting during pneumatic conveying systems, preferred by industrial bakeries with automated dosing equipment.
Leading the category by volume: Spray-Dried. Growing fastest: Freeze-Dried.
End User:
Volume concentration versus formulation complexity splits this axis, with commodity buyers prioritizing unit economics and specialty accounts demanding certificate-backed provenance.
- Snacks:Seasoned chip and extruded snack manufacturers deploy sour cream powder in high-temperature coating drums where liquid dairy would trigger moisture defects. Bulk procurement concentrates among Midwestern production facilities with integrated seasoning lines.
- Food Processing:Ready-meal and sauce manufacturers specify cultured dairy powders for shelf-stable formulations undergoing retort or aseptic processing. FDA dairy identity standards compel clean-label declarations that exclude synthetic acidifiers.
- Bakery:Industrial bread and cracker operations incorporate powder into dry mixes for extended distribution cycles without refrigeration dependency.
- Dairies:Fluid milk processors use sour cream powder as a standardized ingredient in cultured product lines, leveraging consistent fat content and fermentation profiles.
Snacks command the largest shipment volumes. Food Processing shows the steepest expansion trajectory as retort-ready meal formats proliferate.
Application:
Moisture sensitivity and thermal exposure tolerance differentiate use cases, with each application imposing distinct shelf-life and processing constraints.
- Seasonings:Dry blend formulations for snack coatings and tabletop shakers require free-flowing powders with anti-caking properties. Encapsulated lipid technologies are penetrating this segment to protect flavor compounds through high-heat application.
- Sauces:Powdered bases for institutional and retail sauce mixes demand rapid reconstitution without lumping. Clean-label mandates from FDA modernization drive substitution of synthetic stabilizers with cultured dairy solids.
- Soups:Dehydrated soup manufacturers specify low-moisture dairy powders for cup and pouch formats with extended ambient storage requirements.
- Rigid Foods:Extruded and baked goods incorporate sour cream powder for flavor and fat contribution in structurally stable matrices.
Seasonings absorb the highest tonnage. Sauces are climbing the fastest on ready-meal format expansion.
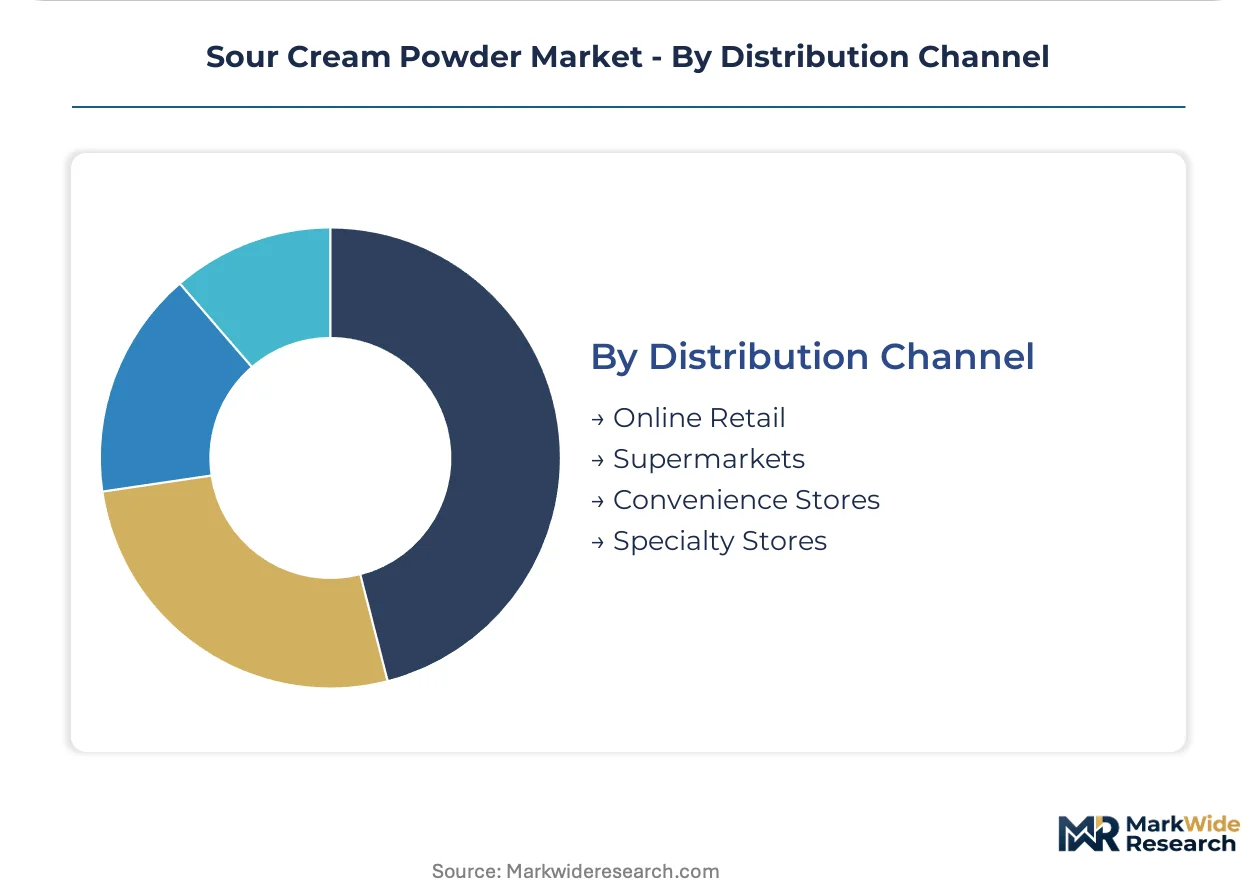
Distribution Channel:
Procurement scale and technical service requirements fragment this axis, with industrial buyers bypassing traditional intermediaries.
- Online Retail:E-commerce platforms serve small-scale food manufacturers and ingredient brokers with fractional pallet quantities and rapid specification lookup.
- Supermarkets:Mass-market retail channels move consumer-packaged sour cream powder for home cooking applications, though volumes remain marginal against industrial segments.
- Convenience Stores:Limited shelf space restricts presence to single-serve and emergency-replacement formats with minimal brand variety.
- Specialty Stores:Gourmet and natural product retailers stock organic and small-batch freeze-dried variants for premium home chefs and artisan food producers.
Direct procurement from drying cooperatives is displacing distributor intermediaries for volume accounts. Online Retail is gaining share fastest among emerging food brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's Fox River Valley anchors North American spray-drying capacity, with Kentucky's Bluegrass region forming a secondary cluster for dairy powder production serving seasoning houses and sauce manufacturers.
United States
Midwest snack seasoning operations and ready-meal producers drive bulk procurement of spray-dried dairy powders. FDA dairy identity standards compel manufacturers to reformulate with recognizable cultured dairy ingredients rather than synthetic acidifiers. Wisconsin and Kentucky production facilities supply dispersible powders for high-temperature coating operations at chip manufacturers.
Germany
REACH chemical safety protocols tighten residual solvent limits for dairy-derived ingredients entering food manufacturing. ECHA substance restrictions require validation of extraction and drying processes against extended certification timelines. Powder exporters face third-party testing costs and prolonged approval cycles for German and French distribution.
Japan
Specialty snack producers and craft food manufacturers import freeze-dried variants for enhanced flavor intensity retention. METI standards govern food additive specifications and import documentation for dairy-derived ingredients. Tsukuba Dairy Products Co., Ltd. anchors domestic production in the Ibaraki prefecture corridor.
Australia
Industrial bakeries and dry-mix manufacturers incorporate sour cream powder for extended distribution cycles without refrigeration dependency. Food Standards Australia New Zealand mandates allergen declaration protocols for dairy-derived ingredients. Melbourne and Sydney processing facilities source spray-dried powders for cracker and biscuit operations.
Brazil
ANVISA regulates dairy ingredient imports with sanitary certification requirements for spray-dried powders entering sauce and seasoning formulations. São Paulo state food processors specify low-moisture dairy powders for ambient storage distribution to retail channels. Southeast industrial corridors concentrate procurement for extruded snack seasoning applications.
Sour Cream Powder Market Vendor Landscape
Premium-margin players sit above commodity-margin players across fermentation control and drying efficiency capabilities. The supplier base clusters around cooperative-backed milk supply security, specialized cultured dairy formulations, and integrated drying operations. Three archetypes dominate: dairy cooperatives with captive milk supply, independent specialty powder formulators, and diversified ingredient houses with seasoning expertise. Capacity expansion and direct-procurement relationship building constitute the dominant competitive moves as snack manufacturers bypass traditional distributor intermediaries.
Among North American cooperative-backed suppliers, Dairy Farmers of America, Inc. exemplifies scale-driven volume leadership through integrated drying operations. Bluegrass Ingredients, Inc. and Commercial Creamery Company occupy differentiated positions within the specialty formulation tier, with the former leveraging Kentucky production proximity to Midwest seasoning houses and the latter anchoring industrial sauce applications through proprietary cultured powder protocols.
| Leading Market Players |
|---|
| Bluegrass Ingredients, Inc. |
| Commercial Creamery Company |
| Dairy Farmers of America, Inc. |
| Hoosier Hill Farm LLC |
| Rogers & Company Foods Pty Ltd |
| The Food Source International Inc. |
| Thrive Life LLC |
| Tsukuba Dairy Products Co., Ltd. |
| Varesco Group |
| Others |
Supply Flow & Price Mechanics
Captive milk supply integration through cooperative structures anchors both procurement stability and margin defense for sour cream powder manufacturers facing volatile CME Group butterfat futures. This backward control over raw cream inputs simultaneously insulates standard-grade producers from commodity swings while enabling premium-tier suppliers to command fermentation-traceability premiums.
Pricing Analysis
Yield-based pricing anchors sour cream powder valuation, with freeze-dried variants commanding multiples against spray-dried grades due to lactic acid retention performance in high-heat applications. Three-tier pricing structure across premium, standard, and economy levels tracks fat content precision, organic certification status, and dispersibility specifications. Cost compression in standard-grade segments is intensifying because Midwest spray-drying capacity expansion outpaces seasoning house demand growth. Snack manufacturers with high-volume coating operations exhibit greatest price sensitivity, while gourmet seasoning blenders prioritize flavor intensity over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Wisconsin and Kentucky spray-drying clusters, where regional weather disruptions and logistics congestion threaten just-in-time delivery to Midwest seasoning houses. Raw material flows draw from Upper Midwest dairy cooperatives, Pennsylvania creameries, and Canadian cross-border milk pooling arrangements. Tariff exposure on Canadian skim solids and whey derivatives feeds into reformulation cost uncertainty for standardized powder grades. Distribution runs through direct-procurement contracts between drying cooperatives and snack manufacturers, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sour cream powder market consolidation accelerates as FSMA documentation burdens and clean-label reformulation cycles force sub-scale dry-mix suppliers toward cooperative absorption or exit.
For Market Incumbents: Anchor fermentation-control capabilities as the primary defensive moat against synthetic acidifier substitution threats from cost-pressured sauce manufacturers. Deepen captive milk supply through cooperative equity expansion in Wisconsin and Kentucky production corridors. Pursue USDA organic certification arbitrage ahead of supply-constrained natural product brand procurement cycles. For New Entrants and Emerging Players: Artisan sauce manufacturers and craft snack startups represent the most penetrable buyer archetype for freeze-dried premium variants with certificate-backed provenance. Target EU Green Deal-aligned export channels with methane-reduction verification for low-carbon dairy ingredient sourcing requirements. Deploy direct sampling programs at specialty food trade shows to bypass established distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in cooperative-backed acquisition by Dairy Farmers of America or Bluegrass Ingredients seeking fermentation-traceability capabilities. Long-term viability favors suppliers with integrated drying operations and organic certification infrastructure rather than toll-processing dependent entrants. Monitor CME Group butterfat futures volatility as the inflection signal for margin compression severity across standard-grade powder specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cream Supply | Cooperative equity stakes in Wisconsin dairy farms secure input cost predictability against CME volatility. |
| Freeze-Drying Capacity Expansion | Gourmet seasoning house procurement preference for flavor-intensity retention justifies premium positioning. |
| USDA Organic Certification Program | Natural product brand procurement pipelines remain undersupplied relative to conventional grade availability. |
| Direct-Procurement Relationship Building | Large-scale chip manufacturers negotiate volume contracts bypassing traditional ingredient distributor margins. |
| EU Green Deal Compliance Investment | Methane-reduction verification unlocks entry paths for North American suppliers into German and French manufacturing. |
Methodological Framework
Document review covered FDA dairy identity standard filings, USDA organic certification databases, and CME Group dairy commodity futures data, complemented by interviews with spray-drying facility operations managers, snack manufacturer procurement directors, and seasoning house formulation chemists. Secondary validation drew from SEC 10-K disclosures of cooperative-backed suppliers, EU ECHA substance restriction updates, and ANVISA sanitary certification requirements. Bottom-up shipment estimates from individual drying facilities were triangulated against top-down demand modeling from end-use consumption patterns.
Volume and value trajectories across the projection horizon reflect segmented modeling by drying technology, fat content tier, certification status, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical procurement volumes adjusted for clean-label reformulation intensity and retort-ready meal format proliferation. Forecast inputs incorporated butterfat cost volatility assumptions and FSMA preventive controls implementation timelines.
Revisions become necessary when FDA dairy identity standard finalization, EU REACH solvent limit enforcement, or Midwest logistics disruption events materialize beyond baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market