
 South America Food Flavor Market | 2026-2036
South America Food Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Flavor Market Analytics
Food manufacturers is reorganizing procurement priorities around clean-label and natural-positioned formulations, pulling flavor suppliers toward botanical extraction capabilities and away from synthetic portfolios. Givaudan SA anchors its regional presence through specialized natural ingredient sourcing networks across the Andes. Kerry Group PLC leverages integrated taste and nutrition platforms to compete for multinational food manufacturer contracts. BASF SE sustains R&D intensity in enzyme-modified flavor precursors that reduce sodium dependency in savory applications.
Food flavors encompass volatile and non-volatile compounds—esters, aldehydes, terpenes, pyrazines, and Maillard reaction products—formulated at parts-per-million precision to deliver consistent sensory profiles in processed foods, beverages, and culinary preparations. Natural flavor extracts command premium positioning as extraction technologies improve yield recovery from native botanicals including açaí, yerba mate, and Andean fruits. The application dimension shows beverages outpacing bakery and confectionery in formulation change velocity, while dairy applications retain mature, slower-moving demand for traditional vanilla and fruit profiles. End-user concentration tilts toward food manufacturers with captive R&D labs, leaving restaurants and catering services as fragmented, price-sensitive accounts served through distributor intermediaries.
ANVISA governs flavor additive approvals and maximum usage levels in Brazil, while Argentina's national food safety authority enforces Mercosur-aligned additive codexes that restrict certain artificial flavor carriers. These frameworks elevate compliance costs for imported synthetic flavor portfolios while creating preferential market access for domestically extracted natural ingredients certified under national organic standards. Stakeholders must monitor regulatory divergence between Mercosur harmonization timelines and Chile's independent FDA-equivalent pathway, which is accelerating its own clean-label additive review schedule.
Market Dynamics
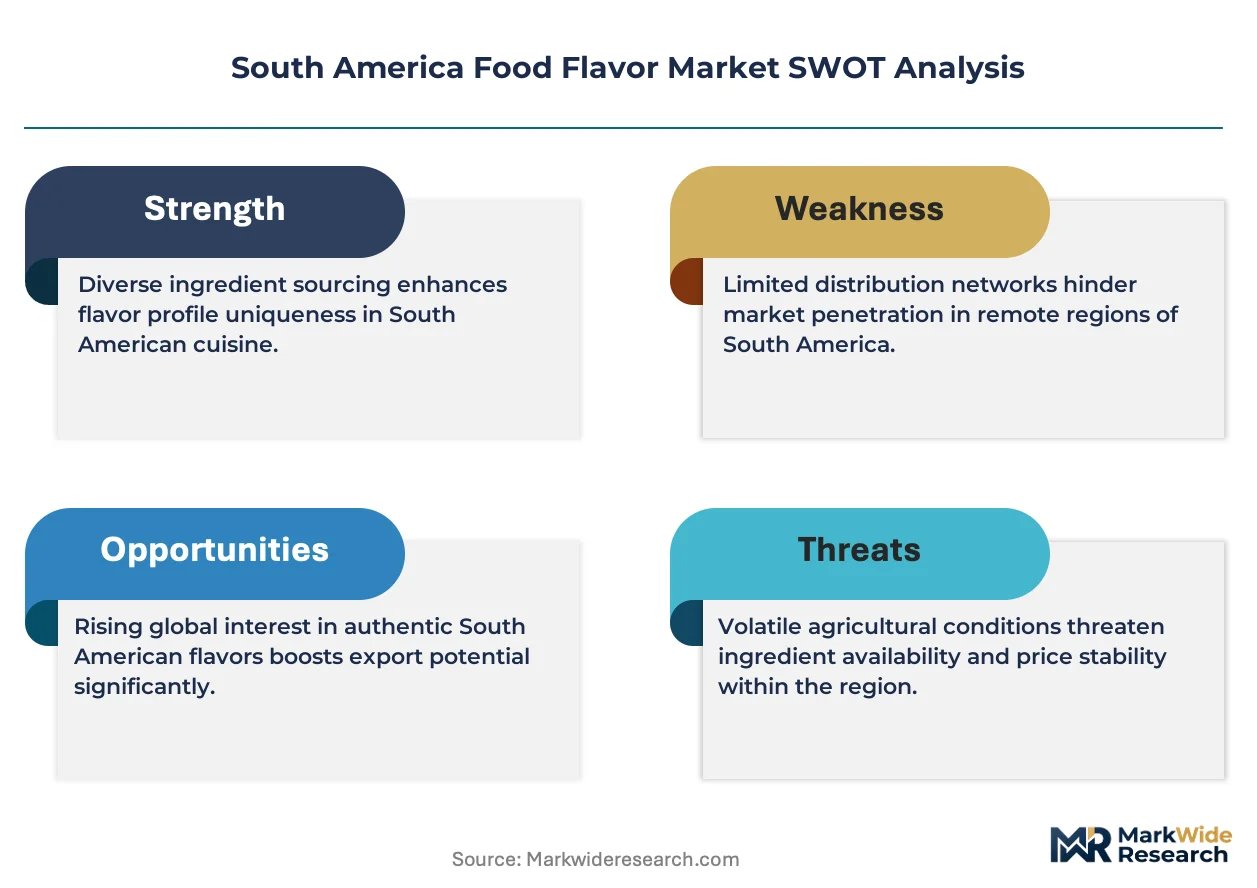
Clean-label procurement mandates from São Paulo-based beverage conglomerates are forcing flavor houses to dismantle synthetic portfolios and rebuild around Andean botanical extraction networks. This structural pivot concentrates supplier power among firms with captive organic certification chains.
Growth Catalysts
- ANVISA reform trajectory:Brazil's updated additive approval pathways accelerate natural extract certifications, compressing time-to-market for yerba mate and açaí-derived flavor compounds.
- Beverage formulation velocity:Carbonated soft drink and ready-to-drink tea manufacturers in Argentina's Buenos Aires province are replacing artificial ester portfolios with enzyme-modified natural precursors.
- Mercosur harmonization:Aligned maximum usage levels across Brazil, Argentina, Uruguay and Paraguay reduce cross-border compliance fragmentation for regional flavor suppliers.
Market Restraints
- Organic botanical input scarcity:Certified organic açaí and camu camu harvests concentrate in Amazonas state, exposing processors to climate-induced yield volatility.
- Extraction equipment import dependency:Supercritical CO2 extraction systems for terpene recovery rely on European and Asian original equipment manufacturers, extending lead times.
- Natural extract cost premium:Botanical-derived flavor compounds carry three-to-five-fold ingredient cost multiples versus synthetic alternatives, constraining adoption in price-anchored confectionery segments.
Strategic Opportunities
- Colombia Andean corridor penetration:Bogotá-based processed food clusters remain under-supplied with regional natural flavor networks, creating first-mover positioning for extraction-capable entrants.
- Plant-based dairy flavor systems:Oat and almond milk manufacturers require masking technologies and creamy flavor precursors distinct from traditional dairy profiles.
- Chile clean-label acceleration:The national food safety authority's independent additive review schedule favors botanical-certified imports ahead of Mercosur alignment timelines.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise in Maillard reaction control and natural precursor stability remains concentrated in legacy synthetic-trained talent pools.
- Organic certification timeline compression:ANVISA's expedited natural additive approvals outpace domestic organic supply chain certification capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Flavor Market |
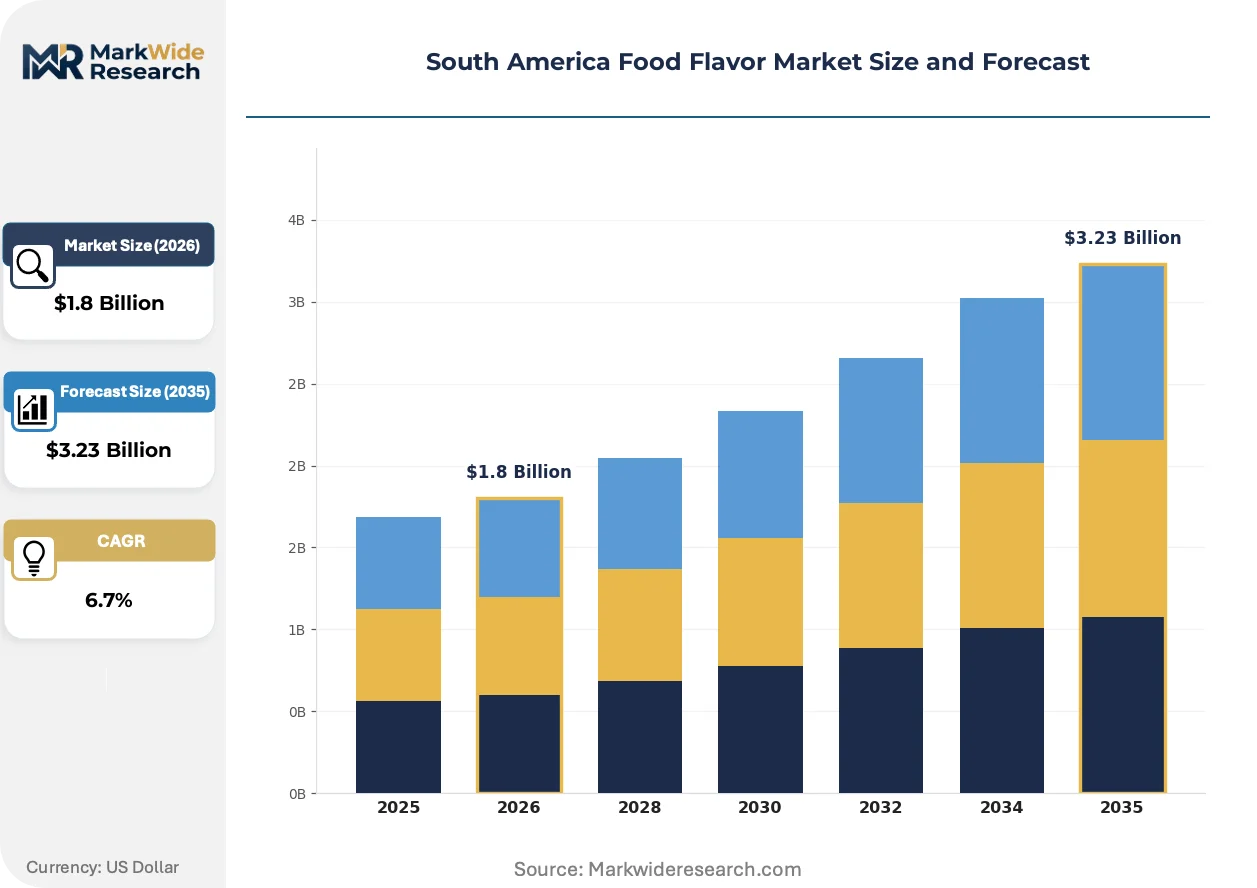
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Natural, Artificial, Organic, Extracts Application: Bakery, Dairy, Beverages, Confectionery End User: Food Manufacturers, Restaurants, Catering Services, Retail Chains Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | International Flavors & Fragrances Inc. (IFF), BASF SE, Givaudan SA, Archer Daniels Midland (ADM), Koninklijke DSM NV, Firmenich SA, Kerry Group PLC, Sensient Technologies, Symrise AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Flavor Market Evolving Landscape
Extraction technology maturation and regulatory preference alignment are splitting the supplier base into synthetic-legacy and botanical-native capabilities. This divergence reshapes competitive positioning around certification depth rather than formulation breadth.
Supercritical CO2 extraction systems for terpene and essential oil recovery are bifurcating the mid-tier flavor house segment. Brazilian beverage manufacturers with captive R&D labs are adopting these systems at accelerated procurement cycles. The technology is compressing synthetic terpene demand while elevating price premiums for cold-pressed Andean botanical extracts with traceable harvest documentation.
ANVISA's 2025-2026 implementation schedule for updated food additive maximum usage levels is tightening synthetic carrier allowances in beverage applications. Industrial consequence includes forced portfolio restructuring among import-dependent synthetic flavor traders. Argentina's national food safety authority is responding with parallel Mercosur-aligned codex revisions, compressing regulatory arbitrage windows between member states.
Direct procurement relationships between São Paulo beverage conglomerates and Andean extraction cooperatives are displacing traditional distributor-mediated supply chains. Regional flavor houses with captive sourcing networks capture volume commitments previously fragmented across multiple intermediaries. This pattern concentrates most visibly in açaí and cupuaçu extract categories where harvest traceability commands formulation priority.
South America Food Flavor Market Segmentation
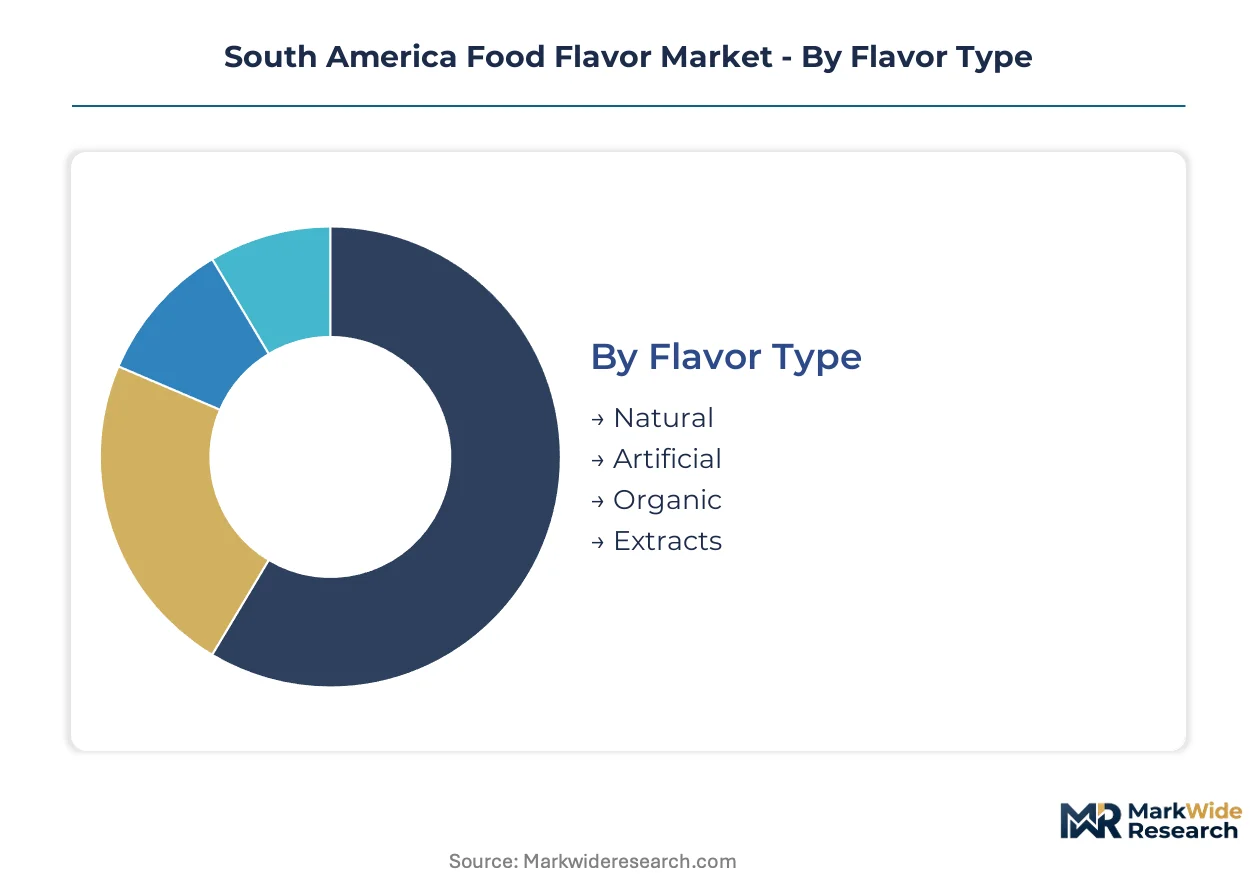
Flavor procurement patterns in South America diverge sharply across formulation types and application channels. Clean-label mandates from Brazilian beverage conglomerates and ANVISA's regulatory trajectory are compressing synthetic segment viability while elevating botanical extraction premiums.
Flavor Type:
Natural extracts face the most acute substitution pressure as synthetic portfolios dismantle under regulatory and procurement mandates.
- Natural:Botanical-derived compounds from yerba mate, açaí, and Andean fruits command formulation priority in São Paulo beverage corridors. ANVISA's expedited certification pathways compress time-to-market for certified organic extracts, though supply concentrates in Amazonas state with climate exposure.
- Extracts:Supercritical CO2 and cold-pressed terpene recovery systems elevate price premiums for traceable harvest documentation. Brazilian manufacturers with captive R&D labs are accelerating procurement of these systems, displacing synthetic terpene demand in carbonated soft drink applications.
- Artificial:Ester and aldehyde portfolios face forced restructuring as Mercosur-aligned codexes restrict maximum usage levels in beverage applications.
- Organic:Certified supply chains lag behind ANVISA approval velocity, creating input scarcity for processors dependent on Amazonas harvests.
Natural anchors the volume base while Extracts gains share at the steepest rate.
Application:
Cost tier stratification separates premium-positioned beverage formulations from price-anchored confectionery segments.
- Beverages:Carbonated soft drink and ready-to-drink tea manufacturers in Buenos Aires province are replacing artificial ester portfolios with enzyme-modified natural precursors. Kerry Group and Givaudan compete for multinational contracts through integrated taste platforms.
- Confectionery:Three-to-five-fold ingredient cost multiples for botanical extracts constrain adoption in price-sensitive segments. Synthetic carriers retain residual demand where regulatory windows permit.
- Bakery:Maillard reaction products and vanilla profiles show slower formulation velocity than beverage applications.
- Dairy:Traditional vanilla and fruit profiles dominate mature demand, though oat and almond milk manufacturers require distinct masking technologies and creamy flavor precursors.
Beverages commands the premium tier while Confectionery remains volume-constrained by cost premiums.
End User:
Customer type concentration tilts procurement power toward entities with captive technical capabilities.
- Food Manufacturers:São Paulo-based conglomerates with in-house R&D labs are forging direct procurement relationships with Andean extraction cooperatives. This pattern displaces traditional distributor-mediated supply chains in açaí and cupuaçu extract categories.
- Restaurants:Fragmented demand aggregates through regional distributor networks with limited formulation technical support.
- Catering Services:Price-sensitive accounts rely on commodity-grade flavor portfolios with minimal clean-label positioning.
- Retail Chains:Private-label procurement teams are accelerating natural extract specifications for store-brand beverage lines.
Food Manufacturers anchors procurement volume while Retail Chains expands specifications most aggressively.
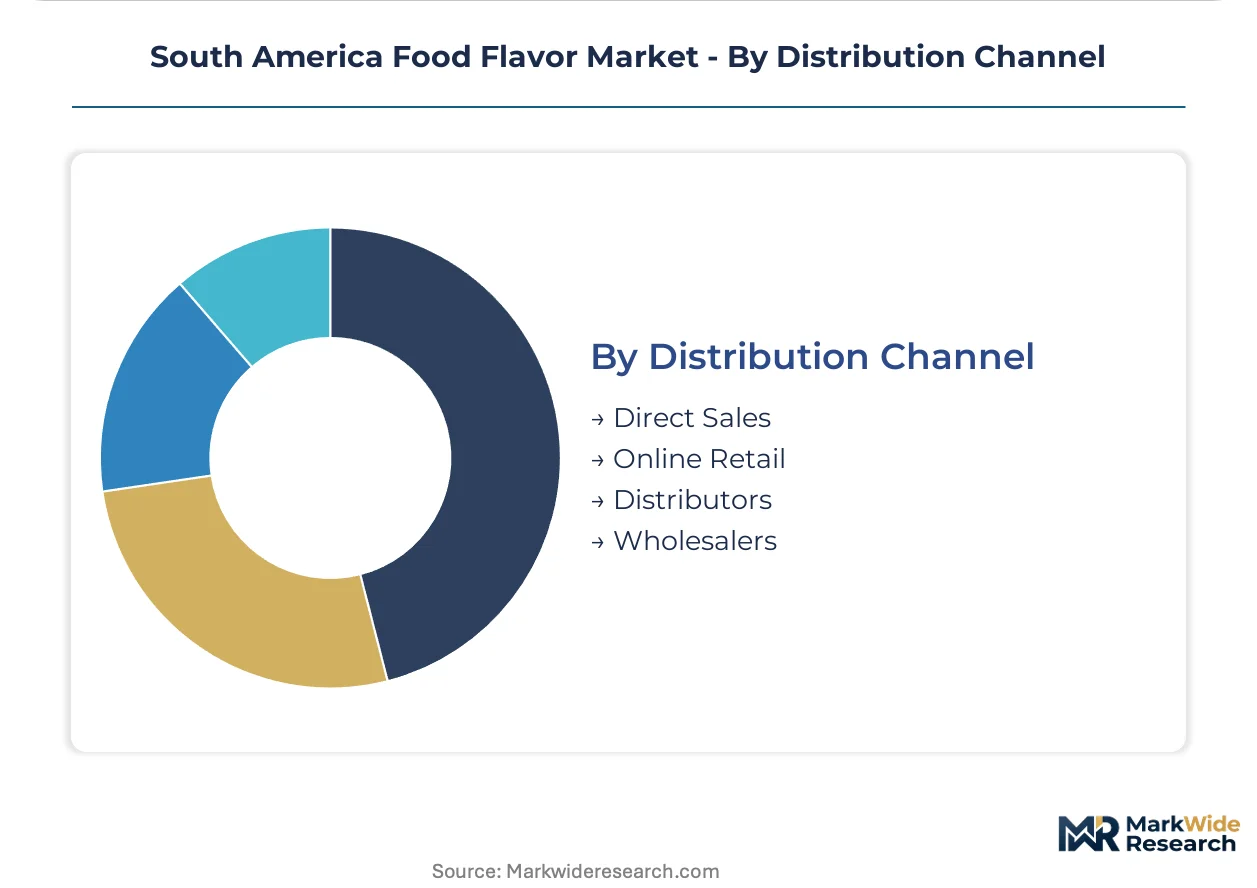
Distribution Channel:
Supply concentration in São Paulo and Buenos Aires corridors shapes channel viability for regional versus imported portfolios.
- Direct Sales:Flavor houses with captive Andean sourcing networks capture volume commitments previously fragmented across multiple intermediaries. Givaudan's specialized natural ingredient networks exemplify this structure.
- Distributors:Traditional intermediaries face margin compression as beverage conglomerates bypass tier-one distribution for extraction cooperative relationships.
- Wholesalers:Commodity-grade synthetic portfolios flow through these channels to price-anchored confectionery and catering segments.
- Online Retail:Limited penetration for industrial-scale flavor procurement; serves small-batch food service and artisanal manufacturer segments.
Direct Sales captures the premium segment while Distributors retains commodity-grade volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports botanical extracts to Argentina's Buenos Aires beverage corridor, while Chile imports enzyme-modified flavor precursors from Andean processing networks. Paraguay and Uruguay serve as transshipment nodes for Mercosur-aligned regulatory compliance.
Brazil
São Paulo state's industrial corridor concentrates multinational flavor house operations alongside processed food clusters. ANVISA's updated additive approval pathways compress certification timelines for yerba mate and açaí-derived compounds. Amazonas state harvests supply certified organic inputs, though climate exposure creates yield volatility for supercritical CO2 extraction facilities.
Argentina
Buenos Aires province beverage manufacturers accelerate procurement of natural precursors to replace artificial ester portfolios. The national food safety authority enforces Mercosur-aligned codex revisions that restrict synthetic carrier maximum usage levels. Córdoba's agro-industrial belt hosts emerging extraction cooperatives serving carbonated soft drink formulation labs.
Chile
Santiago-based food manufacturers source botanical-certified imports ahead of Mercosur alignment timelines. The national food safety authority operates an independent FDA-equivalent pathway accelerating clean-label additive reviews. Valparaíso's port infrastructure handles cold-pressed Andean extract shipments with traceable harvest documentation requirements.
Colombia
Bogotá processed food clusters remain under-supplied with regional natural flavor networks, creating positioning opportunities for extraction-capable entrants. The national food safety authority maintains separate additive review schedules from Mercosur harmonization efforts. Medellín's beverage R&D labs increasingly specify enzyme-modified natural precursors for local formulation.
Uruguay
Montevideo serves as a compliance coordination hub for cross-border flavor ingredient trade within Mercosur. The national food safety authority participates in aligned maximum usage level negotiations across Brazil, Argentina, Paraguay and Uruguay. Local distributors handle residual synthetic portfolio volumes displaced from São Paulo direct procurement relationships.
South America Food Flavor Market Competitive Landscape
Listed leaders compete with private specialists across extraction technology and certification depth. The supplier base concentrates among firms with captive organic supply chains, while import-dependent synthetic traders face forced portfolio restructuring. Three archetypes dominate: integrated taste-nutrition platforms, specialized botanical sourcing networks, and enzyme-modified precursor developers. Competitive moves center on dismantling synthetic portfolios and rebuilding around Andean cooperative relationships, alongside accelerated supercritical CO2 equipment procurement.
Within the integrated platform tier, Kerry Group PLC and Givaudan SA exemplify divergent approaches to regional positioning. Kerry leverages combined taste and nutrition capabilities for multinational food manufacturer contracts. Givaudan anchors presence through specialized natural ingredient sourcing networks across the Andes. BASF SE occupies a position among precursor technology developers, sustaining R&D intensity in enzyme-modified flavor systems that reduce sodium dependency. These three entities represent the structural pivot toward botanical-native capabilities and away from synthetic-legacy portfolios.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. (IFF) |
| BASF SE |
| Givaudan SA |
| Archer Daniels Midland (ADM) |
| Koninklijke DSM NV |
| Firmenich SA |
| Kerry Group PLC |
| Sensient Technologies |
| Symrise AG |
| Others |
Value Network & Pricing Analysis
Ninety-to-120-day lead times for supercritical CO2 extraction equipment from European and Asian OEMs concentrate procurement power among São Paulo beverage conglomerates with advance order pipelines, while compressing margins for mid-tier flavor houses forced into spot-market botanical purchases.
Pricing Analysis
Prior-generation synthetic ester portfolios trade at three-to-five-fold discounts versus current-generation cold-pressed Andean botanical extracts with traceable harvest documentation. Pricing stratifies across premium certified-organic tiers, standard natural-extract grades, and residual synthetic-economy levels for price-anchored confectionery segments. Cost compression in the synthetic tier is intensifying because ANVISA's reform trajectory accelerates natural additive approvals. Food manufacturers with captive R&D labs exhibit least price sensitivity; catering services through distributor intermediaries show greatest price elasticity.
Supply Chain Analysis
Inventory cycles for certified organic açaí and camu camu concentrates in Amazonas state fluctuate with climate-induced harvest volatility, exposing processors to input scarcity. Supply concentrates in Brazil's São Paulo-Amazonas corridor, Argentina's Buenos Aires-Córdoba belt, and Chile's Valparaíso-Santiago logistics nodes. Raw material dependencies center on Andean botanical harvests, enzyme-modified flavor precursors, and supercritical CO2 extraction systems. Single-source vulnerability runs through European and Asian OEM equipment suppliers. Distribution feeds from direct procurement relationships between beverage conglomerates and extraction cooperatives, displacing traditional distributor-mediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among São Paulo-based beverage conglomerates with captive R&D labs and direct Andean cooperative relationships, fragmenting traditional distributor intermediaries into margin-compressed residual channels.
For Market Incumbents: Compound defensive positioning through backward integration into Amazonas state organic certification chains and accelerated supercritical CO2 equipment procurement ahead of competitor order pipelines. Synthetic-legacy portfolio exposure to ANVISA's reform trajectory demands urgent restructuring around botanical-native capabilities. Channel control through direct extraction cooperative relationships represents the priority lever against distributor displacement. For New Entrants and Emerging Players: Differentiate on Andean corridor penetration with cold-pressed terpene recovery systems targeting Bogotá's under-supplied processed food clusters. Colombia's national food safety authority maintains additive review schedules separate from Mercosur harmonization, creating regulatory arbitrage windows. Plant-based dairy flavor systems for oat and almond milk manufacturers offer the most penetrable application segment. Go-to-market through enzyme-modified precursor specialization reduces sodium dependency formulation appeal. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational flavor houses with stranded synthetic-legacy portfolios seeking botanical-native capability acquisitions. Long-term viability favors entities with captive organic supply chains and supercritical extraction infrastructure across the analysis window. Watch for ANVISA certification timeline compression signals indicating organic input scarcity inflection points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amazonas Organic Certification | Captive supply of açaí and camu camu inputs insulates against climate-induced yield volatility. |
| Supercritical CO2 Equipment Procurement Acceleration | Advance order pipelines with European OEMs secure terpene recovery capacity ahead of competitor demand. |
| Direct Extraction Cooperative Relationships | Bypass of distributor intermediaries captures volume commitments from São Paulo beverage conglomerates. |
| Enzyme-Modified Precursor R&D Expansion | Sodium reduction formulations align with ANVISA's clean-label additive approval trajectory. |
| Colombia Andean Corridor Market Entry | First-mover positioning in Bogotá's under-supplied processed food clusters ahead of regional competitor expansion. |
Research Methodology
Desk research of ANVISA regulatory filings, Mercosur codex harmonization documents, and Brazilian customs trade data preceded structured interviews with flavor chemists at São Paulo beverage R&D labs, procurement directors at multinational food manufacturers, extraction cooperative managers in Amazonas state, and supercritical equipment OEM technical sales leads. Secondary validation drew from ANVISA additive approval databases, national organic certification registries, and South American trade flow records. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Variance decomposition across flavor type, application, end-user concentration, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price-tier mix assumptions. Forecast inputs incorporated ANVISA implementation schedule phasing, Mercosur alignment timelines, and supercritical equipment procurement cycle observations.
Decision-makers should treat outputs as directional under assumptions of continued ANVISA reform trajectory, sustained Mercosur harmonization progress, and stable climate patterns in Amazonas harvest zones; material deviation in regulatory velocity or botanical yield would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
Pine Bark Extract Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Citrus Flavors Market