
 Water Flavoring Drop Market | 2026-2036
Water Flavoring Drop Market Size, Share, and Industry Trends Forecast 2026-2036
Water Flavoring Drop Market Insights
Single-source flavor procurement is realigning toward multi-supplier networks as concentrate costs fluctuate. The Coca-Cola Company leverages captive beverage science labs to secure proprietary flavor matrices. PepsiCo anchors North American shelf presence through direct-store-delivery infrastructure. Nestlé S.A. differentiates its portfolio with mineral-enhanced drop formulations targeting wellness positioning.
Water flavoring drops are concentrated liquid additives, typically dosed at one to three milliliters per eight-ounce serving, comprising natural or synthetic flavor compounds, acidulants, and optional sweeteners dissolved in a propylene glycol or glycerin carrier base; they transform plain water into palatable beverages without carbonation equipment. Sugar-free options dominate volume in developed markets where calorie labeling mandates intensify scrutiny of added sweeteners. Natural flavors command premium placement in health stores and specialty shops, while synthetic variants sustain economy-tier positioning in mass retail. Fitness enthusiasts and athletes drive fastest-growing demand for electrolyte-fortified drops with functional mineral claims.
FDA food additive regulations and EFSA flavoring substance evaluations govern permissible compounds and labeling declarations across major markets. USDA organic certification and EU organic regulations create tiered market access for organic extract formulations, with uncertified products excluded from premium channel placement. Stakeholders must monitor evolving sweetener safety assessments and front-of-pack warning label expansions that could reshape permissible claims and channel eligibility.
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to abandon synthetic flavor compounds and rebuild supply chains around certified organic extracts, compressing margins while opening premium channel access.
Growth Catalysts
- Households with children:Parents seeking hydration alternatives to sugar-sweetened beverages drive repeat purchase velocity in mass retail channels.
- FDA food additive regulations:Stricter safety evaluations elevate consumer trust in compliant brands, accelerating category legitimacy.
- Propylene glycol carrier innovation:Improved solubility profiles enable cleaner taste delivery without clouding or separation.
Market Restraints
- Natural extract cost volatility:Weather-dependent botanical harvests in Madagascar and India concentrate input price risk.
- USDA organic certification scarcity:Limited accredited extract suppliers create bottlenecks for clean-label product launches.
- Plain bottled water substitution:Commodity-priced still water retains price-sensitive household volumes.
Strategic Opportunities
- Electrolyte-fortified positioning:Fitness enthusiasts and amateur athletes represent an underserved functional segment.
- Direct-to-subscription models:Recurring delivery platforms bypass slotting fee barriers in consolidated retail.
- EFSA novel food approvals:Emerging botanical extracts from non-traditional sourcing regions await regulatory clearance for EU market entry.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise bridging natural extract behavior and shelf stability commands premium compensation.
- Front-of-pack warning label compliance:Expanding sweetener disclosure mandates in Latin American markets require packaging redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Flavoring Drop Market |
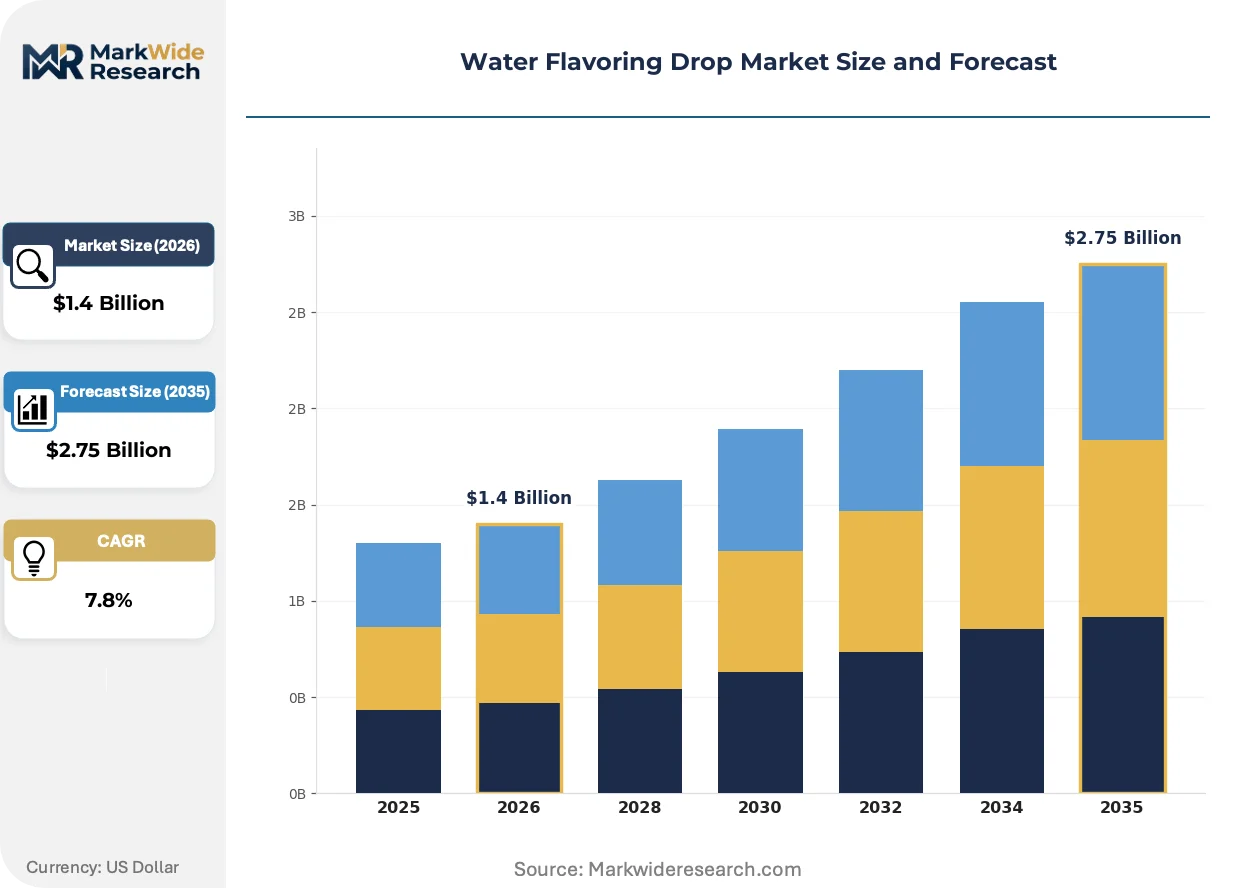
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Sugar-Free Options, Organic Extracts Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops End User: Fitness Enthusiasts, Health-Conscious Consumers, Families, Athletes Flavor Preference: Fruit Flavors, Herbal Flavors, Exotic Flavors, Spice Flavors |
| Companies Covered | The Coca-Cola Company, The Kraft Heinz Company, Nestlé S.A., PepsiCo, Stur Drinks, Nuun Hydration, Capella Flavors, Wisdom Natural Brands, True Citrus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Flavoring Drop Market Trends and Innovations
Formulation science and regulatory positioning are converging to reshape competitive differentiation, with natural extraction methods and functional fortification claiming disproportionate R&D investment.
Microencapsulation technology for volatile citrus and berry extracts is overtaking traditional heat-extraction methods. Premium health-store brands and direct-to-consumer startups are adopting cold-press and CO2 extraction at scale. This shift is overtaking legacy flavor houses that rely on standardized synthetic matrices, compressing their economy-tier pricing power.
EFSA flavoring substance evaluations are tightening permissible compound lists ahead of 2026 renewal cycles. Manufacturers face reformulation costs for synthetic variants losing authorized status. Natural-certified portfolios in Germany and France are capturing shelf space as retailers pre-empt compliance risk.
Subscription-based replenishment is displacing impulse-driven supermarket purchases among urban professionals. Amazon Subscribe and Save and specialized wellness platforms are capturing household pantry stocking. This pattern concentrates in coastal US metropolitan markets where delivery density minimizes shipping cost barriers.
Water Flavoring Drop Market Segmentation
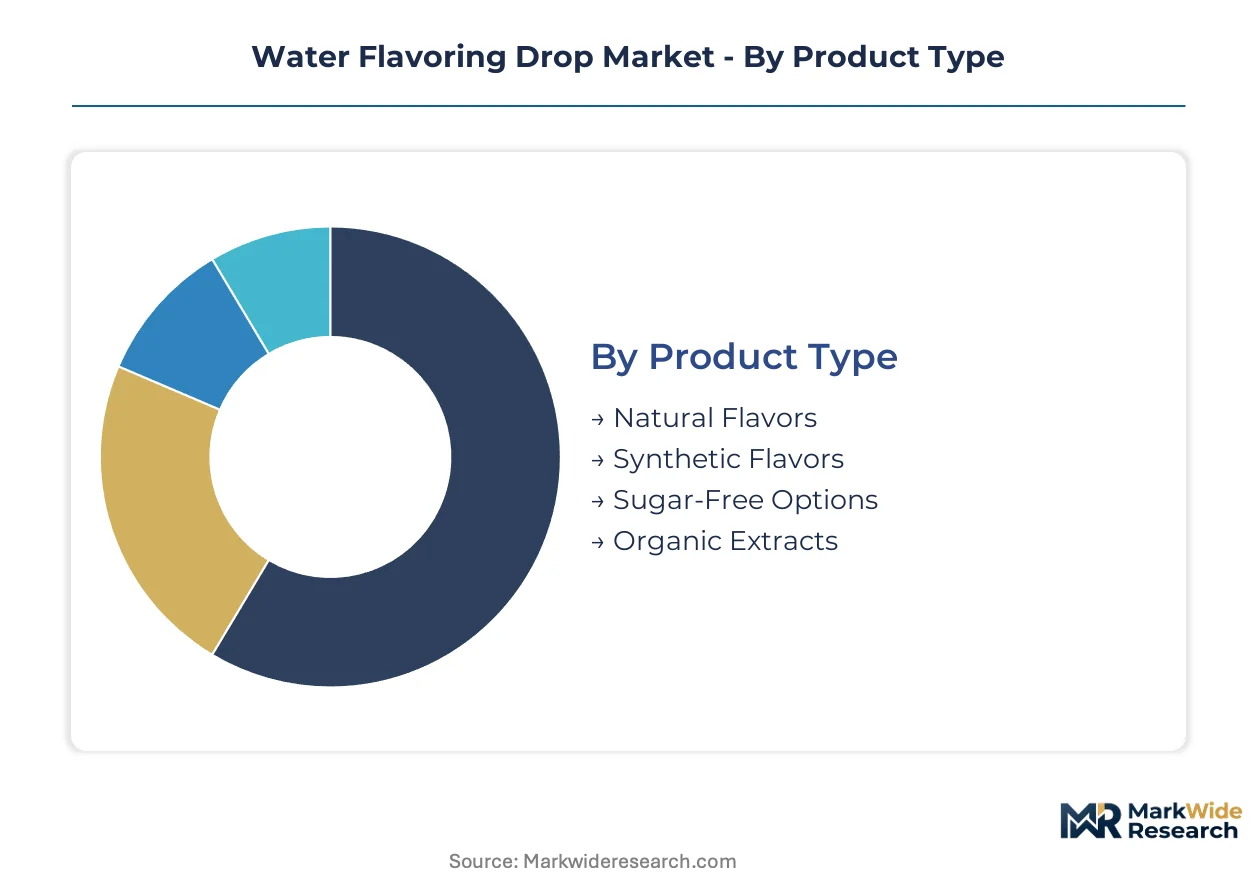
Water flavoring drop manufacturers segment demand across four dimensions to match formulation investment with channel economics. Each category reveals distinct upgrade cycles: households trade up from synthetic to natural variants, while fitness users drive functional repositioning.
Product Type:
Reformulation cycles accelerate as households replace legacy drops with cleaner-label alternatives, compressing product lifecycles from three years toward eighteen months.
- Natural Flavors:Cold-pressed citrus, berry, and botanical extracts suspended in glycerin carriers without synthetic solvents. Clean-label households in the United States pay shelf-price premiums for USDA-certified variants, though Madagascar vanilla and Indian cardamom supply interruptions constrain volume scaling.
- Synthetic Flavors:Standardized ester and aldehyde compounds manufactured in captive flavor science facilities. Economy-tier positioning in mass retail sustains volume, yet EFSA substance evaluations threaten authorization renewals for several high-volume compounds.
- Sugar-Free Options:Stevia, monk fruit, or sucralose-sweetened formulations targeting calorie-labeling compliance.
- Organic Extracts:USDA or EU organic certified botanicals with full traceability documentation.
Sugar-free options sit at the top of the volume ranking, with organic extracts climbing the fastest.
Distribution Channel:
Channel selection determines margin capture, with slotting fee structures favoring incumbent beverage conglomerates over emerging brands.
- Online Retail:Amazon Subscribe and Save and direct-to-consumer wellness platforms bypass retail gatekeeping. Urban coastal households drive recurring replenishment with delivery density minimizing shipping cost barriers.
- Supermarkets:Kroger, Walmart, and Target shelf placement demands promotional spend and direct-store-delivery infrastructure. PepsiCo and The Coca-Cola Company leverage existing beverage routes to secure prime positioning.
- Health Stores:Whole Foods and regional co-ops require third-party clean-label certifications.
- Specialty Shops:Boutique fitness studios and running stores with curated functional assortments.
Supermarkets dominate absolute volume throughput, while online retail expands most quickly.
End User:
User archetypes dictate formulation complexity, with performance demands justifying premium pricing against commodity hydration alternatives.
- Fitness Enthusiasts:Amateur athletes seeking electrolyte fortification without carbonation. Sodium, potassium, and magnesium mineral claims drive repeat purchase in running and CrossFit communities.
- Health-Conscious Consumers:Wellness-oriented households scrutinizing ingredient panels and front-of-pack disclosures.
- Families:Parents replacing sugar-sweetened beverages for children, driving mass-market velocity.
- Athletes:Competitive performers requiring precise electrolyte ratios and rapid hydration protocols.
Families generate the highest absolute purchase frequency, with fitness enthusiasts gaining share fastest.
Flavor Preference:
Flavor portfolio breadth determines retail shelf allocation and manufacturing complexity trade-offs.
- Fruit Flavors:Lemon, lime, berry, and tropical variants comprising the core volume base. Citrus extracts face volatile pricing from Florida and Brazil growing region weather patterns.
- Herbal Flavors:Mint, basil, and lavender botanicals targeting spa and wellness positioning.
- Exotic Flavors:Yuzu, lychee, and passionfruit variants differentiating premium lines.
- Spice Flavors:Ginger, cinnamon, and chai profiles for seasonal and adult-palate targeting.
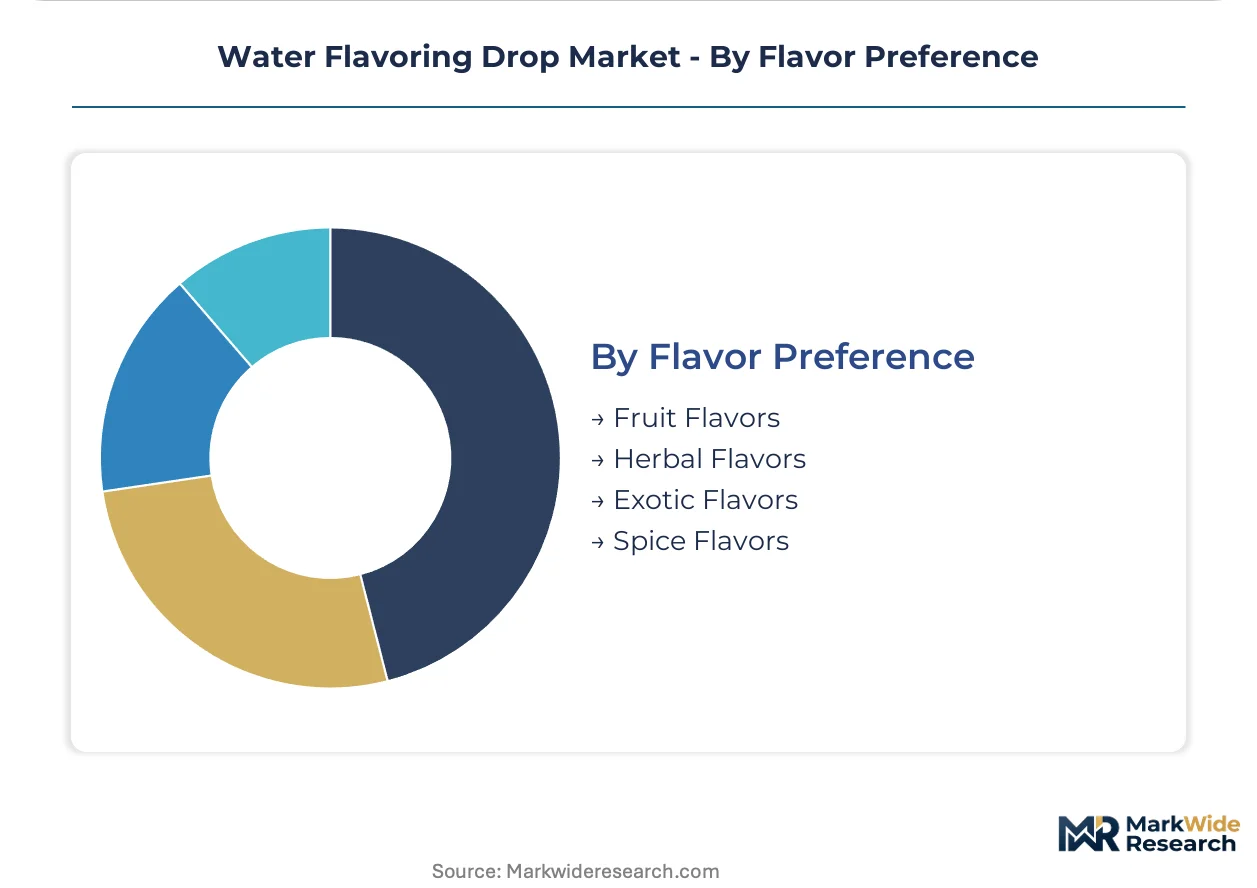
Fruit flavors anchor baseline production runs, with exotic flavors showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States beverage science clusters dominate formulation innovation and clean-label certification infrastructure. Household penetration rates for sugar-free drops exceed comparable developed markets. FDA food additive evaluations and USDA organic certification programs shape permissible claims and channel access.
United States
Families with children drive repeat purchase velocity through mass retail channels. FDA food additive regulations under 21 CFR Part 172 govern permissible flavor compounds and sweetener safety assessments. New Jersey and California host captive beverage science laboratories where The Coca-Cola Company and PepsiCo develop proprietary flavor matrices.
Germany
Wellness-oriented households scrutinize ingredient panels and front-of-pack disclosures with exceptional intensity. EFSA flavoring substance evaluations under Regulation (EC) No 1334/2008 determine authorized compound lists ahead of 2026 renewal cycles. Hamburg and Munich concentrate clean-label brand development as retailers pre-empt compliance risk.
United Kingdom
Subscription-based replenishment displaces impulse-driven supermarket purchases among urban professionals. Food Standards Agency enforcement of retained EU flavoring regulations maintains strict labeling requirements. London anchors direct-to-consumer wellness platform headquarters where recurring delivery models achieve critical density.
France
ANSM and DGCCRF oversight of food contact materials influences carrier base selection for glycerin formulations. Île-de-France hosts mineral-enhanced drop development targeting spa and wellness positioning. Paris retail channels capture premium placement for organic-certified portfolios.
Japan
Fitness enthusiasts and amateur athletes drive demand for electrolyte-fortified functional formulations. Ministry of Health, Labour and Welfare Food Sanitation Act governs permitted food additives and labeling standards. Tokyo-Osaka corridor concentrates specialty health store distribution and boutique fitness studio partnerships.
Water Flavoring Drop Market Competitive Landscape
Global majors compete with regional champions across formulation science and distribution infrastructure. The market exhibits tiered concentration with beverage conglomerates commanding mass retail shelf space through direct-store-delivery networks. Three archetypes dominate: captive flavor science laboratories, mineral-enhanced wellness specialists, and direct-to-consumer subscription platforms. Competitive moves center on backward integration into certified organic extract sourcing and geographic licensing agreements for novel botanical approvals.
Within the global beverage conglomerate tier, The Coca-Cola Company, PepsiCo, and Nestlé S.A. occupy positions defined by scale-driven route-to-market advantages. The Coca-Cola Company exemplifies captive beverage science capabilities. PepsiCo anchors North American shelf presence through established distribution infrastructure. Nestlé S.A. represents mineral-enhanced wellness positioning with traceability-focused formulations.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| The Kraft Heinz Company |
| Nestlé S.A. |
| PepsiCo |
| Stur Drinks |
| Nuun Hydration |
| Capella Flavors |
| Wisdom Natural Brands |
| True Citrus |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap flavor houses in the United States and Germany anchor upstream extract sourcing, tightening pricing discipline as Madagascar vanilla and Indian cardamom harvest volatility feeds into margin compression. Their concentrated ownership structures limit external financing for inventory buffers, amplifying cost pass-through sensitivity when botanical supply tightens.
Pricing Analysis
Input-cost pass-through from weather-dependent botanical harvests drives pricing stratification across premium, standard, and economy tiers. Cold-pressed citrus extracts from Florida and Brazil concentrate price differentiation around certification grade and carrier base quality. Cost compression in synthetic flavor tiers is intensifying because EFSA substance evaluations threaten authorization renewals. Families with children exhibit highest price sensitivity, while fitness enthusiasts tolerate premium positioning for electrolyte fortification.
Supply Chain Analysis
Direct-to-subscription channels handle recurring replenishment demand from urban coastal households, bypassing traditional retail gatekeeping. Propylene glycol and glycerin carrier bases draw from petrochemical and oleochemical suppliers concentrated in the United States, Germany, and China. Single-source vulnerability in Madagascar vanilla and Indian cardamom extracts creates concentrated input risk. Distribution runs through Amazon Subscribe and Save, direct-to-consumer wellness platforms, and direct-store-delivery networks serving mass retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Water Flavoring Drop Market functions as a stable compounder, with household hydration habit formation driving predictable replenishment velocity across economic cycles.
For Market Incumbents: Anchor shelf positioning through direct-store-delivery infrastructure investments that emerging brands cannot replicate. Deepen captive supply of USDA-certified organic extracts before accreditation bottlenecks worsen. Defend against direct-to-consumer subscription platforms by locking in multi-year category captain agreements with Kroger and Walmart.
For New Entrants and Emerging Players: Begin with electrolyte-fortified functional positioning targeting boutique fitness studios and running stores where incumbent coverage remains thin. The specialty fitness channel offers lowest competitive density and highest willingness-to-pay for mineral-enhanced formulations. Pursue influencer partnerships with CrossFit and marathon communities to bypass slotting fee barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional clean-label specialists with certified organic portfolios and underdeveloped subscription infrastructure. The five-to-ten-year viability window favors targets with backward integration into traceable extract sourcing. Monitor EFSA novel food approval timelines as the inflection signal for EU market expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Extract Sourcing | USDA organic certification scarcity creates captive supply advantages for compliant manufacturers. |
| Direct-to-Consumer Subscription Launch | Amazon Subscribe and Save and wellness platforms capture recurring pantry replenishment from urban professionals. |
| Electrolyte Fortification Expansion | Fitness enthusiasts and amateur athletes drive fastest-growing demand for functional mineral claims. |
| EFSA Novel Food Approval Pursuit | Emerging botanical extracts from non-traditional regions await regulatory clearance for EU market entry. |
| Microencapsulation Technology Adoption | Cold-press and CO2 extraction methods overtake legacy heat-extraction for volatile citrus and berry compounds. |
Research Methodology
Direct dialogue with flavor chemists, beverage science directors, retail category buyers, and organic certification auditors grounds qualitative findings in operational reality. Secondary validation draws from FDA food additive filings, EFSA flavoring substance evaluations, USDA organic certification databases, and Nielsen retail audit data. Bottom-up and top-down triangulation cross-checks manufacturer production estimates against channel shipment volumes and household penetration surveys.
Bottom-up modeling builds from individual SKU pricing and volume assumptions across product type, distribution channel, end user, and flavor preference segments. Top-down verification benchmarks aggregate manufacturer capacity and category velocity against macro beverage consumption trends. CAGRs derive from segment-level growth rate blending weighted by current revenue contribution. Forecast inputs include botanical harvest yield projections, regulatory approval timelines, and subscription platform customer acquisition costs.
Several conditions sit outside the modeled scope, including sudden EFSA compound authorization withdrawals, extreme weather events in Madagascar or India, and front-of-pack warning label mandate expansions beyond Latin America. Forecasts reflect assumptions about clean-label preference persistence and subscription adoption saturation levels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Keto Friendly Flavors Market