
 Mexico Food Enzymes Market | 2026-2036
Mexico Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Food Enzymes Market Foresight
The split between premium specialty enzymes and commodity-grade formulations is realigning procurement patterns across Mexican food manufacturing. Kerry Group PLC leverages its integrated ingredient platforms to anchor supply relationships with multinational processors operating in Querétaro and Jalisco. BASF competes through biotechnology leadership in protease development, while ENMEX sustains domestic production scale that controls cost structures for mid-tier bakery clients.
Food enzymes are protein-based biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific chemical reactions in food matrices without becoming consumed in the process. Their primary commercial purpose centers on improving process efficiency, modifying texture, enhancing flavor profiles, and extending shelf stability across industrial food production. Proteases command the largest functional share in meat processing applications where tenderization and protein recovery drive volume, while lipases exhibit the fastest structural growth in dairy flavor modification and reduced-fat cheese systems. The liquid form dominates installed processing equipment compatibility, though powder formulations capture margin pools in small-batch bakery and nutraceutical blending operations.
COFEPRIS maintains primary authority over enzyme safety approvals and maximum usage levels in finished foods, while NOM-051 labeling standards shape how manufacturers communicate enzyme-derived modifications to consumers. The Secretariat of Economy's alignment with CODEX Alimentarius frameworks facilitates export market access for enzyme-treated Mexican food products. Stakeholders must monitor pending amendments to NOM-130 for bakery products, as these revisions could redefine permitted enzyme categories and force reformulation decisions across central Mexico's processing base.
Market Dynamics
COFEPRIS tightening of additive safety assessments is forcing Mexican food manufacturers toward label-friendly enzyme reformulations, compressing approval timelines while expanding demand for clean-label biocatalysts in central Mexico's processing corridors.
Growth Catalysts
- Clean-label bakery reformulation:NOM-051 labeling standards drive tortilla and bread producers toward enzyme-based dough conditioners that replace chemical additives. Guadalajara manufacturers lead adoption.
- Dairy protein recovery expansion:Protease deployment in cheese whey processing improves yield economics for Jalisco dairy cooperatives. Lipase flavor modification commands premium positioning in reduced-fat systems.
- CODEX export alignment:Secretariat of Economy harmonization with international standards opens EU and US market access for enzyme-treated Mexican food products. Querétaro multinationals leverage this pathway.
Market Restraints
- Specialty enzyme cost volatility:Fermentation-grade raw material prices fluctuate with global carbohydrate feedstock markets. Mid-tier bakeries face margin compression.
- Import dependency concentration:Biotechnology leadership resides with European and North American suppliers. Domestic production scale at ENMEX covers only commodity protease and amylase segments.
- Thermostability limitations:Standard enzyme formulations degrade above 60°C in high-temperature processing lines. Tortilla extrusion operations require engineered variants.
Strategic Opportunities
- Yucatán Peninsula penetration:Underdeveloped food processing infrastructure in southeastern Mexico creates first-mover positioning for enzyme suppliers establishing regional technical service.
- Plant-based meat texturization:Emerging application for transglutaminase and protease cross-linking in pea and soy protein systems. Monterrey startups pilot commercial runs.
- NOM-130 bakery amendment anticipation:Pending regulatory revision could expand permitted enzyme categories. Formulation-ready suppliers capture switching volume.
Industry Challenges
- Enzymologist talent scarcity:Industrial biocatalysis expertise concentrates in Mexico City and Guadalajara. Regional processors face recruitment bottlenecks.
- Legacy equipment incompatibility:Powder-to-liquid formulation transitions require stainless steel tankage and precision dosing systems. Small-batch bakeries defer capex.
- COFEPRIS dossier complexity:Novel enzyme approvals demand toxicological and stability documentation. Submission timelines extend 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Food Enzymes Market |
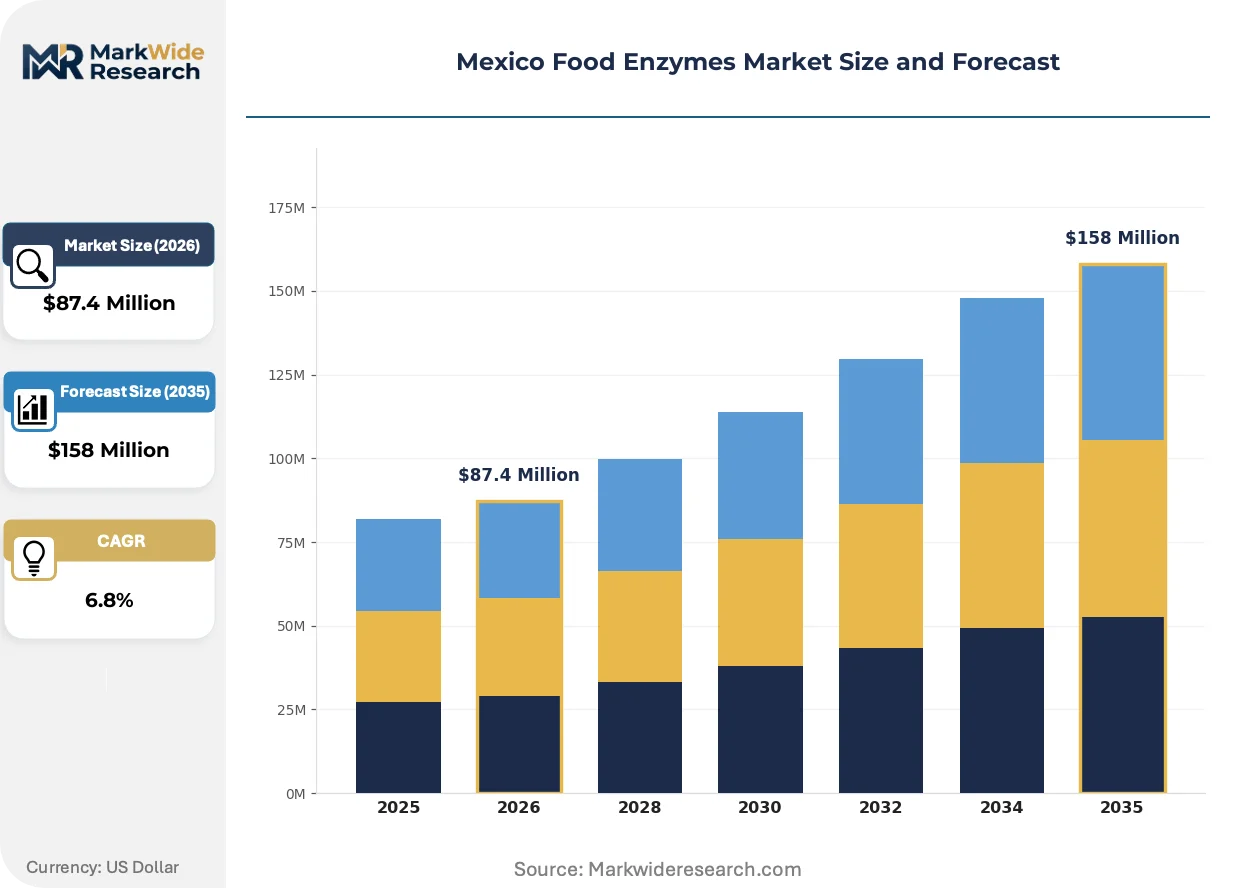
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Baking, Dairy, Beverages, Meat Processing Form: Liquid, Powder, Granular, Tablets End User: Food Manufacturers, Beverage Producers, Bakery Retailers, Nutraceutical Companies |
| Companies Covered | Kerry Group PLC, Amano Enzyme Inc, Koninklijke DSM NV, BASF, Novozymes, Chr Hansen Holding AS, DuPont de Nemours Inc, Associated British Foods PLC, ENMEX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Food Enzymes Market Shifts & Advancements
Biotechnology advancement and regulatory stringency are converging to reshape enzyme deployment patterns across Mexican food manufacturing, with liquid formulation dominance giving way to application-specific delivery systems.
Cell-free enzyme production is decentralizing manufacturing economics by eliminating fermentation infrastructure requirements. Jalisco dairy processors adopt on-site enzyme immobilization for continuous lipase operations. This technology is decentralizing supply chain risk away from concentrated import corridors.
NOM-130 pending amendments for bakery products are recalibrating permitted additive categories. Reformulation timelines compress as manufacturers pre-position enzyme alternatives ahead of final rule publication. Central Mexico tortilla producers accelerate protease and amylase trials to maintain process continuity.
Direct-procurement platforms are shortening enzyme sourcing cycles for mid-tier processors. Traditional distributor networks face disintermediation as Querétaro multinationals negotiate integrated supply agreements with biotechnology suppliers. This pattern concentrates most visibly in baking and dairy verticals where volume scale justifies bypass arrangements.
Mexico Food Enzymes Market Segmentation
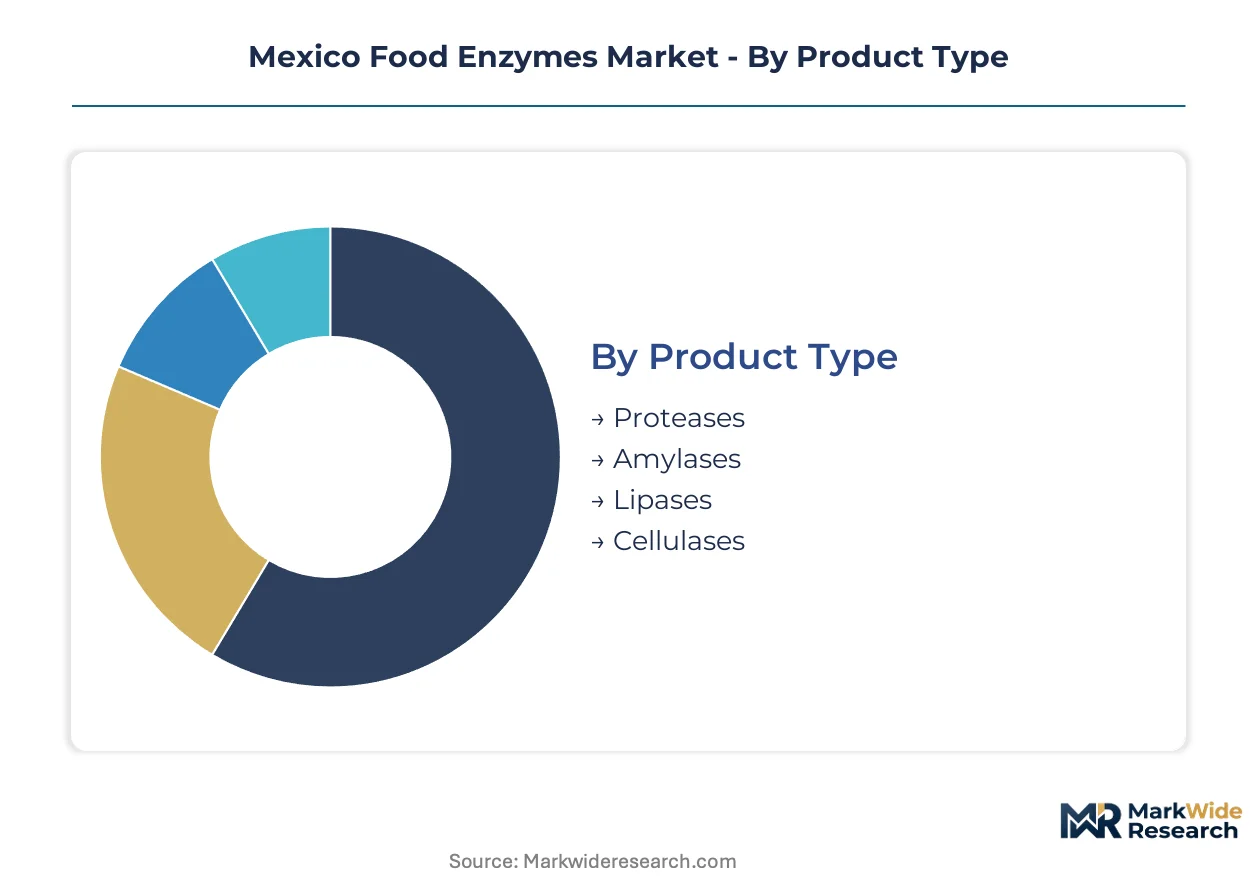
Enzyme selection in Mexico hinges on COFEPRIS classification tiers, with each product category carrying distinct dossier requirements that reshape procurement economics. Manufacturers navigate formulation trade-offs between performance specifications and regulatory pathway complexity.
Product Type:
COFEPRIS maintains separate approval tracks for proteases versus carbohydrases, with lipases facing additional toxicological scrutiny due to potential allergen cross-reactivity in dairy applications.
- Proteases:These protein-hydrolyzing enzymes operate optimally at 45-55°C and pH 6.0-7.5, cleaving peptide bonds to modify texture and accelerate aging. Jalisco dairy cooperatives deploy proteases for whey protein recovery, where yield economics justify premium positioning against commodity alternatives.
- Amylases:Starch-degrading enzymes catalyze dextrinization and sugar release in dough systems, functioning across 50-70°C with calcium ion dependence. Guadalajara tortilla manufacturers dominate volume consumption, driven by NOM-130 reformulation pressures that displace chemical conditioners.
- Lipases:Ester-hydrolyzing biocatalysts generate free fatty acids for flavor development in reduced-fat cheese matrices.
- Cellulases:Cell wall-degrading enzymes improve extraction yields in fruit processing and modify fiber texture in bakery applications.
Proteases sit at the top of the volume ranking, with lipases climbing the fastest.
Application:
End-use concentration determines margin capture, with baking corridors in central Mexico absorbing commodity-grade volumes while dairy verticals sustain specialty pricing.
- Baking:Enzyme deployment spans dough conditioning, shelf-life extension, and crumb structure modification in bread and tortilla production. Mexico City and Guadalajara processors lead adoption as NOM-051 labeling standards force chemical additive replacement.
- Dairy:Protease and lipase systems optimize cheese yield, accelerate ripening, and enable flavor replication in reduced-fat formulations. Querétaro multinationals anchor demand for high-activity concentrates.
- Beverages:Pectinases and amylases clarify fruit juices and modify carbohydrate profiles in fermented drinks.
- Meat Processing:Protease tenderization and transglutaminase cross-linking improve texture and binding in processed protein systems.
Baking commands the largest installed base, with dairy applications gaining share fastest.
Form:
Physical format selection constrains equipment compatibility, with liquid systems requiring stainless steel infrastructure that small-batch operators defer.
- Liquid:Aqueous enzyme concentrates enable precision dosing through automated injection systems, dominating high-volume continuous processing lines. Querétaro multinational facilities specify liquid formats for integration with existing CIP infrastructure.
- Powder:Spray-dried formulations offer extended ambient stability and simplified logistics for regional distributors. Mid-tier bakeries in Monterrey prefer powders for manual batch incorporation.
- Granular:Dust-free agglomerated particles reduce inhalation exposure in handling operations.
- Tablets:Unit-dose solid formats target small-scale nutraceutical blending and artisanal bakery segments.
Liquid formulations dominate value concentration, with powder alternatives expanding most quickly in regional penetration.
End User:
Customer scale fragments procurement behavior, with integrated manufacturers negotiating direct supply agreements while smaller operators rely on distributor networks.
- Food Manufacturers:Large-scale processors operating in Querétaro and Jalisco negotiate integrated supply agreements with biotechnology suppliers, bypassing traditional distribution. Volume scale justifies dedicated technical service and formulation customization.
- Beverage Producers:Fruit juice and fermented drink processors deploy pectinases and glucoamylases for clarification and carbohydrate modification.
- Bakery Retailers:In-store production operations in Mexico City metro area source enzyme-conditioned flour from toll millers.
- Nutraceutical Companies:Specialty enzyme suppliers serve protein hydrolysate and digestive supplement manufacturers with pharmaceutical-grade documentation.
Food manufacturers anchor volume demand, with nutraceutical companies expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial biocatalysis expertise clusters in Mexico City and Guadalajara, anchoring formulation development and technical service capabilities that radiate outward to regional processing corridors. This talent concentration shapes enzyme adoption patterns across distinct sub-national markets.
Mexico City Metro
Bakery manufacturers dominate enzyme procurement for dough conditioning and shelf-life extension in tortilla and bread production. COFEPRIS maintains its headquarters here, streamlining dossier submissions for novel enzyme approvals. Multinational processors in Toluca and Cuautitlán Izcalli operate integrated supply agreements with biotechnology suppliers.
Jalisco
Dairy cooperatives deploy protease systems for whey protein recovery and lipase formulations for reduced-fat cheese flavor modification. The state's alignment with CODEX export frameworks facilitates EU market access for enzyme-treated products. Guadalajara anchors both processing volume and technical service infrastructure for central Mexico.
Nuevo León
Monterrey startups pilot transglutaminase and protease applications in pea and soy protein texturization for plant-based meat systems. The state's industrial base supports precision dosing equipment deployment for liquid enzyme formats. Regional distributors face disintermediation as direct-procurement platforms gain traction.
Bajío Region
Querétaro multinationals negotiate bypass arrangements with European and North American enzyme suppliers, leveraging volume scale for dedicated technical service. NOM-130 pending amendments drive pre-positioning of protease and amylase alternatives among tortilla producers. The corridor exhibits fastest adoption of cell-free enzyme production technologies.
Yucatán Peninsula
Underdeveloped food processing infrastructure creates first-mover positioning for suppliers establishing regional technical service capabilities. Mérida and Cancún processing operations rely on powder formulations due to deferred stainless steel tankage investments. ENMEX commodity-grade coverage extends here, though specialty enzyme access depends on import logistics.
Mexico Food Enzymes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Mexico food enzymes market, with fermentation infrastructure requirements separating integrated manufacturers from formulation specialists. The structure fragments across three tiers: multinational biotechnology leaders, regional integrated ingredient platforms, and domestic commodity-scale producers. Strategic moves concentrate on portfolio diversification toward label-friendly biocatalysts and geographic expansion into underpenetrated southeastern corridors.
Among European biotechnology leaders, Kerry Group PLC and BASF occupy positions exemplifying integrated platform and biotechnology specialization archetypes respectively. Kerry leverages its ingredient systems to anchor supply relationships with Querétaro multinationals, while BASF competes through protease development leadership. ENMEX represents the domestic production archetype, sustaining commodity-scale operations that control cost structures for mid-tier bakery clients in central Mexico.
| Leading Market Players |
|---|
| Kerry Group PLC |
| Amano Enzyme Inc |
| Koninklijke DSM NV |
| BASF |
| Novozymes |
| Chr Hansen Holding AS |
| DuPont de Nemours Inc |
| Associated British Foods PLC |
| ENMEX |
| Others |
Supply & Pricing Matrix
Captive supply arrangements among Querétaro multinationals anchor both procurement leverage and pricing discipline across Mexico's food enzyme market. COFEPRIS regulatory complexity rewards integrated buyers with dedicated technical service tiers while compressing margins for spot-market dependent operators.
Pricing Analysis
The bundled-vs-unbundled service split separates enzyme procurement into integrated supply agreements versus distributor-mediated transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with COFEPRIS dossier complexity adding compliance premiums to novel enzyme categories. Cost compression in commodity protease segments is intensifying because ENMEX domestic scale controls mid-tier bakery pricing. Small-batch tortilla producers in Monterrey exhibit highest price sensitivity, while Querétaro multinationals prioritize formulation customization over unit cost.
Supply Chain Analysis
Direct-to-multinational channels handle hyperscale buyer demand from Querétaro and Jalisco processing corridors, while regional distributors serve mid-tier bakeries with powder formulations. Biotechnology leadership draws from Denmark, the Netherlands, and the United States, with fermentation-grade carbohydrate feedstocks resting on global agricultural commodity markets. Single-source vulnerability concentrates in specialty lipase supply for dairy flavor modification. Distribution runs through integrated ingredient platforms for volume accounts and independent distributors for regional penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are tightening across Mexican food manufacturing as NOM-051 labeling standards displace chemical additives with enzyme-based alternatives, elevating premium biocatalyst demand.
For Market Incumbents: Extend formulation customization capabilities to anchor Querétaro multinational relationships against direct-procurement platform disintermediation. Deepen backward integration into cell-free enzyme production to reduce fermentation infrastructure dependency and compress cost structures for Jalisco dairy verticals. COFEPRIS dossier complexity serves as a defensive moat if toxicological documentation capabilities are maintained. For New Entrants and Emerging Players: NOM-130 pending amendments in Mexico open a window for pre-positioned protease and amylase suppliers to capture switching volume from tortilla producers. Target Yucatán Peninsula technical service gaps where underdeveloped infrastructure defers stainless steel tankage investments and powder formulations dominate. Establish regional distribution partnerships with ENMEX to leverage existing commodity-grade coverage while introducing specialty enzyme access. For Investors and Strategic Acquirers: Roll-up economics work for regional formulation specialists because COFEPRIS approval timelines and technical service requirements fragment competitive positioning beyond multinational scale. Long-term viability hinges on clean-label biocatalyst portfolios aligned with regulatory trajectory. Monitor NOM-130 final rule publication as inflection indicator for reformulation-driven switching volume.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Free Enzyme Production Deployment | Jalisco dairy processors adopt on-site immobilization to decentralize supply chain risk from import corridors. |
| Direct-Procurement Platform Establishment | Querétaro multinationals bypass traditional distributors to negotiate integrated supply agreements with biotechnology suppliers. |
| Regional Technical Service Expansion | First-mover positioning in Yucatán Peninsula captures underdeveloped processing infrastructure with powder formulation focus. |
| Clean-Label Reformulation Partnership | Guadalajara tortilla manufacturers pre-position enzyme alternatives ahead of NOM-130 amendment finalization. |
| Specialty Lipase Capability Investment | Reduced-fat cheese flavor modification commands premium positioning in Jalisco dairy cooperatives. |
Research Methodology
Coverage spans central Mexico baking corridors, Jalisco dairy processing clusters, and Yucatán Peninsula penetration zones, with primary inputs from each. Formulation chemists at multinational processors, COFEPRIS regulatory affairs specialists, procurement leads at mid-tier bakeries, and ENMEX technical sales directors provided structured interviews. Secondary validation drew from COFEPRIS registration databases, NOM-051 and NOM-130 regulatory filings, Secretariat of Economy export statistics, and CODEX Alimentarius alignment documentation. Bottom-up enzyme volume estimates triangulated against top-down food manufacturing output data.
Granularity-level modeling disaggregated protease, amylase, lipase, and cellulase categories across baking, dairy, beverage, and meat processing applications. Liquid, powder, granular, and tablet formats were separately projected alongside food manufacturer, beverage producer, bakery retailer, and nutraceutical company end-user segments. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated NOM-130 amendment probability weighting and cell-free production technology adoption curves.
Revisions become necessary when COFEPRIS regulatory timelines extend beyond modeled assumptions or when carbohydrate feedstock volatility disrupts fermentation economics. Forecasts reflect base-case assumptions regarding clean-label substitution rates and CODEX export alignment maintenance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Pyranose Oxidase Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market