
 Date Syrup Market | 2026-2036
Date Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Date Syrup Market Analysis
Saudi Arabia is fragmenting as new processing facilities enter the date syrup value chain alongside established operators. Al Barakah Dates Factory leverages its integrated palm orchards and industrial-scale extraction infrastructure to dominate bulk supply contracts. Agthia Group (Al Foah) sustains one of the world's largest date processing footprints, extending its reach into European retail channels through organic certification. Bateel International differentiates via gourmet positioning in duty-free and luxury food retail, commanding premium shelf placement.
Date syrup is a viscous liquid sweetener produced by extracting and concentrating the soluble sugars from macerated date fruit, typically containing 60-70% total sugars with glucose and fructose as dominant monosaccharides. Industrial applications exploit its humectant properties and clean-label appeal to replace invert syrups and high-fructose corn syrup in baked goods, beverages, and confectionery. Organic date syrup leads value generation as certification barriers limit supplier pools and justify price premiums in North American and European retail. Conventional date syrup anchors volume throughput in Middle Eastern domestic markets and bulk food manufacturing. The food and beverage industry end-use segment concentrates margin capture, with multinational ingredient buyers negotiating long-term supply agreements directly with Saudi and Emirati processors.
Saudi Arabia's Saudi Food and Drug Authority (SFDA) enforces labeling standards for natural sweeteners that align with Gulf Cooperation Council technical regulations, shaping export readiness for regional suppliers. The European Union's EFSA evaluates novel food applications and health claim substantiation for date-derived ingredients, directly conditioning market access timelines for Middle Eastern exporters. The US FDA classifies date syrup under GRAS status for conventional food use, though organic certification through USDA-accredited bodies adds compliance layers for premium positioning. Stakeholders must monitor evolving added-sugar taxation schemes and front-of-pack labeling mandates across target import markets to anticipate demand inflections.
Market Dynamics
The EU's Farm to Fork Strategy under the European Green Deal is compressing demand timelines for natural sweeteners, forcing Middle Eastern processors to accelerate organic certification timelines and reformulate extraction methods to meet tightening front-of-pack labeling requirements.
Growth Catalysts
- Clean-label mandates:The EU Green Deal's added-sugar disclosure rules push German bakeries and confectioners toward date syrup as a recognizable single-ingredient alternative to invert syrups.
- Industrial humectant substitution:Food manufacturers exploit date syrup's moisture-retention properties to replace high-fructose corn syrup in extended-shelf-life baked goods.
- Saudi processing capacity:New extraction facilities in Al-Qassim Province expand bulk output for export contract fulfillment.
Market Restraints
- Input cost volatility:Date palm harvest fluctuations in Saudi Arabia's Al-Ahsa oasis create raw material price instability for syrup processors.
- Supply concentration risk:Bulk contract dependency on Saudi Arabia's integrated orchard-processor complexes limits buyer negotiation leverage.
- Regulatory friction:EFSA novel food application timelines delay Middle Eastern exporters' access to European health claim positioning.
Strategic Opportunities
- Underpenetrated North American retail:USDA organic certification gaps among Saudi suppliers create first-mover potential for compliant processors in premium US grocery channels.
- Regulatory tailwind:The EU's Nutri-Score front-of-pack labeling system advantages natural sweeteners over refined sugar in continental supermarket placement.
- Beverage formulation:Craft soft-drink manufacturers in Germany adopt date syrup for low-alcohol cocktail bases and functional fermented drinks.
Industry Challenges
- Certification timeline compression:EU organic accreditation requires 18-24 month conversion periods for Saudi date orchards, mismatching buyer procurement cycles.
- Capex intensity:Industrial-scale vacuum evaporation equipment for 60-70% brix concentration demands capital deployment that mid-tier processors struggle to finance.
- Skill scarcity:Food safety auditors qualified for both SFDA and EU organic standards remain concentrated in Riyadh and Jeddah, constraining facility expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Date Syrup Market |
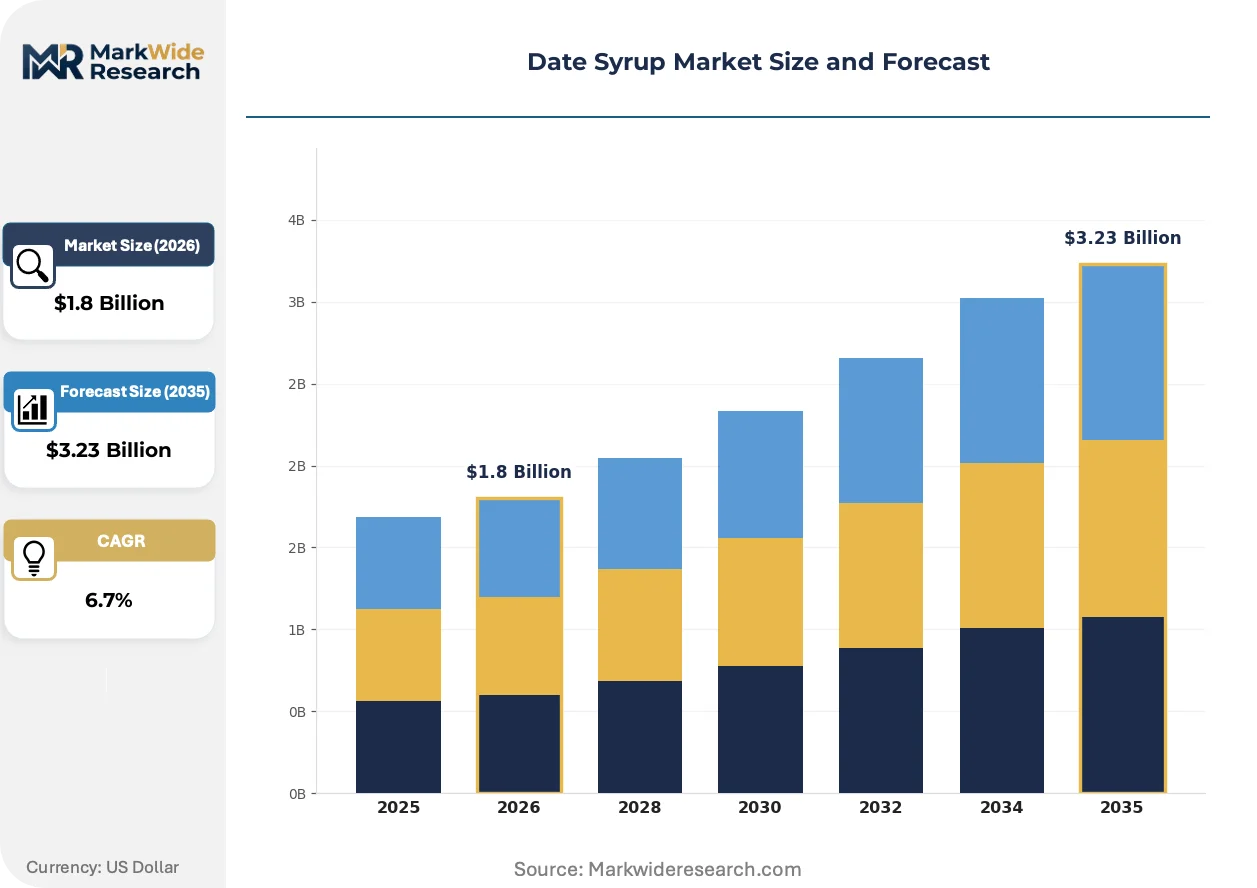
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Date Syrup, Conventional Date Syrup, Raw Date Syrup, Flavored Date Syrup Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Packaging Type: Bottles, Jars, Pouches, Tubs End User: Food & Beverage Industry, Bakeries, Households, Restaurants |
| Companies Covered | D'vash Organics, Lion Dates, Al Barakah Dates Factory, RatinKhosh, Parsunday Symbol Co., Agthia Group (Al Foah), Rapunzel Naturkost, Ariafoods, Bateel International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Date Syrup Market Emerging Trajectories
Extraction technology advances and regulatory disclosure mandates are compressing traditional competitive advantages in the date syrup value chain, rewarding processors who integrate certification and processing capabilities.
Membrane filtration systems for date juice clarification are collapsing the cost gap between artisanal and industrial-grade syrup production. German organic bakeries now source membrane-filtered concentrate at price parity with conventional extraction methods. This compression enables mid-tier Saudi processors to compete for European retail contracts previously captured by integrated orchard operators.
REACH registration requirements for food-contact substances are tightening specification standards for date syrup packaging materials. Exporters to Germany and France must now document migration testing for bisphenol-free containers. Saudi processors with in-house laboratory capabilities secure faster market access than competitors relying on third-party certification.
Direct-procurement relationships between multinational ingredient buyers and Saudi processors are displacing traditional trading-house intermediaries. Nestlé and Unilever procurement teams now negotiate annual volume contracts directly with Al-Qassim extraction facilities. This disintermediation concentrates margin capture at the processing stage and compresses working capital cycles for qualified suppliers.
Date Syrup Market Segmentation
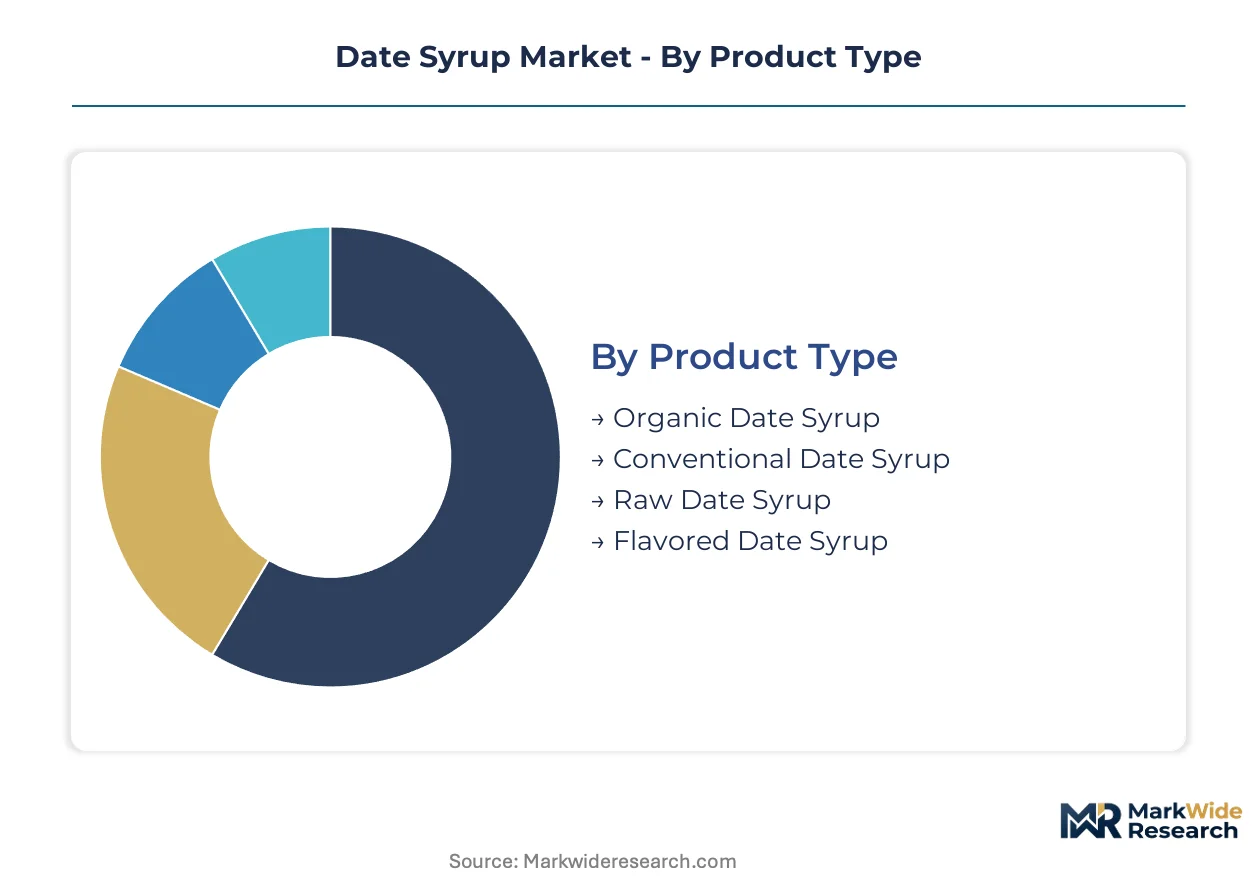
Segmentation in date syrup reveals how certification tiers, channel economics, and end-use specifications fragment procurement patterns. Buyers negotiate entirely different contract terms across organic versus conventional grades, while industrial formulators prioritize humectant performance metrics that retail consumers ignore.
Product Type:
Cycle times vary dramatically: organic certification locks orchards into multi-year conversion timelines, while conventional syrup turns inventory monthly. Raw and flavored variants occupy intermediate positions with seasonal demand spikes.
- Organic Date Syrup:Certification through USDA-accredited bodies or EU organic standards limits supplier pools and justifies price premiums. German health-food retailers and North American clean-label manufacturers concentrate procurement here, though 18-24 month orchard conversion timelines strain buyer procurement cycles.
- Conventional Date Syrup:Anchors volume throughput in Middle Eastern domestic markets and bulk food manufacturing. Saudi Arabia's Al-Qassim Province extraction facilities prioritize this grade for export contract fulfillment to multinational ingredient buyers seeking cost-efficient invert syrup replacements.
- Raw Date Syrup:Minimally processed variant retaining enzymatic activity and broader mineral content. Niche positioning in raw-food diet communities and functional beverage startups.
- Flavored Date Syrup:Infused variants targeting premium gifting and specialty coffee applications. Bateel International's gourmet positioning exploits this segment in duty-free retail.
Conventional date syrup dominates installed base. Organic date syrup is where expansion concentrates.
Distribution Channel:
Cost tiers separate direct-procurement industrial contracts from retail markup structures. Nestlé and Unilever negotiate annual volume agreements directly with Saudi processors, bypassing traditional trading-house margins entirely.
- Online Retail:Direct-to-consumer platforms capture premium organic purchases from health-conscious households. Subscription models in North America reduce customer acquisition costs for certified Saudi suppliers building brand recognition.
- Supermarkets:Shelf placement depends on front-of-pack labeling compliance. EU Nutri-Score advantages drive German retailer listings for natural sweetener alternatives.
- Health Food Stores:Specialty channel prioritizing organic certification and single-ingredient transparency. Independent German organic bakeries source membrane-filtered concentrates here.
- Wholesale:Bulk channel serving food manufacturers and restaurant chains. Al Barakah Dates Factory leverages integrated orchard infrastructure to lock in multi-year supply agreements at this tier.
Wholesale channels move the highest absolute volumes. Online retail is climbing the fastest.
Packaging Type:
Application requirements dictate material selection: food manufacturers prefer bulk formats, while retail positioning demands shelf-ready aesthetics. REACH registration for food-contact substances tightens specification standards for European-bound shipments.
- Bottles:Standard retail format for household table-use positioning. Glass and bisphenol-free plastic variants required for German and French import compliance.
- Jars:Premium gifting and gourmet retail placement. Bateel International commands luxury shelf space with this format in duty-free channels.
- Pouches:Flexible packaging reducing shipping cube for industrial buyers. Growing adoption in bakery and beverage manufacturing for ease of dispensing.
- Tubs:Bulk foodservice format targeting restaurant and catering procurement. Concentrated brix levels reduce per-unit shipping costs.
Bottles dominate household penetration. Pouches are gaining share fastest among industrial buyers.
End User:
Margin capture concentrates at the processing stage for industrial buyers, while retail channels fragment value across distribution intermediaries. Formulation requirements vary: bakeries exploit humectant properties, beverage makers prioritize solubility.
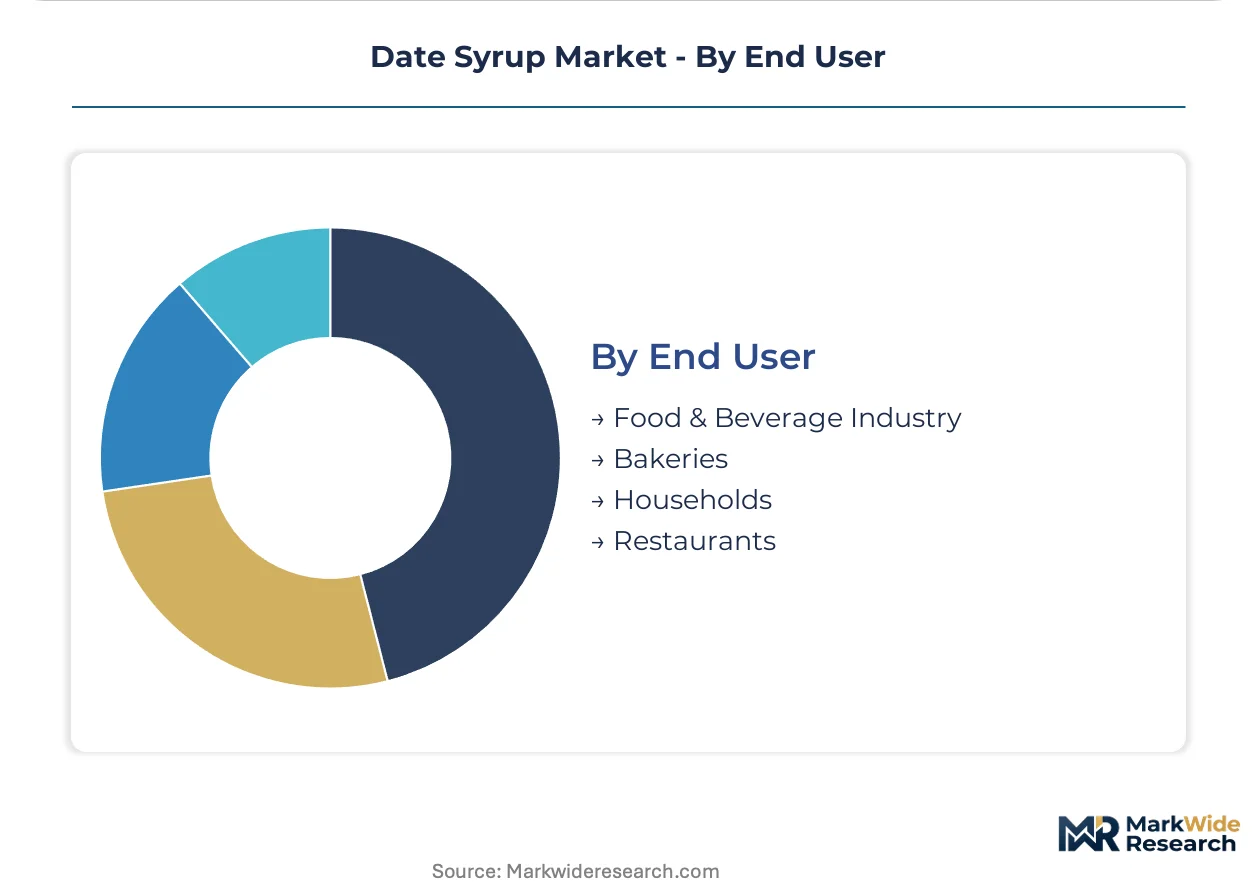
- Food & Beverage Industry:Multinational ingredient buyers negotiate long-term supply agreements directly with Saudi and Emirati processors. This segment concentrates margin capture and compresses working capital cycles for qualified suppliers meeting SFDA and EU organic standards simultaneously.
- Bakeries:Artisan bread and pastry producers across Germany substitute refined sugars with date syrup for clean-label positioning. Membrane filtration advances enable price parity with conventional extraction methods.
- Households:Retail consumers responding to EU Green Deal added-sugar disclosure rules. Organic certification and single-ingredient labeling drive purchase decisions.
- Restaurants:Foodservice channel adopting date syrup for menu differentiation in low-alcohol cocktail bases and functional fermented drinks. German craft soft-drink manufacturers lead here.
Food & Beverage Industry anchors contract value. Bakeries represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia concentrates date syrup processing infrastructure, with Al-Qassim Province extraction facilities supplying bulk contracts to multinational ingredient buyers. German health-food retailers and organic bakeries drive premium demand in Europe.
Germany
Health-conscious consumers and clean-label food manufacturers propel organic date syrup purchases through specialty retailers. The EU's Farm to Fork Strategy tightens added-sugar labeling requirements under the European Green Deal. Artisan bakeries in Berlin and Munich substitute refined sugars with date syrup in breads and pastries.
United States
North American households seek USDA-certified organic sweeteners through direct-to-consumer subscription platforms. The FDA classifies date syrup under GRAS status for conventional food use. California-based clean-label manufacturers negotiate supply agreements with Middle Eastern processors.
Saudi Arabia
Integrated orchard-processor complexes in Al-Ahsa oasis and Al-Qassim Province dominate bulk export contract fulfillment. The Saudi Food and Drug Authority enforces labeling standards aligning with Gulf Cooperation Council technical regulations. New extraction facilities fragment supply-side concentration alongside established operators.
France
REACH registration requirements for food-contact substances tighten packaging specifications for date syrup imports. EFSA evaluates novel food applications and health claim substantiation for date-derived ingredients. Parisian gourmet retailers list membrane-filtered concentrates for premium household positioning.
United Arab Emirates
Duty-free and luxury food retail channels command premium shelf placement for gourmet date syrup variants. MOHAP oversees food safety standards for natural sweeteners re-exported to European markets. Dubai-based processors leverage organic certification to access German supermarket listings.
Date Syrup Market Vendor Landscape
Integrated orchard-operators and specialized extraction facilities split the market between bulk supply contracts and premium retail positioning. Saudi Arabia's Al-Qassim Province hosts the densest concentration of industrial-scale vacuum evaporation infrastructure. Three archetypes dominate: vertically integrated date palm conglomerates with captive raw material supply; mid-tier membrane filtration specialists competing on price parity; and gourmet positioning houses targeting duty-free and luxury channels. Capacity expansion and organic certification acceleration constitute the dominant competitive moves.
Within the integrated orchard tier, Al Barakah Dates Factory and Agthia Group (Al Foah) represent scale-driven supply chain control. Bateel International occupies a position exemplifying gourmet retail specialization. These three entities anchor distinct competitive vectors: bulk industrial supply, multinational retail penetration, and luxury channel premiumization.
| Leading Market Players |
|---|
| D'vash Organics |
| Lion Dates |
| Al Barakah Dates Factory |
| RatinKhosh |
| Parsunday Symbol Co. |
| Agthia Group (Al Foah) |
| Rapunzel Naturkost |
| Ariafoods |
| Bateel International |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Saudi Arabia's Al-Ahsa oasis date palm harvests determines both pricing tier spreads and supply chain shape, compressing margins when climatic stress reduces raw material availability and forcing buyers toward longer-term contract structures that lock in volume at the expense of price flexibility.
Pricing Analysis
The EU's Farm to Fork Strategy dictates the pricing tier structure across the date syrup value chain, separating organic-certified grades commanding shelf-space premiums in German supermarkets from conventional bulk supplies anchoring multinational ingredient contracts. Three-tier pricing stratifies across premium organic, standard conventional, and economy-grade unfiltered variants, with certification level and volume scale as the primary differentiation drivers. Pricing pressure stems from membrane filtration technology collapsing the cost gap between artisanal and industrial extraction methods. Industrial buyers at Nestlé and Unilever procurement desks exhibit the highest price sensitivity, while gourmet retail channels in duty-free environments show minimal elasticity.
Supply Chain Analysis
Integrated orchard-processor complexes in Saudi Arabia's Al-Qassim Province hold the dominant contract-manufacturing capacity, with secondary concentration in the UAE's Dubai processing corridors and emerging capabilities in Iran's southeastern date belt. Raw material supply draws from date palm cultivation clusters, industrial-scale vacuum evaporation equipment, and membrane filtration systems for juice clarification. Single-source vulnerability concentrates in Saudi Arabia's Al-Ahsa oasis, where harvest fluctuations transmit directly into export contract pricing. Distribution runs through direct-procurement relationships between multinational ingredient buyers and Saudi processors, displacing traditional trading-house intermediaries and compressing working capital cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service represents the fastest-expanding recurring-revenue layer in date syrup, with organic accreditation and regulatory compliance consulting outpacing hardware margins from extraction equipment as processors seek to navigate EU and USDA certification timelines.
For Market Incumbents: Entrench market position by accelerating backward integration into captive date palm orchards to secure raw material supply against Al-Ahsa harvest volatility, while simultaneously investing in in-house laboratory capabilities for REACH-compliant packaging migration testing that speeds German market access. Membrane filtration specialists threaten price parity at the mid-tier, making certification speed the critical defensive lever. For New Entrants and Emerging Players: North American retail penetration gaps in USDA-certified organic supply create viable white-space entry points, particularly through direct-to-consumer subscription platforms that reduce customer acquisition costs. Target craft soft-drink manufacturers in Germany seeking low-alcohol cocktail bases, exploiting the beverage formulation angle with solubility-optimized concentrates and rapid organic certification turnaround. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processors with dual SFDA-EU organic certification capabilities and established direct-procurement relationships with multinational ingredient buyers. Long-term viability hinges on regulatory compliance infrastructure rather than commodity extraction scale. Watch for EFSA novel food application approvals as the signal indicating accelerated European health claim positioning and premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acceleration | EU organic accreditation unlocks German supermarket shelf placement under Nutri-Score labeling advantages. |
| Membrane Filtration Capacity Expansion | Cost parity with conventional extraction enables mid-tier Saudi processors to compete for European retail contracts. |
| Direct-Procurement Relationship Development | Annual volume agreements with Nestlé and Unilever procurement teams concentrate margin capture at processing stage. |
| In-House Laboratory Capability Investment | REACH-compliant migration testing for bisphenol-free containers accelerates German and French import clearance. |
| Beverage Formulation Partnership | Craft soft-drink manufacturers in Germany adopt date syrup for functional fermented drink applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with date syrup extraction facility managers, organic certification auditors, multinational ingredient procurement leads at food manufacturers, German health-food retail category buyers, and SFDA regulatory affairs specialists. Secondary validation drew from EU EFSA novel food application databases, USDA organic certification records, Saudi customs export statistics, REACH registration filings for food-contact substances, and GCC technical regulation harmonization documents. Bottom-up volume modeling from processor capacity utilization rates triangulated against top-down demand estimates from end-use industry consumption patterns.
Calibration against historical price realizations for organic versus conventional grades anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included certification tier, distribution channel economics, packaging format specifications, and end-use application requirements ranging from industrial humectant substitution to gourmet retail positioning. CAGRs derived from weighted average growth contributions across these segments, with specific inputs from EU Green Deal implementation timelines and membrane filtration technology adoption curves.
Practitioners should monitor EFSA novel food approval velocities, EU added-sugar taxation scheme expansions, and Al-Ahsa oasis climatic stress indicators for early signals of forecast revision. Quarterly review of organic certification backlog durations and membrane filtration equipment order books is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy Flour Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Gum Arabic Market
Ingredients
Sunflower Protein Market
Ingredients
Soy Hydrolysates Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Edible Animal Fat Market
Ingredients
Icing Shortening Market
Ingredients
Glucosylglycerol Market
Ingredients
Fats and Oils Market
Ingredients
Europe Pea Starch Market
Ingredients
Europe Amino Acid Market