
 Cocoa Extract Market | 2026-2036
Cocoa Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Extract Market Analysis
EU REACH registration requirements for botanical extracts is rebalancing the cost-of-entry calculus for cocoa extract suppliers seeking European market access. Barry Callebaut leverages its integrated bean-to-extract supply chain to control raw material provenance and alkaloid consistency. Cargill competes through its sustainability certification programs that anchor contract relationships with major confectionery manufacturers. Olam dominates West African sourcing corridors, extending its origination networks into Ecuador and Peru to diversify polyphenol profiles.
Cocoa extract comprises concentrated bioactive compounds derived from Theobroma cacao seeds, typically standardized to 10-20% polyphenol content or 0.5-3% theobromine through solvent or supercritical CO2 extraction, serving as functional ingredients for cardiovascular health claims, natural flavoring, and antioxidant applications in formulated products. Powder formats lead volume throughput due to stability and blending compatibility, while liquid extracts capture premium positioning in beverage applications where rapid dispersion matters. Nutraceuticals represents the fastest-expanding end user segment as supplement brands reformulate around clean-label polyphenol sources, whereas food industry applications remain the mature revenue base with established procurement contracts.
FDA GRAS self-affirmation pathways govern cocoa extract entry into US food and supplement channels, while EFSA novel food opinions shape European market access timelines and label claim permissibility. BIS quality certification requirements in India add another compliance layer for exporters targeting pharmaceutical-grade applications. Stakeholders must monitor evolving theobromine threshold regulations across jurisdictions and calibrate extraction processes to meet divergent purity standards before committing to regional capacity expansion.
Market Dynamics
EFSA novel food authorization timelines are compressing competitive windows for cocoa extract suppliers, forcing reformulation cycles to synchronize with regulatory opinion schedules rather than traditional product development calendars.
Growth Catalysts
- Cardiovascular health positioning:Nutraceutical formulators are expanding polyphenol procurement for supplement applications targeting endothelial function claims approved under FDA GRAS self-affirmation pathways.
- REACH registration compliance:European botanical extract standards are filtering out marginal suppliers, concentrating procurement relationships with certified processors capable of documenting alkaloid traceability.
- German extraction capacity expansion:Functional ingredient manufacturers are building dedicated processing facilities in Central Europe to serve regional confectionery and supplement brands with shortened lead times.
Market Restraints
- Cocoa bean price volatility:Input costs fluctuate with West African harvest cycles and currency exposure in Côte d'Ivoire and Ghana origination corridors.
- Polyphenol standardization limits:Natural variation in bean chemistry constrains batch-to-batch consistency for high-concentration extracts above 20% total polyphenol content.
- Theobromine threshold divergence:Jurisdictional regulations on alkaloid limits in food and supplement applications fragment formulation requirements across export markets.
Strategic Opportunities
- Ecuador and Peru sourcing diversification:Olam and competing traders are extending origination networks into Latin American growing regions to access distinct polyphenol profiles and reduce West African concentration risk.
- Liquid extract beverage applications:Rapid-dispersion formats are capturing premium positioning in functional drinks where powder stability constraints limit adoption.
- Indian pharmaceutical-grade certification:BIS quality requirements create a compliance moat for exporters targeting API-adjacent applications with higher purity benchmarks than food-grade specifications.
Industry Challenges
- Supercritical CO2 extraction talent scarcity:Equipment operation and process optimization expertise concentrates among specialists with pharmaceutical extraction backgrounds.
- Dual certification timeline compression:Suppliers must parallel-track FDA GRAS self-affirmation and EFSA novel food opinions to maintain competitive positioning in transatlantic accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Extract Market |
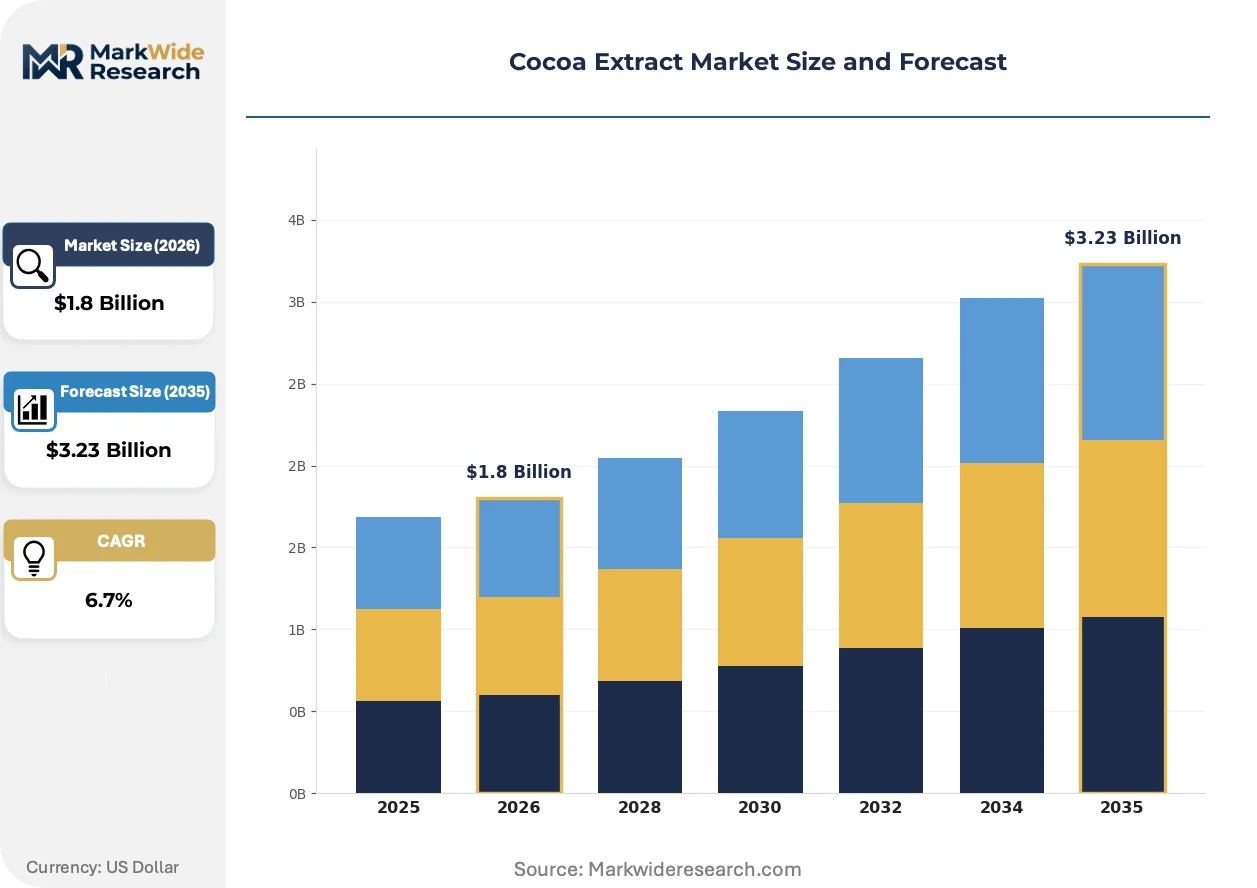
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Extract, Capsules End User: Food Industry, Cosmetic Industry, Nutraceuticals, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores Application: Beverages, Snacks, Dietary Supplements, Skincare |
| Companies Covered | Naturex (Givaudan), Barry Callebaut, Olam, Nexira, Indena, Cargill, Archer Daniels Midland Company, Sabinsa, Blommer Chocolate Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Extract Market Emerging Trajectories
Clean-label polyphenol sourcing is displacing synthetic antioxidant alternatives across formulated products, while extraction technology advances and procurement model evolution reshape supplier-buyer relationships.
Supercritical CO2 extraction is overtaking solvent-based methods for high-value cocoa polyphenol concentrates. Premium nutraceutical manufacturers are adopting this technology to eliminate residual solvent concerns in cardiovascular health supplements. The shift is compressing acceptable purity thresholds and raising capital requirements for new market entrants.
EFSA novel food authorization requirements are tightening botanical extract documentation standards for European market access. Suppliers must now submit comprehensive safety dossiers and alkaloid stability data before commercialization. German functional ingredient manufacturers are restructuring quality assurance teams to manage extended opinion timelines.
Long-term procurement contracts with sustainability certification anchors are displacing spot-market purchasing in major confectionery supply chains. Cargill and integrated processors are locking multi-year volumes through verified cocoa programs. This concentration is most visible in German and Swiss chocolate manufacturing clusters where ESG reporting requirements drive preferential sourcing.
Cocoa Extract Market Segmentation
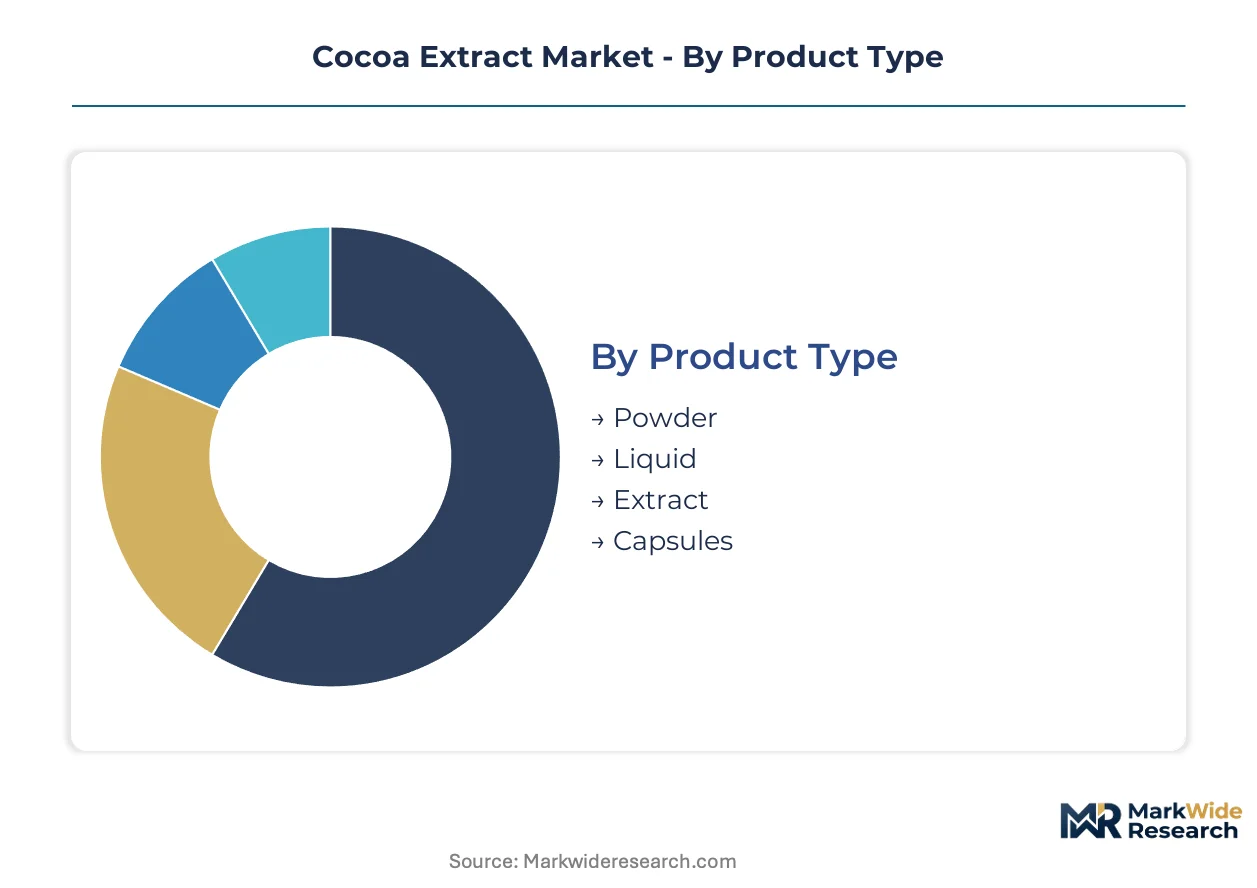
Cocoa extract segmentation reflects divergent regulatory pathways and extraction technology requirements across end-use applications. Product format selection directly determines which certification regimes apply, from FDA GRAS self-affirmation for food-grade powders to EMA pharmaceutical dossiers for API-grade concentrates.
Product Type:
FDA GRAS self-affirmation governs powder and liquid entry into US food channels, while EFSA novel food opinions add 12-18 month lead times for European powder commercialization. Pharmaceutical-grade capsules require parallel CDSCO registration in India and NMPA filings in China, fragmenting compliance architecture by format.
- Powder:Spray-dried or freeze-dried concentrates standardized to 10-20% polyphenol content dominate bulk procurement from German and Swiss confectionery manufacturers seeking blending compatibility with cocoa butter matrices. REACH registration documentation for powder alkaloid profiles now filters marginal suppliers from European accounts.
- Liquid:Hydroalcoholic or glycerin-based extracts with rapid dispersion characteristics capture premium positioning in functional beverage applications where powder hydration kinetics limit adoption. US supplement brands favor liquid formats for tincture and shot positioning under DSHEA compliance frameworks.
- Extract:Supercritical CO2-derived concentrates above 40% polyphenol standardization serve nutraceutical encapsulation with residual solvent elimination claims.
- Capsules:Hard-shell and soft-gel delivery formats require pharmaceutical-grade excipient compatibility testing for CDSCO-regulated Indian exports.
Leading the category by volume: Powder. Growing fastest: Liquid.
End User:
Cost tier stratification separates commodity food-grade procurement from premium nutraceutical and pharmaceutical specifications. Food industry contracts anchor volume throughput at lower margin points, while pharmaceutical applications command 3-5x unit economics contingent on GMP certification depth.
- Food Industry:Confectionery and bakery manufacturers in Germany, Switzerland, and Belgium drive standardized powder procurement through sustainability-certified supply chains with ESG reporting requirements embedded in contract terms.
- Nutraceuticals:Supplement brands reformulating around clean-label polyphenol sources for cardiovascular positioning represent the steepest expansion trajectory, with US and German formulators expanding procurement teams dedicated to cocoa extract sourcing.
- Cosmetic Industry:Antioxidant serum and mask applications in South Korea and France utilize low-theobromine extracts for dermal tolerance compliance.
- Pharmaceuticals:API-adjacent applications targeting endothelial function require BIS certification in India and MFDS pharmaceutical-grade approval in South Korea, creating compliance moats for qualified exporters.
Dominating procurement scale: Food Industry. Expanding most quickly: Nutraceuticals.
Distribution Channel:
Customer type bifurcation separates institutional bulk procurement through specialty intermediaries from direct-to-consumer retail velocity. Health stores and online channels concentrate premium-positioned liquid and capsule formats, while supermarkets move commoditized powder SKUs.
- Specialty Stores:Dedicated supplement retailers in Germany and the US curate premium cocoa polyphenol assortments with third-party alkaloid testing documentation, commanding 25-40% retail margin premiums over mass channels.
- Online Retail:Direct-to-consumer subscription models for cardiovascular health supplements bypass traditional wholesale markups, with US and UK brands leveraging Amazon and proprietary storefronts for liquid extract velocity.
- Health Stores:GNC, Holland & Barrett, and regional pharmacy chains in France and Italy stock standardized capsule formats with visible polyphenol percentage labeling.
- Supermarkets:Mass-market powder placement in Walmart, Carrefour, and Tesco locations serves home baking and hot chocolate applications with lower concentration thresholds.
Generating highest throughput: Specialty Stores. Accelerating fastest: Online Retail.
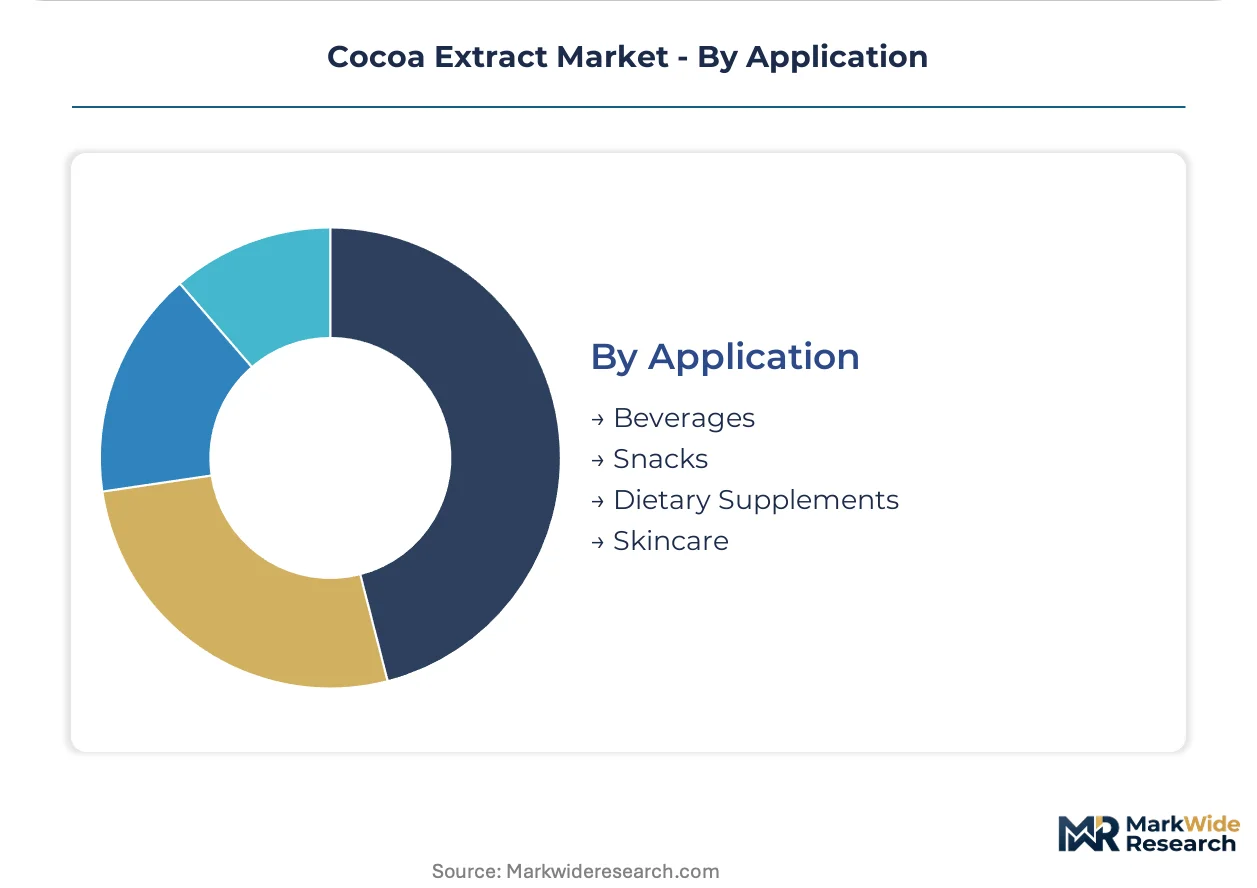
Application:
Maturity gradients separate established food and beverage applications from emerging skincare and precision supplement positioning. Beverages and snacks constitute the revenue base with predictable procurement cycles, while dietary supplements and skincare command innovation premiums.
- Beverages:Functional drink manufacturers in Japan and Germany incorporate rapid-dispersion liquid extracts into RTD cardiovascular health products, with METI food-with-health-claims approval required for Japanese market entry.
- Dietary Supplements:Soft-gel and capsule formats targeting endothelial function claims under FDA GRAS pathways represent the fastest-gaining share, with US and German brands driving formulation innovation around theobromine-standardized extracts.
- Snacks:Energy bar and chocolate-coated applications in Belgium and the Netherlands utilize defatted cocoa powder for antioxidant positioning without alkaloid concentration concerns.
- Skincare:Antioxidant serum and body cream formulations in France and South Korea leverage polyphenol extracts below 0.1% theobromine thresholds for dermal safety compliance.
Anchoring volume throughput: Beverages. Climbing the fastest: Dietary Supplements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Hamburg and Rotterdam concentrate European cocoa extract processing capacity, attracting toll manufacturers serving nutraceutical and confectionery clients with accelerated customs clearance and VAT deferral advantages.
Germany
Cardiovascular supplement brands in Berlin and functional ingredient manufacturers in Hamburg drive polyphenol extract procurement. EFSA novel food authorization timelines shape product launch schedules for exporters targeting German accounts. The Hamburg-Harbor free trade zone hosts dedicated supercritical CO2 extraction facilities supplying Central European confectionery clusters.
United States
FDA GRAS self-affirmation pathways enable rapid supplement formulation cycles for cardiovascular health positioning. DSHEA compliance frameworks govern liquid extract distribution through direct-to-consumer channels. Greater Chicago and northern New Jersey house contract manufacturers blending cocoa polyphenols into soft-gel and capsule formats for national brands.
India
Pharmaceutical-grade API applications in Hyderabad and Mumbai create demand for BIS-certified extracts above food-grade purity thresholds. CDSCO registration requirements filter supplier qualification for endothelial function research programs. Maharashtra's special economic zones accommodate excipient-compatible processing for export-bound capsule formulations.
Switzerland
Chocolate manufacturers in Zurich and Geneva source sustainability-certified cocoa extracts for ESG-aligned procurement contracts. Swissmedic pharmaceutical-grade standards apply to polyphenol concentrates entering clinical research supply chains. The Basel biotech corridor imports high-standardization extracts for cardiovascular mechanism studies.
Japan
METI food-with-health-claims approval governs functional beverage applications incorporating rapid-dispersion liquid extracts. Cosmetic manufacturers in Osaka formulate low-theobromine polyphenol serums for dermal tolerance compliance. The Kanto region's RTD beverage producers trial cardiovascular positioning claims pending regulatory opinion.
Cocoa Extract Market Vendor Landscape
European integrated processors anchor one tier; Asian botanical extract specialists hold contract manufacturing relationships with Western brands. The supplier base concentrates around bean-to-extract integrators capable of documenting alkaloid traceability, mid-scale toll processors serving regional nutraceutical formulators, and commodity traders extending origination networks into Latin America. Capacity expansion and sustainability certification anchoring constitute the dominant competitive moves reshaping procurement relationships.
Among integrated cocoa processors, Barry Callebaut and Cargill exemplify the bean-to-extract archetype with captive supply chain control, while Olam occupies a position representing the diversified origination network model extending beyond West African corridors. Naturex, following its Givaudan acquisition, sits within the flavor and fragrance conglomerate tier leveraging botanical extraction expertise across multiple high-value categories. These three anchors illustrate the structural split between agricultural origination control and specialized extraction capabilities.
| Leading Market Players |
|---|
| Naturex (Givaudan) |
| Barry Callebaut |
| Olam |
| Nexira |
| Indena |
| Cargill |
| Archer Daniels Midland Company |
| Sabinsa |
| Blommer Chocolate Company |
| Others |
Supply Flow & Price Mechanics
West African cocoa bean futures transmit volatility directly into three-tier pricing structures across premium, standard, and economy extract tiers. German toll processors absorb currency exposure in Côte d'Ivoire origination corridors while commanding premiums for EFSA-compliant documentation.
Pricing Analysis
Premium pricing attaches to sub-48-hour lead time guarantees for pharmaceutical-grade polyphenol concentrates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth: BIS-certified extracts command 40% premiums over food-grade powders. Pricing pressure stems from REACH registration cost amortization forcing smaller suppliers toward contract manufacturing relationships. Nutraceutical formulators exhibit lowest price sensitivity due to cardiovascular health claim premiums, while commodity confectionery buyers negotiate multi-year offtake agreements.
Supply Chain Analysis
Reverse-logistics flows for rejected alkaloid batches concentrate in Hamburg free trade zones where toll processors restandardize off-spec material. Supply concentrates in Ghana, Côte d'Ivoire, and Ecuador for bean origination, with German and Swiss facilities handling supercritical CO2 extraction. Raw material dependencies include fermentation-grade cocoa beans, food-grade CO2 solvent, and pharmaceutical-grade excipients. Single-source vulnerability runs through West African port congestion at Abidjan and Tema. Distribution runs through specialty chemical distributors for nutraceutical accounts and direct mill relationships for confectionery volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EFSA novel food authorization timelines erect barrier-to-entry moats favoring incumbent processors with dedicated regulatory affairs capacity.
For Market Incumbents: Anticipate supercritical CO2 equipment operator scarcity compressing utilization rates at expansion facilities. Prioritize captive supply chain control through Ecuador and Peru origination investments. Defend against Latin American traders capturing polyphenol profile diversification premiums by locking multi-year sustainability-certified contracts with Swiss chocolate manufacturers.
For New Entrants and Emerging Players: Contract research organizations serving Basel biotech corridor cardiovascular mechanism studies offer lowest competitive density entry point. Target Indian pharmaceutical-grade API applications where CDSCO registration creates compliance moats against commodity traders. Accelerate market penetration through toll processing partnerships with Hamburg-Harbor free trade zone operators.
For Investors and Strategic Acquirers: EFSA novel food opinion backlog clearance velocity is the leading indicator that regulatory capacity constraints are easing for compliant processors. Five-to-ten year viability favors integrated bean-to-extract operators with dual US-European certification pathways. Monitor German functional ingredient manufacturer capital expenditure announcements for demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Eliminates residual solvent concerns for FDA GRAS cardiovascular supplement positioning. |
| Ecuador and Peru Origination Network Extension | Accesses distinct polyphenol profiles while reducing West African concentration risk. |
| EFSA Novel Food Dossier Preparation | Compresses European commercialization timelines for premium nutraceutical accounts. |
| Indian BIS Certification Investment | Creates compliance moat for API-adjacent endothelial function applications. |
| Sustainability Certification Program Anchoring | Locks multi-year volumes with ESG-reporting German and Swiss confectionery manufacturers. |
Methodological Framework
Independent corroboration across extraction technology specialists, nutraceutical procurement directors, and regulatory affairs consultants underwrites the qualitative findings. Primary fieldwork encompassed supercritical CO2 equipment operators, EFSA novel food dossier preparers, and sustainability certification program managers. Secondary validation drew from EFSA novel food opinions, FDA GRAS notifications, BIS certification registries, and REACH registration databases. Bottom-up capacity assessments triangulated against top-down procurement volume estimates.
Rate-of-change decomposition across product format, end-use application, and geographic regulatory cluster shaped the analytical framework. Modeled dimensions spanned powder versus liquid versus capsule formats, food industry versus nutraceutical versus pharmaceutical end uses, and FDA GRAS versus EFSA novel food versus BIS certification pathways. CAGRs derived from segment-level volume build-ups incorporating extraction yield assumptions and standardization tier mix shifts. Forecast inputs included cocoa bean futures curve trajectories and supercritical CO2 equipment installation pipelines.
Caveats apply where EFSA opinion timeline extensions or West African supply disruptions could materially shift the outlook. Forecasts embed assumptions regarding alkaloid threshold regulatory stability and clean-label polyphenol sourcing momentum. Practitioners should monitor German functional ingredient manufacturer capacity announcements and Ecuadorian cocoa bean polyphenol assay trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market