
 Culinary Essence Market | 2026-2036
Culinary Essence Market Size, Share, and Industry Trends Forecast 2026-2036
Culinary Essence Market Analytics
Asset-light toll manufacturing and contract extraction agreements are tilting competitive dynamics toward mid-sized botanical processors that lack distillation infrastructure. Givaudan leverages captive sourcing from Madagascar vanilla estates to secure oleoresin supply chains. Kerry Group anchors European food service demand through its Taste & Nutrition division's chef-facing technical salesforce. Firmenich sustains premium positioning via proprietary fractional distillation capabilities for heat-sensitive herb essences.
Culinary essences comprise concentrated volatile aromatic compounds extracted through steam distillation, solvent extraction, or cold-pressing from botanical sources, typically standardized to specific flavor intensity measured in fold-strength equivalents for industrial batch consistency. These inputs function as building blocks for flavor modulation across formulated food systems, enabling precise taste replication without volumetric bulk from raw spices or herbs. Essential oils and flavor extracts together command the dominant share of value pools, with essential oils carrying higher per-kilogram pricing due to yield constraints from raw botanicals such as saffron and cardamom. Spice mixes represent the fastest-expanding category as emerging-market food manufacturers seek turnkey seasoning solutions that reduce in-house blending complexity.
FDA's Food Safety Modernization Act preventive controls and the EU's REACH registration requirements for food-contact substances both impose extraction solvent residue limits that reshape supplier qualification protocols. EFSA's ongoing evaluations of botanical novel food statuses further restrict which plant species enter commercial essence production. BIS certification mandates in India add another compliance layer for exporters targeting that manufacturing base. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-in that limits geographic market access.
Market Dynamics
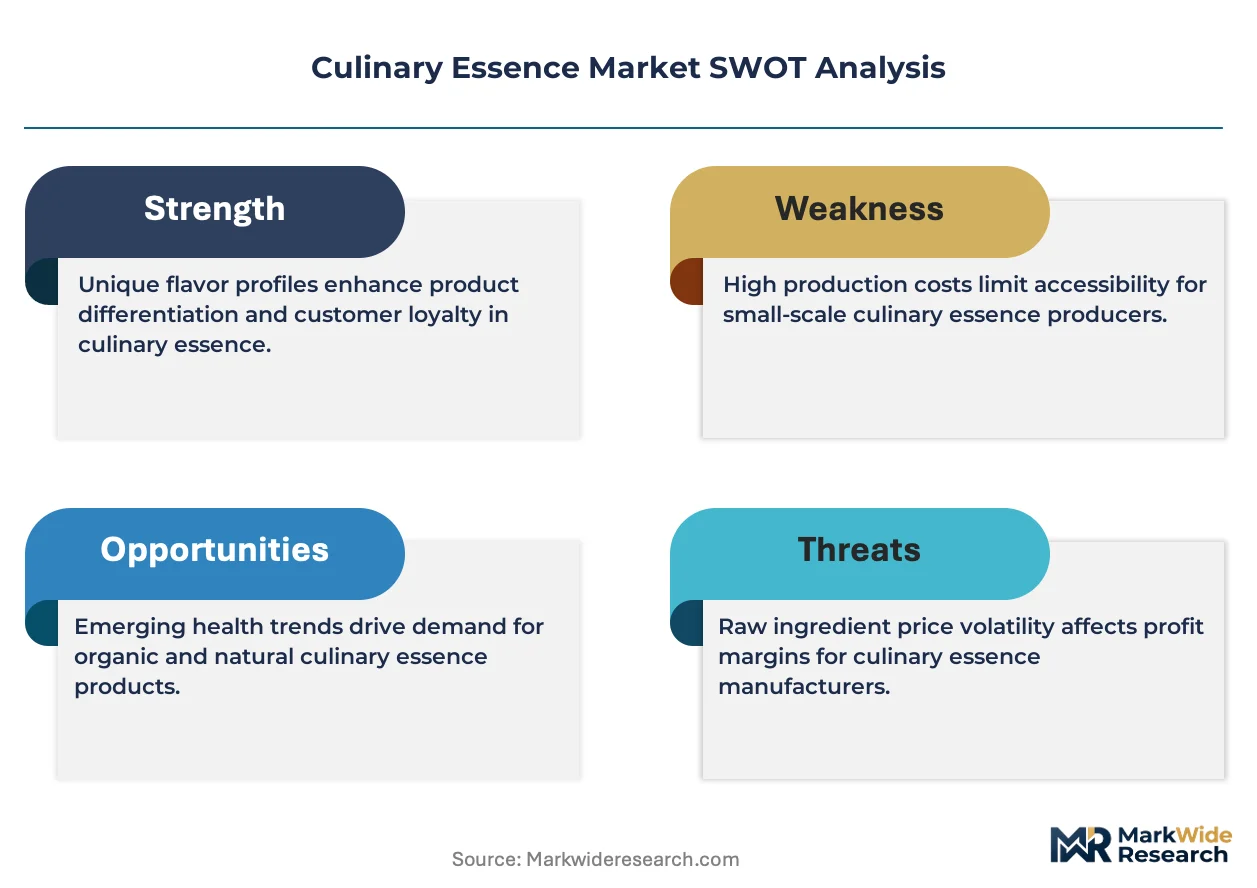
Clean-label reformulation mandates from EFSA and FDA are compressing artificial additive tolerances, forcing food manufacturers to rebuild flavor architectures around botanical extraction methods that carry higher raw material yield variance and solvent compliance costs.
Growth Catalysts
- EU Flavouring Regulation (1334/2008) tightening:Artificial additive approval withdrawals accelerate botanical essence substitution in processed foods across France, Germany, and Italy.
- Steam distillation yield improvements:Advanced vacuum-assisted extraction technologies reduce thermal degradation of heat-sensitive herb volatiles, expanding viable feedstock pools.
- Grasse extraction cluster concentration:French aromatic compound houses supply standardized oleoresins to global fragrance-flavor conglomerates, anchoring premium supply chains.
Market Restraints
- Saffron and cardamom yield constraints:Agricultural output volatility in Iran and Guatemala concentrates pricing power with raw material brokers, compressing processor margins.
- REACH solvent residue thresholds:ECHA registration requirements for food-contact extraction agents impose qualification timelines that freeze supplier switches.
- Synthetic flavor substitution threat:Biotechnology-derived aromatic molecules from fermentation platforms undercut natural essence cost structures in mass-market applications.
Strategic Opportunities
- India BIS certification pathway:Exporters meeting Bureau of Indian Standards mandates gain preferential access to subcontinent food manufacturing growth.
- Spice mix turnkey solutions:Emerging-market processors seek pre-blended seasoning systems that eliminate in-house formulation complexity.
- Carbon-negative extraction incentives:EU Green Deal funding streams reward processors deploying renewable-powered distillation infrastructure.
Industry Challenges
- Fractional distillation skill scarcity:Heat-sensitive herb processing requires specialized chemical engineering talent concentrated in legacy fragrance hubs.
- Multi-jurisdiction formulation lock-in:Divergent FDA, EFSA, and BIS residue limits prevent single-recipe geographic scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Culinary Essence Market |
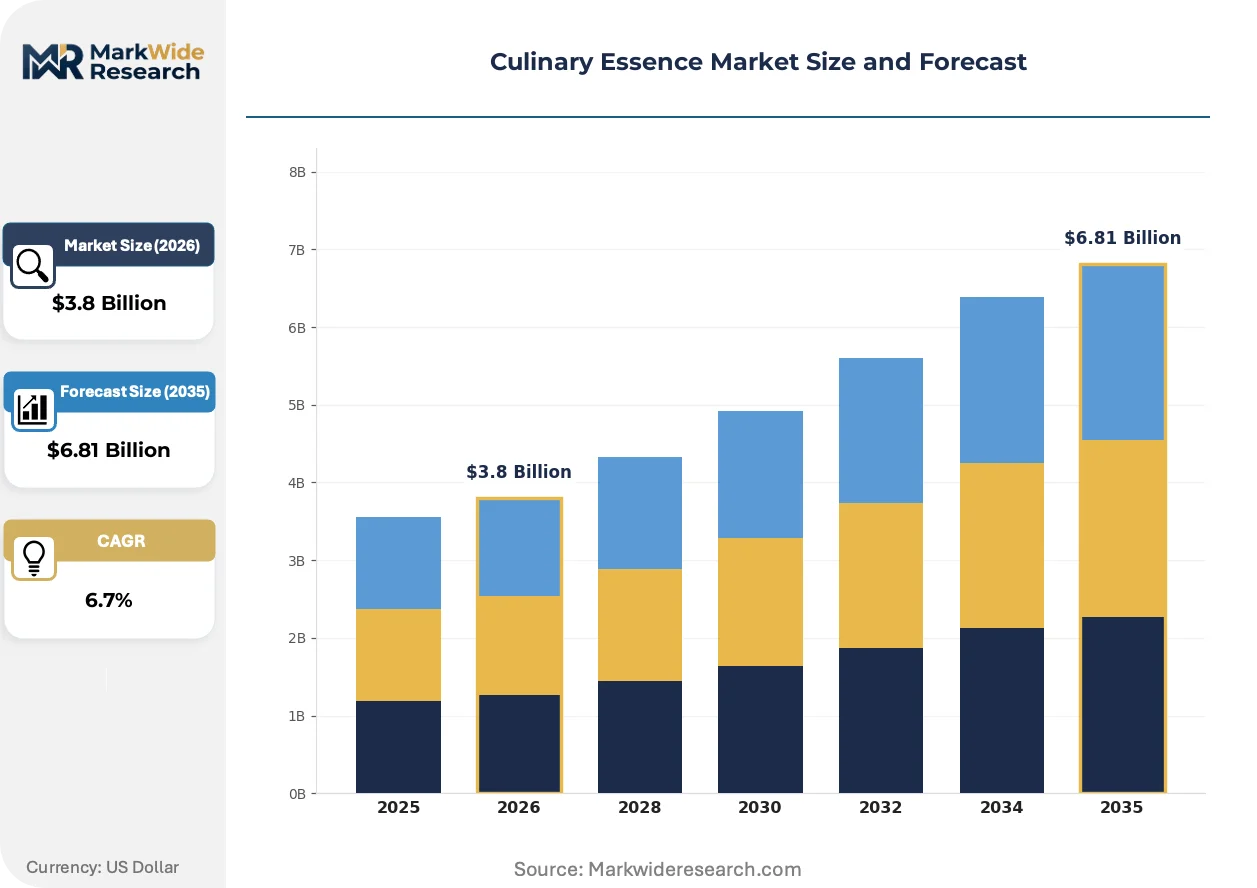
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Flavor Extracts, Spice Mixes, Aromatic Herbs Application: Food & Beverage, Personal Care, Household Products, Pharmaceutical Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Professional Chefs, Home Cooks, Food Manufacturers, Beverage Producers |
| Companies Covered | Firmenich, Kerry Group, Givaudan, Sensient Technologies, Takasago, IFF, Mane, Robertet Group, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Culinary Essence Market Evolving Landscape
Digital replication of sensory profiles and regulatory compression of synthetic inputs are converging to restructure how flavor houses develop, test, and commercialize aromatic compounds for industrial food systems.
Gas chromatography-mass spectrometry (GC-MS) fingerprinting combined with artificial intelligence pattern matching is virtualizing traditional organoleptic panel assessments. Mid-sized flavor houses in Switzerland and the Netherlands deploy these platforms to accelerate botanical screening cycles from months to weeks. The technology is virtualizing the role of master perfumers in early-stage compound identification, compressing R&D headcount requirements while expanding molecular libraries.
EFSA's ongoing novel food status evaluations for botanical species are redrawing permissible extraction source lists. The regulatory friction most acutely affects Mediterranean herb processors dependent on traditional wild-harvested materials. Firms are responding by accelerating domestication programs for borderline species and building dossier submission capabilities in-house.
Chef-facing technical salesforces now anchor premium essence procurement decisions in European food service. Kerry Group's Taste & Nutrition division and comparable technical service organizations displace traditional broker relationships through formulation partnership models. This behavioral shift concentrates most visibly in France and Spain, where restaurant group consolidation amplifies buyer power and rewards suppliers offering kitchen-validated application support.
Culinary Essence Market Segmentation
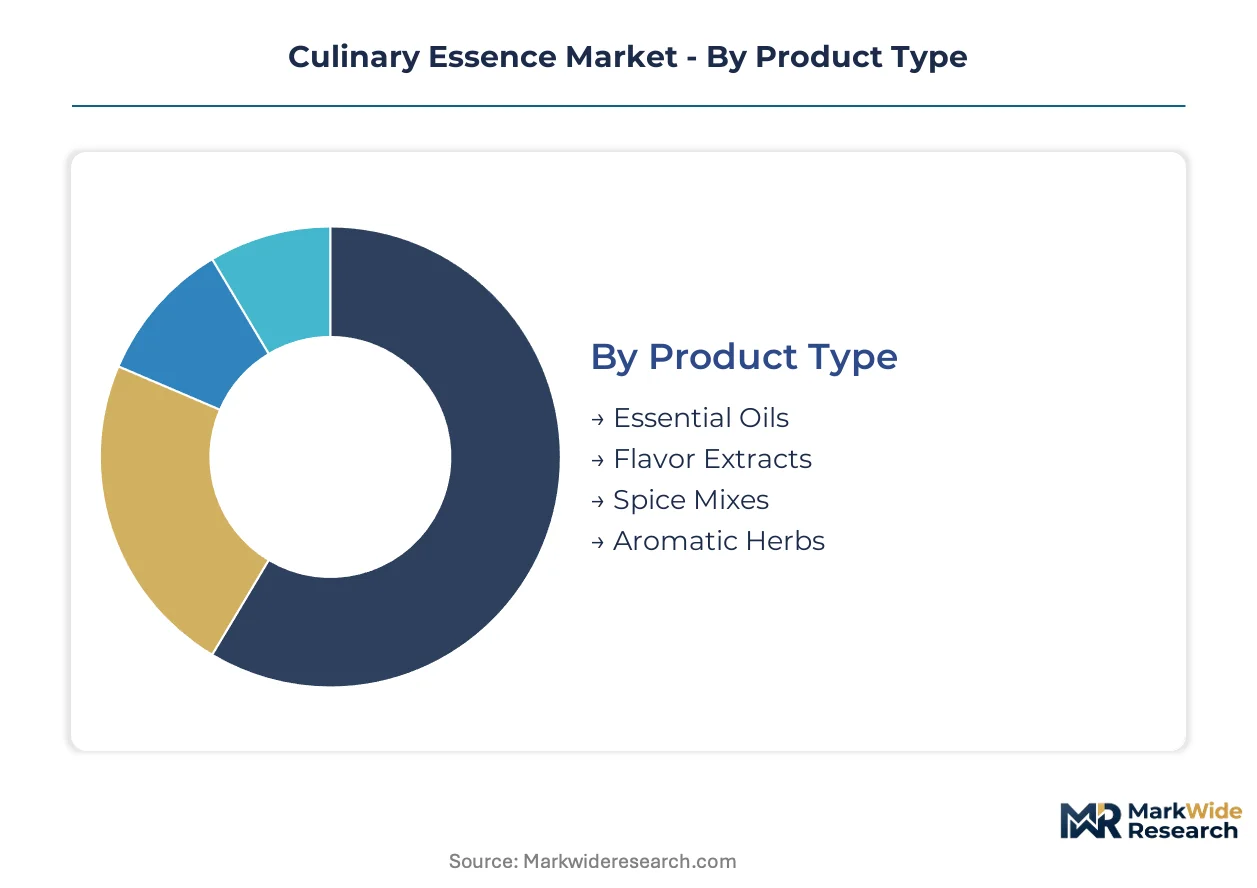
Segmentation in the culinary essence market reveals how formulation requirements diverge across customer sophistication levels. Professional kitchens demand technical specification sheets and batch consistency guarantees that home cooks rarely require. Understanding these service intensity gradients helps suppliers allocate technical sales resources and inventory investments.
Product Type:
After-sales service intensity varies sharply across product categories, with essential oils requiring analytical certification support and spice mixes demanding recipe development assistance.
- Essential Oils:Highly concentrated volatile aromatic compounds standardized to specific fold-strength equivalents for industrial batch consistency. Demand concentrates in pharmaceutical and premium food service channels in France and Switzerland, where EFSA solvent residue documentation requirements drive supplier qualification complexity.
- Flavor Extracts:Solvent-extracted or cold-pressed aromatic compounds offering precise taste replication without volumetric bulk. European food manufacturers in Germany and Italy expand procurement as EU Flavouring Regulation withdrawals compress artificial additive tolerances.
- Spice Mixes:Pre-blended turnkey seasoning systems reduce in-house formulation complexity for emerging-market processors.
- Aromatic Herbs:Botanical materials in raw or minimally processed form serve traditional extraction houses and specialty food producers.
Essential oils hold the largest share; momentum sits with spice mixes.
Application:
Cost tier stratification separates commodity-grade essences for mass-market beverages from pharmaceutical-grade materials commanding analytical certification premiums.
- Food & Beverage:Dominant value pool encompassing flavor modulation across processed foods, beverages, and culinary preparations. Clean-label reformulation mandates from FDA and EFSA accelerate botanical substitution for synthetic additives in US and European manufacturing.
- Personal Care:Fragrance-grade essences for cosmetics and toiletries require IFRA compliance documentation and allergen labeling support.
- Household Products:Lower-specification aromatic inputs for cleaning and air care applications compete on cost against synthetic alternatives.
- Pharmaceutical:USP-grade essential oils for therapeutic and nutraceutical applications demand extensive analytical dossiers and FDA drug master file submissions.
Food and beverage commands the dominant value pool; pharmaceutical applications are climbing the fastest.
Distribution Channel:
Volume concentration favors food service and industrial direct procurement, while online retail fragments order patterns across small-batch buyers.
- Online Retail:E-commerce platforms serve home cooks and small-scale food entrepreneurs with fractional pack sizes and rapid turnaround.
- Supermarkets:Mass-market retail channels move standardized retail-packaged essences for home baking and cooking applications.
- Specialty Stores:Gourmet retailers in France and Italy supply premium single-origin extracts to discerning consumers and small restaurants.
- Food Service:Chef-facing technical salesforces anchor premium essence procurement through formulation partnership models in Spain and France.
Food service holds the largest share; online retail is gaining share fastest.
End User:
Customer type determines specification depth, with food manufacturers requiring full regulatory dossiers and home cooks accepting basic usage guidance.
- Professional Chefs:European restaurant group consolidation amplifies buyer power and rewards suppliers offering kitchen-validated application support.
- Home Cooks:Retail-packaged essences for domestic culinary use prioritize convenience and storage stability over technical documentation.
- Food Manufacturers:Industrial processors across France, Germany, and Italy seek standardized oleoresins with batch-to-batch consistency guarantees for reformulated clean-label product lines.
- Beverage Producers:Soft drink and alcoholic beverage manufacturers demand water-soluble extract formats with specific gravity and refractive index specifications.
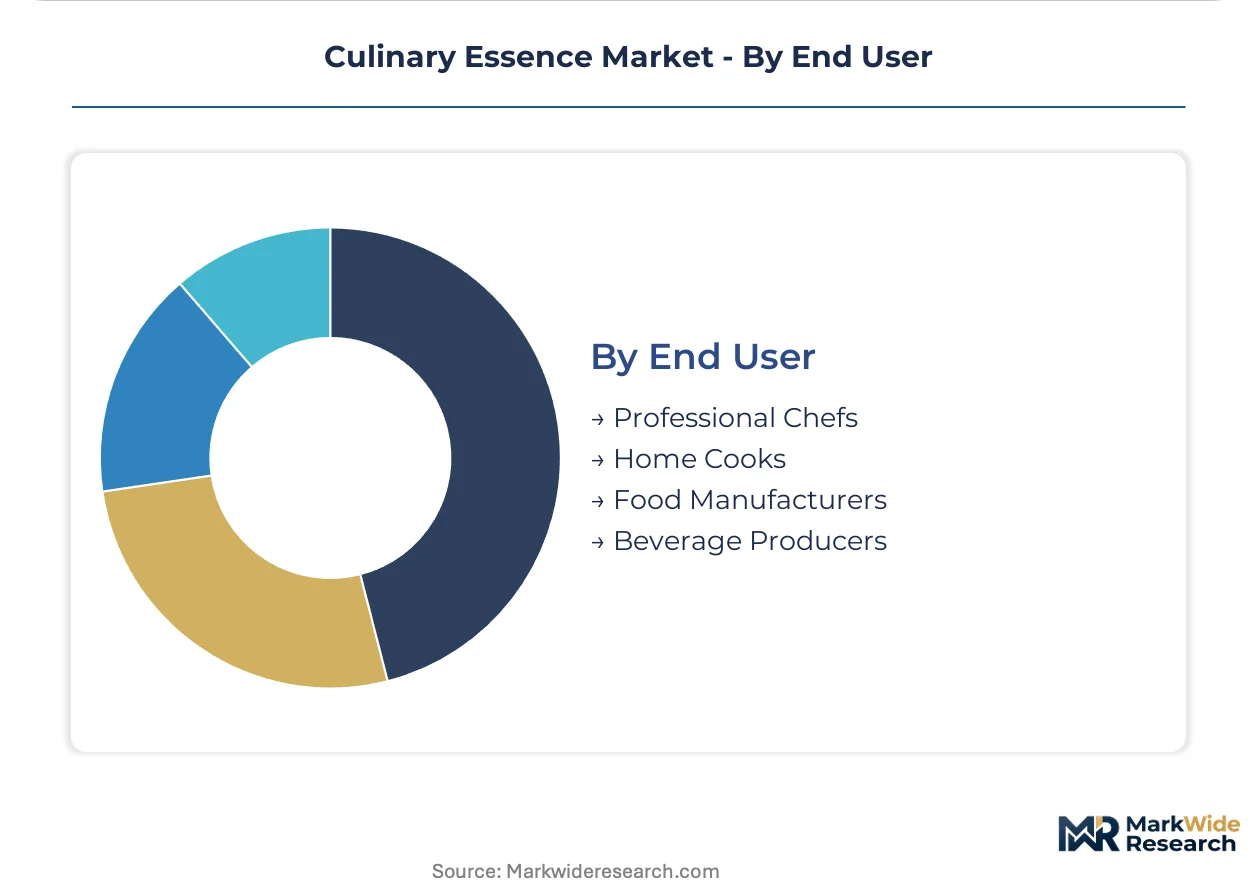
Food manufacturers hold the largest share; beverage producers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in French extraction houses while Indian processors absorb raw material volatility. Grasse-based suppliers command premium spreads on oleoresin contracts. Iranian saffron brokers and Guatemalan cardamom traders capture upstream margins that compress European distiller profitability.
France
Grasse-based aromatic compound houses supply standardized oleoresins to global fragrance-flavor conglomerates, anchoring premium supply chains. EFSA solvent residue documentation requirements under EU Flavouring Regulation 1334/2008 drive supplier qualification complexity for exports. The Provence-Alpes-Côte d'Azur cluster concentrates fractional distillation expertise for heat-sensitive herb processing.
Germany
Industrial food manufacturers in Bavaria and North Rhine-Westphalia expand procurement of natural flavor extracts for clean-label reformulation. REACH registration requirements for food-contact extraction agents impose qualification timelines that freeze supplier switches. The ECHA regulatory framework shapes solvent residue thresholds across Central European processing networks.
United States
FDA Food Safety Modernization Act preventive controls reshape extraction solvent residue limits for imported botanical materials. Beverage producers in California and Texas demand water-soluble extract formats with specific gravity certifications. The Pacific Northwest houses emerging cold-pressing operations for premium culinary oil segments.
India
BIS certification mandates add compliance layers for exporters targeting subcontinent food manufacturing growth. Spice processors in Gujarat and Maharashtra seek turnkey seasoning systems that reduce in-house blending complexity. The Western India cluster concentrates solvent-extraction infrastructure for export-oriented oleoresin production.
Switzerland
Mid-sized flavor houses deploy gas chromatography-mass spectrometry fingerprinting to accelerate botanical screening cycles. Swissmedic oversight intersects with EFSA novel food evaluations for borderline botanical species. The Basel-Zurich corridor concentrates AI-pattern-matching platforms for virtualizing traditional organoleptic assessments.
Culinary Essence Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin on yield-constrained botanicals. The vendor base stratifies between captive-sourcing conglomerates and toll-manufacturing mid-caps lacking distillation infrastructure. Three archetypes dominate: Madagascar vanilla estate owners securing oleoresin supply chains, fractional distillation specialists with heat-sensitive herb capabilities, and chef-facing technical service organizations displacing traditional brokers. Competitive moves concentrate on asset-light contract extraction agreements and domestication programs for borderline botanical species.
Within the captive-sourcing tier, Givaudan represents vertical control over Madagascar vanilla estates. Firmenich exemplifies proprietary fractional distillation capabilities for premium aromatic compounds. Kerry Group anchors the technical service archetype through chef-facing formulation partnerships in European food service.
| Leading Market Players |
|---|
| Firmenich |
| Kerry Group |
| Givaudan |
| Sensient Technologies |
| Takasago |
| IFF |
| Mane |
| Robertet Group |
| Symrise |
| Others |
Value Network & Pricing Analysis
The Marseille-Fos freight corridor channels Iranian saffron and Guatemalan cardamom into European distillation hubs, with container cost volatility amplifying raw material broker pricing power while forcing downstream three-tier pricing structure across premium, standard, and economy certification grades.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across organic-certified, conventional food-grade, and technical-grade tiers. Price differentiation rests on EFSA solvent residue documentation and batch-to-batch consistency guarantees, with cost compression in mass-market tiers intensifying because biotechnology-derived fermentation platforms undercut natural extraction economics. Beverage producers demonstrate highest price sensitivity due to volume scale pressures, while pharmaceutical-grade buyers accept certification premiums for USP-grade analytical dossiers.
Supply Chain Analysis
Extended payment terms from Grasse-based extraction houses to Madagascar vanilla estate cooperatives are reshaping working capital requirements across the value chain. Geographic supply concentrates in France, India, and Switzerland, with raw material dependencies on Iranian saffron stigmas, Guatemalan cardamom pods, and Madagascan vanilla beans. Single-source vulnerability in wild-harvested Mediterranean herbs creates qualification bottlenecks under EFSA novel food evaluations. Distribution runs through chef-facing technical salesforces in European food service and direct procurement contracts with industrial food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Culinary essence incumbents face a substitution defense against biotechnology-derived aromatic molecules from precision fermentation platforms that threaten to displace natural extraction in mass-market applications.
For Market Incumbents: Entrench captive supply relationships with Madagascar vanilla estate cooperatives and Iranian saffron broker networks to secure yield-constrained feedstocks. Accelerate in-house fractional distillation capacity for heat-sensitive herb processing to defend premium positioning against synthetic alternatives. Prioritize EFSA novel food dossier submissions for borderline botanical domestication programs.
For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified solvent-extraction infrastructure serving export-oriented oleoresin production. Target Gujarat-based spice processors seeking turnkey seasoning systems with pre-blended formulation partnerships. Deploy asset-light toll manufacturing agreements to bypass capital-intensive distillation infrastructure requirements.
For Investors and Strategic Acquirers: Mid-sized Swiss flavor houses with AI-pattern-matching GC-MS platforms present consolidation targets as digital screening virtualizes traditional organoleptic assessment roles. Long-term viability hinges on regulatory divergence between FDA preventive controls, EFSA novel food restrictions, and BIS certification mandates creating formulation complexity that rewards multi-jurisdiction compliance capabilities. Monitor EFSA botanical approval timelines as inflection indicators for permissible extraction source list expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Estate Sourcing | Givaudan's Madagascar vanilla plantations secure oleoresin supply chains against raw material broker volatility. |
| AI-Enabled Botanical Screening | Swiss mid-caps deploy GC-MS fingerprinting to compress R&D cycles from months to weeks. |
| Chef-Facing Technical Salesforce Expansion | Kerry Group's Taste & Nutrition division displaces traditional brokers through kitchen-validated formulation partnerships. |
| Domestication Program Investment | Firms accelerate borderline species cultivation to preempt EFSA novel food status restrictions on wild-harvested materials. |
| Carbon-Negative Distillation Infrastructure | EU Green Deal funding streams reward renewable-powered extraction operations with preferential contract access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food evaluation registers, EU customs trade data for oleoresin imports, and fragrance-flavor conglomerate SEC filings. Interviews with extraction house technical directors, procurement leads at German industrial food manufacturers, Grasse-based master perfumers, and BIS certification auditors informed supply chain and regulatory dynamics. Bottom-up volume modeling across product categories triangulates against top-down value aggregation from trade flow analysis.
Forecast inputs span fold-strength standardization tiers, solvent extraction technology adoption curves, and clean-label reformulation penetration rates across food manufacturing segments. Segmentation dimensions include product type volatility, application certification grade, distribution channel service intensity, and end-user specification depth. CAGRs derive from regression analysis of historical procurement volumes against regulatory mandate implementation timelines and biotechnology substitution threat progression.
Sensitivities concentrate around EFSA botanical approval withdrawals, Iranian agricultural output disruption, and fermentation platform cost parity achievement. Forecasts embed assumptions regarding regulatory stability and raw material yield patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
China Food Colorants Market