
 Bitter Apricot Extract Market | 2026-2036
Bitter Apricot Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Bitter Apricot Extract Market Analytics
Pharmaceutical-grade amygdalin specification is collapsing the gap between cosmetic and therapeutic applications. Hunan Nutramax Inc. leverages its Changsha extraction complex to dominate domestic API-grade supply. Shaanxi Guanjie Technology Co., Ltd. anchors wildcrafted sourcing networks across the Qinling Mountains. Xi'an Sost Biological Science & Technology Co., Ltd. differentiates through ISO-certified amygdalin standardization protocols.
Bitter apricot extract comprises cyanogenic glycosides—primarily amygdalin—typically standardized to 98% purity through ethanol extraction and crystallization, serving as an active ingredient in oncology adjuvant therapies and metabolic health supplements. Powder formats lead volume due to blending flexibility in capsule and tablet production, while liquid extracts capture premium positioning in functional beverage formulations. Organic-source material commands margin concentration as EFSA residue limits tighten conventional supply chains.
FDA oversight of amygdalin as an unapproved drug ingredient restricts US therapeutic marketing channels, while EFSA maximum levels for cyanogenic compounds in supplements shape European formulation ceilings. China's NMPA and SAMR jointly govern traditional medicine extract licensing, creating dual compliance burdens for exporters. Stakeholders must monitor evolving cyanide-release testing methodologies as regulatory thresholds tighten across major import jurisdictions.
Market Dynamics
EFSA's tightening maximum levels for cyanogenic glycosides in supplements are compressing conventional supply chains while redirecting procurement toward certified organic extraction facilities in Hunan and Shaanxi provinces.
Growth Catalysts
- Oncology adjuvant demand:Amygdalin standardization to 98% purity through ethanol crystallization is meeting formulation requirements for immune-support protocols in German dietary supplement manufacturing.
- REACH compliance differentiation:EU Novel Food Catalogue alignment is creating procurement preference for ISO-certified extractors with validated cyanide-release testing methodologies.
- Functional beverage premiumization:Liquid extract formats are capturing margin concentration in metabolic health positioning as capsule blending saturates.
Market Restraints
- Raw material volatility:Wildcrafted apricot kernel availability from Qinling Mountain networks fluctuates with harvest cycles and foraging labor constraints.
- FDA therapeutic channel blockage:Unapproved drug ingredient classification prevents US marketing of amygdalin for oncology applications, limiting revenue diversification.
- Substitution pressure:Synthetic B17 analogs and alternative cyanogenic glycoside sources from cassava and flaxseed are eroding bitter apricot's ingredient exclusivity.
Strategic Opportunities
- Cosmeceutical crossover:Pharmaceutical-grade amygdalin specification collapse is enabling topical antioxidant formulations previously segmented from nutraceutical supply.
- SAMR dual-licensing arbitrage:Traditional medicine extract licensing under China's NMPA-SAMR joint governance creates compliance moats for domestic-first exporters.
- Direct-to-practitioner channels:Integrative medicine clinics in North America are bypassing retail supplement distribution for bulk amygdalin procurement.
Industry Challenges
- Analytical chemistry talent scarcity:Validated cyanogenic glycoside quantification requires HPLC-MS specialists in short supply across extraction facilities.
- Dual jurisdiction certification timelines:Simultaneous EFSA residue compliance and SAMR export licensing extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitter Apricot Extract Market |
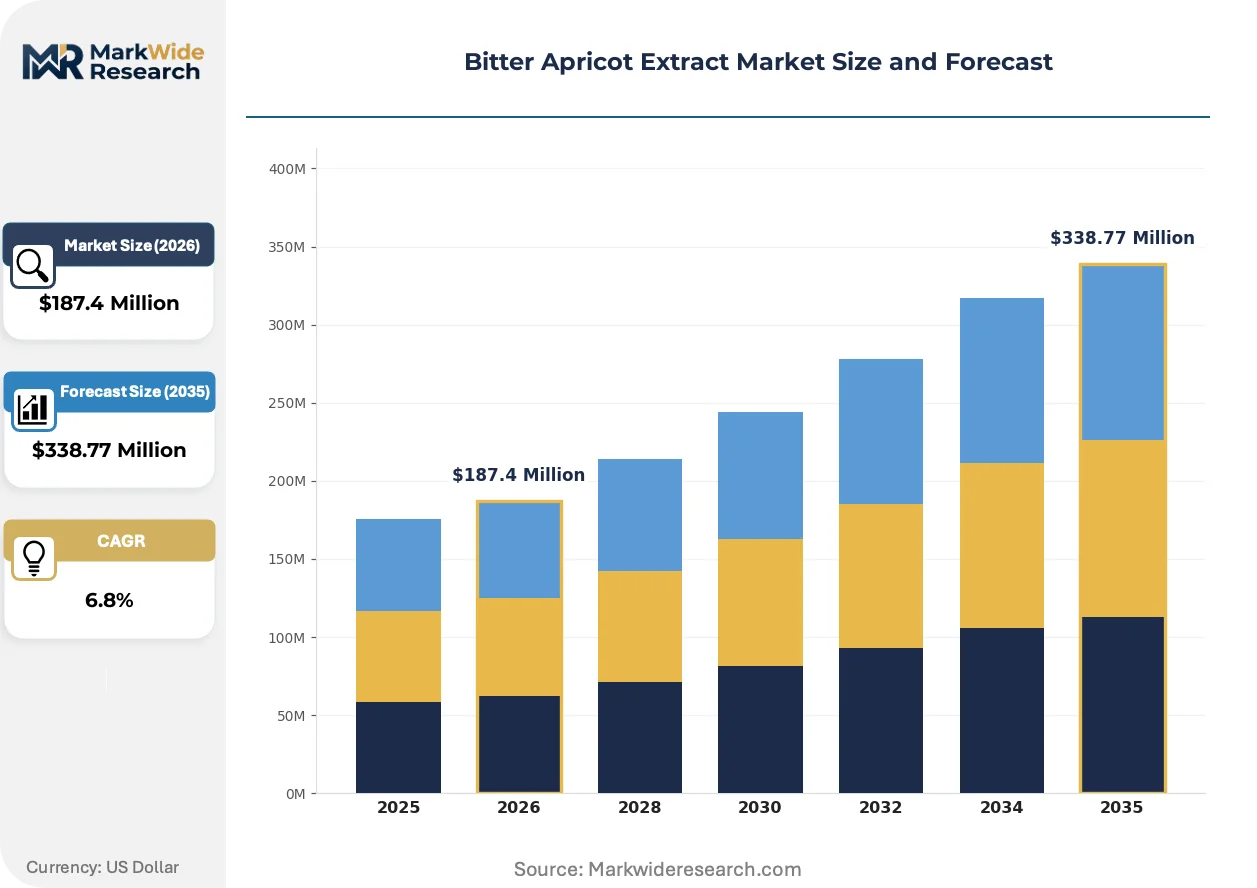
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tincture End User: Pharmaceuticals, Dietary Supplements, Cosmetics, Food & Beverages Source: Organic, Conventional, Wildcrafted, Cultivated Application: Nutraceuticals, Herbal Remedies, Skin Care, Flavored Drinks |
| Companies Covered | Hunan Nutramax Inc., Shaanxi Guanjie Technology Co., Ltd., Xi’an Sost Biological Science & Technology Co., Ltd., Organic Herb Inc., Kingherbs Limited, Nutra Green, Superkost GmbH, Herbo Nutra, Changsha Heking Biotechnology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitter Apricot Extract Market Evolving Landscape
Supercritical CO2 extraction protocols are displacing ethanol-based crystallization as the dominant amygdalin isolation method, altering capital intensity and purity yield tradeoffs across supplier tiers.
Supercritical fluid extraction technology is fragmenting the supplier base by enabling mid-scale processors to achieve API-grade purity without Changsha-scale infrastructure investments. German encapsulation houses are qualifying these alternative sources for immune-support formulations. The technology is fragmenting volume concentration previously held by ethanol-crystallization specialists with captive solvent recovery systems.
REACH Annex XVII amendments on cyanogenic compound thresholds are forcing reformulation of legacy amygdalin concentrations in EU-bound supplements. EFSA guidance evolution is compressing acceptable daily intake ranges and mandating batch-level cyanide-release documentation. German manufacturers are responding by specifying sub-50 ppm cyanogenic glycoside grades previously considered non-standard.
Practitioner-directed procurement is consolidating demand around compounding pharmacies and integrative medicine networks, bypassing retail supplement distribution entirely. North American naturopathic clinics are establishing direct supply relationships with Shaanxi extraction facilities. This channel rotation is most visible in California and Oregon where scope-of-practice regulations permit amygdalin dispensing under clinical supervision.
Bitter Apricot Extract Market Segmentation
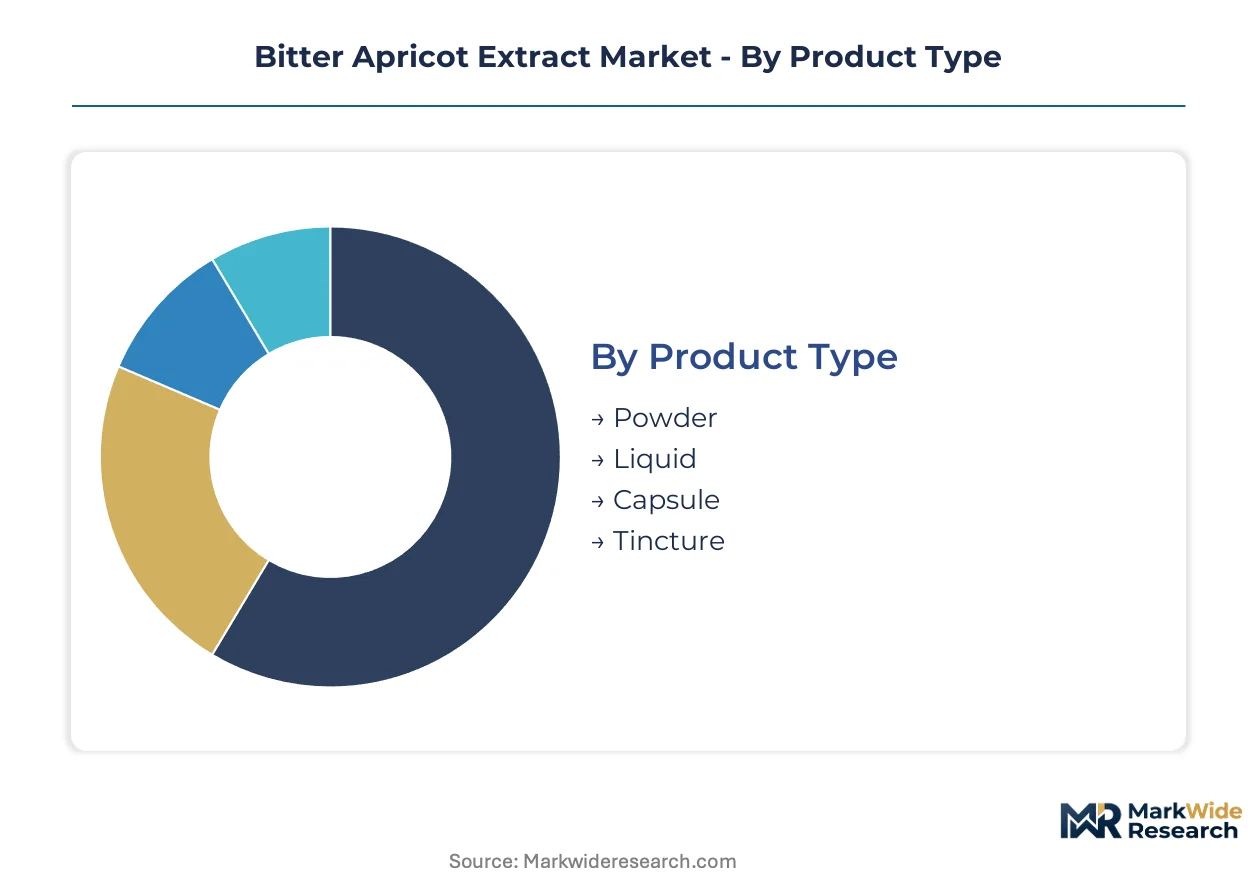
Bitter apricot extract segmentation tracks amygdalin purity grades, extraction methodologies, and regulatory compliance tiers that determine channel access across pharmaceutical and nutraceutical buyers. Powder and liquid formats diverge on capital intensity and certification requirements, while organic sourcing commands premium positioning under tightening EFSA residue protocols.
Product Type:
Powder formats capture the deepest margin pools through bulk encapsulation contracts and API-grade standardization, while liquid extracts concentrate value in functional beverage premiumization.
- Powder:Standardized amygdalin crystalline powder at 98% purity serves capsule and tablet manufacturing through ethanol or supercritical CO2 extraction. German dietary supplement houses specify this grade for immune-support formulations under REACH-compliant sourcing protocols.
- Liquid:Hydroalcoholic tinctures and concentrated extracts enable metabolic health positioning in ready-to-drink applications. California functional beverage startups are qualifying Hunan-sourced liquid extracts for direct-infusion manufacturing lines.
- Capsule:Pre-encapsulated amygdalin reduces formulation complexity for mid-scale supplement brands lacking in-house blending capacity.
- Tincture:Alcohol-based extracts target practitioner-directed dispensing through integrative medicine clinics in Oregon and naturopathic networks.
Powder holds installed capacity. Liquid is rotating up the share rankings.
End User:
Pharmaceutical procurement concentrates on validated cyanide-release documentation, while dietary supplement manufacturing absorbs volume through less stringent purity tiers.
- Pharmaceuticals:API-grade amygdalin for oncology adjuvant protocols requires batch-level HPLC-MS verification and dual jurisdiction certification under China's NMPA-SAMR governance. Shaanxi extraction facilities dominate this channel through captive wildcrafted sourcing networks.
- Dietary Supplements:Encapsulation houses in Germany and North America drive demand for 50-98% purity grades, with EFSA maximum levels for cyanogenic glycosides compressing acceptable concentration ranges.
- Cosmetics:Topical antioxidant formulations leverage pharmaceutical-grade specification collapse, enabling cosmeceutical crossover previously segmented from therapeutic supply.
- Food & Beverages:Flavored drink applications face the tightest regulatory ceilings, with FDA unapproved drug ingredient classification blocking amygdalin marketing for therapeutic claims in US channels.
Dietary supplements anchor volume absorption. Pharmaceuticals command the steepest expansion trajectory on pricing power.
Source:
Organic certification creates compliance moats as conventional supply chains face EFSA residue limit compression, while wildcrafted networks concentrate in specific mountain ecosystems.
- Organic:Certified organic extraction facilities in Hunan province command procurement preference from EU-bound manufacturers facing REACH Annex XVII amendments on cyanogenic compound thresholds.
- Conventional:Standard cultivation supply faces margin compression from tightening purity thresholds and substitution pressure from synthetic B17 analogs.
- Wildcrafted:Qinling Mountain foraging networks supply Shaanxi Guanjie Technology with raw material subject to harvest cycle volatility and labor constraints.
- Cultivated:Controlled orchard production enables batch consistency for encapsulation-grade powder, with Changsha-scale infrastructure investments supporting volume contracts.
Cultivated holds installed capacity. Organic is rotating up the share rankings.
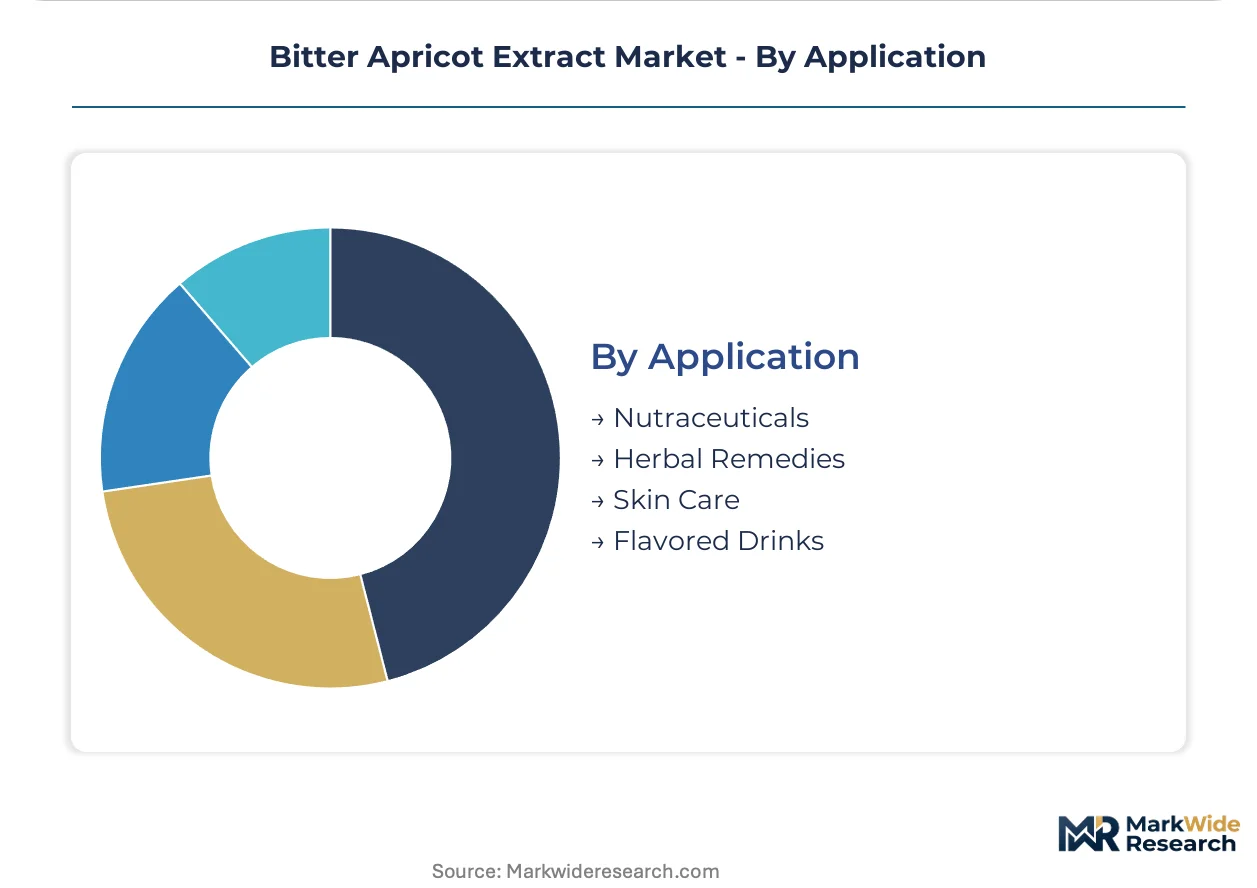
Application:
Nutraceutical encapsulation absorbs the widest purity range, while herbal remedy channels bypass retail distribution through practitioner-directed procurement consolidation.
- Nutraceuticals:Capsule and tablet formulations span 50-98% amygdalin grades, with German manufacturers specifying sub-50 ppm cyanogenic glycoside thresholds previously considered non-standard.
- Herbal Remedies:Traditional medicine extract licensing under China's joint NMPA-SAMR governance creates dual compliance burdens that domestic-first exporters leverage as competitive moats.
- Skin Care:Topical antioxidant positioning benefits from pharmaceutical-grade purity collapse, with supercritical CO2 extraction enabling mid-scale processors to qualify for cosmetic ingredient supply.
- Flavored Drinks:Functional beverage infusion requires liquid extract formats with validated cyanide-release testing, capturing premium positioning as capsule blending saturates.
Nutraceuticals anchor volume absorption. Herbal remedies are gaining share fastest on channel rotation toward direct practitioner supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German encapsulation houses exhibit the lowest price elasticity, absorbing certified-organic premiums for REACH-compliant amygdalin grades, while North American dietary supplement distributors face acute substitution pressure from synthetic B17 analogs.
Germany
Dietary supplement manufacturers in Bavaria and North Rhine-Westphalia drive procurement of 98% purity amygdalin crystalline powder for immune-support protocols. EFSA maximum levels for cyanogenic glycosides under REACH Annex XVII amendments compress acceptable concentration ranges, forcing reformulation toward sub-50 ppm grades. The Eindhoven-to-Düsseldorf corridor concentrates encapsulation capacity where German houses qualify Hunan-sourced extracts for novel food compliance.
United States
California and Oregon naturopathic clinics consolidate practitioner-directed procurement, bypassing retail supplement distribution for bulk amygdalin supply. FDA oversight classifies amygdalin as an unapproved drug ingredient, blocking therapeutic marketing channels and limiting revenue diversification. The Pacific Northwest functional beverage cluster qualifies liquid extract formats for direct-infusion manufacturing despite regulatory ceilings.
China
Changsha-scale extraction complexes in Hunan province dominate API-grade amygdalin supply through ethanol crystallization and emerging supercritical CO2 protocols. NMPA and SAMR joint governance of traditional medicine extract licensing creates dual compliance burdens that domestic-first exporters leverage as competitive moats. Shaanxi's Qinling Mountain wildcrafted sourcing networks anchor pharmaceutical-grade procurement for oncology adjuvant applications.
Canada
Health Canada and PMRA oversight of natural health products shapes amygdalin import thresholds, with British Columbia integrative medicine clinics establishing direct supply relationships with Asian extraction facilities. The Ontario dietary supplement manufacturing corridor absorbs mid-purity grades for encapsulated formulations. Vancouver-based functional beverage startups pilot liquid extract infusion under stricter cyanogenic glycoside documentation requirements.
Switzerland
Swissmedic pharmaceutical licensing creates premium positioning for validated cyanide-release documentation in oncology adjuvant supply. Basel-area encapsulation specialists specify pharmaceutical-grade amygdalin where purity collapse between cosmetic and therapeutic applications enables cosmeceutical crossover. The country's private-label supplement sector concentrates procurement around ISO-certified extractors with batch-level HPLC-MS verification.
Bitter Apricot Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with supercritical CO2 extraction specialists commanding premium positioning while ethanol-crystallization incumbents defend volume contracts through captive solvent recovery systems. The supplier base fragments across three strategic tiers: Changsha-scale infrastructure operators with integrated wildcrafted sourcing networks, mid-scale processors leveraging supercritical fluid technology to achieve API-grade purity, and regional encapsulation houses with backward integration into extraction. Dominant competitive moves include dual jurisdiction certification investments and practitioner-direct channel bypass of retail distribution.
Among Chinese extraction specialists, Hunan Nutramax Inc., Shaanxi Guanjie Technology Co., Ltd., and Xi'an Sost Biological Science & Technology Co., Ltd. occupy positions across the technology-cost spectrum. Hunan Nutramax exemplifies the infrastructure-heavy archetype with Changsha-scale ethanol crystallization capacity. Shaanxi Guanjie anchors wildcrafted sourcing network control through Qinling Mountain procurement relationships. Xi'an Sost represents the certification-driven tier with ISO-standardized amygdalin protocols qualifying for EU Novel Food Catalogue alignment. These three entities collectively illustrate how geographic concentration in Hunan and Shaanxi provinces intersects with divergent technology bets on extraction methodology.
| Leading Market Players |
|---|
| Hunan Nutramax Inc. |
| Shaanxi Guanjie Technology Co., Ltd. |
| Xi'an Sost Biological Science & Technology Co., Ltd. |
| Organic Herb Inc. |
| Kingherbs Limited |
| Nutra Green |
| Superkost GmbH |
| Herbo Nutra |
| Changsha Heking Biotechnology Co., Ltd |
| Others |
Value Network & Pricing Analysis
Synthetic B17 analog substitution is compressing conventional amygdalin premiums while redirecting procurement toward certified organic extraction facilities in Hunan and Shaanxi provinces where EFSA residue compliance commands margin concentration.
Pricing Analysis
After-sales certification documentation drives lifetime value through recurring batch-level HPLC-MS verification contracts. Three-tier pricing structure across API-grade, encapsulation-grade, and beverage-grade purity levels stratifies by cyanide-release testing stringency. Cost compression in conventional wildcrafted supply is intensifying because Qinling Mountain harvest volatility limits volume scaling. German encapsulation houses exhibit the lowest price sensitivity while North American dietary supplement distributors face acute margin pressure from synthetic alternatives.
Supply Chain Analysis
China anchors global amygdalin extraction through Changsha-scale ethanol crystallization complexes and emerging supercritical CO2 facilities in Hunan province. The supply chain draws from apricot kernel cultivation networks, wildcrafted Qinling Mountain foraging operations, and certified organic orchard partnerships. Single-source vulnerability concentrates in Shaanxi's wildcrafted procurement relationships subject to climate-driven harvest fluctuations. Distribution runs through direct-to-practitioner channels consolidating around integrative medicine clinics and compounding pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery justified by EFSA regulatory tightening that periodically eliminates non-compliant suppliers and resets pricing floors for certified organic tiers.
For Market Incumbents: Secure backward integration into captive organic cultivation networks to defend against synthetic B17 substitution pressure. Deepen ISO-certified amygdalin standardization protocols as compliance moats against mid-scale supercritical CO2 entrants. Prioritize dual jurisdiction certification investments under China's NMPA-SAMR joint governance to extend product launch cycle advantages.
For New Entrants and Emerging Players: Anchor in California and Oregon practitioner-directed procurement channels where naturopathic dispensing regulations permit clinical supervision models bypassing retail distribution. Target liquid extract formats for Pacific Northwest functional beverage manufacturing as the most penetrable white space. Qualify through direct supply relationships with compounding pharmacies seeking validated cyanide-release documentation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale processors with supercritical CO2 technology achieving API-grade purity without Changsha-scale infrastructure. Long-term viability over the next decade hinges on regulatory arbitrage capabilities across EFSA, FDA, and SAMR jurisdictions. Watch EFSA maximum level amendments for cyanogenic glycosides as the primary inflection signal compressing conventional supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Jurisdiction Certification Investment | NMPA-SAMR alignment creates compliance moats extending launch cycles by 18-24 months. |
| Supercritical CO2 Capacity Buildout | Mid-scale processors achieve API-grade purity without Changsha-scale solvent recovery infrastructure. |
| Practitioner-Direct Channel Expansion | Integrative medicine clinics in California and Oregon bypass saturated retail supplement distribution. |
| Organic Cultivation Backward Integration | Certified orchard networks command procurement preference under tightening EFSA residue protocols. |
| Analytical Chemistry Talent Acquisition | HPLC-MS specialists enable validated cyanogenic glycoside quantification for batch-level documentation. |
Research Methodology
The analysis maps amygdalin purity grades, extraction methodologies, and regulatory compliance tiers, each validated through extraction facility technical directors, dietary supplement procurement managers, and regulatory affairs specialists. Primary interviews with Hunan and Shaanxi province plant operators combined with secondary validation from EFSA guidance documents, NMPA licensing records, and customs trade data support bottom-up and top-down triangulation across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across powder, liquid, capsule, and tincture format segments. The analytical framework models purity grade tiers, end-use applications spanning pharmaceuticals to functional beverages, and regional regulatory clusters. CAGRs were derived through demand elasticity analysis incorporating EFSA maximum level evolution and substitution pressure from synthetic B17 analogs.
Material uncertainties — regulatory threshold amendments, harvest cycle volatility, and analytical chemistry talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions around certification timeline stability and practitioner channel regulatory permissiveness. Recalibration cycles align with material shifts in EFSA guidance evolution and SAMR export licensing procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market