
 Corn Syrup Market | 2026-2036
Corn Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Syrup Market Analysis
Market Context with Strategic Players
Agronomist and food-process engineering talent is bifurcating between legacy wet milling corridors and emerging organic syrup operations. Cargill, Incorporated leverages its integrated grain origination network across the US Midwest to secure cost-advantaged feedstock positions. Archer Daniels Midland Company sustains one of the largest corn wet milling footprints globally, with capacity concentrated along Illinois River access points. Ingredion Incorporated specializes in non-GMO and clean-label syrup variants that command premium positioning in European export channels.
Technical Definition and Structural Segments
Corn syrup denotes a viscous sweetener manufactured through enzymatic hydrolysis of corn starch, yielding glucose polymers with dextrose equivalence ratings typically spanning 20 to 95 that determine sweetness intensity and functional behavior in food matrices. High fructose corn syrup dominates volume throughput due to its cost parity against sucrose in carbonated beverage applications, while organic corn syrup represents the fastest-growing product type as clean-label mandates propagate through North American and European retail channels. The food and beverage end use industry anchors absolute demand, though pharmaceutical-grade specifications are emerging as a concentrated margin pool for certified producers.
Regulatory Frame and Forward Outlook
The US FDA governs corn syrup labeling under Food Labeling Guide provisions, while the EPA regulates effluent discharge from wet milling facilities under Clean Water Act permits, collectively elevating compliance capital requirements for facility operators. The EU Green Deal and F-Gas Regulation indirectly constrain energy-intensive starch processing, nudging European producers toward efficiency retrofits or import dependence. Stakeholders must monitor evolving added-sugar taxation schemes and biofuel policy competition for corn feedstock, as these dual pressures will determine regional cost structures and sourcing arbitrage opportunities.
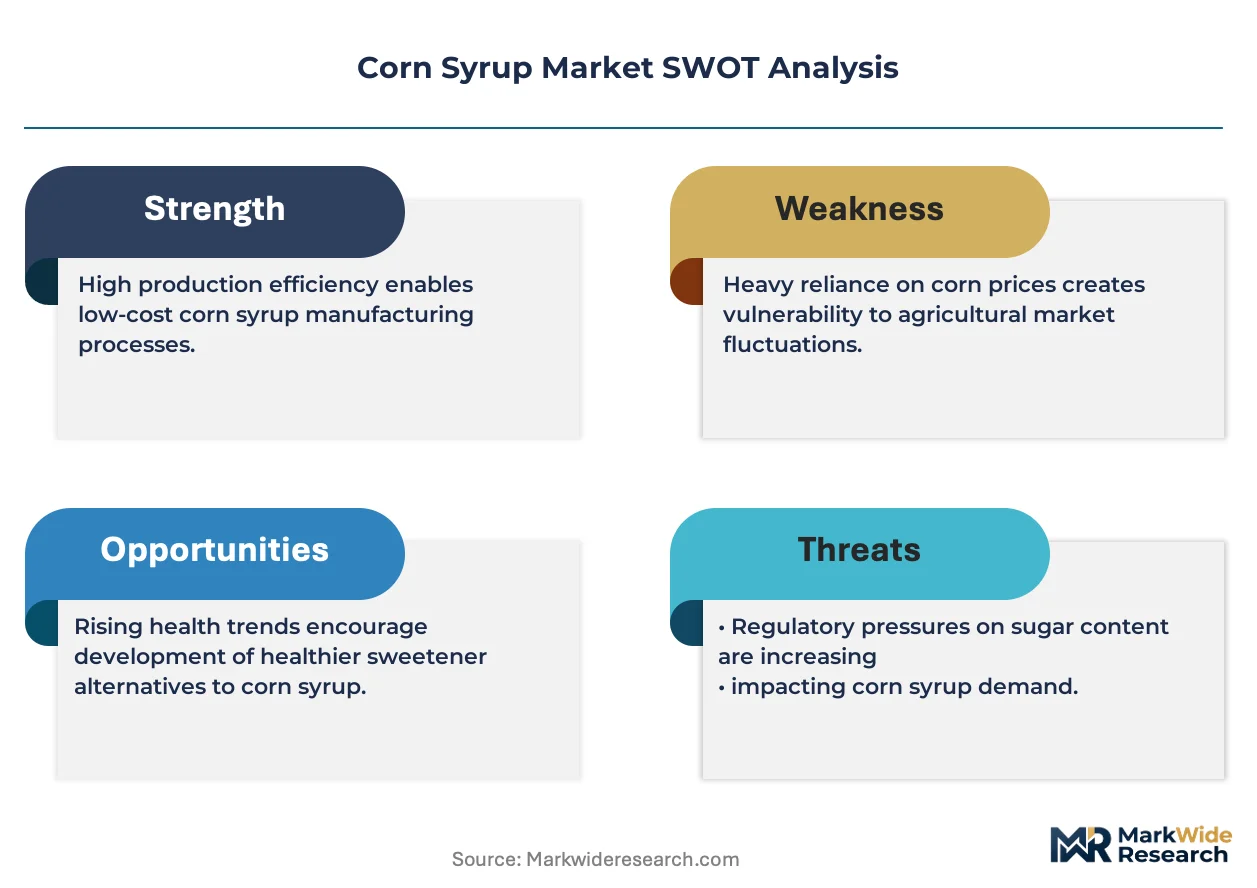
Market Dynamics
The US FDA's added sugars labeling mandate is compressing demand for high-fructose variants while redirecting capital toward enzymatic isomerization retrofits and clean-label alternatives.
Growth Catalysts
- Clean-label mandates:North American and European retail channels are accelerating certification requirements for non-GMO syrup variants, pulling capacity expansions toward identity-preserved corn supply chains.
- Beverage reformulation in Latin America:Mexican and Brazilian bottlers are recalibrating sweetness profiles around HFCS-55 specifications to maintain cost parity against cane sugar.
- Pharmaceutical-grade specifications:USP-grade dextrose monohydrate for IV solutions is creating concentrated margin pools for producers with dedicated fermentation-grade facilities.
Market Restraints
- Feedstock competition from biofuels:Renewable Fuel Standard mandates in the United States divert corn supply toward ethanol production, elevating starch input costs for wet millers.
- Added-sugar taxation schemes:Mexico's IEPS levy on sugar-sweetened beverages directly compresses HFCS offtake volumes in the country's central plateau bottling corridor.
- Substitution by natural sweeteners:Stevia and monk fruit extracts are capturing reformulation slots in premium beverage lines previously held by corn-derived sweeteners.
Strategic Opportunities
- Underpenetrated organic certification:Argentina's Pampas grain belt offers expansion terrain for identity-preserved organic syrup production serving export markets.
- EU Green Deal efficiency incentives:European producers accessing Just Transition Mechanism funds can retrofit evaporative systems to reduce natural gas intensity.
- Direct-to-brewery distribution:Craft brewing clusters in Colorado and Oregon are sourcing maltose-rich syrup variants through bypass channels outside conventional ingredient distributors.
Industry Challenges
- Enzyme engineering talent scarcity:Wet milling operations face recruitment gaps for process engineers capable of optimizing glucoamylase conversion rates in continuous systems.
- Clean Water Act compliance timelines:EPA effluent discharge permits require multi-year capital cycles for biological oxygen demand reduction infrastructure.
- Identity-preserved supply chain integrity:Non-GMO certification demands segregation protocols that increase handling costs and traceability system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Syrup Market |
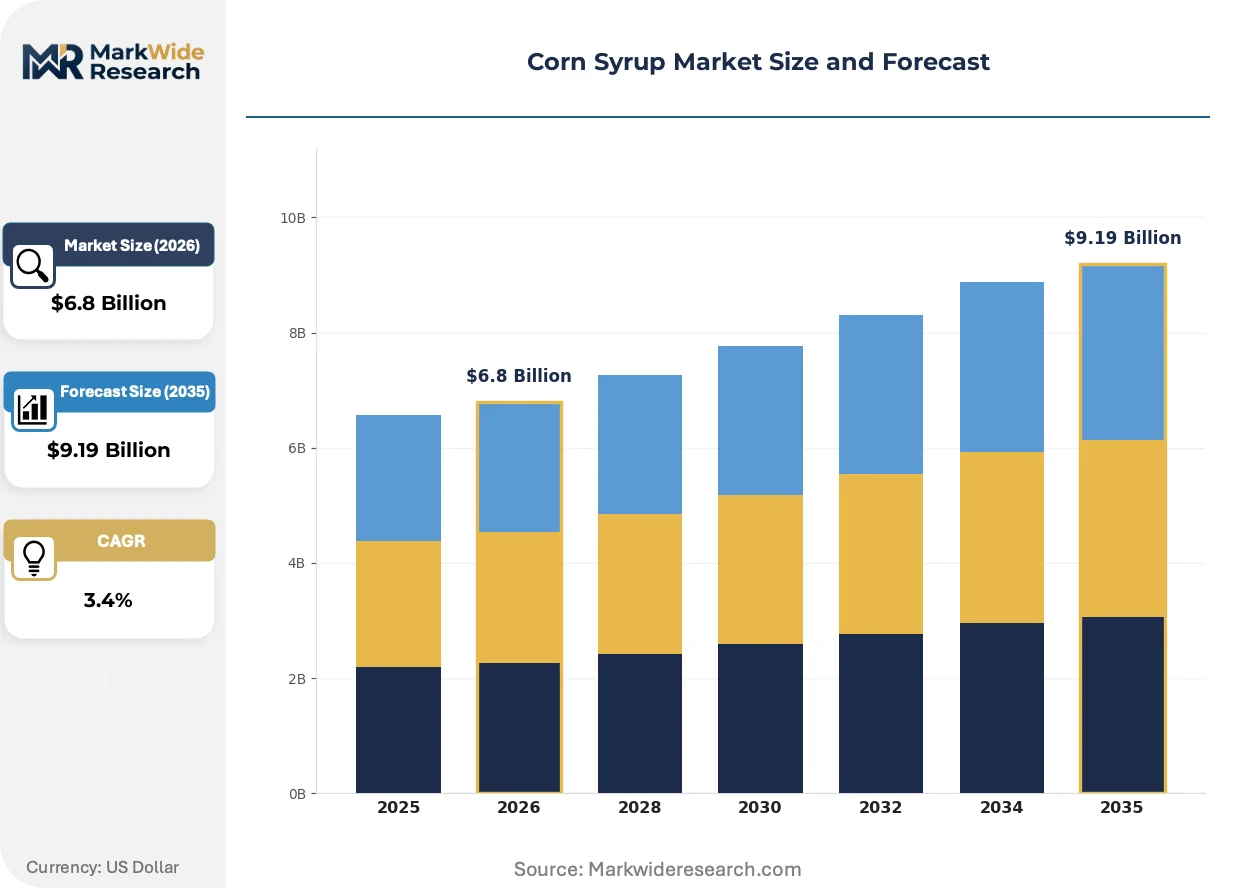
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Corn Syrup, Dark Corn Syrup, High Fructose Corn Syrup, Organic Corn Syrup End Use Industry: Food & Beverage, Confectionery, Bakery, Pharmaceuticals Packaging Type: Bottles, Drums, Bulk Containers, Pouches Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Tate & Lyle PLC, Corn Products International, Archer Daniels Midland Company, Grain Processing Corporation, Tereos SCA, Cargill, Incorporated, Roquette Frères S.A., MGP Ingredients, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Syrup Market Emerging Trajectories
Enzymatic processing advances and regulatory disclosure requirements are splitting the market between commodity-scale HFCS operations and specialized clean-label syrup production.
Continuous enzymatic isomerization using immobilized glucose isomerase columns is fragmenting the traditional batch-processing paradigm. Large beverage manufacturers in the United States are retrofitting Illinois River corridor facilities to capture efficiency gains. This technology is fragmenting capital deployment patterns, with mid-scale millers unable to justify conversion investments retreating toward standard dextrose production.
REACH registration requirements for processing aids are compelling European wet millers to substitute conventional enzyme stabilizers with bio-based alternatives. The industrial consequence is reformulated glucoamylase cocktails with modified temperature stability profiles. Pharmaceutical-grade syrup specifications are most affected, with certified producers accelerating third-party audits to maintain EMA-compliant documentation trails.
Buyers in Mexico's soft drink bottling clusters are consolidating procurement decisions at the corporate headquarters level, displacing regional plant-level sourcing autonomy. This centralization is compressing supplier rosters and extending contract durations. The shift is most visible in Guadalajara and Monterrey, where multinational beverage groups are mandating unified HFCS-55 specifications across their Mexican production network.
Corn Syrup Market Segmentation
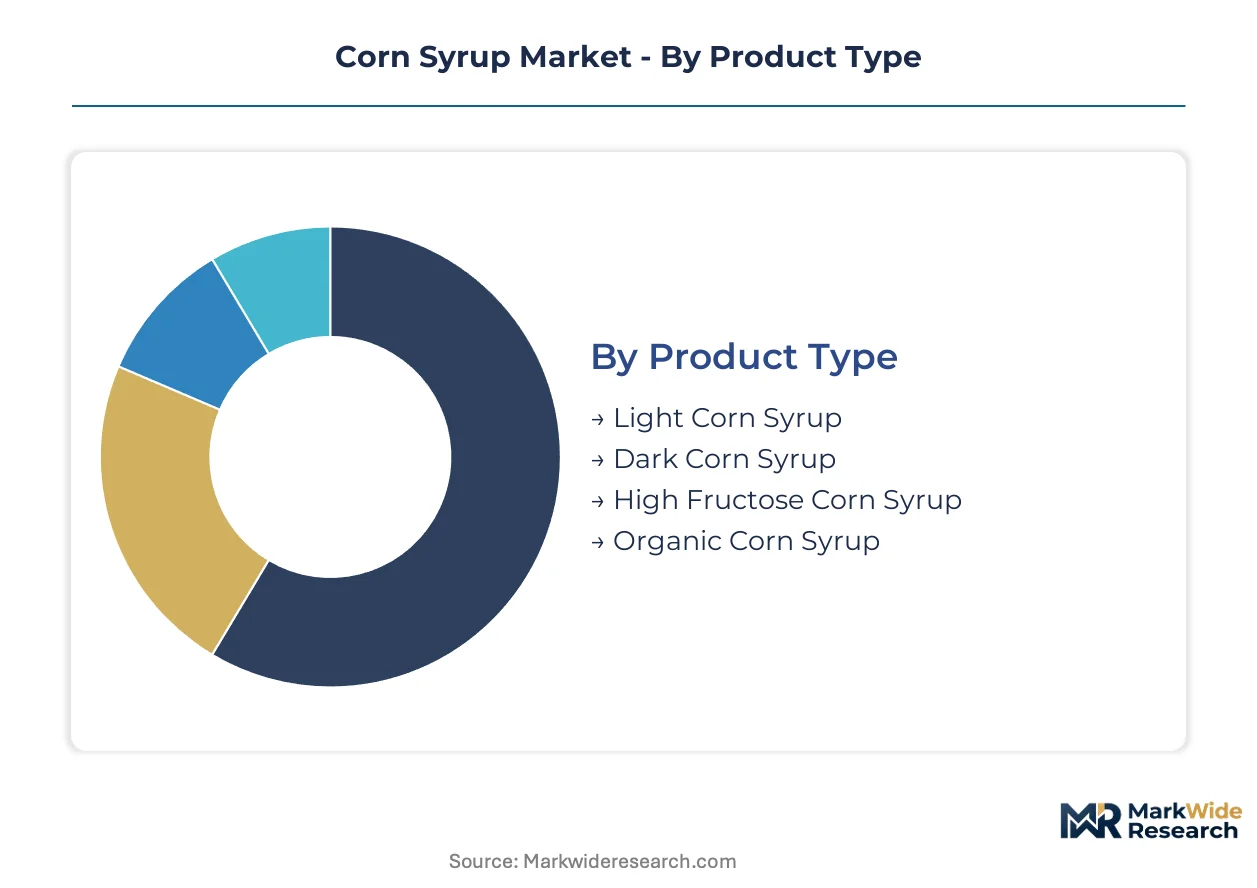
Corn syrup segmentation reveals divergent vulnerability to natural sweetener substitution. Product chemistry and end-use specifications determine which categories face immediate displacement versus sustained demand.
Product Type:
High fructose variants confront the most intense substitution pressure from stevia and monk fruit in beverage reformulation, while organic grades trade on certification premiums.
- High Fructose Corn Syrup:Enzymatic isomerization converts glucose to fructose, yielding sweetness parity with sucrose at lower cost. Mexican bottling clusters in Guadalajara and Monterrey anchor bulk offtake despite IEPS taxation compressing volumes.
- Organic Corn Syrup:Identity-preserved non-GMO corn feedstock undergoes enzymatic hydrolysis under certified organic protocols. North American and European retail channels pull capacity expansions toward segregated supply chains commanding price premiums.
- Light Corn Syrup:Lower dextrose equivalence ratings (20-40) deliver mild sweetness for candy applications without crystallization.
- Dark Corn Syrup:Caramel coloring and molasses notes target pecan pie and barbecue sauce formulations in US regional markets.
High fructose corn syrup retains volume leadership; organic corn syrup holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates commodity-scale food manufacturing from certified pharmaceutical specifications requiring dedicated fermentation-grade facilities.
- Food & Beverage:Carbonated soft drinks, fruit juices, and sports beverages consume the largest syrup volumes. Latin American bottlers recalibrate sweetness profiles around HFCS-55 specifications to maintain cost parity against cane sugar.
- Pharmaceuticals:USP-grade dextrose monohydrate for intravenous solutions demands dedicated production lines with third-party audit trails. Certified producers capture concentrated margin pools unavailable to commodity wet millers.
- Confectionery:Hard candies and caramels exploit corn syrup's hygroscopic properties to prevent sugar crystallization.
- Bakery:Pie fillings and glazes utilize viscosity control for moisture retention in extended shelf-life products.
Food and beverage commands absolute throughput; pharmaceuticals delivers the highest margin per unit volume.
Packaging Type:
Customer type divides procurement patterns between artisanal scale and industrial bulk, with craft brewers and small confectioners driving alternative formats.
- Bulk Containers:Tanker trucks and railcar deliveries serve high-volume beverage bottlers with direct-to-plant logistics. Mexican central plateau soft drink clusters drive tanker-scale offtake through contracted supply agreements.
- Drums:55-gallon steel drums accommodate mid-scale food manufacturers lacking bulk storage infrastructure.
- Bottles:Retail-size packaging targets home bakers and small commercial kitchens through supermarket channels.
- Pouches:Flexible packaging gains traction in foodservice portion-control applications.
Bulk containers dominate industrial procurement; pouches are gaining share fastest in foodservice segments.
Distribution Channel:
Supply concentration in wet milling corridors shapes channel efficiency, with wholesale bypass emerging for brewery clusters seeking maltose-rich variants.
- Wholesale:Ingredient distributors consolidate procurement for regional food manufacturers, offering technical support and formulation services alongside bulk syrup supply.
- Supermarkets:Retail packaging for home baking segments concentrates in US Midwest and Northeast grocery chains.
- Online Retail:Direct-to-consumer channels serve specialty bakers and small confectioners seeking organic or non-GMO certified variants.
- Convenience Stores:Limited retail syrup SKUs target impulse baking purchases in urban markets.
Wholesale retains channel dominance; online retail is expanding most quickly for certified organic grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's added sugars labeling mandate anchors North American regulatory influence, while Latin American bottling clusters and European clean-label mandates reshape regional procurement patterns across wet milling corridors.
United States
Carbonated beverage reformulation and pharmaceutical-grade dextrose specifications drive demand bifurcation. The EPA enforces Clean Water Act effluent permits for Illinois River corridor wet milling facilities. Decatur, Illinois hosts concentrated wet milling capacity where Archer Daniels Midland and Cargill operate integrated grain origination-to-syrup production networks.
Mexico
Soft drink bottling clusters in Guadalajara and Monterrey sustain bulk HFCS-55 offtake despite sweetness profile recalibration pressures. Mexico's IEPS levy on sugar-sweetened beverages directly compresses syrup volumes in the central plateau region. Multinational beverage groups are consolidating procurement decisions at corporate headquarters, displacing regional plant-level sourcing autonomy.
Brazil
Beverage manufacturers recalibrate formulations around cost parity between corn-derived sweeteners and domestic cane sugar. ANVISA governs food additive specifications for industrial sweeteners entering packaged food channels. São Paulo state's beverage production belt anchors South American syrup demand, with bottlers negotiating long-term supply contracts.
Germany
REACH registration requirements for processing aids compel wet millers to substitute conventional enzyme stabilizers with bio-based alternatives. The EU Green Deal and F-Gas Regulation indirectly constrain energy-intensive starch processing, nudging producers toward efficiency retrofits. Hamburg and Lower Saxony harbor concentrated food ingredient manufacturing where clean-label certification premiums command European export positioning.
Argentina
Identity-preserved organic corn production in the Pampas grain belt offers expansion terrain for certified syrup serving export markets. The country's national agricultural regulator oversees organic certification protocols for segregated supply chains. Buenos Aires province hosts emerging organic wet milling investments targeting North American and European retail channel premiums.
Corn Syrup Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier competitive structure in corn syrup manufacturing. The upper tier commands grain origination networks and river-access wet milling infrastructure, while specialists concentrate on non-GMO certification and pharmaceutical-grade specifications. Three archetypes dominate: integrated agribusiness conglomerates with captive corn supply, regional wet millers serving beverage bottling clusters, and certified organic processors capturing clean-label premiums. Capacity expansion along enzymatic isomerization retrofits and backward integration into identity-preserved corn supply chains represent the dominant competitive moves.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through Midwest grain origination networks and Illinois River corridor wet milling footprints. Ingredion Incorporated occupies a specialist position, representing the certified variant archetype with non-GMO and clean-label syrup production. These three entities anchor the competitive spectrum from commodity-scale HFCS operations to premium-grade organic certification.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Corn Products International |
| Archer Daniels Midland Company |
| Grain Processing Corporation |
| Tereos SCA |
| Cargill, Incorporated |
| Roquette Frères S.A. |
| MGP Ingredients |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Cane sugar substitution in Mexican bottling corridors simultaneously redraws procurement geography and compresses margin structures across HFCS-55 contracts. The shift forces wet millers to absorb feedstock volatility while defending long-term offtake agreements against regional sweetener arbitrage.
Pricing Analysis
Price spreads between Illinois River corridor supply and Guadalajara delivery points reflect rail-tariff differentials and IEPS tax incidence. Three-tier pricing structure across pharmaceutical-grade, certified organic, and commodity HFCS tiers segments buyer sensitivity, with beverage bottlers exhibiting highest price elasticity. Cost compression in standard dextrose runs through biofuel-driven corn feedstock competition. Pharmaceutical specifications command lowest sensitivity due to USP certification barriers and IV-solution liability exposure.
Supply Chain Analysis
Inbound container congestion at Veracruz and Manzanillo ports elevates enzyme stabilizer costs for Mexican wet milling operations. Supply concentrates in the United States, Brazil, and Argentina, with the Pampas grain belt emerging as organic certification terrain. Starch processing draws from corn origination networks, glucoamylase enzyme supply, and natural gas for evaporative systems. Single-source vulnerability sits with Illinois River corridor concentration for North American HFCS output. Distribution runs through tanker-scale direct-to-plant logistics for beverage bottlers and ingredient distributor networks for mid-scale food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corn syrup market functions as a defensive-moat structure where regulatory entrenchment around FDA labeling requirements and EPA discharge permits creates substantial compliance barriers for prospective entrants.
For Market Incumbents: Shield market position through backward integration into identity-preserved corn supply chains and accelerated enzymatic isomerization retrofits. Natural sweetener substitution in premium beverage lines threatens HFCS-55 volume retention, while Clean Water Act compliance timelines demand multi-year capital deployment into biological oxygen demand reduction infrastructure. For New Entrants and Emerging Players: Lead with organic certification as the primary wedge, targeting Argentina's Pampas belt for identity-preserved supply chain development. The underpenetrated European clean-label channel offers the most penetrable white space, with direct-to-brewery distribution bypassing conventional ingredient distributors as the viable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified-specialist acquisition targets over commodity-scale assets. Long-term viability centers on pharmaceutical-grade specification capabilities and non-GMO certification infrastructure. The signal to watch is IEPS tax expansion across additional Latin American jurisdictions as an inflection indicator for regional HFCS demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Isomerization Retrofit | Illinois River corridor facilities capture efficiency gains from immobilized glucose isomerase column technology. |
| Identity-Preserved Supply Chain Integration | Segregated organic corn sourcing commands premium positioning in European export channels. |
| Pharmaceutical-Grade Facility Certification | USP-grade dextrose monohydrate production opens concentrated margin pools for IV solution suppliers. |
| Direct-to-Brewery Distribution Bypass | Craft brewing clusters in Colorado and Oregon source maltose-rich variants outside conventional channels. |
| Just Transition Mechanism Fund Access | European producers retrofit evaporative systems to reduce natural gas intensity under EU Green Deal incentives. |
Methodological Framework
Desk research of FDA labeling guidance documents, EPA effluent discharge permits, and EMA pharmaceutical-grade specifications preceded structured interviews with wet milling plant managers, beverage procurement executives, and organic certification auditors. Secondary validation drew from customs trade data, SEC 10-K filings of integrated agribusiness conglomerates, and ANVISA food additive registrations. Bottom-up capacity assessments triangulated against top-down demand modeling across beverage, pharmaceutical, and confectionery end uses.
Variance decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions encompass product chemistry tier, end-use industry specification, packaging format scale, and regional regulatory cluster. CAGRs derive from historical capacity utilization trends, forward contract coverage ratios, and substitution elasticity estimates for natural sweetener penetration. Forecast inputs include corn feedstock basis differentials and enzyme processing cost curves.
The analysis sits within stated boundaries; outcomes outside sustained biofuel policy support or expanded sugar-sweetened beverage taxation would require recalibration. Forecasts reflect documented assumptions regarding IEPS levy stability and REACH registration timelines for processing aids. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Low-Fat Sugar Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Liquid Sugar Market
Sweeteners
Sugar Syrups Market
Sweeteners
Rice Syrup Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Dry Molasses Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
South America Stevia Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Europe Stevia Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Maltitol Market
Sweeteners
Maltol and Ethyl Maltol Market