
 Brazil Alcohol E-Commerce Market | 2026-2036
Brazil Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Alcohol E-Commerce Market Insights
Brazil's Southeast logistics corridor is tilting toward automated fulfillment centers to support same-day alcohol delivery density. MercadoLibre leverages its established Mercado Envíos infrastructure to control last-mile costs across state capitals. Anheuser-Busch InBev anchors its position through direct-to-consumer storefronts integrated with existing brewery distribution nodes. Rappi competes by embedding alcohol SKUs within its broader quick-commerce super-app ecosystem.
Brazil alcohol e-commerce denotes the digital sale and home delivery of fermented and distilled beverages through web and mobile platforms, requiring age-verification protocols and temperature-controlled logistics for product integrity. Beer dominates transaction volume due to replenishment frequency and lower per-unit shipping friction, while spirits command higher margins concentrated in premium price tiers. Third-party platforms capture the bulk of consumer traffic, though subscription services represent the fastest-growing structural channel as recurring revenue models reduce customer acquisition costs. Direct-to-consumer channels remain nascent but attract producer investment where regulatory permits allow bypassing traditional wholesale tiers.
ANVISA governs beverage labeling and advertising restrictions, while Brazil's Consumer Protection Code (CDC) mandates transparent pricing and delivery timelines for online alcohol transactions. State-level tax regimes, particularly ICMS variations across Minas Gerais, São Paulo, and Rio de Janeiro, fragment compliance costs and shape regional platform profitability. Stakeholders must monitor pending federal legislation on cross-state e-commerce taxation that would redraw competitive boundaries between national aggregators and localized operators.
Market Dynamics
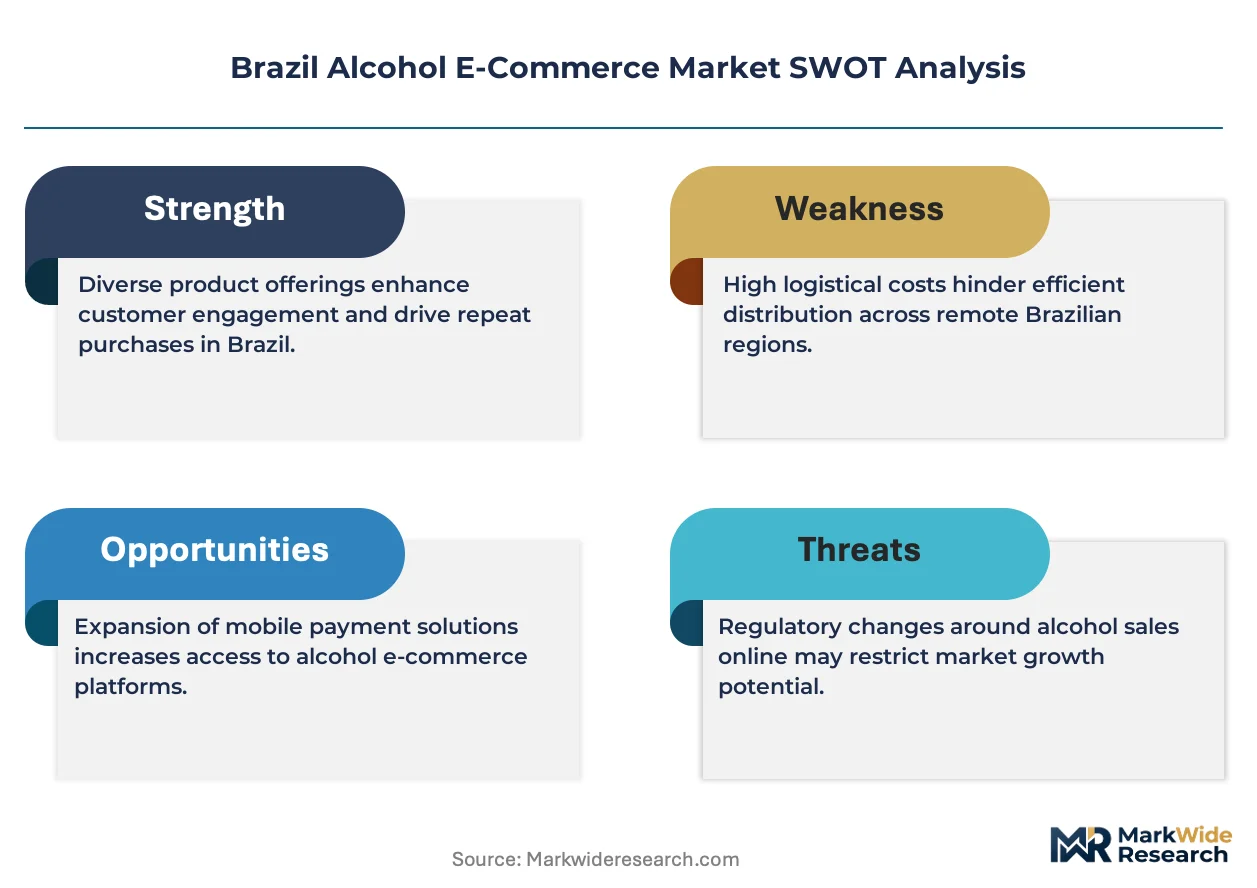
ANVISA's evolving digital compliance protocols for beverage sales are compressing platform operational timelines while forcing investments in age-verification infrastructure across Brazil's Southeast logistics corridor.
Growth Catalysts
- Mobile-first purchasing habits:Urban millennials in São Paulo and Rio de Janeiro drive transaction density through smartphone-native interfaces, reducing friction in repeat purchase cycles.
- ICMS tax variations:State-level fiscal disparities across Minas Gerais, São Paulo, and Rio de Janeiro create arbitrage opportunities for platforms optimizing fulfillment center placement.
- Subscription services:Recurring revenue models reduce customer acquisition costs for operators capturing replenishment-frequency demand in beer and ready-to-drink categories.
Market Restraints
- Temperature-controlled logistics costs:Cold-chain requirements for product integrity inflate per-unit fulfillment expenses, compressing margins on lower-priced SKUs.
- Metropolitan delivery network concentration:Same-day density depends on automated fulfillment centers anchored in São Paulo and Rio de Janeiro, leaving secondary cities underserved.
- Consumer Protection Code mandates:Brazil's CDC imposes transparent pricing and delivery timeline disclosures that constrain promotional flexibility during competitive pressure periods.
Strategic Opportunities
- Northeast and Central-West penetration:Underdeveloped digital alcohol commerce in Recife, Fortaleza, and Brasília offers first-mover expansion potential before infrastructure saturation.
- Direct-to-consumer regulatory permits:Producers leveraging ANVISA-compliant bypass channels can capture wholesale-tier margins currently absorbed by third-party aggregators.
- Quick-commerce super-app embedding:Alcohol SKU integration within broader grocery and convenience ecosystems captures impulse purchase behavior outside dedicated beverage platforms.
Industry Challenges
- Age-verification technology integration:Real-time identity authentication at point-of-delivery requires coordination between platform APIs, driver applications, and ANVISA audit trails.
- Cross-state e-commerce taxation uncertainty:Pending federal legislation on interstate digital sales tax harmonization threatens to redraw competitive boundaries between national operators and localized specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Alcohol E-Commerce Market |
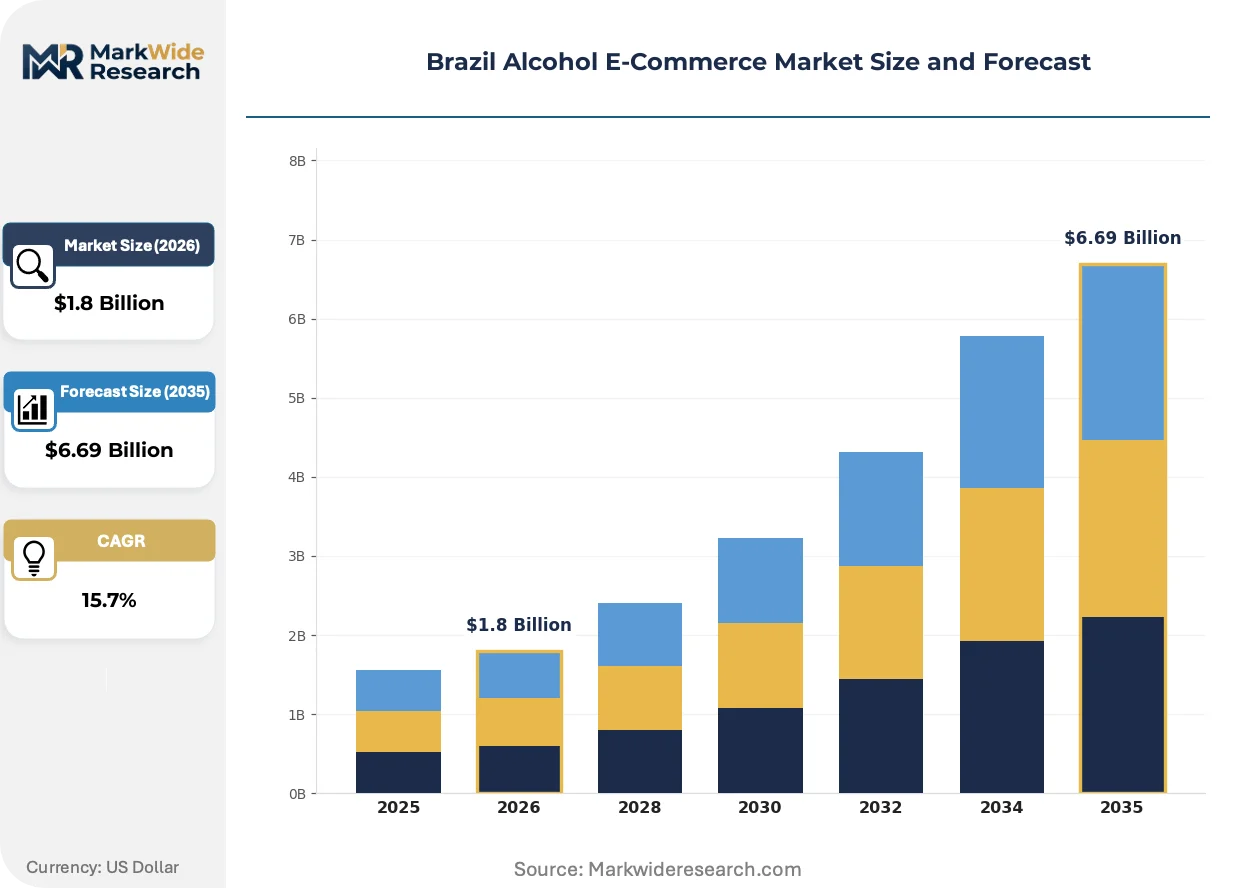
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.69 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Liqueurs Distribution Channel: Online Retailers, Direct-to-Consumer, Third-Party Platforms, Subscription Services Customer Type: Individuals, Corporations, Restaurants, Event Planners Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | MercadoLibre, Amazon, Rappi, iFood, James Delivery, Diageo, Anheuser-Busch InBev, Heineken, Magazine Luiza, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Alcohol E-Commerce Market Trends and Innovations
Digital infrastructure investments are compressing fulfillment timelines while regulatory digitization and shifting consumption patterns restructure competitive positioning across Brazil's alcohol e-commerce landscape.
Blockchain-enabled provenance tracking is digitizing supply chain transparency for premium spirits categories. High-margin producers in Rio de Janeiro and São Paulo are adopting distributed ledger verification to authenticate vintage claims and distillery origin. This technology is digitizing trust mechanisms that previously required physical inspection, compressing the due diligence window for cross-state transactions.
ANVISA's forthcoming digital labeling requirements will mandate QR-code nutritional and allergen disclosure for all fermented and distilled beverages sold online. This regulatory shift forces platform operators to restructure product detail pages and backend data pipelines before enforcement deadlines. Premium spirits sellers face the steepest compliance costs given SKU complexity and import documentation requirements.
Replenishment automation through smart-home device integration is altering purchase initiation patterns. Urban consumers in São Paulo's dense metropolitan corridors are shifting from active search-and-buy cycles toward algorithmic reorder triggers based on consumption velocity. This behavioral pivot concentrates volume with platforms offering API connectivity to IoT-enabled refrigerator inventory systems, displacing traditional browse-based discovery channels.
Brazil Alcohol E-Commerce Market Segmentation
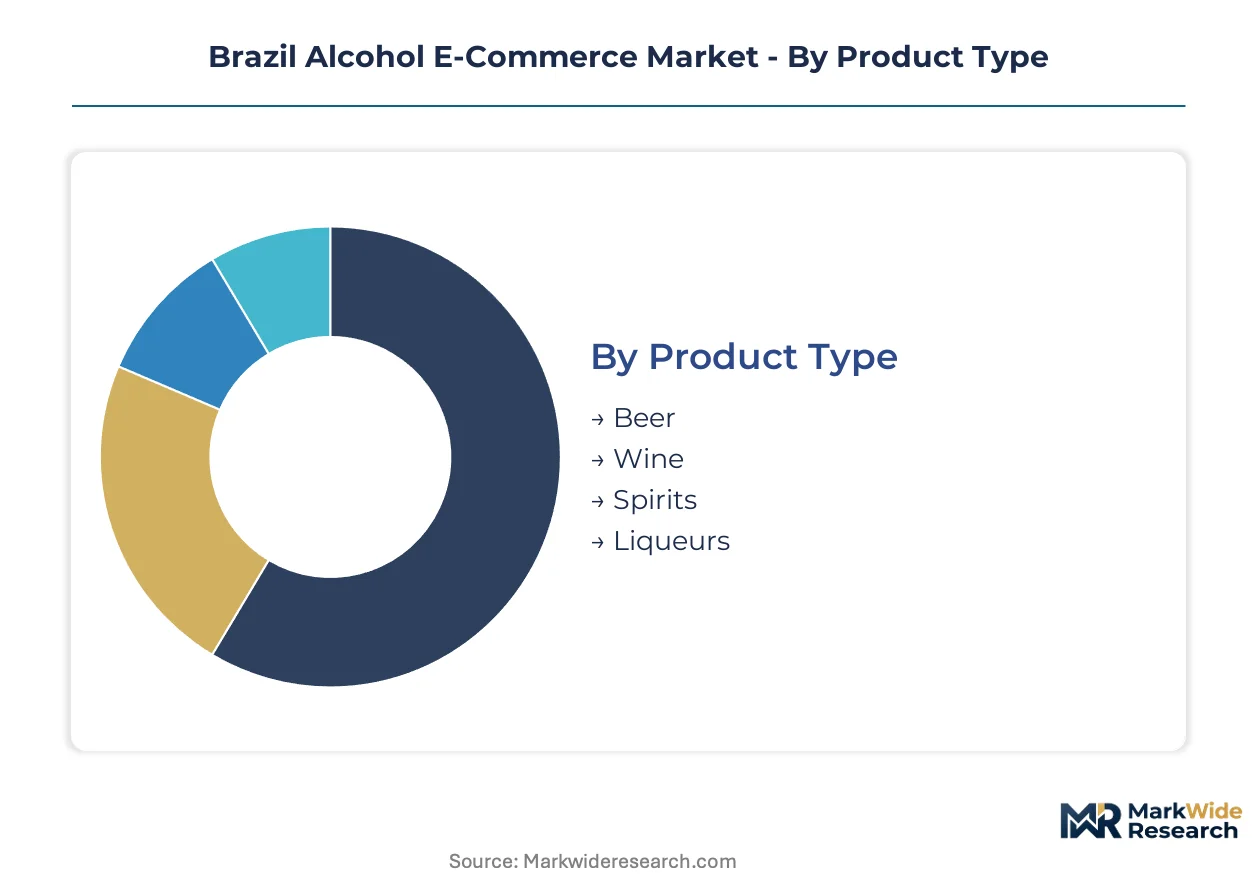
Segmentation in Brazil's alcohol e-commerce market reveals how regulatory constraints, logistics infrastructure, and purchasing behavior fragment commercial opportunity. Distinct product categories and channel models face divergent margin pressures and compliance burdens across Brazil's state-level regulatory patchwork.
Product Type:
Mature categories dominate transaction volume while emerging segments command premium positioning and specialized fulfillment protocols.
- Beer:Fermented malt beverages with lower alcohol content and standardized packaging formats suit high-frequency replenishment cycles. São Paulo's metropolitan delivery networks concentrate demand for same-day beer fulfillment, driven by temperature-controlled logistics requirements that preserve product integrity during transit.
- Spirits:Distilled beverages including whiskey, vodka, and cachaça carry higher per-unit margins and complex ANVISA labeling obligations. Rio de Janeiro's premium consumer base concentrates demand for aged and imported spirits, constrained by import documentation delays and state-level ICMS tax variations.
- Wine:Grape-derived fermented beverages requiring cellar-temperature storage and vintage-specific provenance tracking.
- Liqueurs:Sweetened spirit-based products with lower volume velocity and specialized occasion-based purchasing patterns.
Beer handles the majority of throughput; spirits is the fastest mover on share.
Distribution Channel:
Channel economics vary sharply by customer acquisition cost structure and regulatory compliance burden.
- Third-Party Platforms:Aggregator marketplaces capturing consumer traffic through consolidated inventory exposure and established trust mechanisms. São Paulo and Rio de Janeiro anchor platform density, with ANVISA audit trail requirements forcing API investments in age-verification infrastructure.
- Subscription Services:Recurring revenue models algorithmically triggering replenishment based on consumption velocity. Urban millennial households in Brazil's Southeast concentrate adoption, expanding most quickly as customer lifetime value economics improve.
- Online Retailers:Dedicated digital storefronts operating within traditional wholesale-tier distribution frameworks.
- Direct-to-Consumer:Producer-controlled channels bypassing intermediaries where ANVISA permits allow.
Third-party platforms handle the majority of throughput; subscription services is the fastest mover on share.
Customer Type:
Purchasing patterns diverge between volume-driven institutional buyers and frequency-driven individual consumers.
- Individuals:End consumers purchasing for personal consumption through mobile-native interfaces. São Paulo's dense metropolitan corridors concentrate individual transaction density, driven by smartphone-first purchasing habits and same-day delivery expectations.
- Restaurants:Foodservice operators sourcing beverage inventory through digital procurement channels. Rio de Janeiro's hospitality sector concentrates demand, constrained by ANVISA's digital compliance protocols for commercial resale documentation.
- Corporations:Business entities procuring for employee events or client entertainment.
- Event Planners:Occasion-specific bulk purchasers with concentrated seasonal demand spikes.
Individuals handle the majority of throughput; restaurants is the fastest mover on share.
Price Tier:
Margin structures stratify across cost tiers with divergent logistics and marketing intensity requirements.
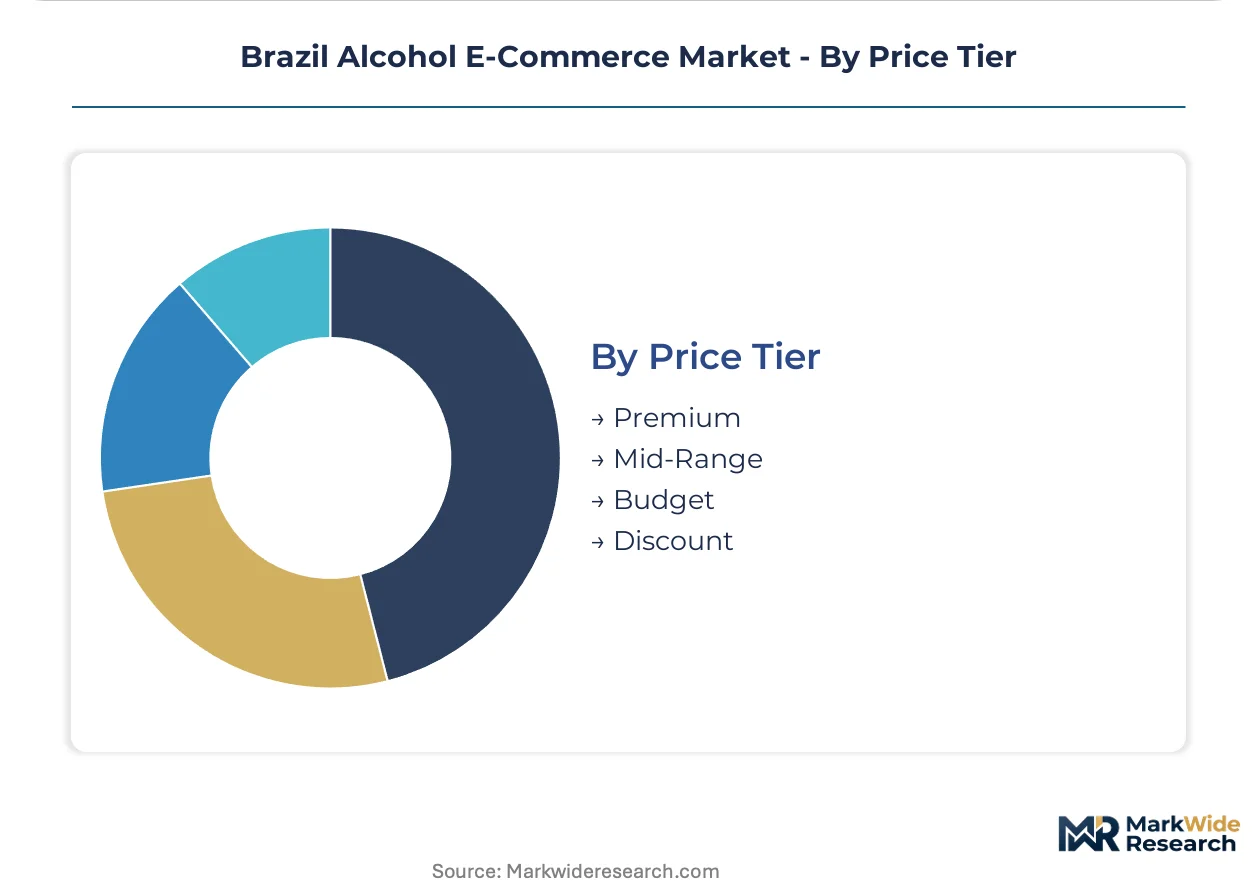
- Premium:Upper-price-segment products commanding brand equity and provenance authentication investments. São Paulo's affluent consumer base concentrates premium demand, driven by blockchain-enabled supply chain transparency for vintage spirits claims.
- Budget:Entry-price-segment products optimized for replenishment frequency and minimal shipping friction. Brazil's Southeast logistics corridor concentrates budget-tier volume, constrained by cold-chain cost compression on lower-margin SKUs.
- Mid-Range:Middle-positioned products balancing brand recognition with accessibility.
- Discount:Promotional-price products with minimal brand investment and highest price elasticity.
Budget handles the majority of throughput; premium is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Brazil concentrates alcohol e-commerce transaction density through São Paulo and Rio de Janeiro's metropolitan corridors, while Northeast and Central-West states exhibit divergent consumption patterns favoring wholesale-tier procurement over digital replenishment cycles.
São Paulo
Urban millennials drive mobile-first beer replenishment through same-day delivery networks anchored in Greater São Paulo's automated fulfillment centers. ANVISA's digital compliance protocols force platform investments in age-verification APIs and audit trail infrastructure. The ABC Paulista industrial corridor hosts temperature-controlled logistics nodes serving Brazil's densest alcohol consumption cluster.
Rio de Janeiro
Premium spirits demand concentrates in Rio de Janeiro's affluent coastal zones, with blockchain-enabled provenance tracking penetrating aged cachaça and imported whiskey categories. State-level ICMS tax variations create fulfillment arbitrage opportunities against São Paulo-based competitors. The Port of Rio de Janeiro anchors import documentation workflows for luxury beverage SKUs.
Minas Gerais
Belo Horizonte's emerging middle-class households exhibit accelerating subscription service adoption for mid-range wine and craft beer categories. ANVISA's forthcoming QR-code labeling mandates compress compliance timelines for platforms serving the state's dispersed interior municipalities. The state's cachaça-producing regions drive direct-to-consumer permit applications bypassing traditional wholesale tiers.
Bahia
Salvador's hospitality sector concentrates restaurant-grade alcohol procurement through digital channels, though cold-chain infrastructure gaps constrain same-day delivery penetration. The state's Consumer Protection Code enforcement varies across municipal jurisdictions, fragmenting platform operational standardization. Feira de Santana's logistics corridor hosts emerging fulfillment investments targeting Northeast expansion.
Rio Grande do Sul
Porto Alegre's beer-centric consumption culture supports replenishment-frequency platform models, with winter seasonal spikes straining temperature-controlled capacity. State-level tax competition with Santa Catarina shapes cross-border fulfillment strategies. The Serra Gaúcha wine region experiments with direct-to-consumer regulatory permits for boutique vineyard channels.
Brazil Alcohol E-Commerce Market Competitive Landscape
Capability concentration sits with logistics-integrated platforms; scale advantage sits with beverage producers operating direct storefronts. The market structures around three tiers: super-app ecosystems embedding alcohol within broader quick-commerce, dedicated beverage platforms optimizing cold-chain density, and producer-controlled channels leveraging distribution node proximity. Strategic moves center on fulfillment automation investments and subscription service algorithm deployment to capture replenishment-frequency demand.
Within the super-app tier, MercadoLibre and Rappi represent divergent scale-capture strategies, with the former leveraging captive logistics infrastructure and the latter embedding alcohol SKUs within restaurant delivery density. Anheuser-Busch InBev occupies a position exemplifying producer-direct models, anchoring competitive pressure through brewery-adjacent fulfillment nodes that compress last-mile costs.
| Leading Market Players |
|---|
| MercadoLibre |
| Amazon |
| Rappi |
| iFood |
| James Delivery |
| Diageo |
| Anheuser-Busch InBev |
| Heineken |
| Magazine Luiza |
| Others |
Pricing and Supply Chain Analysis
ICMS tax variation exposure across Minas Gerais, São Paulo, and Rio de Janeiro determines both pricing tier spreads and supply chain shape, forcing platforms to optimize fulfillment center placement against state-level fiscal arbitrage while compressing margin structures on cross-border transactions.
Pricing Analysis
São Paulo commands premium delivery pricing against Belo Horizonte and Salvador due to same-day density and cold-chain infrastructure concentration. Three-tier pricing structure across premium, standard, and economy levels separates aged spirits from mass-market beer from discount private-label SKUs. Price differentiation hinges on temperature-controlled handling requirements and ANVISA compliance certification tiers. Cost compression in the budget tier is intensifying because automated fulfillment investments favor high-velocity SKUs. Restaurants exhibit highest price sensitivity due to thin foodservice margins; individual consumers in Rio de Janeiro's coastal zones show lowest sensitivity for provenance-authenticated spirits.
Supply Chain Analysis
Temperature-controlled logistics providers in Brazil's Southeast anchor fulfillment capacity, with Mercado Envíos and specialized beverage 3PLs controlling automated warehouse nodes. Geographic supply concentration centers on São Paulo, Rio de Janeiro, and Minas Gerais for cold-chain infrastructure; Portugal and Argentina for imported wine and spirits inputs. Raw material dependencies include malt and hops for beer production, glass bottle manufacturing, and refrigerant gases for transport fleets. Single-source vulnerability runs through São Paulo's ABC Paulista corridor where automated fulfillment density concentrates. Distribution runs through platform-controlled last-mile networks and producer-direct brewery nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's alcohol e-commerce market sits in early-cycle expansion, with subscription service penetration in urban millennial households providing structural tailwinds for recurring revenue capture ahead of infrastructure saturation.
For Market Incumbents: Insulate margin structures by deepening captive logistics control through automated fulfillment center expansion in São Paulo's ABC Paulista corridor, countering Rappi's super-app density threat. Anchor defensibility through backward integration into temperature-controlled fleet ownership, reducing per-unit delivery cost exposure on high-frequency beer replenishment cycles.
For New Entrants and Emerging Players: Establish a beachhead in Recife and Fortaleza's underserved Northeast corridor before national aggregators deploy automated fulfillment density. Target the restaurant procurement segment in Salvador and Brasília where digital penetration lags consumer channels. Lead with white-label subscription algorithms for craft beer and mid-range wine categories, bypassing platform fee structures through direct merchant relationships.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors logistics-integrated specialists over pure-play aggregators. Long-term viability hinges on cold-chain asset ownership and ANVISA compliance infrastructure rather than consumer app engagement alone. Acquisition target archetype: regional operators with state-level tax optimization capabilities and established driver networks. Monitor pending federal cross-state e-commerce taxation legislation as inflection signal for competitive boundary redraw.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fulfillment Center Deployment | MercadoLibre's captive infrastructure compresses same-day delivery costs in São Paulo density corridors. |
| Subscription Service Algorithm Launch | IoT-enabled refrigerator integration captures replenishment-frequency demand from urban millennial households. |
| Direct-to-Consumer Regulatory Permit Acquisition | Anheuser-Busch InBev's brewery-adjacent nodes bypass wholesale tiers where ANVISA allows. |
| Quick-Commerce Super-App Embedding | Rappi's restaurant delivery density enables impulse alcohol capture outside dedicated beverage platforms. |
| Blockchain Provenance Tracking Implementation | Premium spirits sellers in Rio de Janeiro authenticate vintage claims through distributed ledger verification. |
Research Methodology
Desk research of ANVISA regulatory filings, state-level ICMS tax codes, and platform operator disclosures preceded structured interviews with logistics operations directors, beverage category managers at MercadoLibre and Rappi, cold-chain 3PL executives, and ANVISA compliance officers. Primary fieldwork combined with secondary validation against customs records, SEC filings for listed beverage producers, and regional trade association data. Bottom-up transaction volume modeling triangulated against top-down market sizing from macro consumption indicators.
Assumptions held fixed include ANVISA's digital labeling enforcement timeline and current state-level tax fragmentation; variables tested included subscription service penetration velocity and cross-state e-commerce legislation passage. The analytical framework segmented across product type, distribution channel, customer type, and price tier dimensions over the projection horizon. CAGRs derived from logistic curve fitting against mobile commerce adoption patterns and metropolitan delivery density saturation curves. Forecast inputs incorporated temperature-controlled logistics cost trajectories and urban millennial household formation rates.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, consumer credit availability, and fuel price volatility would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and infrastructure investment continuity. Cross-checking against Nielsen retail audit data and platform-reported GMV disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
Cider and Perry Market