
 Russia Food Colorants Market | 2026-2036
Russia Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Food Colorants Market Analytics
The Eurasian Economic Union's technical regulation TR CU 029/2012 on food additives is pivoting Russian manufacturers toward natural and certified-clean label colorants. Chr. Hansen Holding A/S leverages its fermentation-derived pigment portfolio to anchor premium positioning in dairy applications. Sensient Technologies Corporation competes through advanced emulsion technologies that improve stability in beverage formulations. BASF SE dominates synthetic colorant supply with manufacturing scale that sustains cost advantages across mass-market confectionery channels.
Food colorants comprise pigments and dyes added to edible products to restore, enhance, or standardize visual appearance, typically formulated as carotenoid, anthocyanin, or azo-based compounds with specified light stability and pH tolerance thresholds. Their primary commercial purpose is to influence consumer purchase decisions through consistent color signaling of flavor, freshness, and quality across packaged goods. Natural colorants lead value contribution as bakery sector buyers prioritize plant-derived alternatives with documented stability under pasteurization. Synthetic colorants retain volume dominance in beverage industry applications where cost-sensitive producers demand batch-to-batch consistency at scale. Lake colors occupy a specialized margin pool in confectionery manufacturing, where fat-soluble formats enable coating uniformity without moisture migration.
Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces state registration requirements for new food additives, while Eurasian Economic Union harmonized standards govern maximum permitted concentrations and labeling disclosures. These frameworks compel reformulation investments and elevate barriers for uncertified imports. The Federal Agency on Technical Regulating and Metrology (Rosstandart) coordinates conformity assessment procedures that delay market entry for non-compliant suppliers. Stakeholders must monitor evolving EEU amendment drafts and build regulatory intelligence capabilities to preempt compliance-driven supply disruptions.
Market Dynamics
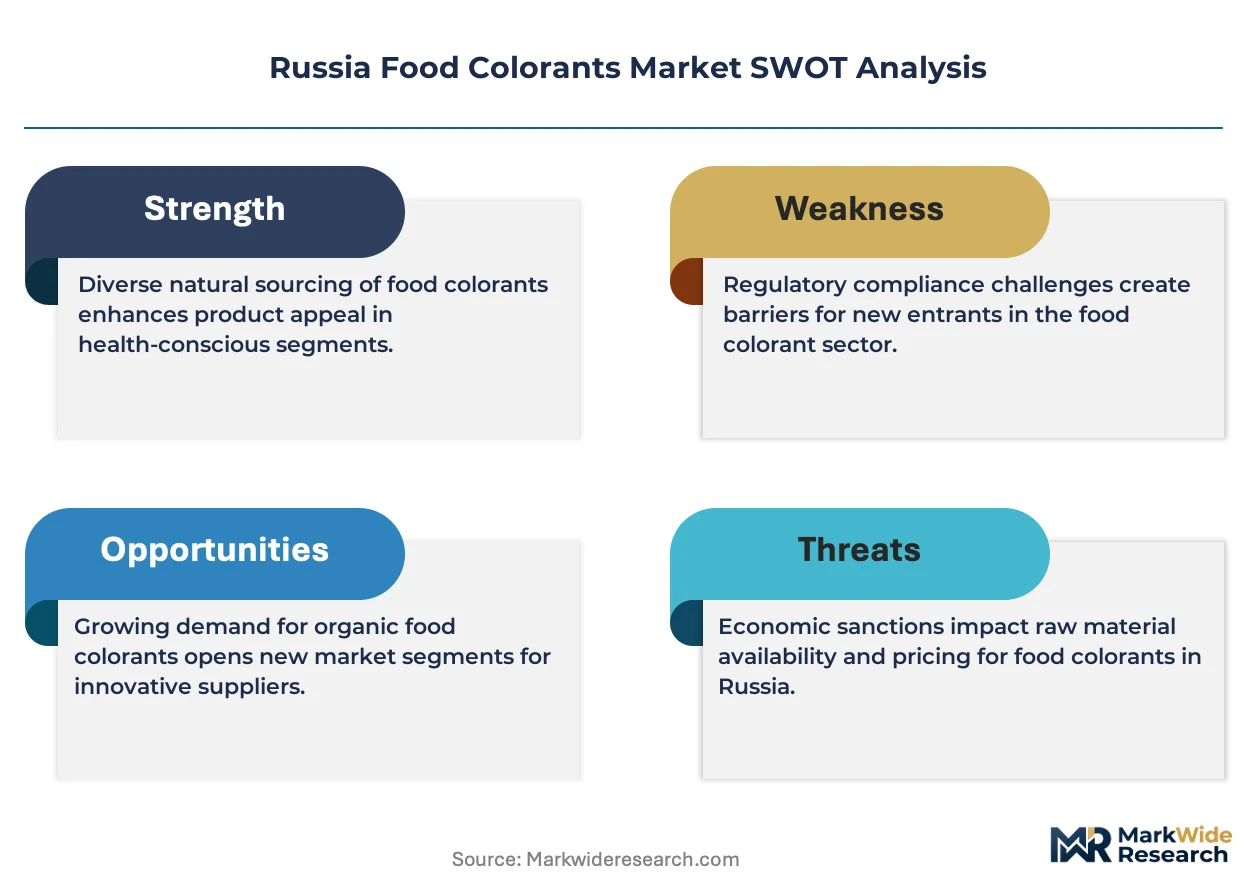
Clean-label reformulation mandates under TR CU 029/2012 are forcing Russian food manufacturers to rebuild colorant supply chains around certified-natural inputs, compressing synthetic pigment procurement volumes while elevating qualification barriers for new suppliers.
Growth Catalysts
- TR CU 029/2012 Amendment Trajectory:Eurasian Economic Union tightening of purity thresholds for synthetic additives is redirecting R&D budgets toward fermentation-derived and plant-extracted alternatives.
- Confectionery Sector Expansion:Moscow-based manufacturers are scaling output of premium chocolate and gummy categories that require stable natural colorants for export positioning.
- Pasteurization-Resistant Anthocyanins:Advances in encapsulation chemistry are unlocking bakery applications previously reserved for azo dyes.
Market Restraints
- Beetroot and Grape Skin Input Volatility:Agricultural yield fluctuations for key natural pigment feedstocks create margin compression for extractors without long-term grower contracts.
- Import Dependency for High-Purity Carotenoids:Domestic fermentation capacity gaps force reliance on Danish and Indian suppliers, exposing buyers to currency and logistics risk.
- Lake Color Solubility Ceiling:Fat-soluble formats face formulation constraints in reduced-fat confectionery segments where water-based systems dominate.
Strategic Opportunities
- Siberian and Far Eastern Federal Districts:Underdeveloped processed food infrastructure in these regions offers first-mover positioning for regional colorant blending facilities.
- Plant-Based Meat Analogues:Emerging mycoprotein and pea-protein manufacturers require heme-mimicking colorants that natural pigment suppliers can formulate.
- Organic Certification Premium Channel:Ecocert and RusOrganic standards create pricing power for certified-clean label suppliers in specialty retail.
Industry Challenges
- State Registration Timeline Compression:Rospotrebnadzor review cycles for novel additives extend 18-24 months, delaying product launches and freezing reformulation pipelines.
- Legacy Soviet-Era Equipment Retrofit Costs:Soviet-built dairy and beverage plants require capital-intensive line upgrades to handle natural colorant pH sensitivity and dosing precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Food Colorants Market |
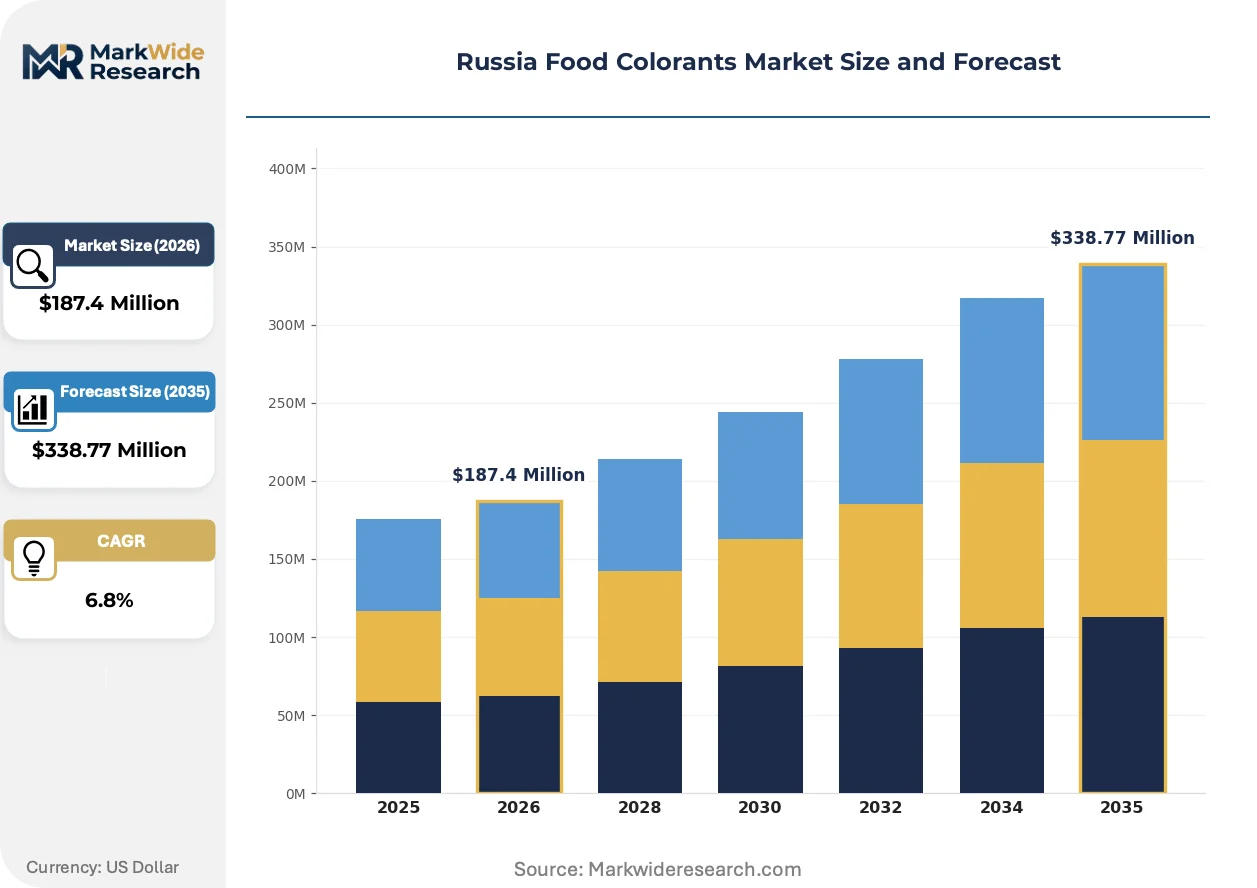
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Lake Colors, Water-soluble Colors End User: Beverage Industry, Bakery Sector, Dairy Products, Confectionery Manufacturers Application: Food Preservation, Aesthetic Appeal, Color Enhancement, Nutritional Benefits Form: Liquid, Powder, Gel, Granular |
| Companies Covered | Chr. Hansen Holding A/S, Sensient Technologies Corporation, Archer Daniels Midland Company, Givaudan, BASF SE, GNT Group B.V., Eco Resource, Riken Vitamin Co. Ltd, Biocol Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Food Colorants Market Evolving Landscape
Bioprocess engineering and regulatory harmonization are converging to displace legacy synthetic pigment systems, while procurement centralization among Russian retail chains is reshaping supplier relationship structures.
Microencapsulation technology for anthocyanin and betalain stability is modularizing how natural colorants integrate into heat-processed applications. Bakery manufacturers in the Central Federal District are adopting these systems at accelerating rates. The technology is modularizing supplier value propositions from commodity pigment sales toward integrated formulation services.
Rospotrebnadzor and Rosstandart are coordinating stricter conformity assessment procedures for imported colorant batches, extending documentation requirements and inspection frequencies. Industrial consequence includes inventory holding cost inflation for traders dependent on non-EAEU supply sources. Dairy processors are responding by qualifying domestic fermentation partners to preempt border delay risks.
Centralized procurement by X5 Retail Group and Magnit is compressing supplier negotiation cycles and unbundling technical service from pigment supply contracts. Regional distributors are losing volume share to direct manufacturer-retailer arrangements. This pattern is most visible in Moscow and St. Petersburg metropolitan procurement zones where buyer concentration is highest.
Russia Food Colorants Market Segmentation
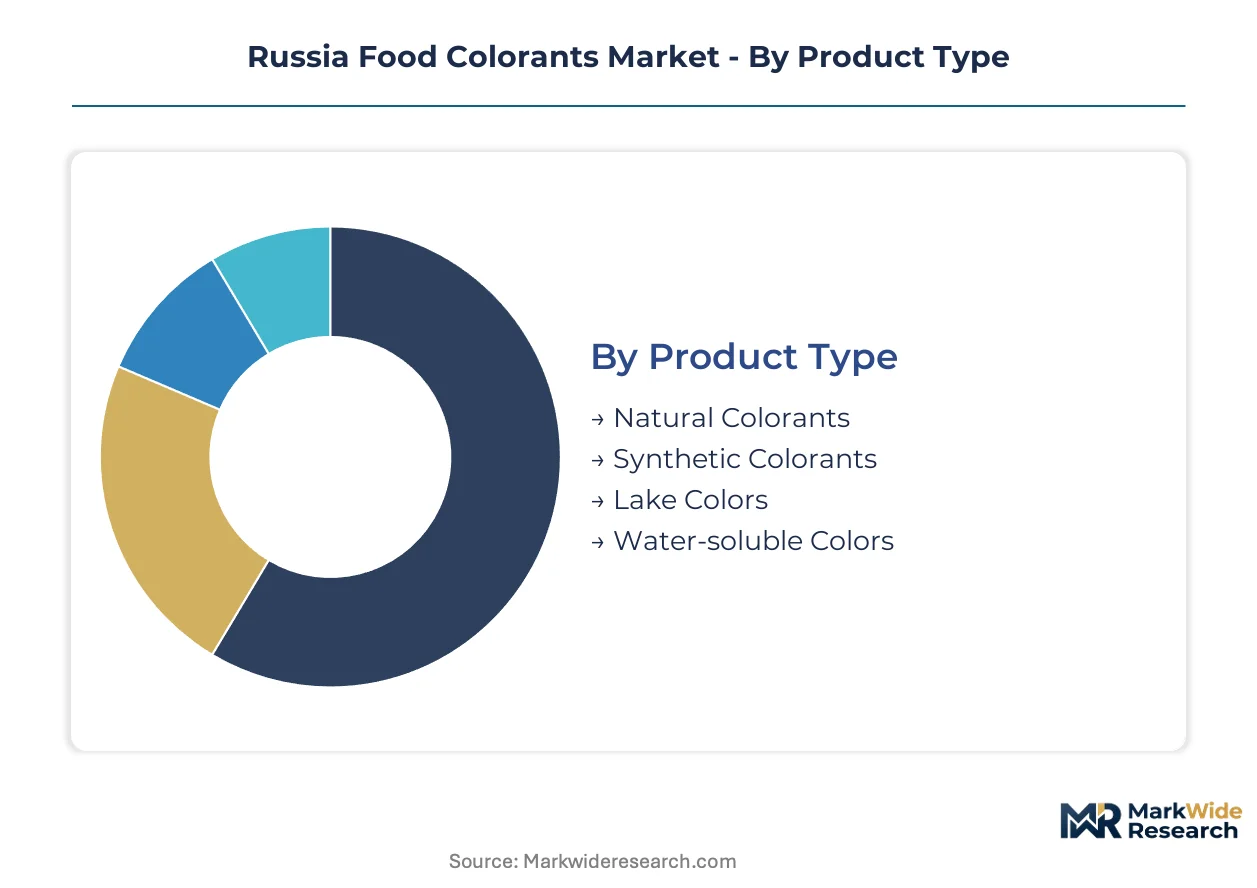
Colorant procurement patterns in Russia diverge sharply across product chemistry, processing requirements, and end-use stability demands. Manufacturers segment supply strategies to align with TR CU 029/2012 compliance tiers and the technical constraints of Soviet-era production infrastructure.
Product Type:
Buyers differentiate primarily by reformulation cost exposure and certification pathway complexity under Eurasian Economic Union standards.
- Natural Colorants:Fermentation-derived carotenoids and plant-extracted anthocyanins command premium positioning. Moscow dairy processors anchor procurement volumes here, prioritizing clean-label compliance for export-oriented yogurt and cheese lines.
- Synthetic Colorants:Azo-based dyes and certified artificial pigments retain cost advantages at scale. Beverage manufacturers in the Central Federal District sustain volume dominance despite tightening purity thresholds.
- Lake Colors:Fat-soluble complexes enable coating uniformity in high-fat confectionery applications.
- Water-soluble Colors:Liquid and powder formats serve reduced-fat formulations where moisture compatibility is paramount.
Volume sits with Synthetic Colorants; growth tilts toward Natural Colorants.
End User:
Application temperature profiles and pH tolerance requirements separate procurement specifications across Russian food manufacturing clusters.
- Beverage Industry:Carbonated and still drink producers demand batch-to-batch chromatic consistency under acidic conditions. Central Federal District bottlers drive specification standardization for caramel and tartrazine replacements.
- Confectionery Manufacturers:Chocolate and gummy producers require heat-stable pigments for tempering and depositing processes. Moscow-based exporters are expanding natural colorant qualification to meet EU retail buyer requirements.
- Bakery Sector:Pasteurization-resistant encapsulation systems are unlocking anthocyanin adoption for bread and pastry applications.
- Dairy Products:Fermentation-derived beta-carotene dominates yogurt and processed cheese coloring.
Beverage Industry procurement holds the largest share; Confectionery Manufacturers are climbing the fastest as export orientation intensifies.
Application:
Functional purpose determines regulatory scrutiny intensity and documentation burden for Russian manufacturers.
- Color Enhancement:Restoration of visual uniformity lost during processing. Mass-market confectionery and beverage producers concentrate procurement here, prioritizing cost efficiency over origin certification.
- Aesthetic Appeal:Novel color creation for premium positioning. Specialty retail channels in St. Petersburg and Moscow are driving demand for plant-derived alternatives with Ecocert documentation.
- Food Preservation:Antioxidant-active pigments like carotenoids provide secondary shelf-life extension.
- Nutritional Benefits:Provitamin A and polyphenol content supports health-positioned product claims.
Color Enhancement commands current volumes; Aesthetic Appeal shows the steepest expansion trajectory as premium retail formats multiply.
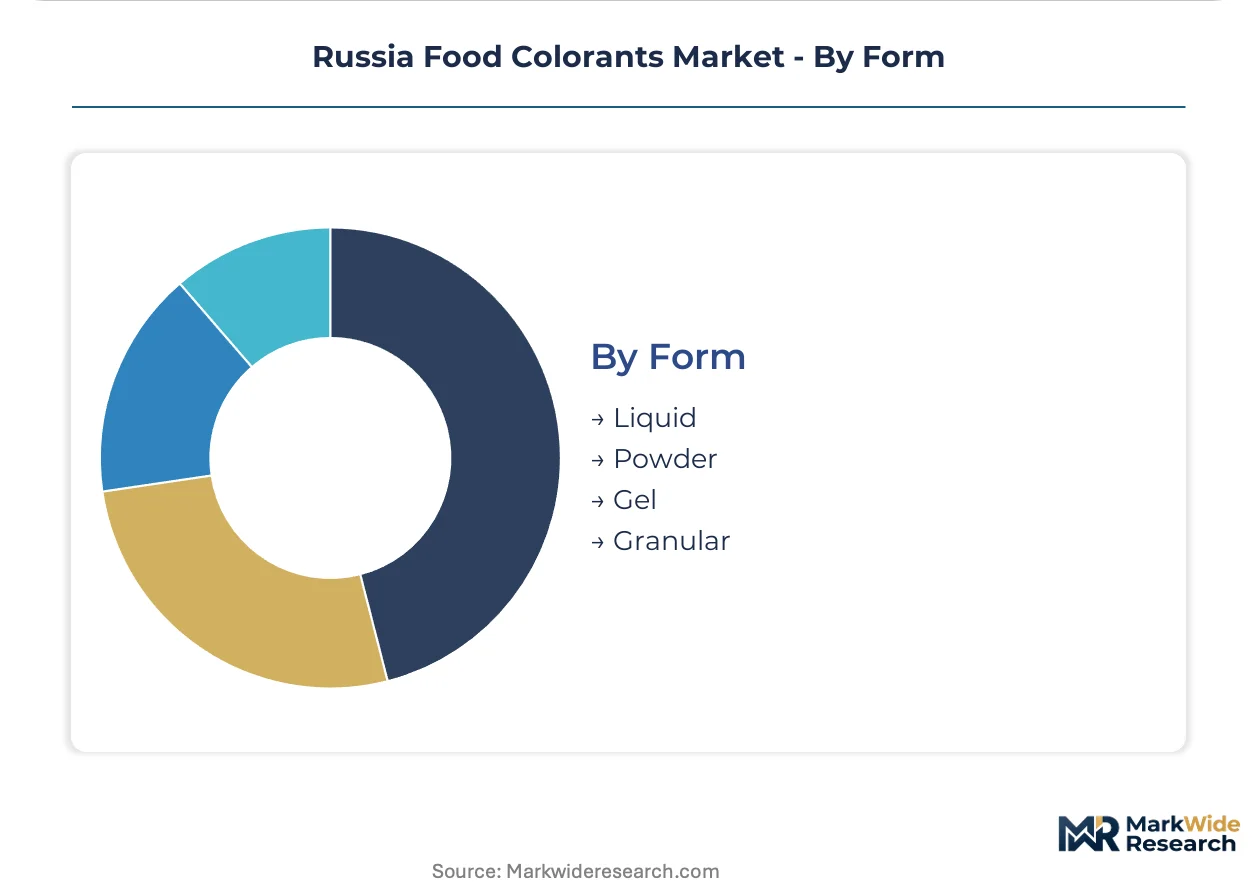
Form:
Dosing precision and line compatibility with legacy equipment shape format selection across Russian processing plants.
- Liquid:Pump-dispersed solutions integrate with existing Soviet-era dairy and beverage infrastructure. Central Federal District plants prefer this format for minimal retrofit requirements.
- Powder:Dry blends offer extended shelf stability and reduced transport costs. Siberian and Far Eastern manufacturers favor powders given logistics constraints and warehouse temperature variability.
- Gel:Viscous formats enable precise deposition in confectionery coating applications.
- Granular:Free-flowing particles suit high-speed blending in industrial bakery operations.
Liquid formats dominate installed base compatibility; Powder is gaining share fastest as regional production disperses beyond Moscow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow anchors Russian food colorant procurement, concentrating dairy and confectionery demand within the Central Federal District's processing corridor.
Central Federal District
Moscow-based yogurt and processed cheese manufacturers drive fermentation-derived carotenoid volumes. Rospotrebnadzor enforces state registration requirements that delay novel additive launches by 18-24 months. The Moscow-St. Petersburg industrial corridor hosts the country's densest cluster of clean-label reformulation activity.
Volga Federal District
Samara and Kazan beverage bottlers sustain synthetic colorant demand for carbonated drinks. TR CU 029/2012 purity thresholds are forcing gradual migration toward encapsulated natural alternatives. Regional distributors face margin compression as procurement centralizes toward Moscow.
Siberian Federal District
Novosibirsk bakery processors adopt pasteurization-resistant anthocyanin systems for bread applications. Logistics constraints favor powder formats over liquid due to warehouse temperature variability. Local blending facilities remain underdeveloped relative to demand growth.
Northwestern Federal District
St. Petersburg specialty retail channels drive Ecocert-certified natural colorant premiums. Eurasian Economic Union harmonized standards govern maximum permitted concentrations for export-oriented confectionery. The city's premium chocolate manufacturers are expanding natural pigment qualification.
Southern Federal District
Rostov-on-Don agricultural processors supply beetroot and grape skin feedstocks for domestic extraction. Agricultural yield volatility creates input cost uncertainty for natural pigment producers. Regional fermentation capacity gaps force reliance on imported high-purity carotenoids.
Russia Food Colorants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and formulation service integration. The market structures around three concentration nodes: multinational pigment specialists with Eurasian distribution networks, domestic blenders serving regional processors, and agricultural extractors controlling upstream feedstock access. Two competitive moves dominate: fermentation technology licensing to bypass import dependency, and direct procurement contracts with retail chains that disintermediate traditional distributors.
Among multinational specialists, Chr. Hansen Holding A/S and Sensient Technologies Corporation exemplify the premium-tier archetype through fermentation-derived portfolios and advanced emulsion capabilities. BASF SE occupies a position representing scale-driven synthetic supply. These three entities anchor the competitive framework within which domestic blenders and agricultural extractors must differentiate.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Givaudan |
| BASF SE |
| GNT Group B.V. |
| Eco Resource |
| Riken Vitamin Co. Ltd |
| Biocol Ltd |
| Others |
Value Network & Pricing Analysis
Beetroot and grape skin agricultural inputs flow through extraction facilities in the Southern Federal District before stratifying into certification-tiered pricing brackets downstream. TR CU 029/2012 compliance costs accumulate at each processing stage, compressing margins for uncertified traders while elevating premium capture for fermentation-derived alternatives.
Pricing Analysis
Value-based pricing anchored to pasteurization stability outcomes separates premium natural colorants from commodity synthetics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under Eurasian Economic Union standards and volume scale of procurement contracts. Cost compression in the standard tier is intensifying because agricultural yield volatility for anthocyanin feedstocks forces extractors to absorb input spikes. Beverage manufacturers in the Central Federal District exhibit highest price sensitivity due to thin margins on carbonated drinks, while export-oriented confectionery buyers prioritize stability performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Moscow and St. Petersburg operate hub-and-spoke patterns that consolidate pigment batches before final-mile delivery to Central Federal District processors. Upstream supply draws from Denmark and India for high-purity carotenoids, India for annatto extracts, and domestic Southern Federal District farms for beetroot feedstocks. Single-source vulnerability for fermentation-derived pigments exposes buyers to currency fluctuation and customs inspection delays under tightening Rospotrebnadzor protocols. Distribution runs through direct manufacturer-retailer arrangements that X5 Retail Group and Magnit are imposing, disintermediating traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology for anthocyanin stability is displacing legacy azo dye systems across Russian bakery and confectionery applications, compressing reformulation timelines for manufacturers dependent on Soviet-era infrastructure.
For Market Incumbents: Lock in fermentation technology licensing agreements with Danish and Indian partners to preempt import dependency risks from TR CU 029/2012 purity threshold tightening. Secure long-term grower contracts in the Southern Federal District for beetroot and grape skin feedstocks to buffer agricultural yield volatility. Prioritize backward integration into domestic extraction capacity to reduce exposure to currency-driven cost compression.
For New Entrants and Emerging Players: Encapsulation chemistry expertise offers entry positioning into pasteurization-resistant bakery applications previously closed to natural alternatives. Target Siberian and Far Eastern Federal Districts where regional blending facilities remain underdeveloped relative to demand growth from Novosibirsk processors. Lead with formulation-as-a-service go-to-market models that bundle technical support with pigment supply, mirroring Sensient Technologies Corporation's emulsion technology approach.
For Investors and Strategic Acquirers: Rospotrebnadzor state registration timeline compression for novel additives is the leading indicator that regulatory intelligence capabilities will differentiate acquisition targets. Long-term viability centers on suppliers with established Eurasian Economic Union certification pathways and domestic fermentation partnerships. Acquisition target archetype: mid-cap extractors with Ecocert or RusOrganic credentials and existing relationships with Moscow-based dairy processors. Watch for amendment drafts to TR CU 029/2012 as the inflection signal for accelerated synthetic-to-natural substitution mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Licensing | Reduces import dependency for carotenoids under tightening EEU purity standards. |
| Long-term Grower Contracts | Stabilizes beetroot and grape skin input costs against Southern Federal District yield volatility. |
| Microencapsulation R&D Investment | Unlocks bakery sector adoption previously reserved for heat-stable synthetic dyes. |
| Direct Retailer Procurement Agreements | Bypasses distributor margin compression from X5 Retail Group and Magnit centralization. |
| Ecocert/RusOrganic Certification | Captures premium pricing in St. Petersburg and Moscow specialty retail channels. |
Research Methodology
Multi-period observation of Rospotrebnadzor registration timelines, TR CU 029/2012 amendment trajectories, and Central Federal District procurement patterns anchored the trend analysis, supplemented by interviews with formulation chemists at dairy processors, procurement directors at confectionery exporters, technical R&D leads at colorant suppliers, and regulatory affairs specialists navigating Eurasian Economic Union harmonization. Secondary validation drew from Eurasian Economic Union technical regulation databases, Russian customs import records for pigment classifications, Rosstandart conformity assessment bulletins, and SEC filings of multinational suppliers. Bottom-up volume estimates from end-use segment consumption combined with top-down macroeconomic triangulation.
Segment-weighting across product type, end user, application, and form dimensions shaped the analytical framework, with natural versus synthetic chemistry split and pasteurization stability performance tier as cross-cutting variables. CAGRs were derived from regression analysis of historical procurement volumes against regulatory phase-in schedules and clean-label adoption curves across the analysis window. Industry-specific forecast inputs included encapsulation technology penetration rates in bakery applications and fermentation capacity buildout timelines for domestic carotenoid production.
Forecast precision tightens around the base case; tail outcomes carry wider variance under agricultural yield shocks, currency devaluation episodes, or accelerated TR CU 029/2012 amendment implementation. Outputs reflect documented assumptions regarding regulatory timeline adherence and technology adoption elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Lemon Extract Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Natural Food Colors Market