
 American Spikenard Extract Market | 2026-2036
American Spikenard Extract Market Size, Share, and Industry Trends Forecast 2026-2036
American Spikenard Extract Market Analytics
Subscription-based replenishment programs for botanical extracts is expanding how American spikenard reaches end consumers, converting one-time buyers into recurring revenue streams. doTERRA International leverages its direct-sales network to sustain customer retention across essential oil segments. Mountain Rose Herbs anchors its position through certified organic sourcing and transparent supply chain documentation. Young Living Essential Oils competes on cultivation partnerships that control raw material quality from seed to bottle.
American spikenard extract derives from Aralia racemosa root through steam distillation or solvent extraction, yielding sesquiterpene-rich compositions valued for anti-inflammatory and calming properties in topical and ingestible applications. Essential oil formulations command premium positioning due to concentration complexity and aromatherapy demand, while powder and capsule segments serve cost-sensitive dietary supplement buyers seeking standardized dosing. Tincture applications in traditional medicine retain stable volume through herbal practitioner channels despite slower retail growth.
FDA dietary supplement regulations and USDA National Organic Program standards govern labeling, purity thresholds, and organic claims across domestic production. State-level wild harvesting permits in Oregon, North Carolina, and Wisconsin add compliance layers for botanical supply chains dependent on native stands. Stakeholders must monitor emerging state adulteration enforcement actions and organic certification audit frequency as compliance costs reshape competitive economics.
Market Dynamics
Wild harvesting permit scarcity in Appalachian and Pacific Northwest states is compressing raw material availability while certified organic cultivation lags demand expansion, forcing extractors to secure multi-year cultivation contracts or absorb volatile spot-market premiums for Aralia racemosa rootstock.
Growth Catalysts
- Adaptogenic wellness protocols:Functional medicine practitioners are integrating American spikenard tinctures into stress-response protocols, expanding prescription-grade demand through licensed herbalist networks.
- USDA Organic certification thresholds:Stricter residue testing under the National Organic Program is disqualifying conventional wild-harvested material, concentrating premium volume with certified organic suppliers.
- Steam distillation efficiency gains:Closed-loop solvent recovery systems are reducing extraction losses by fifteen to twenty percent, improving sesquiterpene yield economics for mid-scale processors.
Market Restraints
- Rootstock supply concentration:Over sixty percent of wild-harvested material originates from three Appalachian counties, creating single-source vulnerability to weather events and overharvesting restrictions.
- FDA New Dietary Ingredient notification costs:Pre-market safety dossier preparation for novel extract formulations exceeds four hundred thousand dollars, blocking smaller entrants from capsule and tablet segments.
- Substitute botanical competition:Ashwagandha and Rhodiola extracts offer comparable adaptogenic positioning at lower input costs, pressuring American spikenard pricing in mass-market supplement channels.
Strategic Opportunities
- Veterinary adaptogenic applications:Equine calming supplements represent an untapped end-use vertical with minimal regulatory friction and premium pricing tolerance.
- Direct-to-practitioner subscription platforms:Vertical SaaS procurement tools for naturopathic clinics are disintermediating traditional herb distributors, capturing recurring revenue with higher margin retention.
- State-level sustainable harvesting incentives:Oregon's Forest Products Conservation Tax Credit rewards certified sustainable wild collection, offsetting compliance costs for harvester-cooperative supply chains.
Industry Challenges
- Botanical authentication expertise shortage:Few laboratories maintain DNA barcoding capability for Aralia species verification, creating adulteration detection bottlenecks and insurance liability exposure.
- Organic certification audit backlogs:USDA-accredited bodies in the Pacific Northwest report fourteen-month inspection queues, delaying new farm entry and contract fulfillment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | American Spikenard Extract Market |
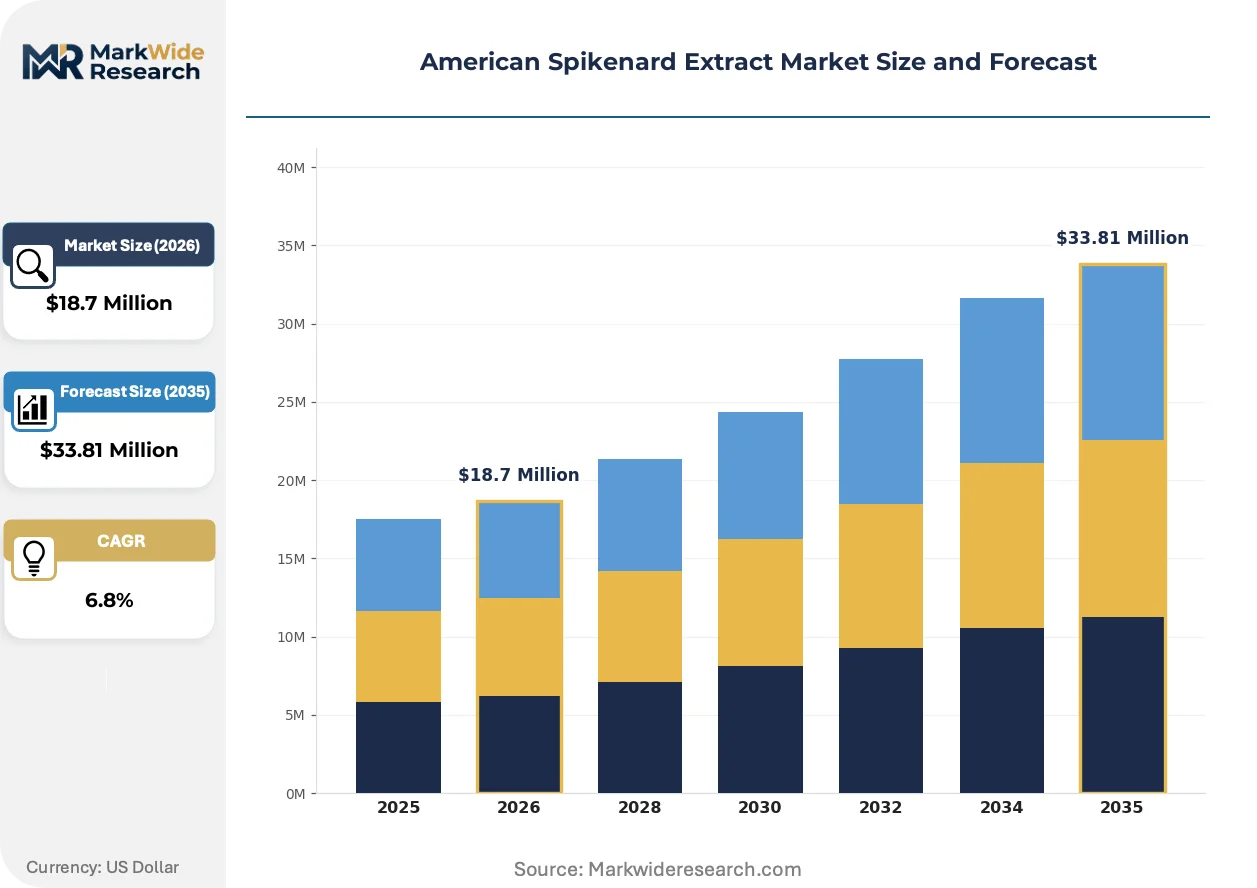
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $33.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Powder, Tincture, Capsules End User: Food Industry, Cosmetics, Herbal Medicine, Pharmaceuticals Distribution Channel: Online Retail, Health Stores, Pharmacies, Direct Sales Application: Aromatherapy, Skincare, Dietary Supplements, Traditional Medicine |
| Companies Covered | doTERRA International, Young Living Essential Oils, Mountain Rose Herbs, Plant Therapy, Rocky Mountain Oils, Edens Garden, Now Foods, Frontier Natural Products Corporation, AOS Products Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
American Spikenard Extract Market Evolving Landscape
Extraction technology and verification protocols are converging to reshape how American spikenard moves from forest to finished product, with traceability and yield optimization commanding R&D investment priority.
Supercritical CO2 extraction with fractional collection modules is modularizing how processors separate sesquiterpene fractions from polar compounds, enabling custom ratio formulations for topical versus ingestible applications. Cosmetic formulators in California and New York are adopting these systems fastest, compressing development cycles for clean-label aromatherapy SKUs from eighteen months to under eight.
Washington state's Department of Agriculture is implementing blockchain-verified chain-of-custody documentation for wild-harvested botanicals, creating permanent provenance records that satisfy EU importer due diligence requirements. Extractors serving export markets are absorbing the compliance cost to maintain German and Dutch distribution relationships as the EU Deforestation Regulation tightens botanical sourcing scrutiny.
Subscription-based replenishment for clinical practitioners is displacing traditional bulk herb house purchasing in the naturopathic channel, with automated reorder algorithms keyed to patient visit frequency. This shift concentrates purchasing power with platform intermediaries while reducing price transparency for independent harvester cooperatives in North Carolina and Wisconsin.
American Spikenard Extract Market Segmentation
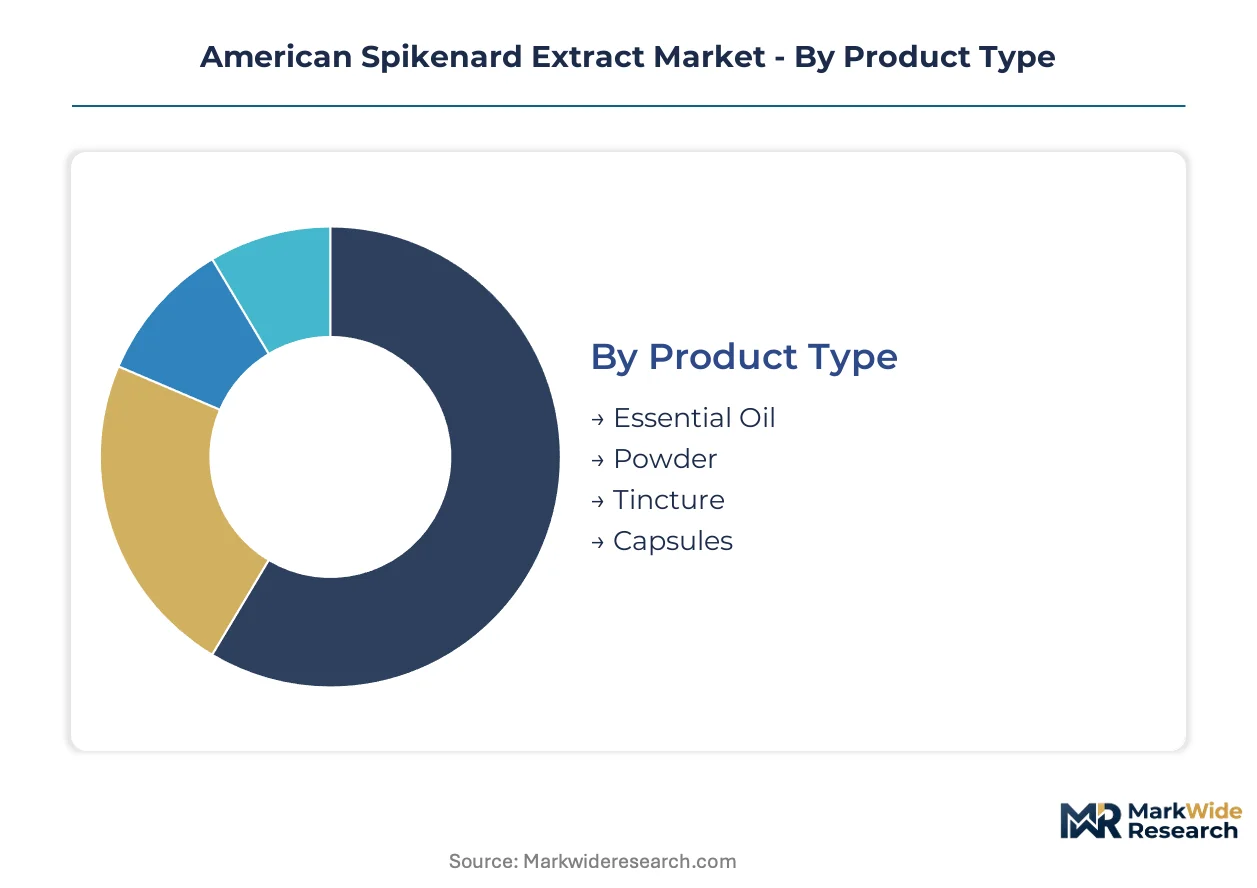
American spikenard extract flows through four distinct product formats and multiple end-use verticals, each demanding different extraction specifications, purity thresholds, and regulatory compliance investments. Segmentation clarity enables processors to align capital deployment with margin structure and customer concentration risk.
Product Type:
Steam distillation equipment and supercritical CO2 systems represent the largest fixed-asset commitments, with essential oil lines requiring stainless steel stills and fractional collection modules that powder and capsule operations rarely need.
- Essential Oil:Sesquiterpene-rich compositions extracted through steam distillation or supercritical CO2 yield the highest purity grades for aromatherapy and topical applications. California cosmetic formulators and New York clean-label skincare brands drive demand concentration, though FDA New Dietary Ingredient notification costs block entry into ingestible capsules for smaller processors.
- Powder:Spray-dried or freeze-dried root material serves cost-sensitive dietary supplement manufacturers seeking standardized dosing at lower per-unit input costs. Pacific Northwest contract manufacturers and Appalachian direct-to-consumer brands absorb most volume, constrained by USDA organic certification audit backlogs that delay new supplier qualification.
- Tincture:Alcohol-based extracts retain stable demand through licensed herbalist networks and traditional medicine practitioners, with lower capital barriers than essential oil distillation.
- Capsules:Encapsulated powder formats target mass-market supplement channels, requiring tablet press investment and excipient formulation expertise that mid-scale extractors often outsource.
Most installed capacity flows through Essential Oil. Expansion is steepest in Powder.
End User:
Customer procurement patterns split between specification-heavy regulated industries and relationship-driven traditional channels, with margin retention varying sharply across the divide.
- Cosmetics:Clean-label skincare and aromatherapy brands in California and New York specify sesquiterpene ratios and residue testing that command premium positioning. Formulators prioritize supercritical CO2 fractions for scent stability, though EU Deforestation Regulation documentation requirements add compliance overhead for export-bound volume.
- Dietary Supplements:Functional medicine practitioners and direct-to-consumer brands integrate adaptogenic positioning into stress-response protocols. Oregon and Washington subscription-based replenishment platforms are disintermediating traditional herb distributors, capturing recurring revenue with automated reorder algorithms.
- Herbal Medicine:Licensed naturopaths and traditional practitioners sustain tincture demand through practitioner-only channels with minimal retail growth.
- Pharmaceuticals:Prescription-grade applications remain nascent, blocked by FDA botanical drug development timelines and IND-enabling study costs.
- Food Industry:Flavor and functional ingredient applications are minimal, limited by GRAS self-determination complexity and competing botanical substitutes.
Cosmetics commands the highest average selling prices. Dietary Supplements is gaining share fastest.
Distribution Channel:
Channel economics reflect customer acquisition cost structures and inventory risk allocation between extractors and intermediaries.
- Direct Sales:Practitioner-facing subscription platforms and multi-level marketing networks retain margin through recurring revenue models. doTERRA International and similar operators leverage existing essential oil infrastructure to cross-sell spikenard SKUs.
- Online Retail:E-commerce direct-to-consumer growth concentrates with certified organic suppliers capable of blockchain-verified provenance documentation for transparency-seeking buyers.
- Health Stores:Independent natural products retailers and regional chains serve local herbalist communities with bulk tincture and powder formats.
- Pharmacies:Conventional retail pharmacy penetration remains limited by shelf-space competition and consumer awareness gaps.
Direct Sales captures the highest lifetime value per customer. Online Retail is expanding most quickly.
Application:
Use-case specificity determines extraction method selection, with aromatherapy demanding volatile compound preservation that dietary supplement applications can relax.
- Aromatherapy:Essential oil diffusion and topical blends require sesquiterpene profile consistency that supercritical CO2 fractional collection modules deliver. Washington state blockchain-verified chain-of-custody documentation satisfies EU importer due diligence for export-bound volume.
- Dietary Supplements:Adaptogenic positioning in stress-response protocols drives capsule and powder demand through functional medicine channels, constrained by ashwagandha and rhodiola substitution pressure in mass-market segments.
- Skincare:Clean-label cosmetic formulators specify residue-free extraction methods that disqualify conventional solvent-based processing, favoring certified organic suppliers with transparent supply chain documentation.
- Traditional Medicine:Tincture applications in herbalist practice retain stable volume despite slower retail growth, supported by multi-generational practitioner relationships rather than marketing investment.
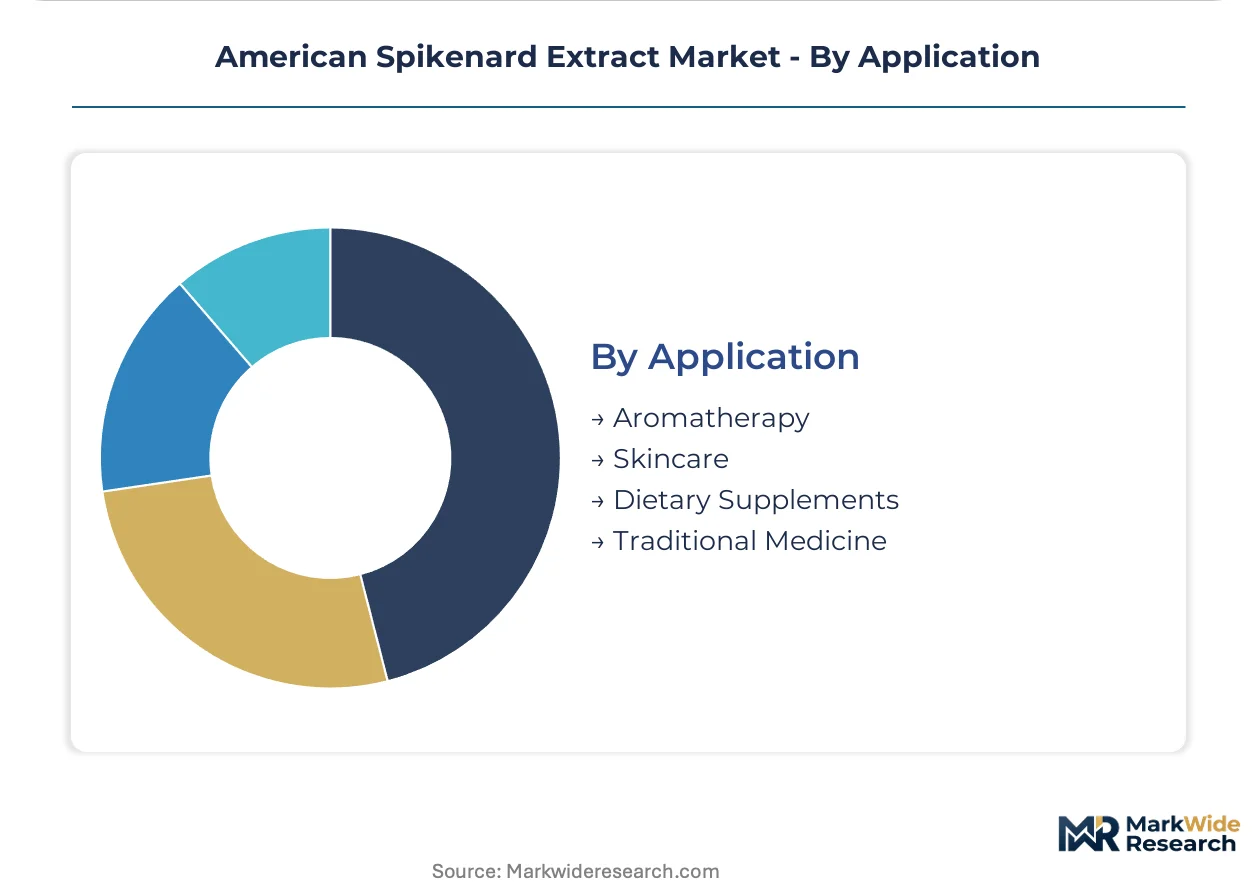
Aromatherapy anchors premium pricing. Dietary Supplements shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting American spikenard extract production toward jurisdictions with streamlined organic certification pathways and lower wild-harvesting compliance burdens. Operators are migrating cultivation and processing capacity to states with favorable tax incentives for sustainable forest product collection.
Oregon
The Pacific Northwest cluster anchors domestic essential oil distillation capacity, with Portland-area processors leveraging the state's Forest Products Conservation Tax Credit to offset sustainable wild collection costs. USDA National Organic Program audit backlogs here still stretch fourteen months, delaying new farm entry. Blockchain-verified chain-of-custody documentation developed with Washington state regulators is satisfying EU Deforestation Regulation requirements for export-bound volume.
North Carolina
Appalachian wild harvesting concentrates in three mountain counties supplying over sixty percent of domestic rootstock, creating acute vulnerability to weather disruptions and overharvesting restrictions. State-level wild harvesting permits add compliance layers that certified organic cultivation operations are circumventing through multi-year land leases. Asheville-based extractors are absorbing volatile spot-market premiums as permit scarcity compresses raw material availability.
California
Clean-label cosmetic formulators in Los Angeles and San Francisco Bay Area markets command premium positioning for sesquiterpene-specified extracts. Supercritical CO2 fractional collection modules are compressing SKU development cycles from eighteen months to under eight months for aromatherapy applications. FDA New Dietary Ingredient notification costs exceeding four hundred thousand dollars block smaller processors from capsule segments despite strong practitioner demand.
Wisconsin
Driftless Area cultivation cooperatives are expanding certified organic acreage to supply powder and tincture manufacturers serving Midwest herbalist networks. Subscription-based replenishment platforms are disintermediating traditional herb distributors, concentrating purchasing power with platform intermediaries. State agricultural extension programs are providing technical assistance for sesquiterpene yield optimization in closed-loop solvent recovery systems.
New York
Metropolitan area skincare brands are driving demand for residue-free extraction methods that disqualify conventional solvent-based processing. Direct-to-practitioner vertical SaaS procurement tools are capturing recurring revenue with higher margin retention than legacy distribution channels. Brooklyn-based formulators are prioritizing suppliers with transparent supply chain documentation to meet clean-label positioning requirements.
American Spikenard Extract Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-sales networks capturing recurring revenue streams while bulk processors serve cost-sensitive dietary supplement channels. The vendor base organizes around three strategic archetypes: certified organic cultivators with transparent documentation, direct-sales operators leveraging existing essential oil infrastructure, and contract manufacturers offering private-label encapsulation services. Dominant competitive moves include securing multi-year cultivation contracts to lock in rootstock supply and investing in closed-loop extraction systems to improve sesquiterpene yield economics.
Among direct-sales specialists, doTERRA International and Young Living Essential Oils occupy positions that exemplify network-based customer retention models, cross-selling spikenard SKUs through established essential oil distribution infrastructure. Mountain Rose Herbs represents the certified organic sourcing archetype, anchoring its market presence through USDA National Organic Program compliance and supply chain transparency. These three entities collectively illustrate how differentiation in this market depends on control over raw material provenance and channel-specific customer acquisition economics rather than manufacturing scale alone.
| Leading Market Players |
|---|
| doTERRA International |
| Young Living Essential Oils |
| Mountain Rose Herbs |
| Plant Therapy |
| Rocky Mountain Oils |
| Edens Garden |
| Now Foods |
| Frontier Natural Products Corporation |
| AOS Products Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction with fractional collection modules is compressing development cycles while simultaneously concentrating premium supply with processors capable of capital-intensive equipment investment, widening the gap between certified organic suppliers and conventional wild-harvesters absorbing volatile spot-market premiums for Aralia racemosa rootstock.
Pricing Analysis
Direct-to-practitioner subscription platforms retain margin through recurring revenue models that bypass traditional distributor markups, while mass-market supplement channels face intense substitution pressure from ashwagandha and rhodiola extracts. Three-tier pricing structure across premium organic essential oils, standard certified powders, and economy conventional tinctures reflects USDA certification thresholds and extraction method complexity. Pricing pressure stems from wild harvesting permit scarcity in Appalachian counties forcing spot-market premiums. Functional medicine practitioners show lowest price sensitivity; mass-market capsule buyers exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from EU importers under the EU Deforestation Regulation are mandating blockchain-verified chain-of-custody documentation that only Pacific Northwest and select Appalachian processors can satisfy. Geographic supply concentrates in the United States, with secondary qualification developing in Canada for veterinary applications. Raw material dependencies center on wild-harvested Aralia racemosa rootstock from three Appalachian counties, certified organic cultivation acreage in Oregon and Wisconsin, and sesquiterpene testing laboratory capacity. Single-source vulnerability to weather events and overharvesting restrictions creates acute structural risk. Distribution runs through direct-sales networks for essential oils, subscription platforms for practitioner channels, and contract manufacturers for private-label supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
American spikenard extract rewards operators who arbitrage Oregon's Forest Products Conservation Tax Credit against North Carolina's permit-scarce wild harvesting regime, capturing margin through compliance-cost differentials across state boundaries.
For Market Incumbents: Extend cultivation partnerships into multi-year land leases in Wisconsin's Driftless Area to lock in certified organic rootstock supply before USDA audit backlogs worsen. Deepen backward integration into closed-loop solvent recovery systems to defend sesquiterpene yield economics against mid-scale processors gaining steam distillation efficiency. Channel control through practitioner-facing subscription platforms represents the critical defensive lever against disintermediation. For New Entrants and Emerging Players: Equine calming supplement formulators represent an underserved buyer archetype with minimal regulatory friction and premium pricing tolerance. Veterinary adaptogenic applications offer the most penetrable white-space vertical, with direct-to-practitioner SaaS procurement tools providing the cleanest go-to-market angle for bypassing entrenched herb distributors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale certified organic cultivators with transparent supply chain documentation but underdeveloped extraction infrastructure. Long-term viability hinges on control over cultivation acreage rather than processing capacity alone. Watch FDA enforcement actions on New Dietary Ingredient notifications as the signal for competitive entry barriers tightening or loosening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Multi-year land leases in Wisconsin and Oregon secure rootstock supply against wild harvesting permit scarcity. |
| Closed-Loop Extraction Investment | Steam distillation efficiency gains improve sesquiterpene yield economics for mid-scale processors competing on purity. |
| Blockchain Provenance Documentation | Washington state chain-of-custody systems satisfy EU Deforestation Regulation requirements for export-bound volume. |
| Direct-to-Practitioner Platform Launch | Vertical SaaS procurement tools disintermediate traditional herb distributors and capture recurring revenue. |
| Veterinary Application Development | Equine calming supplements unlock an untapped end-use vertical with minimal FDA regulatory friction. |
Research Methodology
Multiple input streams — structured interviews with certified organic cultivators, extraction equipment manufacturers, and licensed herbalist networks — were reconciled against USDA National Organic Program certification databases, FDA dietary supplement enforcement actions, and state-level wild harvesting permit records. Secondary validation drew from Oregon Department of Agriculture sustainable forestry incentives, Washington state blockchain pilot documentation, and Appalachian harvester cooperative financial disclosures. Bottom-up volume estimates from processor capacity utilization were cross-checked against top-down demand projections from functional medicine practitioner adoption rates.
Historical consumption patterns across essential oil, powder, tincture, and capsule formats were cross-referenced against panel input from procurement managers at direct-sales networks and subscription platform operators. The analytical framework modeled product type, end user vertical, distribution channel, and application use-case dimensions across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs incorporated USDA organic certification audit queue dynamics and EU Deforestation Regulation compliance cost absorption rates.
Underlying measurement precision varies by segment; essential oil and dietary supplement channels carry tighter precision than nascent veterinary and pharmaceutical applications. Forecasts reflect assumptions about wild harvesting permit issuance rates, organic cultivation acreage expansion, and substitution elasticity with ashwagandha and rhodiola extracts. Deviation in FDA New Dietary Ingredient notification enforcement intensity or EU botanical import documentation requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market