
 Global Floral Flavors Market | 2026-2036
Global Floral Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Floral Flavors Market Intelligence
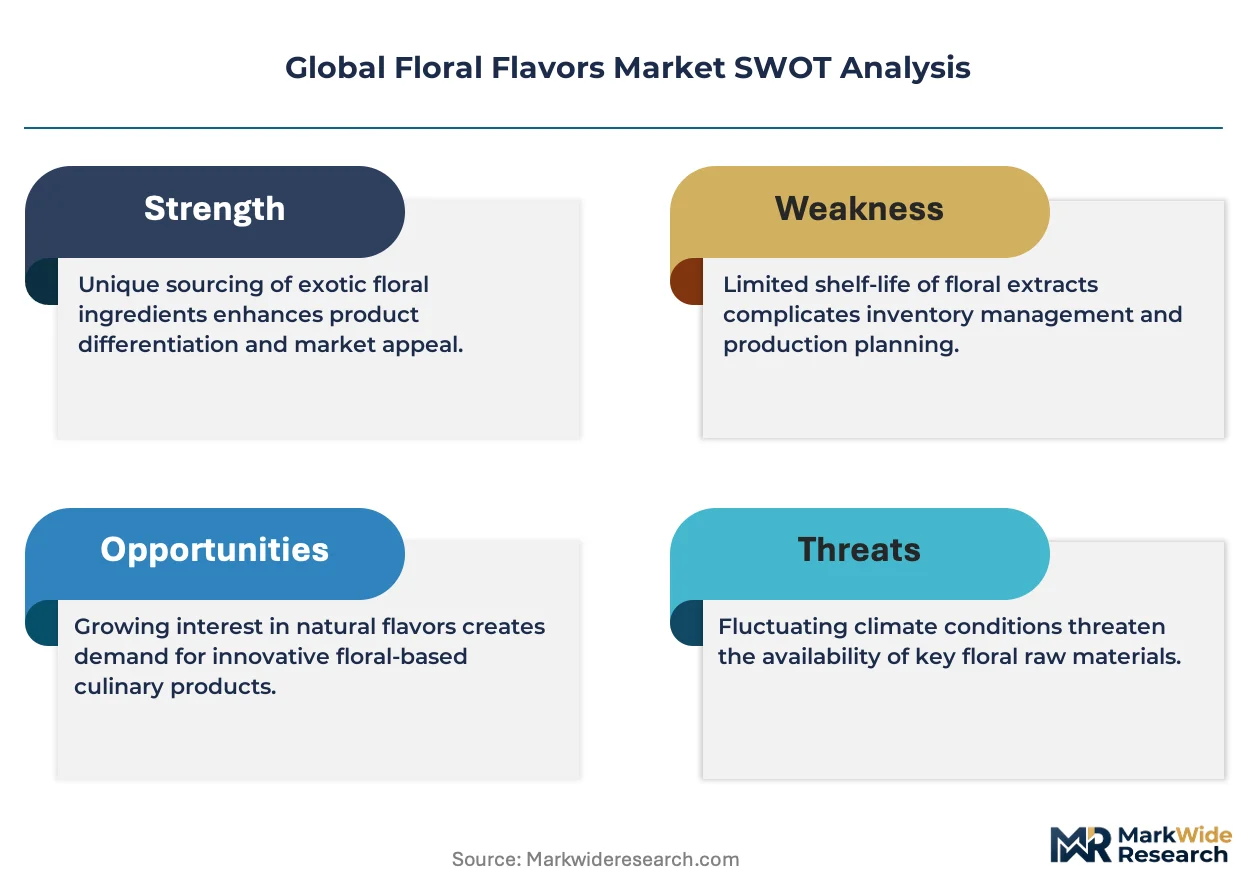
European essential oil distilleries is consolidating around certified organic rose and lavender fields in Bulgaria and France. Givaudan leverages its Grasse-based extraction infrastructure to supply fragrance houses with traceable botanical supply chains. Firmenich SA anchors its competitive position through proprietary enzymatic processing that preserves volatile terpene profiles. Symrise AG differentiates via deep partnerships with Moroccan jasmine cooperatives, securing multi-year harvest contracts.
Floral flavors denote aromatic compounds extracted from flower petals, buds, or whole blossoms through steam distillation, solvent extraction, or supercritical CO2 processing, yielding essential oils, absolutes, or hydrosols used to impart scent and taste in consumer products. Steam-distilled lavender and cold-pressed orange blossom oils dominate volume flows into beverage and confectionery applications, where clean-label positioning commands shelf space. Solvent-extracted jasmine and rose absolutes capture concentrated margin pools in fine fragrance and luxury cosmetics, while CO2 extraction methods are gaining traction among pharmaceutical-grade suppliers seeking solvent-free certification for aromatherapy and nutraceutical uses.
FDA food additive regulations, EFSA flavoring substance evaluations under Regulation EC No 1334/2008, and India's FSSAI natural flavoring guidelines collectively determine which botanical extracts achieve commercial clearance across major demand centers. REACH registration requirements and EU Green Deal biodiversity targets are tightening traceability mandates, forcing extractors to document cultivation provenance and sustainable harvesting practices. Stakeholders must monitor evolving clean-label certification schemes and bioprospecting access agreements as botanical supply chains face intensifying scrutiny from both regulators and consumer advocacy groups.
Market Dynamics
REACH registration requirements and EU Green Deal biodiversity targets are compressing formulation timelines for fragrance houses, forcing accelerated migration from synthetic molecules to traceable botanical supply chains as regulatory clearance windows narrow.
Growth Catalysts
- EU Green Deal biodiversity mandates:REACH restrictions on synthetic fragrance precursors redirect R&D budgets toward certified organic rose and lavender cultivation in Bulgaria and France.
- Steam distillation infrastructure:Traditional extraction methods dominate beverage-grade lavender and orange blossom oil flows, securing clean-label shelf positioning in premium sparkling water.
- Japan:METI guidance on natural ingredient sourcing reinforces domestic demand for pharmaceutical-grade CO2 extracts in aromatherapy applications.
Market Restraints
- Input cost volatility:Jasmine harvest yields in Morocco fluctuate with rainfall patterns, compressing margin predictability for absolute suppliers.
- Supply concentration risk:Bulgarian rose oil distillation clusters around the Kazanlak Valley, creating single-point vulnerability for fine fragrance formulators.
- Regulatory friction:FSSAI natural flavoring guidelines in India impose multi-year documentation requirements that delay new extract commercialization.
Strategic Opportunities
- Ayurvedic nutraceuticals:India's established extraction infrastructure supports expansion into clinical-grade floral hydrosols for wellness applications.
- Direct-to-brand procurement:Beverage manufacturers bypass traditional distributors to contract directly with Grasse-based extraction facilities.
- Enzymatic processing patents:Proprietary terpene preservation technologies create defensible IP positions in luxury cosmetics formulation.
Industry Challenges
- Skilled distiller scarcity:Traditional steam distillation expertise concentrates among aging practitioners in southern France, constraining capacity expansion.
- Organic certification timelines:ECOCERT and USDA Organic accreditation cycles extend 18-24 months, delaying new field commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Floral Flavors Market |
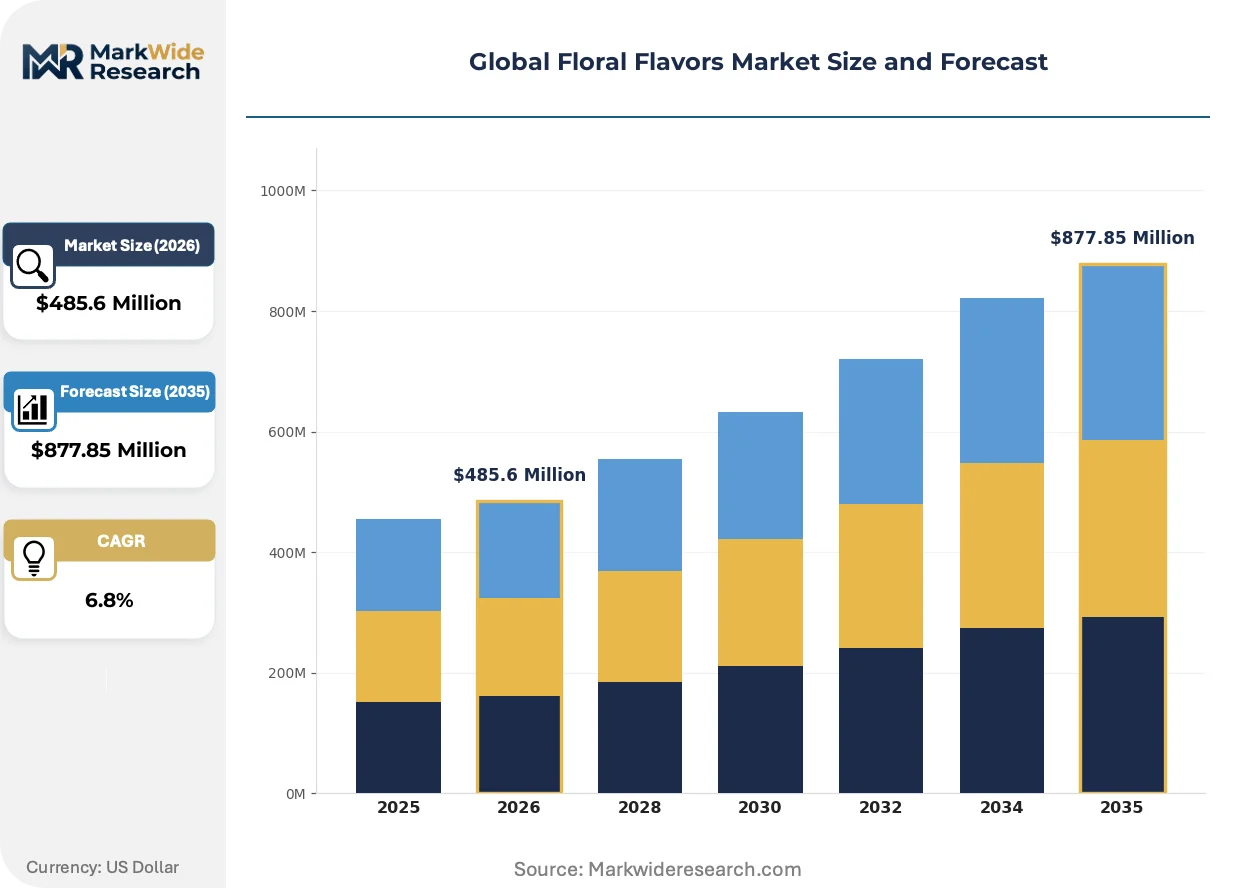
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
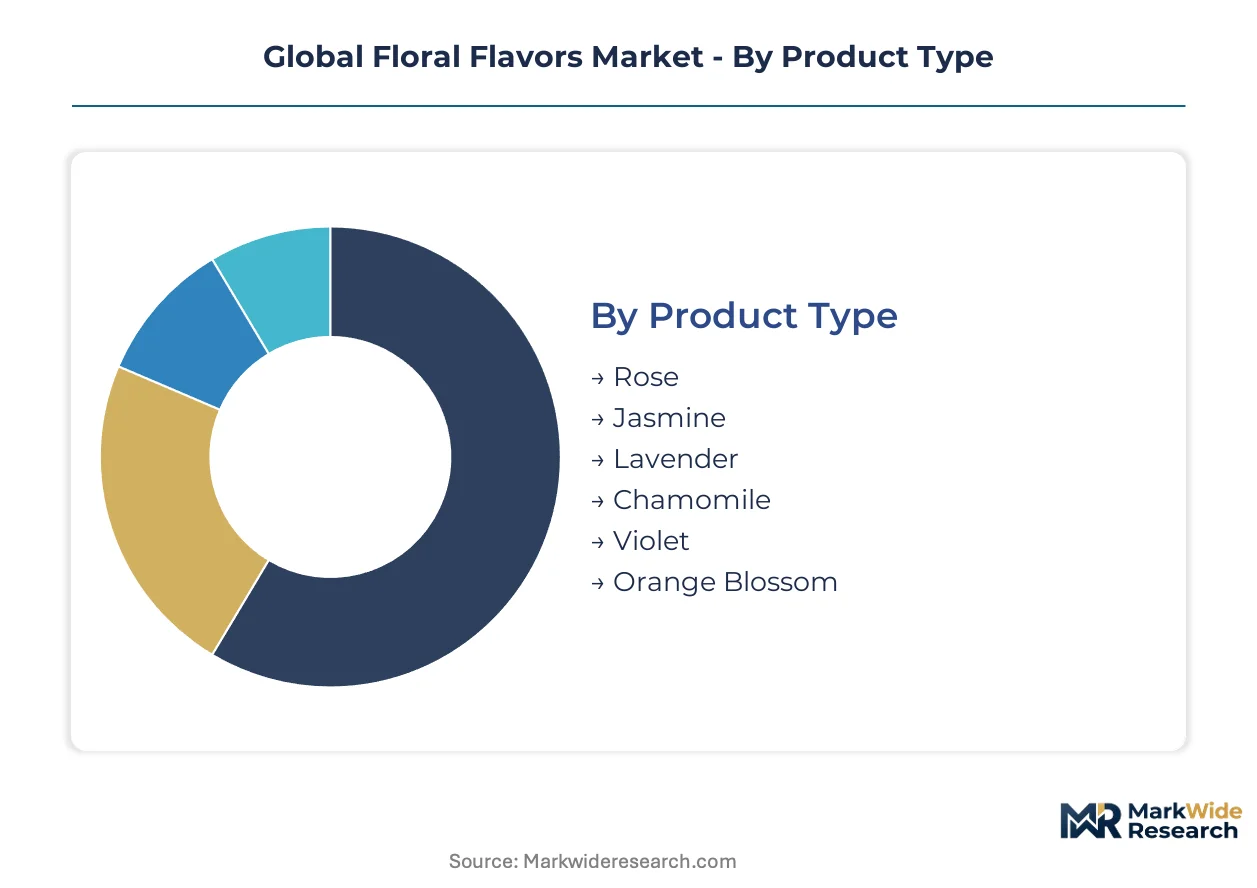
| Segmentation | Product Type: Rose, Jasmine, Lavender, Chamomile, Violet, Orange Blossom Application: Beverages, Confectionery, Cosmetics, Pharmaceuticals, Personal Care, Household Products Extraction Method: Steam Distillation, Solvent Extraction, Cold Pressed, CO2 Extraction, Maceration End User Industry: Food & Beverage Manufacturers, Fragrance Producers, Pharmaceutical Companies, Cosmetic Brands, Aromatherapy Providers |
| Companies Covered | Givaudan, Firmenich SA, International Flavors & Fragrances Inc., Symrise AG, Sensient Technologies Corporation, Takasago International Corporation, Mane SA, BASF SE, Robertet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Floral Flavors Market Strategic Shifts & Innovations
Extraction technology maturation and regulatory chemistry restrictions are compressing the synthetic-to-botanical transition timeline across fragrance and flavor applications.
Supercritical CO2 extraction is consolidating its position in pharmaceutical-grade supply chains by eliminating residual solvent concerns that plague traditional hexane-based absolute production. Nutraceutical manufacturers in Japan and Switzerland prioritize CO2-processed chamomile and calendula extracts for capsule formulations. The technology is consolidating quality premiums previously captured by cold-pressed and enfleurage methods.
EFSA flavoring substance evaluations under Regulation EC No 1334/2008 are tightening safety dossier requirements for botanical extracts entering food and beverage channels. Fragrance houses now submit toxicological data 12-18 months earlier in development cycles. Fine fragrance applications face compressed innovation pipelines as reformulation costs escalate.
Long-term harvest contracting is displacing spot-market purchasing among major fragrance houses seeking supply security. Moroccan jasmine cooperatives now lock three-to-five-year purchase commitments with European formulators. Grasse-based extraction facilities report similar contract structures for Bulgarian lavender and Turkish rose.
Global Floral Flavors Market Segmentation
Formulation pipelines across beverages, cosmetics, and pharmaceuticals require distinct floral extract specifications. Procurement teams segment sourcing by terpene profile stability, solvent residue thresholds, and volume scalability to match end-use regulatory requirements.
Product Type:
Upgrade cycles in premium fragrance and clean-label beverage formulations are accelerating replacement of synthetic alternatives with certified botanical extracts.
- Rose:Bulgarian damascena and Moroccan centifolia varietals yield high citronellol and geraniol concentrations prized in fine fragrance. Distilleries in Kazanlak Valley face capacity constraints as Grasse-based houses lock multi-year harvest contracts.
- Jasmine:Grandiflorum absolutes from solvent extraction command concentrated margin pools in luxury cosmetics. Moroccan cooperatives report three-to-five-year purchase commitments from European formulators seeking supply security against rainfall-driven yield volatility.
- Lavender:Steam-distilled Bulgarian and French oils dominate beverage-grade volume flows into premium sparkling water.
- Chamomile:CO2-extracted German and Egyptian varieties target pharmaceutical-grade aromatherapy applications in Japan and Switzerland.
- Violet:Ionone-rich leaf extracts serve niche confectionery and fine fragrance formulations with limited commercial scale.
- Orange Blossom:Cold-pressed Tunisian and Spanish neroli oils supply clean-label confectionery and beverage markets.
Volume placements concentrate in lavender and rose oils; the faster expansion belongs to chamomile CO2 extracts for nutraceutical capsules.
Application:
Margin structures diverge sharply between mass-market beverage dosing and micro-batch fine fragrance compounding.
- Beverages:Premium sparkling water and botanical spirits manufacturers specify steam-distilled lavender and orange blossom oils for clean-label positioning. EFSA flavoring evaluations under Regulation EC No 1334/2008 compress formulation timelines.
- Cosmetics:Solvent-extracted jasmine and rose absolutes capture quality premiums in luxury skincare. Proprietary enzymatic processing patents at Grasse-based facilities preserve volatile terpene profiles for shelf-stable formulations.
- Confectionery:Violet and rose water hydrosols flavor premium chocolate and sugar confectionery with traceable organic certification.
- Pharmaceuticals:CO2-extracted chamomile and calendula meet pharmaceutical-grade specifications for aromatherapy and clinical wellness applications.
- Personal Care:Lavender and chamomile essential oils formulate mass-market shampoos and lotions with natural positioning claims.
- Household Products:Lower-concentration lavender and orange blossom oils scent eco-labeled cleaning and home fragrance products.
Revenue concentration sits with cosmetics and beverages; pharmaceuticals are climbing the fastest on METI-guided demand in Japan.
Extraction Method:
Technology maturation timelines and regulatory clearance windows determine capital allocation across processing infrastructure.
- Steam Distillation:Traditional batch processing of lavender and orange blossom dominates beverage-grade volume. Aging practitioner scarcity in southern France constrains capacity expansion despite demand acceleration.
- CO2 Extraction:Supercritical processing eliminates residual solvent concerns for pharmaceutical-grade chamomile and calendula. Japanese and Swiss nutraceutical manufacturers prioritize CO2 certification for capsule formulations.
- Solvent Extraction:Hexane-based absolute production yields jasmine and rose concentrates for fine fragrance. REACH registration requirements pressure migration toward traceable supply chains.
- Cold Pressed:Mechanical expression preserves neroli oil integrity for premium confectionery and beverage applications.
- Maceration:Oil-infusion methods serve small-batch artisanal producers with limited commercial scale.
Installed capacity concentrates in steam distillation; CO2 extraction is gaining share fastest on pharmaceutical certification demand.
End User Industry:
Procurement authority is shifting from traditional distributors toward direct brand-contractor relationships with extraction facilities.
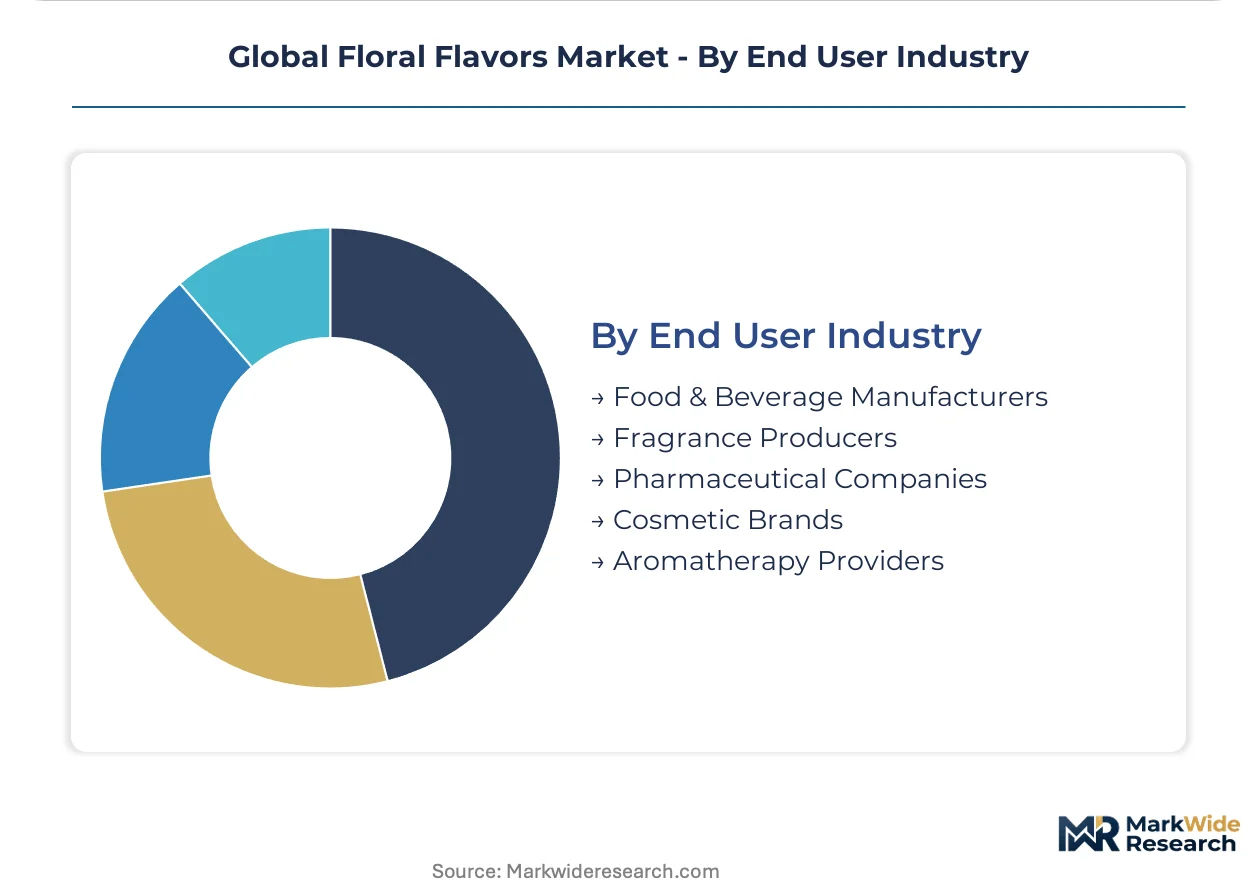
- Food & Beverage Manufacturers:Premium sparkling water and botanical spirits producers contract directly with Grasse-based extraction facilities, bypassing traditional distributors. FDA food additive regulations and FSSAI natural flavoring guidelines govern clearance pathways.
- Fragrance Producers:Givaudan, Firmenich SA, and Symrise AG anchor supply through proprietary processing patents and Moroccan jasmine cooperative partnerships.
- Pharmaceutical Companies:Japanese and Swiss manufacturers prioritize CO2-extracted chamomile for aromatherapy capsule formulations under METI guidance.
- Cosmetic Brands:Luxury skincare houses specify solvent-extracted jasmine and rose absolutes with ECOCERT organic accreditation.
- Aromatherapy Providers:Clinical-grade hydrosol demand in India leverages established Ayurvedic extraction infrastructure for wellness expansion.
Contract value concentrates with fragrance producers and food & beverage manufacturers; pharmaceutical companies show the steepest procurement trajectory on nutraceutical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulgarian rose fields in the Kazanlak Valley anchor European supply chains, while Moroccan jasmine cooperatives and Indian Ayurvedic processors sustain parallel extraction networks across distinct regulatory environments.
France
Grasse-based extraction facilities supply fragrance houses with traceable botanical supply chains as EU Green Deal biodiversity mandates redirect formulation budgets toward certified organic cultivation. ECHA REACH registration requirements compress clearance timelines for plant-derived alternatives. The Provence-Alpes-Côte d'Azur region concentrates traditional steam distillation expertise among aging practitioners.
India
Ayurvedic medicine traditions sustain established extraction infrastructure for clinical-grade floral hydrosols targeting wellness applications. FSSAI natural flavoring guidelines impose multi-year documentation requirements that delay new extract commercialization. Maharashtra and Karnataka host pharmaceutical-grade processing facilities serving domestic aromatherapy demand.
Japan
METI guidance on natural ingredient sourcing reinforces procurement of pharmaceutical-grade CO2 extracts for capsule formulations. Japanese nutraceutical manufacturers prioritize solvent-free certification for chamomile and calendula extracts. The Kanto region around Tokyo anchors import distribution networks for Swiss and German extraction specialists.
Bulgaria
The Kazanlak Valley concentrates damascena rose oil distillation capacity facing constraints from multi-year harvest contracts locked by Grasse-based houses. ECOCERT organic accreditation cycles extend 18-24 months for new field commercialization. Bulgarian lavender cultivation competes with French supply for beverage-grade volume flows.
Morocco
Grandiflorum jasmine absolutes from solvent extraction command concentrated margin pools in luxury cosmetics as rainfall patterns drive harvest yield volatility. Moroccan cooperatives report three-to-five-year purchase commitments from European formulators seeking supply security. The Marrakech-Safi region anchors traditional enfleurage processing for niche fragrance applications.
Global Floral Flavors Market Key Industry Players
Global majors compete with regional champions across extraction infrastructure and cooperative partnerships, producing a tiered structure where proprietary processing patents sit alongside traditional harvest contracting. Swiss and German fragrance houses anchor premium positioning through Grasse-based facilities and enzymatic technologies. Three archetypes dominate: integrated fragrance-flavor conglomerates with proprietary extraction assets, specialized botanical houses leveraging regional cooperative networks, and diversified chemical suppliers extending into natural ingredients. Competitive moves concentrate on long-term harvest contracting and direct-to-brand procurement relationships that bypass traditional distribution.
Within the integrated conglomerate tier, Givaudan and Firmenich SA exemplify positioning anchored in proprietary extraction infrastructure and processing patents. Symrise AG occupies a distinct position through deep cooperative partnerships with regional harvest networks. Among diversified chemical suppliers, BASF SE represents scale-driven entry into botanical alternatives. Sensient Technologies Corporation and Takasago International Corporation sit within the specialized mid-tier, reflecting geographic diversification strategies across North American and Asian demand centers.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich SA |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Sensient Technologies Corporation |
| Takasago International Corporation |
| Mane SA |
| BASF SE |
| Robertet Group |
| Others |
Cost & Logistics Intelligence
Jasmine harvest yields in Morocco fluctuate with rainfall patterns, transmitting volatility through absolute pricing tiers as Grasse-based fragrance houses absorb premium risk via long-term purchase commitments while beverage manufacturers downstream face spot-market exposure for lavender and orange blossom oils.
Pricing Analysis
Certification bundling separates ECOCERT-accredited organic extracts from conventional grades, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on terpene profile stability and solvent residue thresholds, with pharmaceutical-grade CO2 extracts commanding quality premiums over steam-distilled beverage grades. Cost compression in standard-tier lavender oil is intensifying because Bulgarian field expansion lags organic accreditation timelines. Beverage manufacturers exhibit highest price sensitivity due to volume procurement scales, while luxury cosmetics houses absorb premium pricing for jasmine absolutes.
Supply Chain Analysis
EU Green Deal local-content mandates and REACH traceability requirements are reshaping sourcing patterns toward documented cultivation provenance in Bulgaria, France, and Morocco. Raw material flows draw from damascena rose fields in Kazanlak Valley, grandiflorum jasmine cooperatives around Marrakech-Safi, and lavender cultivation across Provence-Alpes-Côte d'Azur. Single-source vulnerability concentrates in Bulgarian rose oil distillation clusters. Distribution runs through direct-to-brand procurement relationships that bypass traditional fragrance distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction is displacing hexane-based solvent methods across pharmaceutical-grade supply chains, compressing the synthetic-to-botanical transition timeline for fragrance and flavor applications.
For Market Incumbents: Anticipate regulatory chemistry restrictions under EFSA flavoring substance evaluations by accelerating enzymatic processing patent filings that preserve volatile terpene profiles. Secure backward integration into certified organic rose and lavender cultivation in Bulgaria and France before ECOCERT accreditation cycles extend capacity constraints. Counter rainfall-driven jasmine yield volatility through deeper cooperative partnerships with Moroccan harvest networks. For New Entrants and Emerging Players: REACH registration requirements in Europe open a window for solvent-free CO2 extraction specialists to capture pharmaceutical-grade contract manufacturing demand from Japanese nutraceutical manufacturers under METI guidance. Target India's Ayurvedic wellness expansion where FSSAI documentation delays create incumbent vulnerability for clinical-grade floral hydrosol supply. Pursue direct-to-brand procurement relationships with premium sparkling water manufacturers seeking traceable botanical supply chains. For Investors and Strategic Acquirers: Multi-year harvest contract announcements from Grasse-based extraction facilities are the leading indicator that supply security premiums are becoming embedded in valuation frameworks. Position for consolidation plays across enzymatic processing technology holders and regional cooperative networks. Watch organic certification backlog queues as the inflection signal for capacity-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Harvest Contracting | Grasse-based houses lock Bulgarian rose supply against Kazanlak Valley capacity constraints. |
| Enzymatic Processing Patent Investment | Firmenich SA and competitors defend terpene preservation IP for luxury cosmetics formulations. |
| Direct-to-Brand Procurement | Beverage manufacturers bypass distributors to contract with Provence extraction facilities. |
| CO2 Extraction Scale-Up | Swiss and Japanese nutraceutical suppliers prioritize solvent-free certification for capsule formulations. |
| Organic Certification Pipeline | ECOCERT and USDA Organic accreditation investments secure clean-label shelf positioning premiums. |
Research Approach
Document review covered EU REACH registration databases, EFSA flavoring substance evaluations, FSSAI natural flavoring guidelines, and METI natural ingredient sourcing guidance, complemented by interviews with extraction facility technical directors, fragrance house procurement leads, beverage manufacturer R&D heads, and cooperative agricultural managers. Secondary sources included customs trade data for essential oil flows, ECOCERT organic certification registries, and SEC filings from integrated fragrance-flavor conglomerates. Bottom-up field-level cultivation data triangulated against top-down formulation demand estimates.
Segmentation outputs across product type, application, extraction method, and end-user industry were modeled over the projection horizon. CAGRs were derived from trend extrapolation of procurement contract values and volume placements by extraction technology. Industry-specific forecast inputs incorporated organic certification pipeline timelines and rainfall-correlated jasmine yield volatility indices.
Caveats apply where regulatory clearance delays, harvest yield shocks, or synthetic fragrance substitution reversals could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Africa Food Flavor Market