
 Water-Soluble Flavors Market | 2026-2036
Water-Soluble Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Soluble Flavors Market Analytics
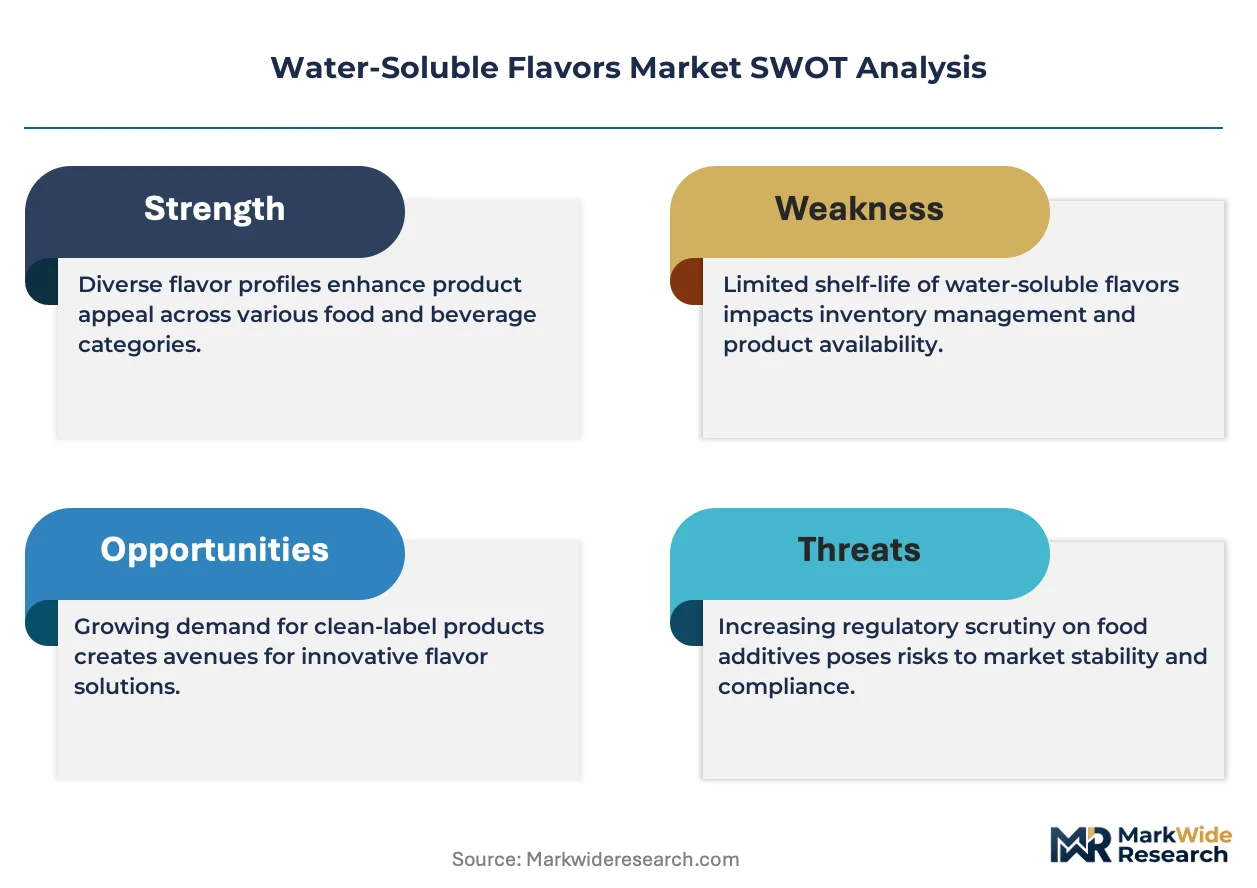
Asset-light toll manufacturing and third-party flavor compounding arrangements are reshaping competitive entry in water-soluble flavors. Givaudan SA leverages captive biotechnology platforms to secure botanical extraction capacity. International Flavors & Fragrances Inc. anchors North American beverage supply through integrated flavor creation labs. Symrise AG competes via fermentation-derived natural molecules that bypass agricultural supply volatility.
Water-soluble flavors comprise volatile and non-volatile compounds engineered for complete dispersion in aqueous matrices, typically delivered as liquid emulsions, spray-dried powders, or plated systems with particle sizes below 300 microns for uniform suspension. Natural flavors command premium positioning as clean-label formulations displace artificial alternatives in beverage and dairy applications. Fruit flavors dominate volume in confectionery and soft drink channels where heat-stable citrus and berry profiles sustain repeat purchase. Herbal flavors represent the fastest-expanding margin pool as functional beverage producers seek adaptogenic and botanical positioning.
FDA food additive regulations under 21 CFR 172 and the EPA's Clean Water Act discharge standards govern US manufacturing compliance, while EU Flavoring Regulation 1334/2008 and EFSA safety evaluations shape permissible substance lists across European formulations. BIS certification requirements and FSSAI flavor standards in India add complexity for exporters targeting emerging processed food markets. Stakeholders must monitor evolving natural flavor definition disputes between jurisdictions that threaten harmonized product registration strategies.
Market Dynamics
Clean-label beverage formulation mandates are compressing artificial flavor inventories while biotechnology platforms expand natural extraction capacity, forcing procurement restructuring across carbonated and functional drink supply chains.
Growth Catalysts
- EU Flavoring Regulation 1334/2008:Tightening permissible substance lists accelerates natural flavor substitution in German and French beverage manufacturing corridors.
- Fermentation-derived molecules:Precision biotechnology bypasses agricultural supply volatility for heat-stable citrus and berry profiles in soft drink applications.
- Adaptogenic positioning:Functional beverage producers in North America drive herbal flavor demand for botanical and nootropic product lines.
Market Restraints
- Botanical raw material concentration:Vanilla and citrus extract supply clusters in Madagascar and Brazil expose formulators to climate-driven price spikes.
- 21 CFR 172 compliance costs:FDA food additive petition requirements extend new natural flavor approval timelines to 24-36 months.
- Spray-drying energy intensity:Natural flavor encapsulation requires 40% more thermal input than artificial alternatives, compressing margin at mid-tier producers.
Strategic Opportunities
- India processed food expansion:BIS certification and FSSAI flavor standard alignment opens export pathways for compliant natural extract suppliers.
- Direct-to-beverage-compound distribution:Toll manufacturing partnerships bypass traditional flavor house intermediaries for regional craft producers.
- EU Green Deal bioeconomy incentives:Fermentation platform investments qualify for circular economy funding streams in German biotechnology clusters.
Industry Challenges
- Flavor chemist talent scarcity:Natural extraction and emulsion stabilization expertise concentrates at legacy European technical institutes.
- Cross-jurisdictional registration complexity:Divergent natural flavor definitions between FDA, EFSA, and FSSAI force redundant safety dossier preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Soluble Flavors Market |
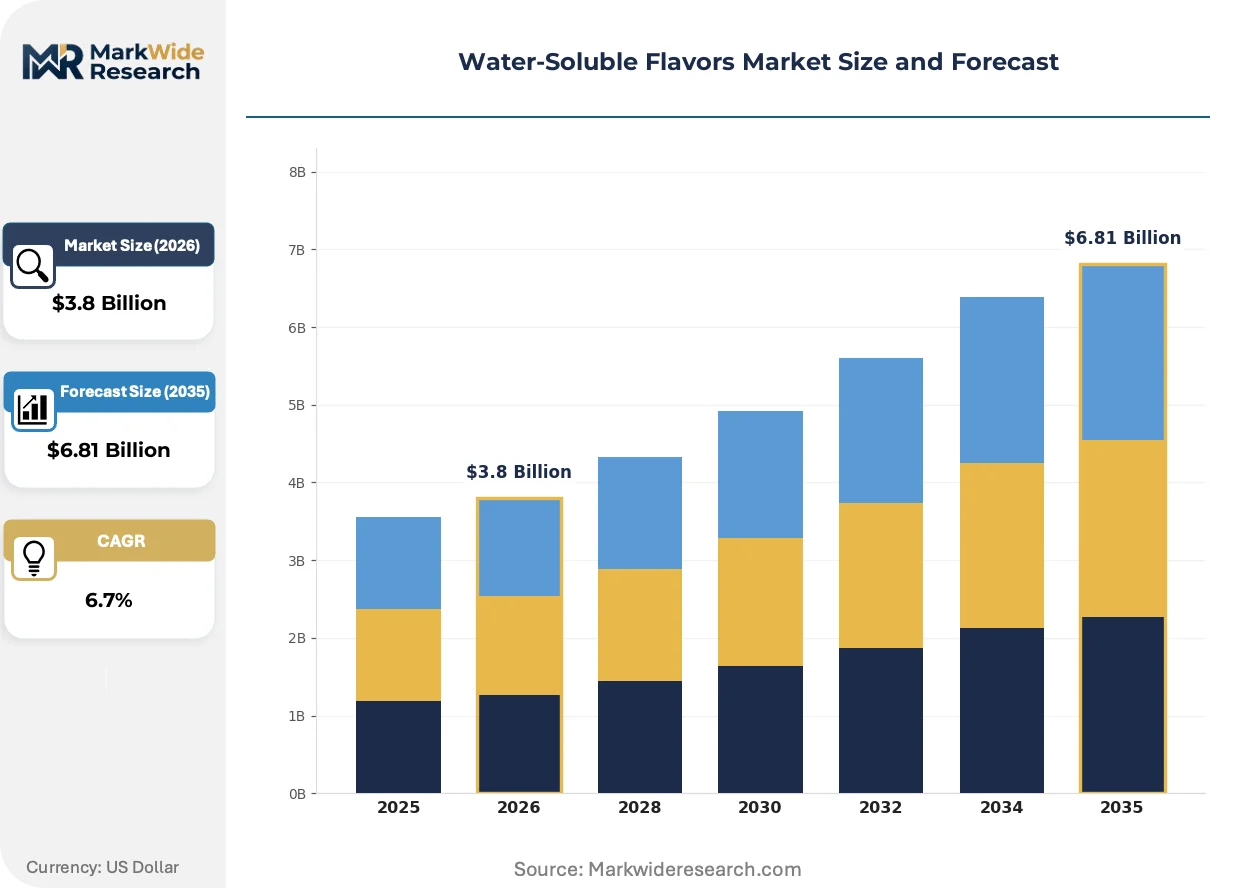
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Fruit Flavors, Herbal Flavors Application: Beverages, Dairy Products, Bakery Items, Confectionery End User: Food Manufacturers, Beverage Producers, Restaurants, Home Consumers Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Givaudan SA, International Flavors & Fragrances Inc., Symrise AG, Firmenich SA, Kerry Group plc, Takasago International Corporation, Sensient Technologies Corporation, Archer-Daniels-Midland Company, Nature's Flavors, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Soluble Flavors Market Evolving Landscape
Biotechnology platforms, regulatory harmonization pressures, and procurement restructuring are compressing traditional flavor house intermediation while expanding captive manufacturing options.
Cell-culture extraction technology is virtualizing botanical supply chains by producing rare volatile compounds without agricultural cultivation. Premium beverage producers in Germany and Switzerland are adopting these platforms for vanilla and saffron profiles previously constrained by harvest volatility. This virtualization is compressing traditional spice trade margins while securing year-round supply consistency for clean-label formulations.
EFSA safety evaluation protocols under EU Flavoring Regulation 1334/2008 are tightening natural flavor substance lists ahead of 2025 reauthorization cycles. Flavor houses must resubmit dossiers for legacy botanical extracts or face formulation exclusion. Heat-stable citrus applications in carbonated beverages face the highest reformulation pressure, driving accelerated fermentation-derived alternative development.
Buyer concentration among multinational beverage conglomerates is compressing supplier negotiation leverage. Procurement teams now mandate integrated flavor creation labs co-located with production facilities, displacing arm's-length compound purchasing. This consolidation is most visible in North American functional beverage manufacturing, where technical collaboration agreements replace transactional supply contracts.
Water-Soluble Flavors Market Segmentation
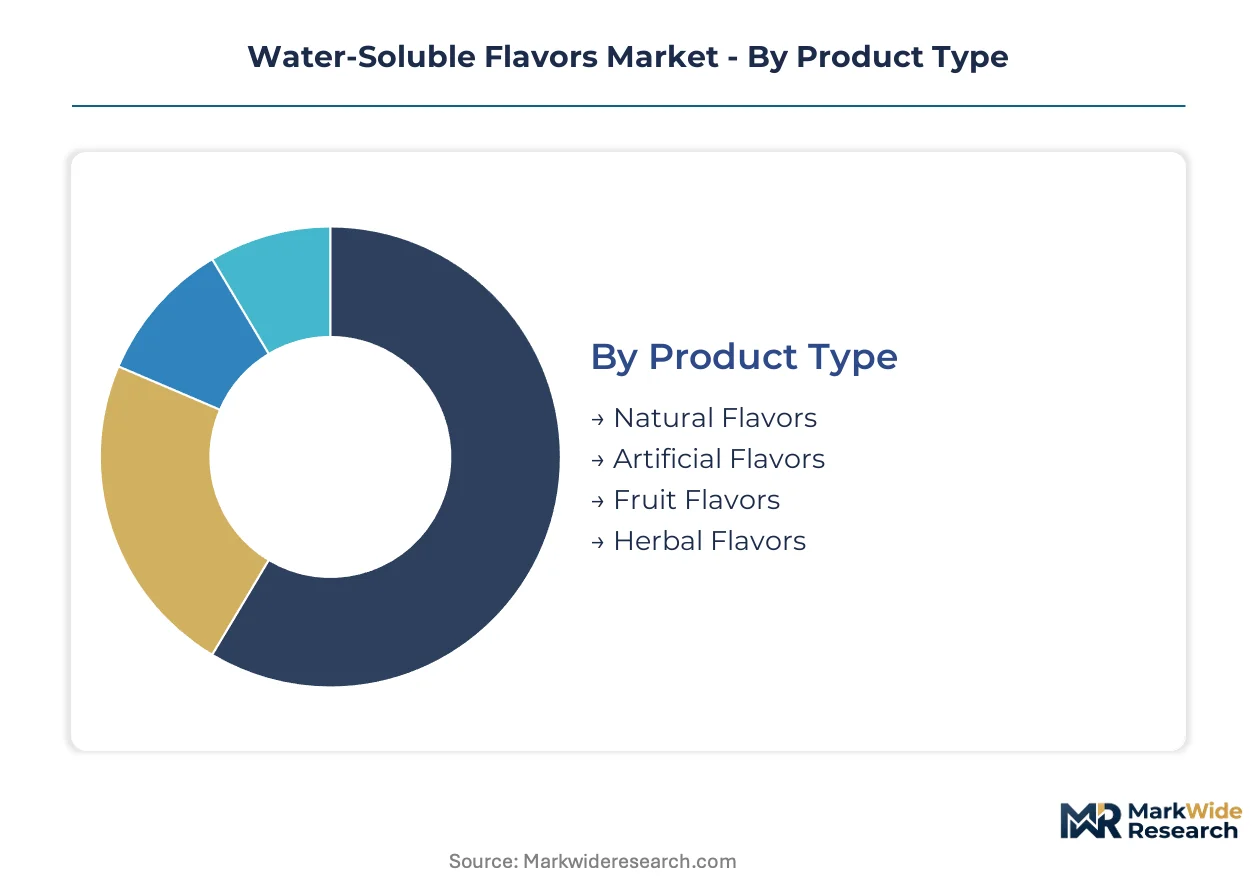
Water-soluble flavors fragment across technical specifications, regulatory classifications, and end-use performance requirements. Procurement teams evaluate segments against clean-label mandates, heat stability thresholds, and aqueous dispersion characteristics that vary sharply by application matrix.
Product Type:
Use-case spectrum spans certified natural extracts for premium beverage positioning through cost-engineered artificial systems for commodity confectionery.
- Natural Flavors:Botanical and fermentation-derived volatile compounds meeting EU Flavoring Regulation 1334/2008 natural substance definitions. German beverage manufacturers concentrate procurement here as clean-label portfolios displace artificial inventories.
- Fruit Flavors:Heat-stable citrus and berry profiles engineered for carbonated soft drink applications. Demand clusters in North American functional beverage production where repeat purchase rates depend on consistent sensory delivery across batch variations.
- Artificial Flavors:Synthetic molecules delivering standardized intensity at lower unit cost. Remains entrenched in price-sensitive confectionery channels where regulatory pressure lags beverage applications.
- Herbal Flavors:Adaptogenic and botanical positioning compounds for nootropic beverage lines. Steepest expansion trajectory as functional drink producers seek differentiation through ashwagandha, ginseng, and botanical blends.
Established volume favors fruit flavors; emerging adoption favors herbal flavors.
Application:
Margin tier separates premium-positioned functional beverages from commodity bakery and confectionery uses.
- Beverages:Aqueous matrices demanding complete dispersion below 300 microns with flavor stability across pasteurization and carbonation cycles. Carbonated and functional drink producers in Germany and Switzerland drive specification tightening.
- Dairy Products:Emulsion-compatible profiles resisting protein interaction and fat separation. Clean-label natural substitution accelerates as EU dairy processors reformulate under EFSA evaluation protocols.
- Confectionery:Heat-stable systems surviving high-temperature processing and extended shelf storage. Fruit profiles dominate volume though artificial alternatives retain share in private-label segments.
- Bakery Items:Oven-stable volatile retention through encapsulation and spray-dried delivery. Energy-intensive natural encapsulation compresses margins at mid-tier suppliers serving regional bakeries.
Premium positioning concentrates in beverages; cost engineering dominates confectionery.
End User:
Customer scale determines technical collaboration depth versus transactional procurement terms.
- Beverage Producers:Multinational conglomerates mandating integrated flavor creation labs co-located with production facilities. Procurement teams displace arm's-length compound purchasing with captive technical agreements.
- Food Manufacturers:Processed food exporters targeting India navigate BIS certification and FSSAI flavor standard complexity for market access.
- Restaurants:Foodservice operators sourcing concentrated flavor systems for beverage fountain and dessert applications.
- Home Consumers:Retail-packaged extracts and emulsions for baking and beverage preparation. Online retail channels expand access to specialty botanical profiles previously restricted to commercial supply.
Scale concentration favors beverage producers; fragmentation favors food manufacturers.
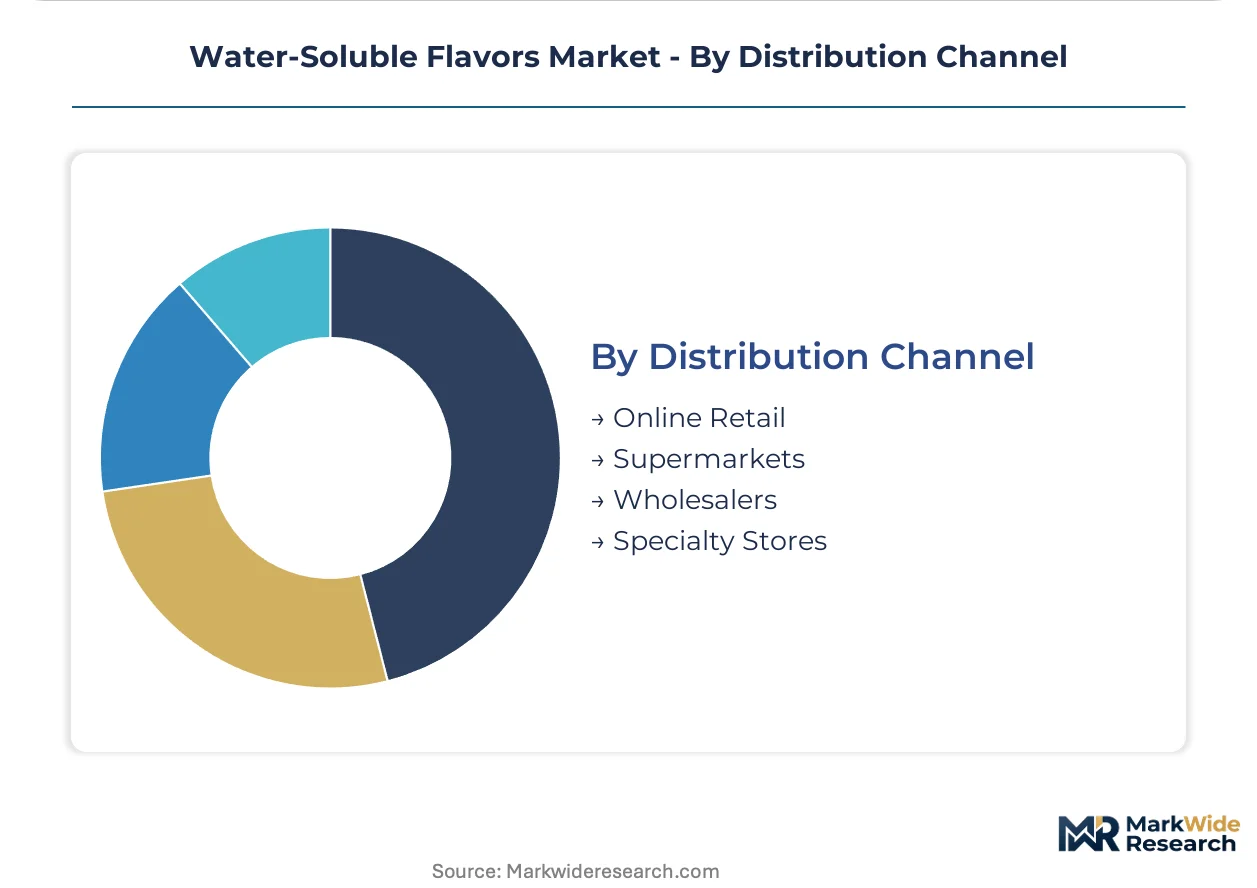
Distribution Channel:
Supply chain configuration separates direct-to-manufacturer compound distribution from retail intermediation.
- Wholesalers:Bulk compound distribution to regional food and beverage manufacturers. Toll manufacturing partnerships increasingly bypass traditional flavor house intermediaries for mid-tier producers.
- Online Retail:Direct-to-consumer and small-batch commercial supply of specialty extracts and botanical concentrates.
- Supermarkets:Mass-market retail placement of consumer-packaged flavor emulsions and baking extracts.
- Specialty Stores:Premium natural and organic flavor positioning for clean-label home baking and craft beverage preparation.
Procurement rationalization favors wholesalers; niche positioning favors specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in water-soluble flavors reveal Germany as the dominant net exporter of natural extracts, while the United States and India represent the largest import markets driven by beverage manufacturing expansion and processed food sector growth.
Germany
EU Flavoring Regulation 1334/2008 compliance mandates accelerate natural flavor substitution across carbonated and functional drink portfolios. The EU Green Deal bioeconomy incentives fund fermentation platform investments in biotechnology clusters. The beverage manufacturing corridor in Bavaria and Baden-Württemberg concentrates technical flavor houses co-located with production facilities.
United States
FDA food additive regulations under 21 CFR 172 govern new natural flavor approval timelines extending 24-36 months for petition requirements. The EPA's Clean Water Act discharge standards shape manufacturing compliance costs. Integrated flavor creation labs in California and New Jersey anchor North American beverage supply through captive technical agreements.
India
BIS certification requirements and FSSAI flavor standards add complexity for exporters targeting emerging processed food markets. The country's national food safety regulator enforces evolving natural flavor definitions that threaten harmonized product registration strategies. Maharashtra and Gujarat host regional food manufacturers navigating export pathway compliance.
Switzerland
Swissmedic and federal food safety frameworks align with EU Flavoring Regulation 1333/2008 through bilateral agreements. Premium beverage producers in Zurich and Basel adopt cell-culture extraction technology for vanilla and saffron profiles previously constrained by harvest volatility. Biotechnology clusters secure circular economy funding for fermentation-derived natural molecules.
Brazil
ANVISA flavor additive regulations govern permissible substance lists for beverage and confectionery applications. Citrus extract supply clusters expose formulators to climate-driven price spikes in São Paulo and Minas Gerais production zones. Regional craft producers increasingly seek toll manufacturing partnerships bypassing traditional flavor house intermediaries.
Water-Soluble Flavors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and fermentation technology. The vendor base concentrates around multinational flavor houses with captive biotechnology platforms and regional toll manufacturers serving mid-tier beverage producers. Three archetypes dominate: integrated flavor creation labs with co-located production, fermentation-derived natural molecule specialists, and asset-light toll compounding operations. M&A activity targets botanical extraction capacity, while strategic partnerships secure year-round supply consistency for clean-label formulations.
Within the integrated platform tier, Givaudan SA and International Flavors & Fragrances Inc. exemplify archetypes combining biotechnology platforms with beverage supply chain integration. Symrise AG occupies a position representing fermentation-derived natural molecule specialists that bypass agricultural supply volatility. These three entities anchor competitive positioning across European and North American manufacturing corridors where procurement teams mandate technical collaboration agreements replacing transactional supply contracts.
| Leading Market Players |
|---|
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Firmenich SA |
| Kerry Group plc |
| Takasago International Corporation |
| Sensient Technologies Corporation |
| Archer-Daniels-Midland Company |
| Nature's Flavors, Inc. |
| Others |
Value Network & Pricing Analysis
Botanical raw material concentration in Madagascar and Brazil exposes formulators to climate-driven price spikes that compress both margin structures at mid-tier producers and procurement strategies across German and North American beverage manufacturing corridors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium natural extracts command position based on EU Flavoring Regulation 1334/2008 certification and fermentation-derived provenance, while standard tiers compete on heat-stable citrus and berry consistency. Cost compression in economy artificial segments intensifies because spray-drying natural flavors demands forty percent more thermal input than synthetic alternatives. Mid-tier regional producers exhibit highest price sensitivity; multinational beverage conglomerates least.
Supply Chain Analysis
Export-control restrictions on biotechnology transfer limit cell-culture extraction platform diffusion beyond Swiss and German innovation clusters. Madagascar vanilla and Brazilian citrus supply concentration creates single-source vulnerability for natural extract procurement. Formulation inputs draw from fermentation-derived molecules, spray-dried encapsulation systems, and aqueous emulsion matrices. Distribution runs through captive technical agreements replacing arm's-length compound purchasing at multinational beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EU Flavoring Regulation 1334/2008 compliance timelines and FDA 21 CFR 172 petition requirements create switching-cost barriers that protect incumbent flavor houses.
For Market Incumbents: Build captive biotechnology moats through fermentation platform investments in German clusters qualifying for EU Green Deal bioeconomy funding. Secure botanical extraction capacity via toll manufacturing partnerships that bypass agricultural supply volatility. Counter cell-culture extraction entrants by accelerating EFSA dossier resubmissions ahead of reauthorization cycles.
For New Entrants and Emerging Players: Mid-market functional beverage producers in India seeking BIS certification alignment represent the most penetrable entry point. Regional craft carbonated drink manufacturers in Brazil's São Paulo corridor offer second white-space target. Pursue direct-to-beverage-compound distribution partnerships that displace traditional flavor house intermediaries.
For Investors and Strategic Acquirers: EFSA safety evaluation protocol tightening ahead of reauthorization cycles reshapes the acquisition landscape toward fermentation-derived natural molecule specialists. Five-to-ten year viability favors platform integrators with co-located flavor creation labs over component extraction plays. Monitor EFSA natural flavor substance list exclusions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Investment | EU Green Deal bioeconomy funding in German biotechnology clusters secures bypass of agricultural supply volatility. |
| Cell-Culture Extraction Scale-Up | Virtualized vanilla and saffron production compresses traditional spice trade margins while ensuring year-round supply. |
| Direct-to-Manufacturer Distribution | Toll manufacturing partnerships displace flavor house intermediaries for regional craft beverage producers. |
| Regulatory Dossier Resubmission | EFSA safety evaluation compliance ahead of reauthorization cycles protects legacy botanical extract formulations. |
| Integrated Flavor Creation Lab Expansion | Co-located technical collaboration agreements replace transactional supply contracts at multinational beverage conglomerates. |
Research Methodology
Operator-level perspectives from flavor creation chemists, beverage procurement directors, fermentation platform engineers, and regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined with secondary validation against EU Flavoring Regulation 1334/2008 implementation records, FDA 21 CFR 172 petition databases, FSSAI flavor standard circulars, and trade flow documentation from German and Brazilian customs authorities. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include natural versus artificial substance classification, heat stability performance tier, beverage versus dairy versus confectionery application matrix, and regional regulatory cluster alignment. CAGRs derived from volume trajectory analysis incorporating biotechnology platform adoption curves and clean-label substitution elasticity estimates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price volatility and energy cost trajectories would shift the trajectory. Forecasts reflect documented assumptions around EFSA reauthorization timing and FDA petition approval velocity. Material shifts in natural flavor definition harmonization between FDA, EFSA, and FSSAI jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Acerola Extracts Market