
 Beverage Flavoring Market | 2026-2036
Beverage Flavoring Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Flavoring Market Analysis
Flavor chemist talent pipelines in Western Europe is collapsing as universities shutter specialized fragrance and flavor programs, tightening the specialist labor pool that formulation houses depend upon. Givaudan S.A. leverages its captive training academies in Switzerland and Singapore to sustain proprietary workforce development. Kerry Group plc anchors its competitive position through backward integration into botanical extraction and dairy-derived flavor precursors.
Beverage flavoring encompasses the compounding of volatile aromatic molecules, essential oils, and taste modulators into standardized delivery systems, typically specified by flavor intensity measured in parts per million and solubility profiles tailored to aqueous or acidic matrices. The primary commercial purpose is to engineer consistent sensory experiences across carbonated, still, and alcoholic beverage production at industrial scale. Natural flavor types command premium positioning as CPG brands reformulate away from artificial additives, while liquid forms dominate high-volume manufacturing due to dosing precision and batch uniformity. Powder formats are gaining share in ready-to-mix and single-serve applications where logistics cost and shelf stability override mixing convenience.
FDA GRAS self-affirmation pathways and EFSA flavoring substance evaluations create divergent compliance burdens for suppliers operating across Atlantic markets, with the EU's stricter positive-list approach limiting molecular innovation relative to American notification frameworks. The F-Gas Regulation and REACH chemical registration requirements further constrain solvent-based extraction processes that supply natural flavor precursors. Stakeholders must monitor regulatory divergence between Washington and Brussels as a determinant of which flavor technologies achieve scalable market access.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing the permissible molecular palette for flavor houses, forcing simultaneous investment in natural extraction infrastructure and novel biotech-derived aroma compounds to maintain sensory performance without synthetic additives.
Growth Catalysts
- EU Green Deal chemical phase-outs:REACH restrictions on petrochemical solvents are accelerating capital flows into enzymatic and fermentation-based flavor biomanufacturing, creating first-mover advantages for suppliers with pilot-scale bioreactors operational.
- Functional beverage end-use expansion:Adaptogen and nootropic drink categories are specifying flavor systems with masking capabilities for bitter bioactive compounds, opening premium specification tiers for modulator technologies.
- Munich-Cologne innovation corridor concentration:Germany's beverage R&D cluster is generating concentrated demand for rapid-prototyping flavor services, pulling regional formulation capacity and technical sales presence northward.
Market Restraints
- Botanical raw material volatility:Climate stress on vanilla orchids in Madagascar and citrus crops in Spain is amplifying price swings for natural flavor precursors, compressing gross margins on clean-label product lines.
- Specialist labor scarcity:University closures of flavor chemistry programs across France, the Netherlands, and the UK are constricting the pipeline of trained flavorists, extending project timelines and inflating compensation costs.
- F-Gas Regulation solvent constraints:The EU's phasedown of hydrofluorocarbon extraction solvents is forcing process revalidation for natural flavor houses dependent on traditional volatile recovery systems.
Strategic Opportunities
- India beverage manufacturing expansion:FSSAI modernization and PLI scheme incentives for food processing are attracting multinational flavor houses to establish local compounding facilities serving South Asian markets.
- Precision fermentation aroma molecules:Convergence of synthetic biology with beverage formulation is enabling cost-parity production of rare natural-identical compounds previously extractable only from scarce botanicals.
- Direct-to-brand digital flavor platforms:Cloud-based sensory profiling tools are disintermediating traditional distributor relationships, allowing mid-size beverage startups to specify custom flavor systems without minimum volume commitments.
Industry Challenges
- Cross-Atlantic regulatory divergence:FDA GRAS self-affirmation pathways permit faster molecular innovation than EFSA's positive-list system, forcing dual-track compliance architectures that duplicate toxicology and safety documentation investments.
- Legacy equipment integration:Automated dosing systems for liquid flavor delivery require retrofitting of existing batch processing lines, generating capital intensity and production downtime for mid-volume manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Flavoring Market |
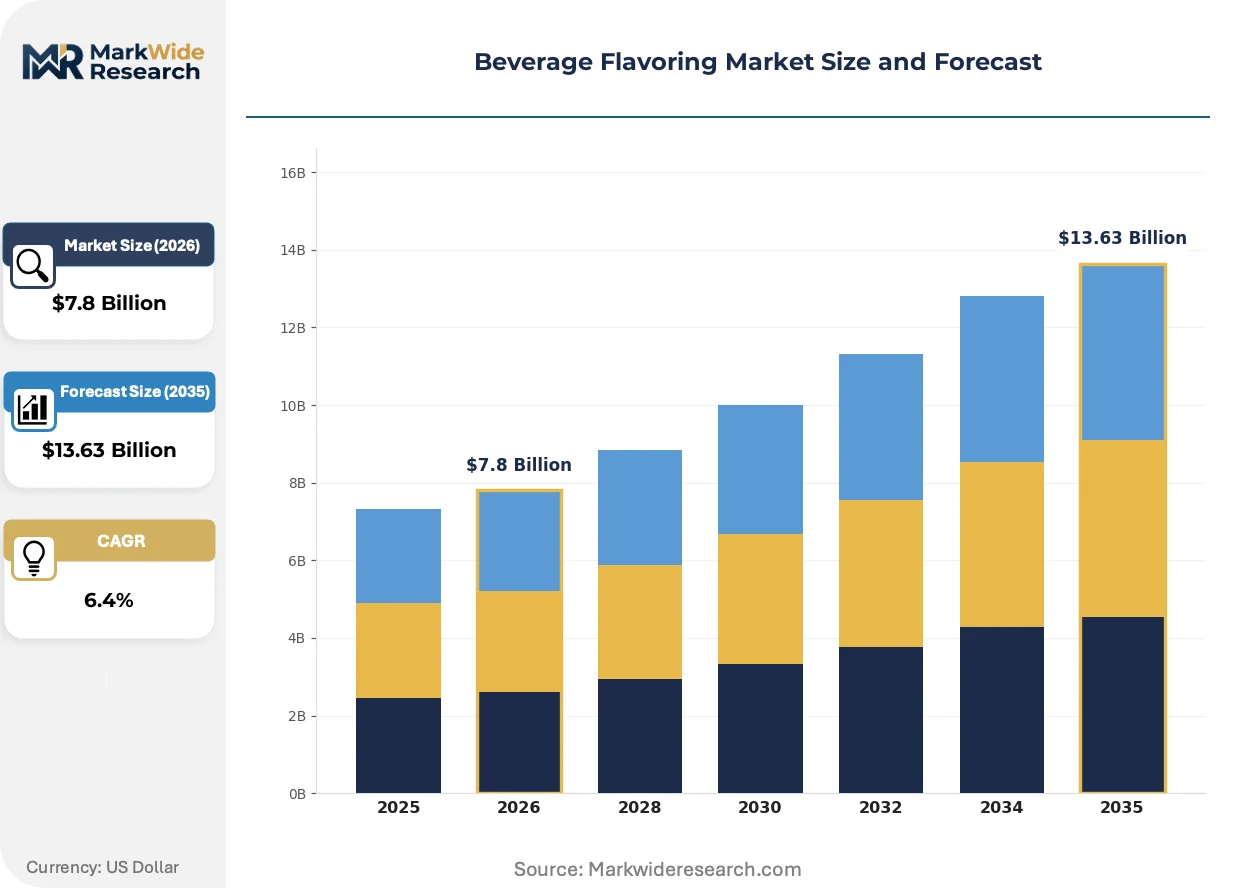
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Natural, Artificial, Organic, Concentrated End User: Manufacturers, Retailers, Bartenders, Home Users Application: Sodas, Cocktails, Energy Drinks, Tea Form: Liquid, Powder, Extract, Emulsion |
| Companies Covered | Givaudan S.A., International Flavors & Fragrances Inc., Kerry Group plc, Sensient Technologies Corporation, ADM, dsm-firmenich, Symrise AG, Takasago International Corporation, MB-Holding GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Flavoring Market Emerging Trajectories
Biotechnology-derived flavor precursors and AI-assisted sensory mapping are compressing development cycles while regulatory chemistry restrictions are fragmenting formulation approaches across Atlantic markets.
Precision fermentation platforms for producing natural-identical aromatic molecules is bifurcating the supply base between petrochemical-derived synthetic houses and biotech-enabled specialists. Functional beverage manufacturers in North America and Western Europe are adopting these inputs at pilot scale, with several brands completing consumer acceptance testing. The technology is bifurcating cost structures and supplier qualification criteria, as fermentation-derived materials command organic-compatible positioning despite energy-intensive upstream processing.
EFSA's systematic re-evaluation of flavoring substances under the Union List is tightening permissible thresholds for several historically common molecules. Flavor houses operating across EU markets face reformulation mandates for established beverage brands, triggering portfolio consolidation around highest-volume approved compounds. Carbonated soft drink categories with legacy flavor profiles are most affected, with several major suppliers accelerating natural replacement programs ahead of regulatory deadlines.
Direct specification relationships between beverage startups and flavor technology platforms are displacing traditional distributor-mediated procurement in ready-to-drink segments. Digital sensory configuration tools allow brands to iterate flavor profiles without physical sample shipping, compressing development timelines from months to weeks. This pattern is most visible in the US and UK craft beverage sectors, where small-batch manufacturers prioritize speed-to-market over volume-negotiated pricing.
Beverage Flavoring Market Segmentation
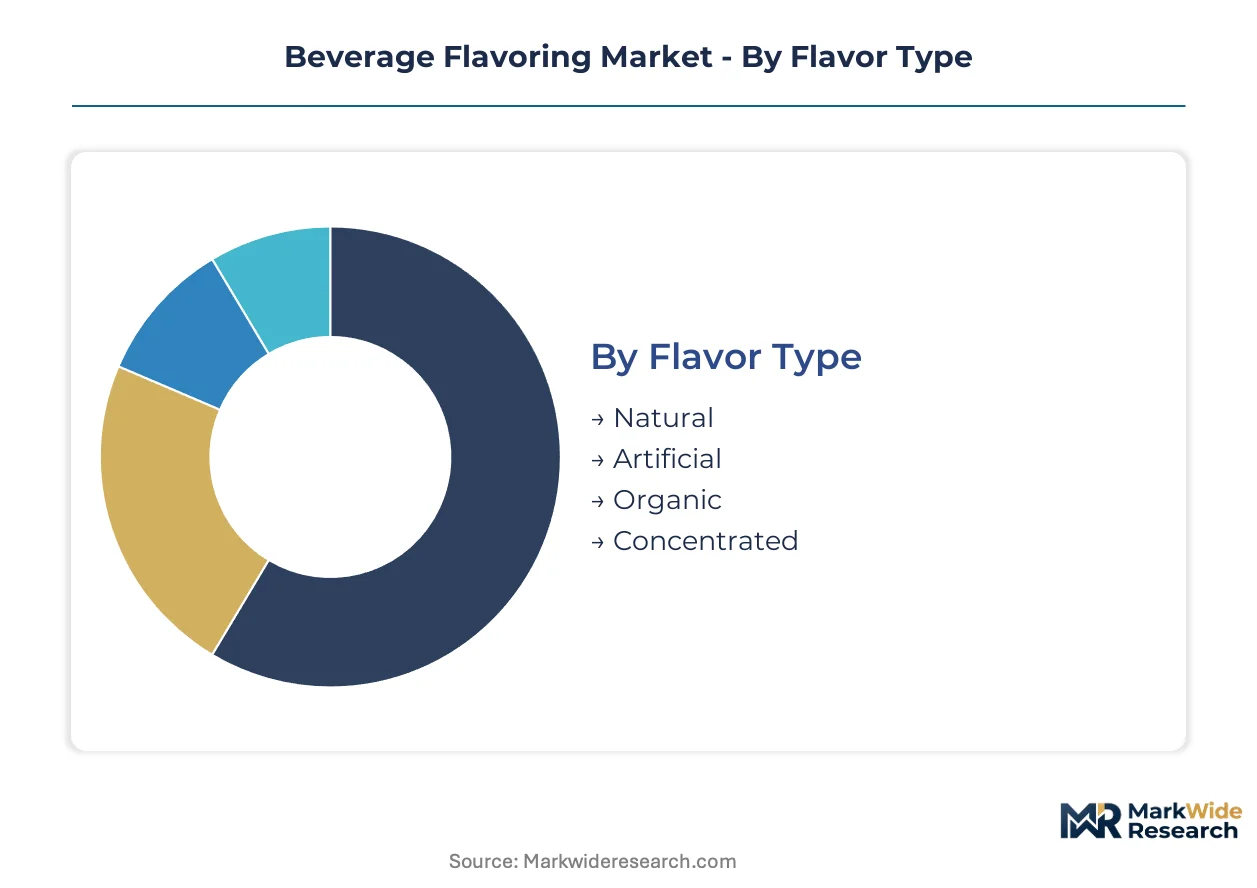
Segmentation in beverage flavoring reveals how formulation requirements diverge across regulatory environments, end-use applications, and manufacturing scale. Understanding these divisions exposes where substitution pressures and margin compression concentrate most intensely.
Flavor Type:
Substitution pressure from clean-label mandates weighs most heavily on artificial segments, while natural and organic categories face supply-side constraints from botanical scarcity and extraction solvent restrictions.
- Natural:Derived from botanical, animal, or microbial sources through physical, enzymatic, or microbiological processes. Demand concentrates in Germany's Munich-Cologne corridor where functional beverage startups specify these inputs for EU Green Deal compliance, though Madagascar vanilla and Spanish citrus supply volatility compresses margins.
- Artificial:Synthesized from petrochemical precursors with standardized molecular purity and intensity measured in parts per million. Reformulation mandates from EFSA's Union List re-evaluations are forcing accelerated replacement programs in carbonated soft drinks, particularly where legacy profiles depend on historically common molecules now facing threshold restrictions.
- Organic:Certified natural flavors meeting USDA or EU organic processing standards with full traceability documentation.
- Concentrated:High-intensity flavor systems with reduced water content for logistics efficiency in long-distance supply chains.
Natural flavor types retain volume leadership; organic variants hold the steepest expansion curve as certification premiums justify input costs for positioned brands.
End User:
Cost tier stratification separates industrial-scale procurement from small-volume specification relationships, with digital platforms now enabling direct access for previously excluded customer segments.
- Manufacturers:Industrial beverage producers operating automated batch processing lines with precise dosing requirements and batch uniformity specifications. Procurement concentrates among functional drink manufacturers in North America and Western Europe who are accelerating clean-label flavor system adoption, with minimum volume commitments traditionally locking out mid-tier players.
- Retailers:Private-label and co-packing operations sourcing finished flavor systems for branded distribution. Cloud-based sensory profiling tools are disintermediating traditional distributor relationships, allowing these entities to specify custom systems without volume thresholds previously required.
- Bartenders:On-premise mixology professionals seeking small-batch and craft flavor components for cocktail programs.
- Home Users:Consumer-direct purchasers of ready-to-mix formats for domestic beverage preparation.
Manufacturers command absolute volume share; retailers are climbing the fastest as digital procurement platforms expand accessible specification tiers.
Application:
Application segmentation tracks how flavor performance requirements vary across pH matrices, carbonation levels, and bioactive compound masking demands.
- Sodas:Carbonated soft drinks requiring flavor stability in acidic, pressurized environments with legacy profiles most affected by EFSA reformulation mandates. Several major suppliers are accelerating natural replacement programs ahead of regulatory deadlines, with established brands facing the steepest technical challenges in maintaining sensory parity.
- Energy Drinks:Functional beverages incorporating caffeine, taurine, and adaptogenic compounds demanding sophisticated bitter-masking modulator technologies. North American and Western European manufacturers are specifying premium flavor systems with these capabilities, opening higher-margin specification tiers for specialized suppliers.
- Cocktails:Alcoholic mixed drinks with flavor solubility requirements in ethanol-water matrices.
- Tea:Still and ready-to-drink tea applications where heat stability and tannin interaction determine performance.
Sodas retain volume leadership; energy drinks hold the steepest expansion curve as functional positioning commands formulation investment.
Form:
Form selection reflects trade-offs between dosing precision, logistics cost, shelf stability, and existing equipment compatibility.
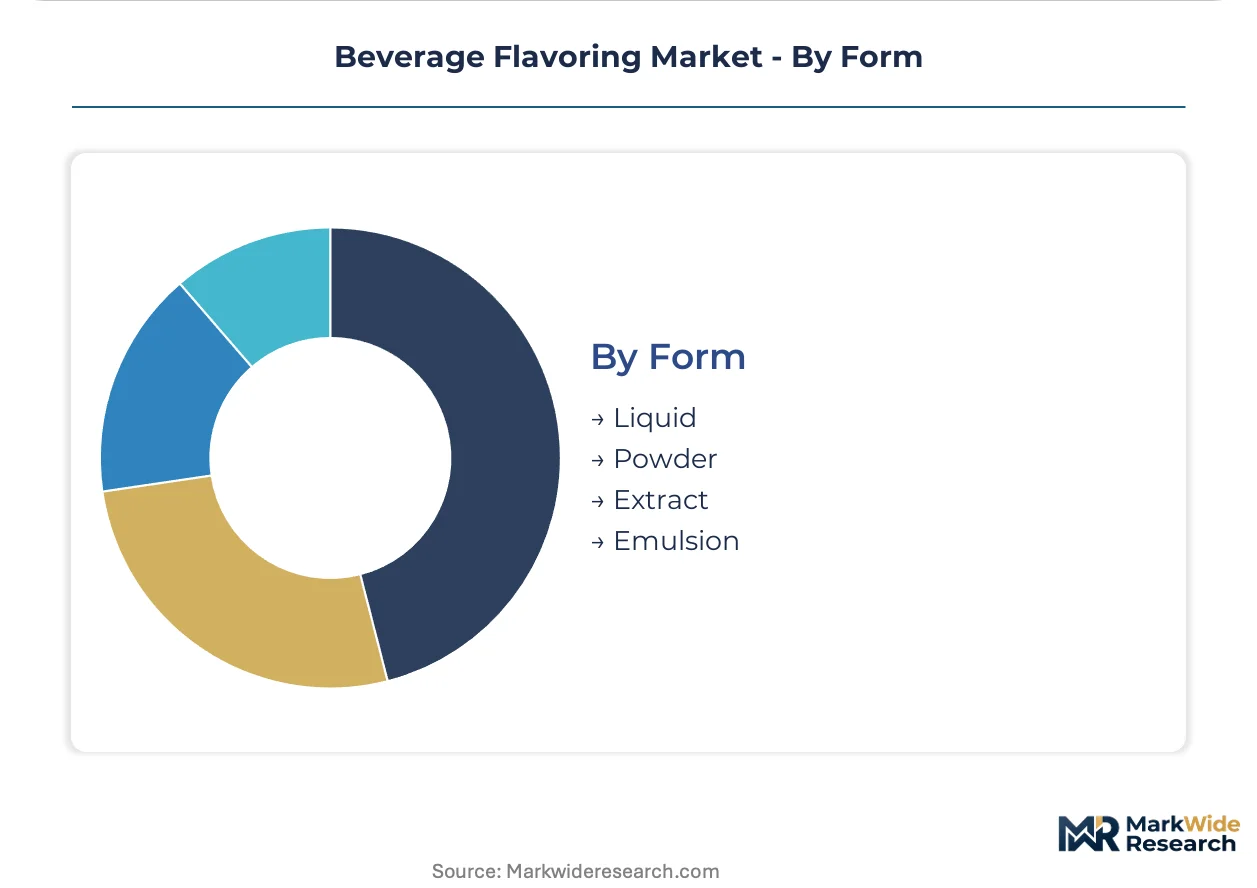
- Liquid:Aqueous or solvent-based delivery systems enabling precise volumetric dosing and rapid batch homogenization. High-volume manufacturing in automated facilities favors this format for uniformity, though F-Gas Regulation constraints on hydrofluorocarbon extraction solvents are forcing process revalidation for natural liquid flavor houses.
- Powder:Spray-dried or encapsulated formats with extended shelf stability and reduced shipping weight. Ready-to-mix and single-serve applications in India and other South Asian markets are gaining share where logistics costs and storage duration override mixing convenience advantages of liquid alternatives.
- Extract:Concentrated botanical preparations with defined aromatic compound profiles.
- Emulsion:Oil-in-water dispersions for lipophilic flavor compounds requiring stability in aqueous matrices.
Liquid formats retain volume leadership; powder variants are expanding most quickly in ready-to-mix segments where distribution economics favor stability over convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German functional beverage startups prioritize clean-label natural systems for EU Green Deal compliance, while US manufacturers exploit FDA GRAS flexibility for faster molecular innovation. Indian and Chinese markets favor powder formats for logistics efficiency in dispersed distribution networks.
Germany
Munich-Cologne corridor concentrates demand for rapid-prototyping flavor services as functional drink manufacturers accelerate procurement. EFSA's Union List re-evaluations and REACH chemical registration constrain permissible additives, forcing reformulation of legacy carbonated profiles. Bavaria anchors the innovation cluster with technical sales presence pulling regional formulation capacity northward.
United States
Energy drink and adaptogen categories specify premium flavor systems with bitter-masking modulator technologies. FDA GRAS self-affirmation pathways permit faster molecular innovation than European frameworks, enabling pilot-scale deployment of precision fermentation aroma molecules. Craft beverage startups in distributed metro markets adopt direct-to-brand digital flavor platforms.
India
Ready-to-mix and single-serve applications drive powder format expansion where logistics costs and shelf stability override liquid convenience. FSSAI modernization and PLI scheme incentives attract multinational flavor houses to establish local compounding facilities. Maharashtra and Gujarat host emerging manufacturing clusters serving South Asian markets.
France
University closures of specialized fragrance and flavor programs constrict talent pipelines, extending project timelines for formulation houses. ANSM and ECHA enforcement of F-Gas Regulation phasedowns forces process revalidation for solvent-dependent natural extraction operations. Paris-based flavor houses face specialist labor scarcity alongside regulatory chemistry restrictions.
Switzerland
Captive training academies sustain proprietary workforce development as Western European talent pools contract. Swissmedic and EFSA alignment maintains strict additive thresholds while enabling premium positioning for natural-identical compounds. Zurich and Geneva anchor technical centers supplying formulation expertise across continental markets.
Beverage Flavoring Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around backward integration capabilities and biotech-enabled production platforms. The upper tier commands formulation scale and regulatory navigation expertise across divergent Atlantic compliance architectures. Mid-tier specialists occupy precision fermentation, botanical extraction, and digital sensory configuration niches. Competitive moves concentrate on M&A for captive supply chains and capacity expansion in enzymatic biomanufacturing.
Within the integrated leader tier, Givaudan S.A. and Kerry Group plc exemplify divergent strategic archetypes—Swiss precision in proprietary workforce development versus Irish backward integration into botanical and dairy-derived precursors. Sensient Technologies Corporation occupies a position among North American specialists leveraging color-and-flavor combined expertise. These three entities represent the spectrum from full-stack formulation houses to focused technology platforms, each anchoring distinct competitive vectors in a market bifurcating between petrochemical-derived synthetics and biotech-enabled natural-identical production.
| Leading Market Players |
|---|
| Givaudan S.A. |
| International Flavors & Fragrances Inc. |
| Kerry Group plc |
| Sensient Technologies Corporation |
| ADM |
| dsm-firmenich |
| Symrise AG |
| Takasago International Corporation |
| MB-Holding GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at precision fermentation facilities in Switzerland and Singapore shapes price floors for natural-identical aroma compounds, compressing margins for synthetic houses while elevating biotech-enabled suppliers. EFSA's Union List re-evaluations and REACH solvent restrictions simultaneously constrain supply alternatives and reinforce premium positioning for compliant inputs.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational flavor houses and functional beverage manufacturers, insulating premium tiers from spot volatility in Madagascar vanilla and Spanish citrus markets. Price differentiation rests on certification grade—USDA Organic and EU organic processing standards command substantial premiums over conventional natural—and volume scale, with automated dosing system compatibility adding further tier separation. Cost compression in artificial flavor segments is intensifying because EFSA reformulation mandates accelerate replacement timelines. Small-batch craft beverage startups exhibit highest price sensitivity, while energy drink manufacturers with bitter-masking requirements demonstrate lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
Strategic stockpiling of botanical precursors prevails among European natural flavor houses confronting F-Gas Regulation phasedowns and climate-stressed vanilla orchid harvests. Geographic supply concentration centers on Madagascar for vanilla, Spain and Italy for citrus essential oils, and India for spice-derived aromatic compounds. Raw material dependencies encompass hydrofluorocarbon extraction solvents, enzymatic processing agents, and fermentation feedstocks. Single-source vulnerability in Madagascar vanilla orchids exposes formulators to acute price spikes. Distribution runs through regional compounding facilities serving the Munich-Cologne corridor, with direct-to-brand digital platforms disintermediating traditional distributor relationships in North American craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough driven by EFSA's systematic flavoring substance re-evaluations, which forced inventory destocking and reformulation investment that now converts to replacement demand.
For Market Incumbents: Secure captive supply chains for botanical precursors through backward integration into extraction operations in India and East Africa, insulating margin positions from Madagascar vanilla volatility. Accelerate precision fermentation capacity additions in Switzerland and Singapore to defend against emerging biotech specialists exploiting regulatory chemistry restrictions. For New Entrants and Emerging Players: Lead with digital sensory configuration platforms targeting mid-tier craft beverage startups in the US and UK, where minimum volume commitments exclude them from incumbent distributor relationships. Penetrate India's ready-to-mix powder segment through FSSAI-compliant local compounding facilities, leveraging PLI scheme incentives and logistics-cost advantages over liquid imports. For Investors and Strategic Acquirers: Precision fermentation technology platforms with pilot-scale bioreactors operational represent the highest-conviction acquisition archetype, given their first-mover positioning as REACH petrochemical solvent restrictions tighten. Monitor EFSA Union List publication schedules as inflection indicators—accelerated additive delistings would trigger consolidation demand for natural-replacement capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables cost-parity production of rare natural-identical compounds previously extractable only from scarce botanicals. |
| Captive Botanical Extraction | Secures supply chains for Madagascar vanilla and Spanish citrus precursors amid climate volatility. |
| Digital Sensory Platform Launch | Disintermediates distributor relationships for mid-tier craft beverage startups requiring rapid prototyping. |
| EFSA Compliance Certification | Accelerates natural replacement programs ahead of Union List reformulation mandates for carbonated soft drinks. |
| India Compounding Facility Expansion | Captures powder format demand in South Asian markets where FSSAI modernization attracts multinational investment. |
Methodological Framework
The analysis maps natural extraction infrastructure, precision fermentation platforms, synthetic production facilities, and digital sensory configuration tools, each validated through flavor chemists, procurement directors at functional beverage manufacturers, regulatory affairs specialists, and technical sales executives. Primary interviews combined with secondary validation from EFSA Union List publications, REACH registration databases, FSSAI modernization directives, and customs trade records. Bottom-up facility capacity assessments triangulated against top-down consumption estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled flavor type, end-user scale tier, application matrix requirements, and form factor logistics economics. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers. Industry-specific forecast inputs encompassed EFSA re-evaluation timelines and F-Gas Regulation phasedown schedules.
Forecasts assume regulatory continuity in EU REACH and F-Gas frameworks, FDA GRAS notification pathways, and FSSAI modernization trajectories; material policy shifts would require re-modeling. Revision becomes warranted when botanical supply disruption indices or precision fermentation yield improvements cross thresholds altering cost-parity timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market