
 Smoked Dextrose Market | 2026-2036
Smoked Dextrose Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Dextrose Market Analytics
Food-grade pyrolysis specification upgrades is redrawing competitive boundaries in smoked dextrose supply. Roquette Frères S.A. leverages its starch refining infrastructure to secure consistent dextrose feedstock for smoke infusion processes. Kerry Group anchors its position through specialized savory flavor systems that integrate smoked dextrose into turnkey seasoning blends. Cargill Incorporated controls broad agricultural sourcing networks that stabilize raw material flows for smoke-derived ingredients.
Smoked dextrose is a carbohydrate-based flavor carrier produced through controlled pyrolysis of dextrose monohydrate, yielding phenolic and carbonyl compounds that impart smoky aroma at concentrations between 0.1% and 2.0% by weight in finished formulations. Powder and liquid variants dominate current production volumes, with powder formats commanding stronger positions in dry seasoning applications due to extended shelf stability and ease of blending. Bakery and snack applications represent the most active demand channels, as manufacturers reformulate traditional smoked ingredients to reduce sodium and eliminate nitrite-curing associations.
FDA food additive regulations and the EU's Flavouring Regulation (EC) No 1334/2008 govern smoke condensate and pyroligneous acid derivatives, directly constraining which thermal decomposition products qualify for food-grade smoked dextrose. BIS standards in India and China's SAMR food safety protocols are tightening contaminant limits for polycyclic aromatic hydrocarbons in smoke-flavored ingredients. Stakeholders must monitor evolving maximum residue levels for benzo(a)pyrene and related compounds as regulatory divergence between jurisdictions intensifies compliance complexity.
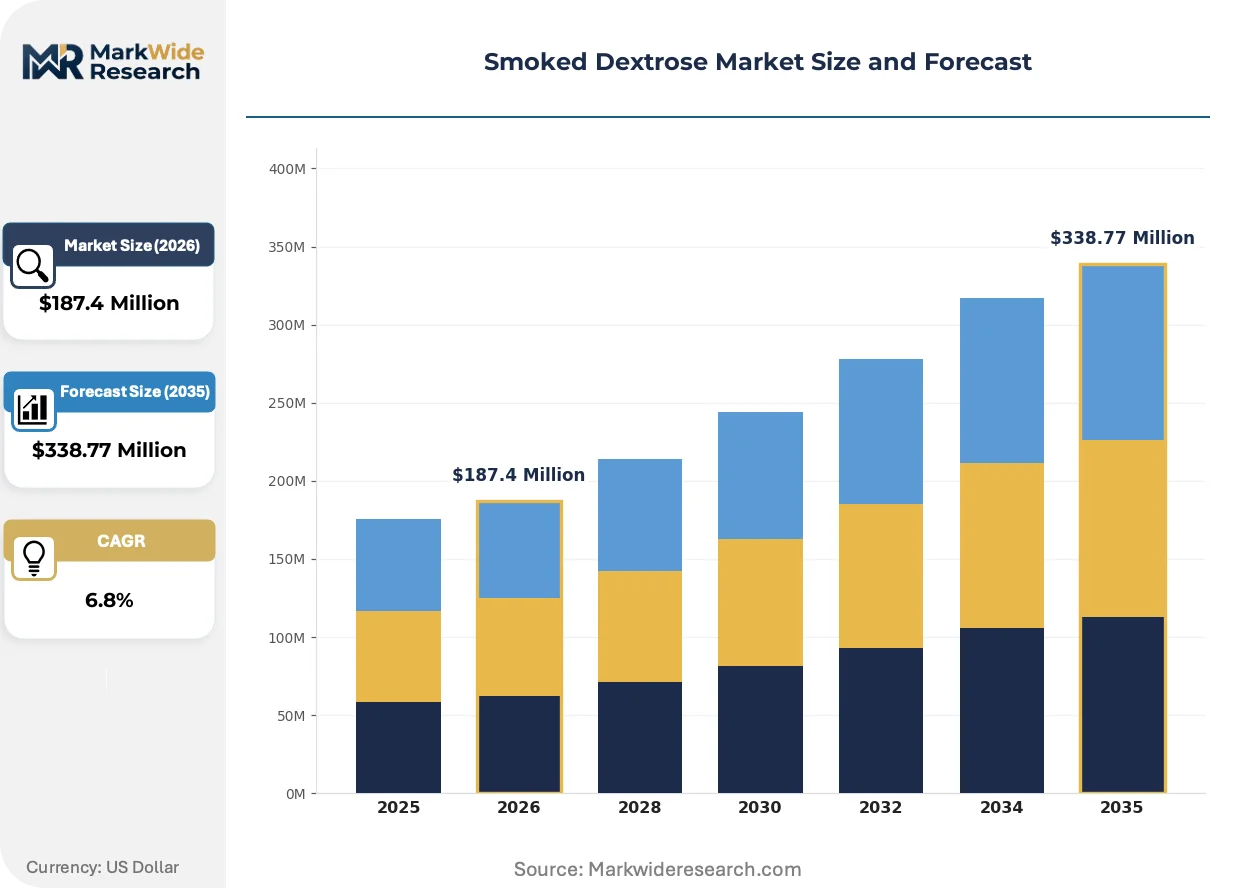
Market Dynamics
Clean-label reformulation mandates are compressing traditional smoke flavor categories, forcing carbohydrate-based carriers into center-stage positions within savory seasoning portfolios. Pyrolysis control technology upgrades now determine which suppliers qualify for food-grade certification.
Growth Catalysts
- EU Flavouring Regulation (EC) No 1334/2008:Strict purity benchmarks for smoke condensates accelerate food-grade dextrose substitution for liquid smoke extracts in meat-alternative formulations.
- Snack seasoning manufacturers:Sodium reduction targets drive adoption of smoked dextrose as a flavor-intensifying carrier that reduces salt dependency without taste compromise.
- Controlled pyrolysis methods:Precision temperature protocols enable consistent phenolic compound profiles that meet pharmaceutical-grade contamination thresholds.
Market Restraints
- Maize price volatility:Dextrose monohydrate feedstock costs fluctuate with agricultural commodity cycles, compressing margin structures for smoke-infused ingredient specialists.
- German production concentration:Pyrolysis capacity clusters in Central European industrial zones, creating geographic supply vulnerability for North American buyers.
- Liquid smoke substitutes:Established pyroligneous acid suppliers defend entrenched positions in traditional meat processing through decades-long customer relationships.
Strategic Opportunities
- India FSSAI pathway:Emerging clean-label snack markets lack domestic smoked dextrose production, creating first-mover advantages for importers meeting BIS contaminant standards.
- Plant-based seafood:Smoke-flavored carbohydrate carriers address taste authenticity gaps in algae-protein and mycoprotein analogs where traditional curing is impossible.
- Carbon accounting integration:EU Green Deal supply-chain disclosure rules favor pyrolysis processes with renewable energy inputs, rewarding early decarbonization investments.
Industry Challenges
- PAH analytical capability:Polycyclic aromatic hydrocarbon testing at parts-per-billion precision requires capital-intensive chromatography infrastructure that mid-scale producers struggle to fund.
- Legacy seasoning system integration:Dry-blend manufacturers face workflow reconfiguration costs when substituting liquid smoke dosing with powdered dextrose handling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Dextrose Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granulated, Liquid, Syrup Application: Beverages, Snacks, Sauces, Bakery End User: Food Manufacturers, Restaurants, Retail, Catering Services Packaging Type: Bags, Jars, Bulk Containers, Sachets |
| Companies Covered | Red Arrow International LLC, Roquette Frères S.A., Kerry Group, Ingredion Incorporated, Tate & Lyle PLC, Givaudan SA, Cargill Incorporated, Henning Gesellschaft für Nahrungsmitteltechnik mbH, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Dextrose Market Evolving Landscape
Precision pyrolysis engineering is fragmenting the smoke flavor supply base into technology-tiered segments, separating certified food-grade producers from industrial chemical suppliers. This bifurcation accelerates as downstream buyers consolidate approved vendor lists.
Continuous-flow pyrolysis reactors with real-time temperature feedback loops are displacing batch kiln systems in commercial smoked dextrose manufacturing. Snack seasoning houses in Germany and the Netherlands adopt these systems to secure consistent benzo(a)pyrene levels below 0.5 micrograms per kilogram. The technology is displacing artisanal smoke houses from clean-label supply chains entirely.
REACH authorization requirements for pyrolysis-derived substances tighten substance-by-substance scrutiny across European manufacturing zones. EFSA scientific opinions on smoke flavor primary products now demand expanded toxicological datasets, extending regulatory timelines by eighteen to thirty-six months. Smoked dextrose categories with established safety dossiers capture displaced volume from newly restricted liquid smoke fractions.
Direct procurement relationships between snack manufacturers and pyrolysis operators are compressing traditional flavor house intermediaries. Large seasoning compounders in North America now specify smoked dextrose grades directly, bypassing integrated flavor system suppliers. This pattern concentrates most visibly in private-label snack production, where cost transparency pressures exceed brand-guarding considerations.
Smoked Dextrose Market Segmentation
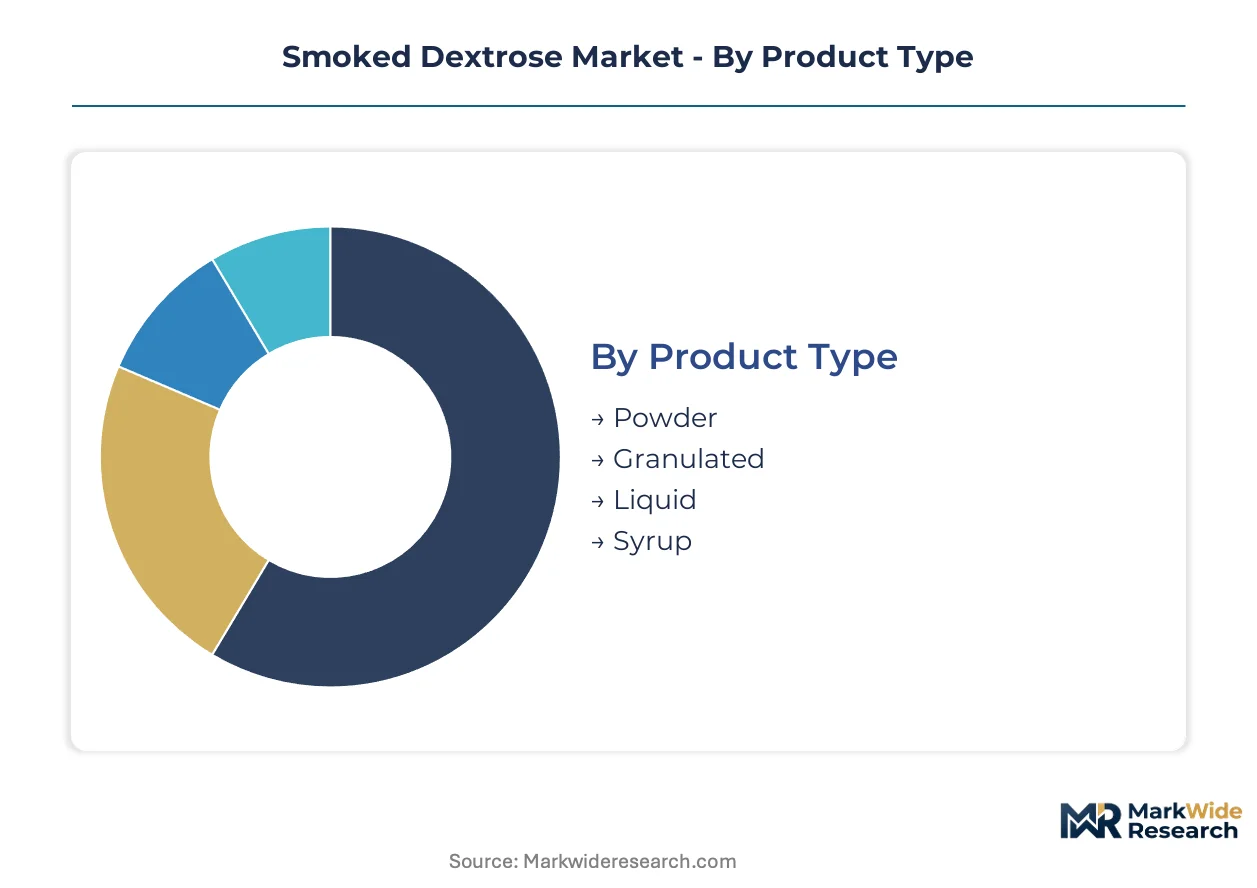
Segmentation in smoked dextrose reveals how pyrolysis-derived carriers penetrate distinct supply channels. Product format determines handling infrastructure, while end-user scale dictates certification requirements and procurement protocols.
Product Type:
Powder and liquid variants flow through divergent distribution channels, with dry formats dominating seasoning house supply chains and liquid concentrates serving beverage and sauce manufacturers directly.
- Powder:Fine-particle dextrose monohydrate infused through controlled pyrolysis, offering extended shelf stability and homogeneous blending in dry seasoning matrices. Snack manufacturers in Germany and the Netherlands specify powder grades below 0.5 micrograms per kilogram benzo(a)pyrene for clean-label meat alternatives.
- Liquid:Aqueous suspensions of pyrolyzed dextrose compounds enabling precise dosing in pumped sauce systems and beverage flavor lines. Beverage compounders favor liquid formats for rapid dissolution and consistent phenolic compound distribution without dusting hazards.
- Granulated:Coarse-crystal carriers with reduced surface area, suited for coarse-grind seasoning applications where flowability outweighs rapid solubility.
- Syrup:High-viscosity concentrates targeting artisanal sauce producers and small-batch bakery operations requiring measured pour control.
By volume, powder leads. By growth pace, liquid concentrates are expanding most quickly in beverage reformulation pipelines.
Application:
Application segmentation tracks where sodium-reduction mandates and nitrite-avoidance trends concentrate demand for smoke-flavored carbohydrate carriers.
- Snacks:Potato chip, popcorn, and extruded snack seasonings represent the dominant demand channel, with manufacturers substituting smoked dextrose for liquid smoke to eliminate solvent residues and achieve clean-label positioning.
- Sauces:Barbecue and savory sauce formulations leverage smoked dextrose for flavor depth without the labeling complications of pyroligneous acid derivatives.
- Bakery:Smoke-tinged breads and savory pastries adopt dextrose carriers for controlled aroma release during baking cycles.
- Beverages:Craft cocktail mixes and smoke-flavored non-alcoholic drinks represent an emerging application with specialized solubility requirements.
Snacks command the largest revenue share. Beverage applications are climbing the fastest as mixology trends migrate to packaged formats.
End User:
End-user scale determines whether procurement flows through distributor networks or direct pyrolysis operator relationships.
- Food Manufacturers:Large-scale seasoning compounders and private-label snack producers drive bulk procurement, often specifying contaminant thresholds directly with pyrolysis facilities to bypass flavor house markups.
- Restaurants:Chef-driven kitchens and chain restaurant R&D departments source smoked dextrose for menu development and signature sauce programs.
- Retail:Specialty food retailers and direct-to-consumer spice brands package smoked dextrose for home cooking enthusiasts.
- Catering Services:Large-volume event caterers utilize smoked dextrose for consistent smoke flavor in off-site preparation where traditional smoking equipment is impractical.
Food manufacturers dominate procurement volume. Retail channel development is gaining share fastest as consumer packaged goods brands expand specialty seasoning portfolios.
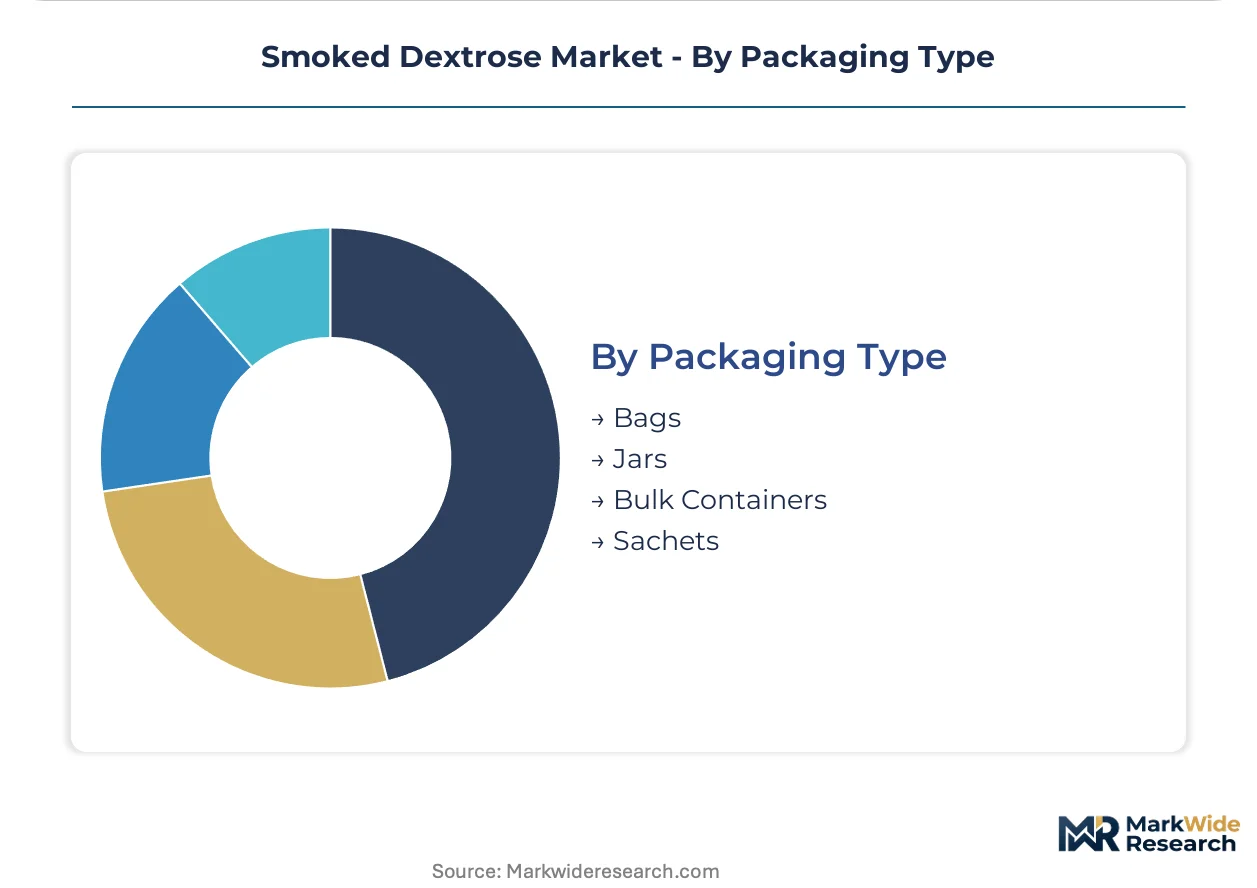
Packaging Type:
Packaging configuration aligns with end-user handling infrastructure and inventory velocity requirements.
- Bulk Containers:Intermediate bulk containers and drum formats serve high-volume seasoning houses with pneumatic conveying systems.
- Bags:Multi-wall paper and polymer bags balance moisture protection with manual handling feasibility for mid-scale manufacturers.
- Jars:Consumer-facing glass and PET containers target retail and restaurant pantry segments.
- Sachets:Single-use portion packs support foodservice distribution and sampling programs.
Bulk containers lead by tonnage. Sachet formats are expanding most rapidly in foodservice trial programs and airline catering supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyrolysis capacity clusters disproportionately in Germany and the Netherlands, creating geographic chokepoints for clean-label smoke flavor supply chains. Snack seasoning manufacturers in North America and Asia-Pacific source heavily from these Central European hubs, exposing procurement networks to trans-Atlantic logistics volatility.
United States
Snack seasoning compounders in Chicago and Minneapolis drive powder-grade procurement for sodium-reduced chip and popcorn formulations. FDA food additive regulations constrain which pyrolysis-derived phenolic compounds qualify for GRAS status, filtering supplier qualification. Private-label producers in the Midwest are establishing direct pyrolysis operator relationships to bypass traditional flavor house markups.
Germany
Meat-alternative manufacturers in Berlin and Hamburg seek authentic smoke notes without nitrite-curing associations, accelerating dextrose carrier substitution. EFSA scientific opinions on smoke flavor primary products demand expanded toxicological datasets, extending regulatory timelines for new entrants. Continuous-flow pyrolysis reactors with real-time temperature feedback dominate production zones around Cologne.
Netherlands
Beverage reformulation pipelines in Amsterdam and Rotterdam favor liquid smoked dextrose concentrates for craft cocktail mix applications. REACH authorization requirements for pyrolysis-derived substances tighten substance-by-substance scrutiny across Dutch manufacturing zones. Precision pyrolysis engineering capabilities concentrate in Eindhoven's food technology corridor.
India
Emerging clean-label snack markets in Mumbai and Delhi lack domestic smoked dextrose production, creating first-mover advantages for importers meeting BIS contaminant standards. FSSAI pathway development for smoke-flavored carbohydrate carriers remains underdefined, delaying local manufacturing investment. Mid-scale seasoning houses in Gujarat pilot powder-grade imports for regional savory snack brands.
China
SAMR food safety protocols are tightening polycyclic aromatic hydrocarbon limits for smoke-flavored ingredients, aligning with international purity benchmarks. Shanghai and Guangzhou-based sauce manufacturers evaluate dextrose carriers to replace liquid smoke in barbecue formulations. Dual carbon goals pressure pyrolysis operators to document renewable energy inputs for EU-facing export certifications.
Smoked Dextrose Market Competitive Landscape
Concentration sits with diversified ingredient conglomerates controlling starch refining infrastructure and pyrolysis certification capabilities. The vendor base separates into three functional tiers: integrated agricultural processors with captive dextrose supply, specialized savory flavor houses with turnkey seasoning integration, and regional pyrolysis operators serving niche geographic markets. Dominant competitive moves include backward integration into dextrose monohydrate feedstock production and strategic partnerships with snack manufacturers seeking direct procurement relationships.
Within the integrated agricultural processor tier, Roquette Frères S.A., Cargill Incorporated, and Archer Daniels Midland Company exemplify archetypes leveraging broad sourcing networks to stabilize raw material flows. Kerry Group and Givaudan SA occupy positions as specialized savory flavor system integrators. Red Arrow International LLC and Henning Gesellschaft für Nahrungsmitteltechnik mbH represent regional pyrolysis specialists with concentrated European production footprints.
| Leading Market Players |
|---|
| Red Arrow International LLC |
| Roquette Frères S.A. |
| Kerry Group |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Givaudan SA |
| Cargill Incorporated |
| Henning Gesellschaft für Nahrungsmitteltechnik mbH |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
EU Flavouring Regulation (EC) No 1334/2008 gates both supply qualification and price differentiation simultaneously, as food-grade pyrolysis certification separates certified producers from industrial chemical suppliers. Benzo(a)pyrene thresholds below 0.5 micrograms per kilogram command premium positioning, while uncertified batches face exclusion from clean-label procurement channels entirely.
Pricing Analysis
EU Flavouring Regulation (EC) No 1334/2008 dictates the pricing tier structure across pharmaceutical-grade, food-grade, and industrial-grade smoked dextrose categories. Price differentiation centers on contaminant certification levels and pyrolysis control precision, with snack manufacturers in Germany and the Netherlands paying premiums for verified low-PAH powder grades. Cost compression in standard-grade segments is intensifying because maize feedstock volatility transfers directly into margin pressure. Private-label snack producers exhibit highest price sensitivity, while meat-alternative specialists prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory cycles extend eight to twelve weeks for North American buyers sourcing from German and Dutch pyrolysis clusters. Supply concentrates in Germany, the Netherlands, and Belgium, where continuous-flow reactor technology anchors food-grade production capacity. Raw material flows draw from maize starch refining networks in France, Ukraine, and Argentina. Single-source vulnerability runs through Cologne-Eindhoven production corridors, where regulatory approval lags prevent rapid supplier switching. Distribution runs through seasoning house intermediaries for mid-scale buyers, while large compounders pursue direct pyrolysis operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smoked dextrose penetration sits at early-cycle expansion, with clean-label snack reformulation in North America and Europe driving first-wave adoption velocity ahead of Asia-Pacific market development.
For Market Incumbents: Consolidate pyrolysis certification advantages by locking in multi-year supply agreements with German meat-alternative manufacturers before REACH authorization timelines extend. Backward integration into dextrose monohydrate feedstock production in France and Ukraine hedges against maize price volatility threatening margin structures. Capacity expansion in Rotterdam-Antwerp corridor captures beverage reformulation demand for liquid concentrate grades. For New Entrants and Emerging Players: Lead with India FSSAI pathway development, where domestic production absence creates import arbitrage opportunities for BIS-compliant powder grades. Target mid-scale seasoning houses in Gujarat and Maharashtra seeking clean-label alternatives to liquid smoke. Partner with European pyrolysis technology licensors to shortcut continuous-flow reactor deployment timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision pyrolysis engineering segments, as real-time temperature feedback systems and parts-per-billion PAH analytics infrastructure demand concentrated capital deployment. Five-to-ten year viability favors integrated agricultural processors with captive starch refining and existing smoke flavor regulatory dossiers. Watch for EFSA scientific opinion publication timelines as inflection signals for category expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dextrose Feedstock | Roquette Frères S.A. and Cargill Incorporated stabilize raw material flows against agricultural commodity cycles. |
| Precision Pyrolysis Certification Investment | Continuous-flow reactor deployment in Cologne secures EFSA-compliant benzo(a)pyrene thresholds below 0.5 micrograms per kilogram. |
| Direct Procurement Relationship Development | Private-label snack producers in Chicago and Minneapolis bypass flavor house markups through pyrolysis operator contracts. |
| India FSSAI Regulatory Pathway Navigation | First-mover importers meeting BIS contaminant standards capture emerging clean-label snack demand in Mumbai and Delhi. |
| Carbon Accounting Integration | EU Green Deal supply-chain disclosure rules reward pyrolysis operators with documented renewable energy inputs. |
Research Methodology
A spread of perspectives from pyrolysis plant managers, snack seasoning procurement leads, regulatory affairs directors at flavor houses, and EFSA scientific committee members converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EU flavoring regulation filings, BIS contaminant standard documentation, and customs trade data for dextrose derivative flows. Bottom-up volume modeling triangulated against top-down expenditure analysis across the projection horizon.
Segmentation dimensions modeled include product format tier, application channel, end-user scale, and regional regulatory cluster. CAGRs were derived through trend extrapolation anchored to documented clean-label reformulation mandates and sodium reduction target implementation. Forecast inputs incorporated maize starch price volatility bands and REACH authorization timeline scenarios for pyrolysis-derived substances.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated FSSAI pathway development would require recalibration. Forecasts reflect assumptions on certification adoption rates and trade flow continuity through Rotterdam and Hamburg ports. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Mint Essential Oils Market