
 Yogurt Alternative Market | 2026-2036
Yogurt Alternative Market Size, Share, and Industry Trends Forecast 2026-2036
Yogurt Alternative Market Analytics
Plant-based food formulation expertise is rotating from niche startups into mainstream CPG operations, tightening the talent pool for dairy-alternative R&D. Danone S.A. leverages its European fermentation infrastructure to anchor oat and almond yogurt production at scale. Chobani LLC competes through Greek yogurt heritage translated into coconut-based lines, while Oatly AB dominates oat-specific processing technology and brand recognition in retail chilled sets.
Yogurt alternatives comprise cultured, plant-based preparations using oat, almond, soy, or coconut substrates with live bacterial cultures, achieving protein content between 3-8 grams per serving and pH ranges of 4.0-4.6 for shelf stability and sensory performance. Their primary commercial purpose is delivering spoonable, fermented nutrition to consumers excluding dairy for allergy, ethical, or metabolic reasons. Almond and coconut formulations lead current retail velocity in North American and European supermarkets, while oat bases capture the fastest-growing share due to neutral flavor profiles and favorable sustainability positioning. Single-serve cups concentrate the highest margin pools in convenience-oriented channels, though tubs sustain volume in family-format grocery purchasing.
FDA labeling standards for plant-based dairy terms, EFSA novel food approvals for emerging protein sources, and EU Green Deal carbon-accounting requirements collectively shape formulation choices, clean-label claims, and cross-border market access for yogurt alternative manufacturers. The EU AI Act and CSRD reporting frameworks will soon extend supply-chain transparency obligations into agricultural input sourcing. Stakeholders must monitor how fermentation technology patents and regional clean-label enforcement diverge to anticipate where production economics and consumer trust will shift next.
Market Dynamics
Fermentation technology patent clustering and EU Green Deal carbon-accounting mandates are compressing formulation timelines while forcing capital redeployment toward low-carbon processing infrastructure. Foodservice operators now specify clean-label credentials in procurement contracts, tightening supplier qualification windows.
Growth Catalysts
- EU Green Deal carbon-accounting:Mandatory Scope 3 disclosure for agricultural inputs is accelerating supplier transitions to regenerative oat and almond sourcing in Germany and France.
- Foodservice channel expansion:Institutional cafeterias in the Netherlands and Sweden are mandating plant-based options, creating dedicated chilled set placements for cultured alternatives.
- Precision fermentation:Novel protein production methods are reducing reliance on commodity crop inputs while enabling custom amino acid profiles for texture optimization.
Market Restraints
- Input cost volatility:Almond water intensity and drought exposure in California supply basins create price instability for base ingredient procurement.
- EFSA novel food approval timelines:Emerging protein sources from precision fermentation face 18-24 month safety assessment windows, delaying commercial launch schedules.
- Technical texture limitations:Current oat protein networks fail to replicate Greek yogurt viscosity without added hydrocolloids, complicating clean-label positioning.
Strategic Opportunities
- Underpenetrated Eastern European retail:Poland and Romania maintain minimal chilled plant-based dairy sets, offering first-mover shelf space capture potential.
- CSRD supply-chain transparency:Early compliance with EU corporate sustainability reporting requirements is creating preferred supplier status for ingredient traceability investments.
- Direct-to-foodservice distribution:Bypassing traditional retail slotting fees through institutional contracts improves margin capture and volume predictability.
Industry Challenges
- Fermentation specialist scarcity:Plant-based dairy R&D talent pools are contracting as mainstream CPG operations absorb experienced formulation scientists from niche startups.
- Clean-label certification complexity:Divergent national enforcement of "natural" claims across EU member states creates reformulation burdens for cross-border product consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yogurt Alternative Market |
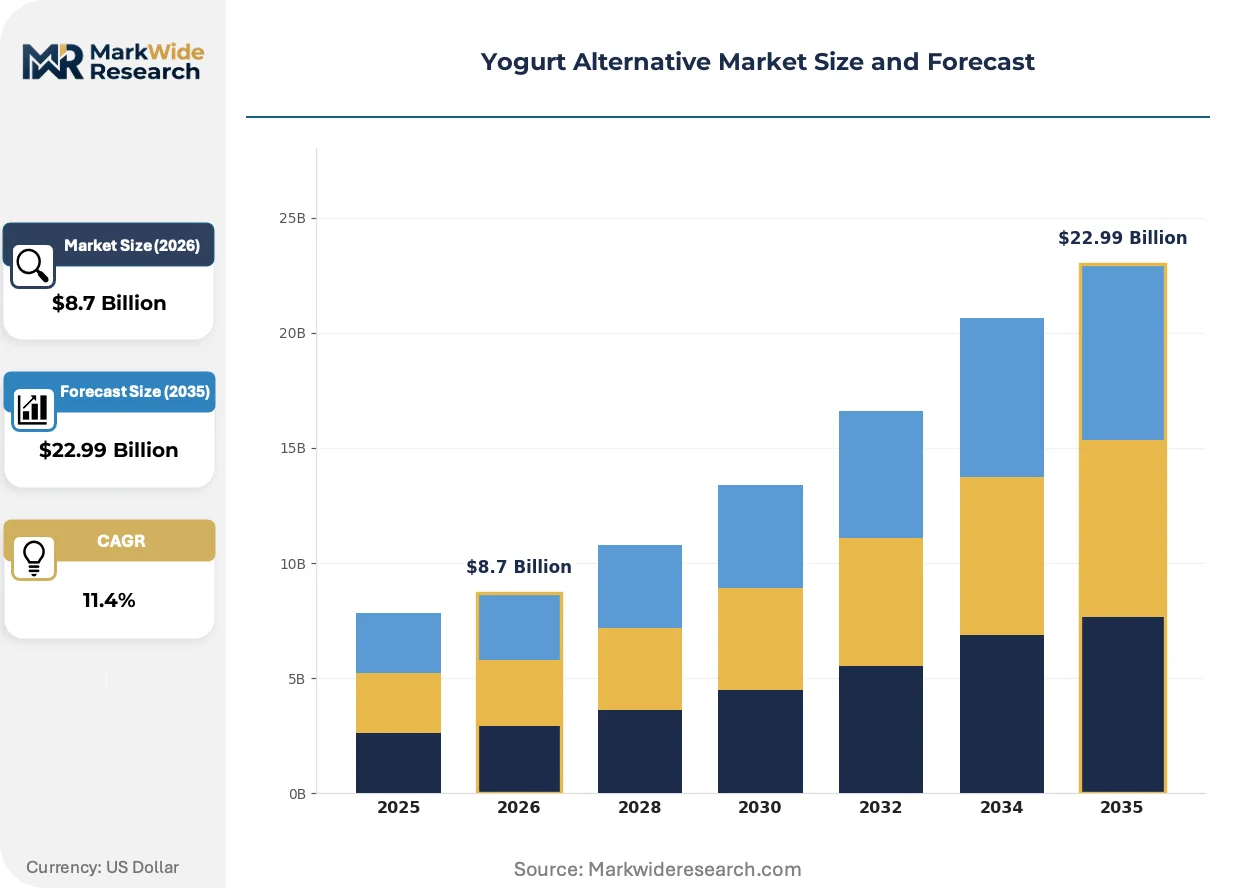
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond, Coconut, Soy, Cashew Application: Snack, Breakfast, Ingredient, Dessert End User: Health-conscious Consumers, Vegans, Lactose Intolerant Individuals, Fitness Enthusiasts Package Type: Single-serve Cups, Pouches, Tubs, Bottles |
| Companies Covered | Danone S.A., Chobani LLC, General Mills, Inc., Oatly AB, Forager Project, LLC, Califia Farms, LLC, The Hain Celestial Group, Inc., Kite Hill, Good Karma Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yogurt Alternative Market Evolving Landscape
Bioprocessing advances and regulatory disclosure mandates are fragmenting traditional production economics while creating new competitive moats around carbon-verified supply chains. Formulation science is pivoting from ingredient substitution toward functional protein network engineering.
Precision fermentation for dairy-identical proteins is bifurcating the ingredient supply base. Early-stage adopters in premium positioning segments are securing exclusive offtake agreements, while conventional plant-protein suppliers face margin compression in mid-market formulations. This technology is enabling texture parity without hydrocolloid additives, reshaping clean-label competitive dynamics.
EU F-Gas Regulation phase-down schedules are forcing refrigeration infrastructure replacement across Central European processing facilities. Industrial consequence includes accelerated capital expenditure cycles for cold-chain-dependent fermentation operations. German and Dutch manufacturing clusters are responding with ammonia-based cooling system retrofits and heat recovery integration.
Buyer procurement specifications now embed lifecycle carbon thresholds as primary qualification criteria. Foodservice distributors in Scandinavia and the Low Countries are displacing traditional supplier scorecards with verified emission accounting. This pattern is most visible in institutional catering contracts across Copenhagen, Amsterdam, and Stockholm metropolitan procurement pools.
Yogurt Alternative Market Segmentation
Yogurt alternative manufacturers configure product portfolios around substrate functionality, consumption occasion, and distribution channel economics. Segment boundaries are blurring as multi-use formulations target both retail and foodservice procurement specifications simultaneously.
Product Type:
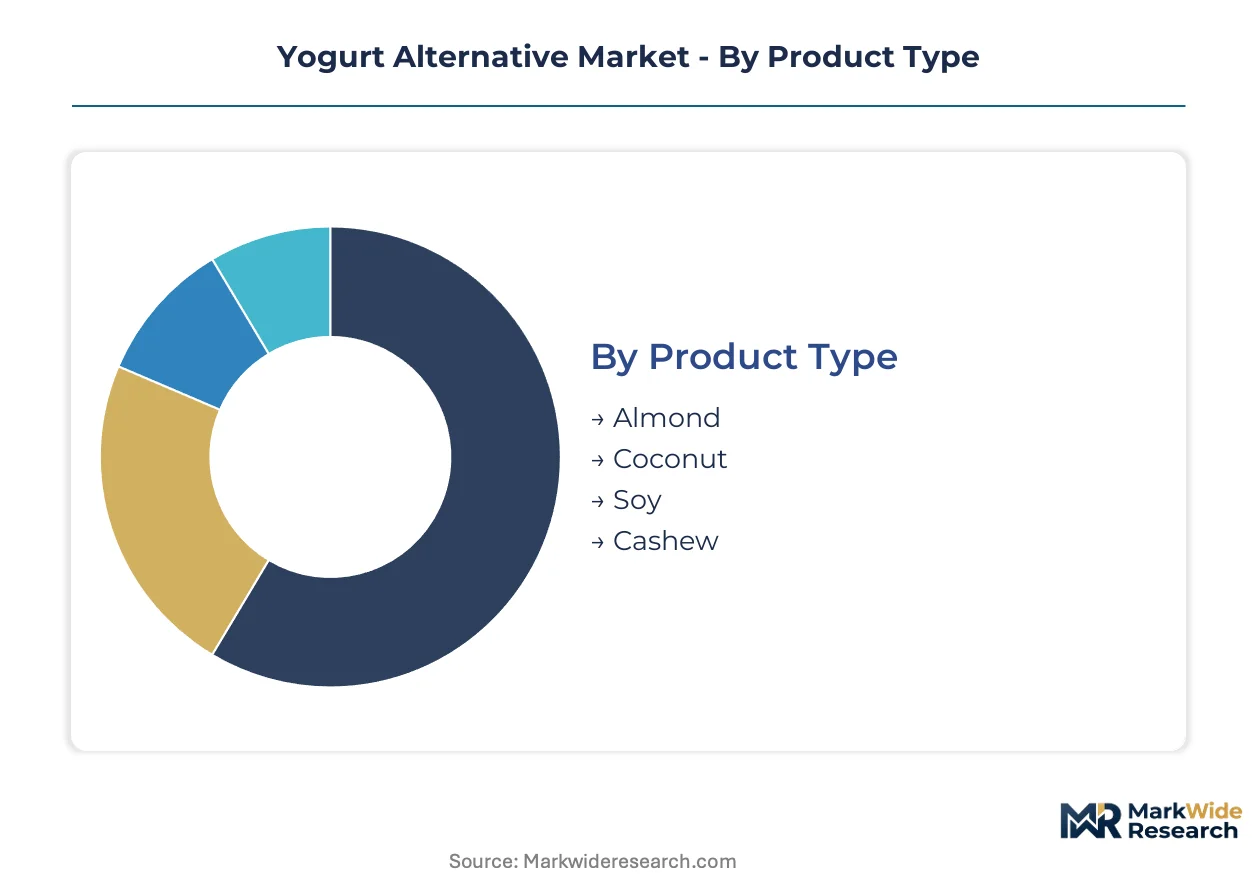
Almond and coconut bases dominate export-led positioning into North American and European retail sets, while soy retains stronger domestic anchoring in Asian markets. Oat substrates, though not formally categorized here, increasingly cross-train into multiple product type classifications.
- Almond:High-fat content (7-9%) delivers creamy mouthfeel without hydrocolloid dependence. German retailers are expanding chilled almond yogurt facings as EU Green Deal carbon-accounting favors lower-water-input sourcing from Mediterranean orchards over California basins.
- Coconut:Saturated fat profile (10-12%) enables Greek-style viscosity replication. Demand concentrates in Netherlands and UK foodservice channels where clean-label procurement mandates exclude added stabilizers.
- Soy:Complete protein matrix (6-8g per serving) serves established vegetarian populations. Japanese and South Korean manufacturing clusters maintain captive soy yogurt production for domestic convenience store distribution.
- Cashew:Neutral flavor base supports premium positioning in specialty retail. Limited commercial scale due to African and Indian supply concentration and price volatility.
Almond commands the established base. The steepest expansion runs through coconut as foodservice clean-label specifications harden.
Application:
Margin structures diverge sharply by consumption occasion, with breakfast and snack applications driving volume and dessert formulations capturing premium pricing.
- Snack:Single-serve portability requirements favor pouch and cup formats. US grab-and-go channel placement is tightening shelf velocity thresholds for new entrants.
- Breakfast:Parfait and granola pairing applications dominate German and Swedish retail chilled sets. Protein fortification claims are becoming table stakes in this occasion.
- Ingredient:Foodservice manufacturing demand for smoothie bases and frozen dessert inputs. B2B procurement contracts in France and Italy specify minimum solids content and fermentation culture viability.
- Dessert:Indulgence-positioned formulations with elevated fat and sugar profiles. UK premium grocery multiples are expanding dedicated dessert yogurt alternative bays.
Breakfast anchors volume throughput. Ingredient applications are climbing fastest as foodservice operators internalize plant-based menu development.
End User:
User segmentation reflects dietary motivation rather than demographic clustering, complicating traditional targeting approaches.
- Health-conscious Consumers:Probiotic culture count and added protein claims drive purchase decisions. German pharmacy channel distribution is expanding for medical-positioned variants.
- Vegans:Ethical sourcing verification and B12 fortification requirements. Scandinavian institutional procurement mandates are creating dedicated vegan-only supply lines.
- Lactose Intolerant Individuals:Functional necessity positioning with digestive health claims. Italian and Spanish retail maintains strong penetration due to Mediterranean lactose sensitivity prevalence.
- Fitness Enthusiasts:Macro-calculated formulations with elevated protein (8g+) and controlled carbohydrate. UK gym and sports nutrition channels are expanding chilled grab-and-go placement.
Health-conscious consumers represent the revenue core. Vegan-identified users are gaining share fastest as generational dietary shifts accelerate.
Package Type:
Packaging format selection determines cold-chain infrastructure requirements and retail slotting fee economics.
- Single-serve Cups:Standard 150g format dominates convenience store and café impulse purchase. German and Dutch retailers are specifying recyclable or compostable cup mandates under EU packaging regulations.
- Pouches:Flexible format for children's snacking and on-the-go consumption. UK school feeding programs are piloting pouch-based yogurt alternatives for allergen management.
- Tubs:Family-size formats (400-500g) for household pantry stocking. French and Italian hypermarkets maintain extensive tub facings for multi-occasion purchasing.
- Bottles:Drinkable yogurt alternatives for beverage channel placement. Limited penetration due to fermentation stability challenges in liquid format.
Tubs sustain the volume foundation. Single-serve cups are expanding most quickly as convenience retail formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor breakfast-oriented tubs with protein fortification claims, while US buyers gravitate toward single-serve snack cups for grab-and-go convenience. Dutch foodservice channels lead institutional adoption with clean-label procurement mandates. Japanese retail maintains distinctive soy-based traditions against oat and almond inflows.
Germany
Retail shelf space for chilled plant-based dairy alternatives has expanded significantly in Berlin and Hamburg metropolitan clusters. The EU Green Deal's Scope 3 disclosure requirements are accelerating transitions to regenerative oat sourcing from domestic and Baltic suppliers. Bavarian processing facilities are retrofitting ammonia-based cooling systems to comply with F-Gas Regulation phase-down schedules.
United States
Grab-and-go channel placement in convenience stores and cafés drives single-serve cup velocity, with protein content claims becoming table stakes. FDA labeling standards for plant-based dairy terms shape formulation choices and clean-label positioning. California's Central Valley almond orchards face water intensity pressures, creating price instability for base ingredient procurement.
Netherlands
Institutional cafeterias in Amsterdam and Rotterdam metropolitan areas mandate plant-based options, creating dedicated chilled set placements for cultured alternatives. CSRD reporting frameworks extend supply-chain transparency obligations into agricultural input sourcing. Dutch manufacturing clusters are integrating heat recovery systems alongside ammonia cooling retrofits.
Japan
Convenience store distribution networks sustain captive soy yogurt production for domestic consumption, resisting oat and almond substitution. The country's national food safety regulator maintains novel food assessment protocols for emerging protein sources. Tokyo and Osaka metropolitan areas concentrate R&D activity for texture optimization in traditional fermentation formats.
Sweden
Scandinavian institutional procurement mandates are creating dedicated vegan-only supply lines with B12 fortification requirements. EFSA novel food approvals for precision fermentation proteins face extended assessment windows, delaying commercial launches. Stockholm's metropolitan procurement pools embed lifecycle carbon thresholds as primary supplier qualification criteria.
Yogurt Alternative Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation infrastructure ownership and retail chilled set access determining tier placement. The upper tier commands scale advantages in oat and almond substrate processing, while specialists compete on coconut-based viscosity replication and clean-label positioning. Three archetypes dominate: diversified dairy incumbents with plant-based extensions, oat-specific technology pure-plays, and coconut-forward heritage yogurt translators. Competitive moves concentrate on foodservice direct distribution partnerships and carbon-verified supply chain certification.
Among diversified dairy incumbents, Danone S.A. and General Mills, Inc. exemplify the integrated leader archetype through European fermentation infrastructure leverage and mainstream CPG operational scale. Chobani LLC occupies a position within the heritage-translation tier, applying Greek yogurt expertise to coconut-based line development. Oatly AB anchors the substrate-specialist vector, with brand recognition and processing technology concentrated in retail chilled sets.
| Leading Market Players |
|---|
| Danone S.A. |
| Chobani LLC |
| General Mills, Inc. |
| Oatly AB |
| Forager Project, LLC |
| Califia Farms, LLC |
| The Hain Celestial Group, Inc. |
| Kite Hill |
| Good Karma Foods, Inc. |
| Others |
Value Network & Pricing Analysis
Oat substrate substitution for almond bases is simultaneously shifting supply geography toward Nordic and Baltic growing regions and compressing per-unit input costs as Mediterranean almond orchards face water pricing pressures. This displacement dynamic concentrates procurement leverage among processors with multi-substrate fermentation flexibility while fragmenting pricing power across regional ingredient markets.
Pricing Analysis
Long-term offtake contracts with regenerative oat cooperatives in Germany and Sweden anchor pricing for premium clean-label tiers, while spot-market almond procurement from California and Spain introduces volatility into mid-range formulations. Price differentiation hinges on EU Green Deal carbon-verification certification and organic substrate sourcing tier. Cost compression in standard-tier products is intensifying because hydrocolloid-dependent texture systems face clean-label substitution pressure. Foodservice buyers exhibit highest price sensitivity due to volume procurement scale, while pharmacy-channel health-positioned variants maintain lowest sensitivity through medical-necessity positioning.
Supply Chain Analysis
Inventory lead times for precision fermentation-derived protein inputs extend 18-24 months due to EFSA novel food approval sequencing, forcing manufacturers to maintain dual-sourcing buffers across conventional plant proteins. Supply concentrates in Germany, the Netherlands, and Sweden for chilled finished goods, while almond and coconut base ingredients draw from Spain, Indonesia, and the Philippines. Single-source vulnerability runs through California Central Valley almond supply exposed to drought-driven allocation restrictions. Distribution runs through temperature-controlled retail chilled sets in Northern Europe and direct-to-foodservice institutional contracts in Scandinavian metropolitan procurement pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yogurt alternative market sits in a post-pandemic cyclical recovery phase as foodservice channel normalization restarts institutional procurement volumes and regenerative agriculture investment cycles mature.
For Market Incumbents: Fortify fermentation infrastructure ownership through ammonia cooling retrofits in Bavarian and Dutch processing clusters ahead of F-Gas Regulation phase-down deadlines. Secure exclusive offtake agreements with precision fermentation protein suppliers to preempt texture-parity competition from clean-label challengers. Deepen backward integration into Baltic oat sourcing to hedge California almond price volatility. For New Entrants and Emerging Players: White-space foodservice formulation services—where incumbents under-serve small-batch custom culture development—offer entry points into Netherlands and Swedish institutional procurement pools. Target Poland and Romania retail chilled sets for first-mover shelf space capture before EU packaging regulation mandates raise capital barriers. Pursue direct-to-institutional distribution bypassing retail slotting fees to improve margin capture. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors substrate-specialist technology pure-plays with patented oat-processing IP and established retail chilled set access. Long-term viability over the coming decade rests on carbon-verified supply chain certification and precision fermentation scale-up execution. Monitor EFSA novel food approval timelines for dairy-identical proteins as the inflection signal for texture-parity competitive disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Infrastructure Retrofit | Ammonia cooling adoption in German facilities ensures F-Gas Regulation compliance while securing production continuity. |
| Precision Fermentation Partnership | Exclusive offtake agreements for dairy-identical proteins enable clean-label texture parity without hydrocolloid additives. |
| Regenerative Sourcing Certification | EU Green Deal Scope 3 compliance creates preferred supplier status in Scandinavian institutional procurement pools. |
| Direct-to-Foodservice Distribution | Bypassing retail slotting fees through Amsterdam and Rotterdam institutional contracts improves margin predictability. |
| Eastern European Shelf Expansion | First-mover positioning in Polish and Romanian chilled sets captures volume before packaging regulation raises barriers. |
Research Methodology
Desk research of customs trade records, EU regulatory filings, and retail audit databases preceded structured interviews with fermentation R&D directors, foodservice procurement managers, and chilled dairy category buyers at German and Dutch retailers. Primary fieldwork with plant-based formulation scientists and institutional cafeteria operators was cross-validated against secondary data from EFSA novel food registers and SEC filings of publicly traded CPG parents. Bottom-up volume modeling triangulated against top-down market sizing across substrate type and distribution channel.
Variance decomposition across the projection horizon isolates growth contributions from foodservice channel expansion, precision fermentation adoption curves, and regulatory compliance cost pass-through. Segmentation modeling incorporated substrate functionality, consumption occasion, package format economics, and regional regulatory cluster. CAGRs were derived from fitted growth curves rather than linear extrapolation, with inputs including fermentation capacity utilization rates and retail shelf space expansion trajectories in named metropolitan clusters.
Forecasts assume regulatory continuity in EU Green Deal carbon-accounting, F-Gas Regulation phase-down schedules, and FDA plant-based dairy labeling standards; material policy shifts would require re-modeling across substrate sourcing and clean-label claim permissibility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Walnut Milk Market